
 Snooker Tables Market | 2026-2036
Snooker Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Snooker Tables Market Analysis
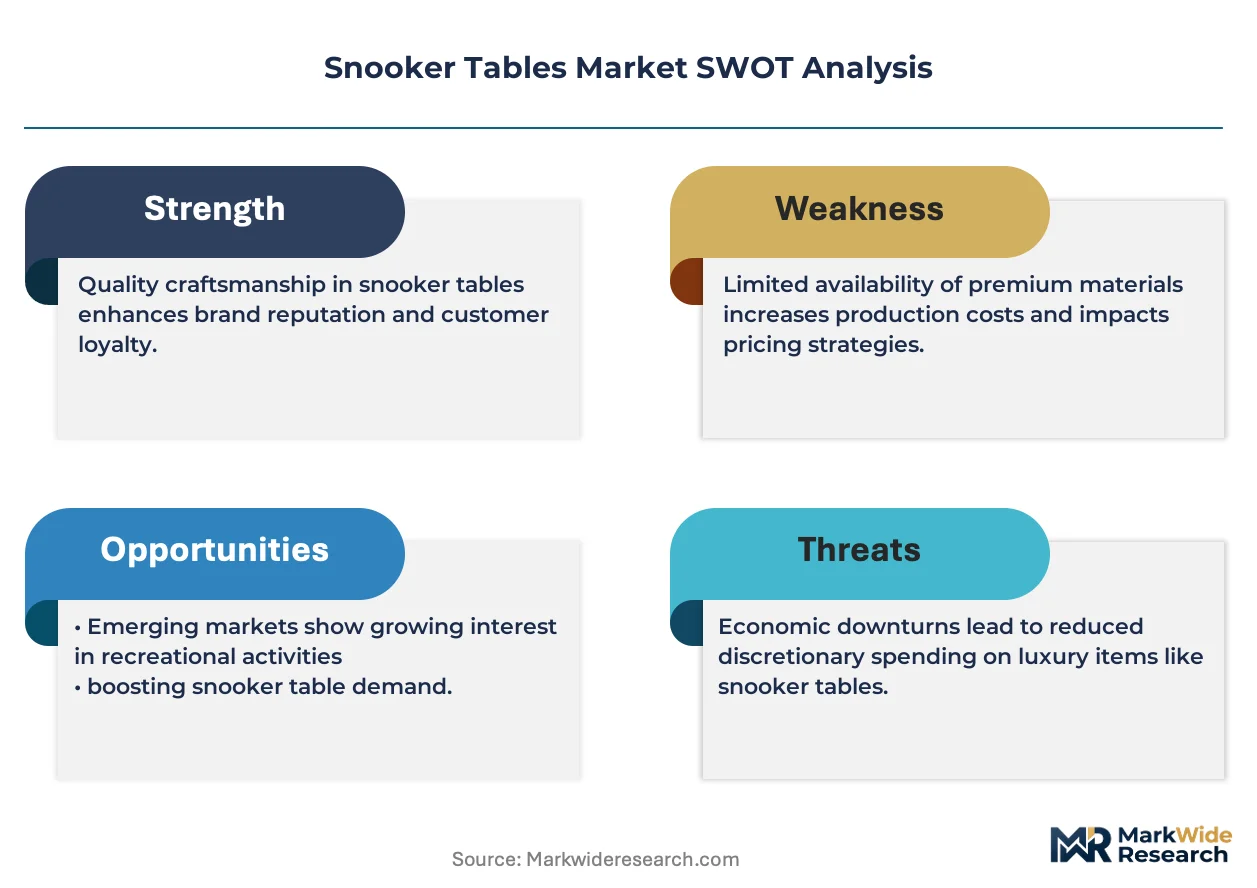
EU REACH regulation is rebalancing material sourcing across the snooker table supply chain by restricting certain wood preservatives and surface coatings used in slate bed construction. Riley England leverages its heritage manufacturing base to sustain premium positioning in tournament-grade tables. Wiraka Pte Ltd. anchors Southeast Asian distribution through specialized regional dealer networks. Beijing Xingwei Sports Goods Co. Ltd. dominates domestic Chinese volume with integrated slate quarrying and frame fabrication.
A snooker table consists of a precision-leveled slate bed typically measuring 12 feet by 6 feet, covered with woven wool-nylon cloth stretched over vulcanized rubber cushions, all supported by a hardwood or engineered frame designed to maintain dimensional stability within 0.1 millimeter tolerance for competitive play. Professional-grade 12-foot tables command the highest margin pools due to slate sourcing costs and artisan assembly requirements, while portable and home segments compete on price through MDF substrate substitution and knock-down frame engineering. Composite material experimentation is displacing traditional hardwood in mid-tier commercial installations where humidity fluctuation tolerance outweighs aesthetic authenticity.
CE marking governs structural safety and surface chemical emissions for tables distributed across European member states, while China's GB standards and MIIT directives regulate domestic manufacturing quality and sports equipment classification. The US EPA and state-level CARB restrictions on formaldehyde emissions from composite wood products shape import eligibility for Asian-manufactured tables entering North American channels. Stakeholders must monitor evolving slate extraction licensing in Italy and Brazil, as quarry access consolidation threatens to reshape cost structures independent of finished goods demand cycles.
Market Dynamics
REACH compliance in Europe is tightening material specifications for wood treatments and finishes, forcing manufacturers to reformulate surface coatings and requalify slate bed adhesives across their European distribution networks.
Growth Catalysts
- Commercial club expansion:Recreational centers in China are accelerating replacement cycles through local tournament infrastructure investments.
- Composite material adoption:Engineered substrates are displacing traditional hardwood in mid-tier commercial installations where humidity tolerance outweighs aesthetic demands.
- GB standards alignment:China's MIIT directives are streamlining domestic manufacturing quality classifications, reducing certification friction for local producers.
Market Restraints
- Slate quarry access consolidation:Licensing restrictions in Italy and Brazil are concentrating raw material supply among fewer extraction operators.
- CARB formaldehyde thresholds:California Air Resources Board emission limits on composite wood products are blocking entry for Asian-manufactured tables with MDF substrates.
- Artisan assembly bottlenecks:Tournament-grade 12-foot tables require skilled craftsmen for precision leveling within 0.1 millimeter tolerance, constraining volume scaling.
Strategic Opportunities
- Portable segment penetration:Knock-down frame engineering and lightweight substrates are opening home recreational markets previously blocked by space constraints.
- EU Green Deal alignment:Bio-based coating formulations qualify for preferential procurement scoring in municipal recreational facility tenders.
- Southeast Asian dealer network expansion:Specialized regional distributors in Singapore and Malaysia are capturing underserved commercial club demand outside established European supply channels.
Industry Challenges
- Precision calibration expertise scarcity:Slate bed installation requires technicians trained in dimensional stability protocols, with certification programs lagging behind commercial deployment timelines.
- Multi-jurisdiction compliance layering:Simultaneous CE marking, GB standards, and state-level EPA requirements force parallel testing tracks that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snooker Tables Market |
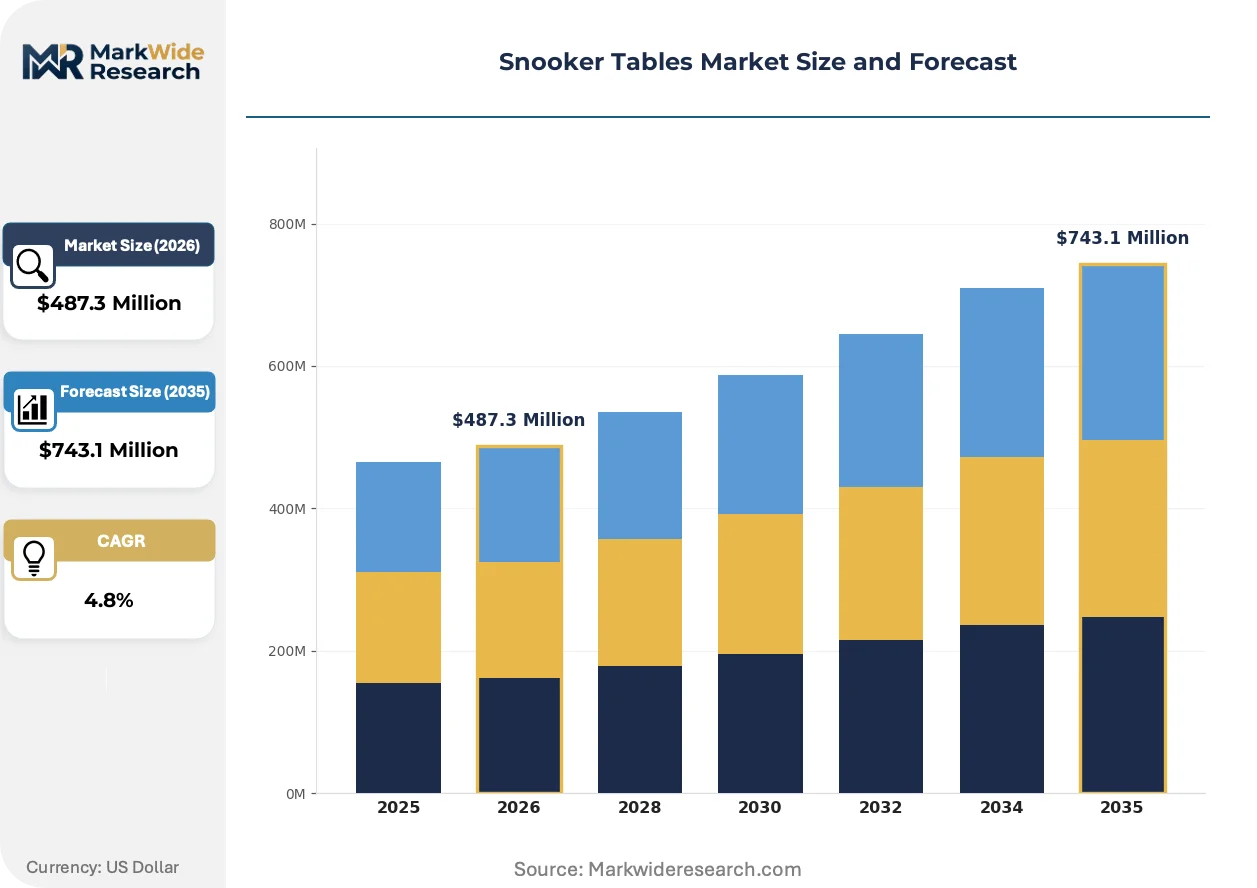
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Home, Professional, Portable, Commercial Material: Wood, MDF, Steel, Composite Size: 7 ft, 8 ft, 9 ft, 12 ft Accessory Type: Cues, Chalk, Covers, Lights |
| Companies Covered | Riley England, Wiraka Pte Ltd., Snooker Alley, Beijing Xingwei Sports Goods Co. Ltd., Brunswick Corporation, Diamond Billiard Products Inc., Birmingham Billiards Ltd., Ortmann Billiards, Real Billiard Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snooker Tables Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape how snooker table manufacturers balance performance specifications with compliance requirements across distributed production networks.
Carbon-fiber reinforced polymer framing is consolidating market share in high-humidity commercial installations. Southeast Asian recreational centers facing monsoon season moisture exposure are specifying composite substrates over traditional hardwood. This material transition is consolidating supplier relationships around specialized polymer compounders with sporting goods formulation experience.
ECHA's evolving SVHC candidate list is restricting chromium-based wood preservatives previously standard in frame treatments. European manufacturers must now qualify alternative biocide systems or shift to heat-treated timber processes. Tournament-grade table producers serving the UK and German markets are absorbing extended requalification timelines for revised finishing protocols.
Direct-to-venue specification consulting is replacing traditional distributor-led sales in premium commercial segments. Facility designers in Shanghai and Beijing are engaging manufacturers early in construction planning to integrate customized table dimensions. This pattern is most visible in China's tier-one cities where integrated sports complex developments are specifying proprietary slate dimensions during architectural design phases.
Snooker Tables Market Segmentation
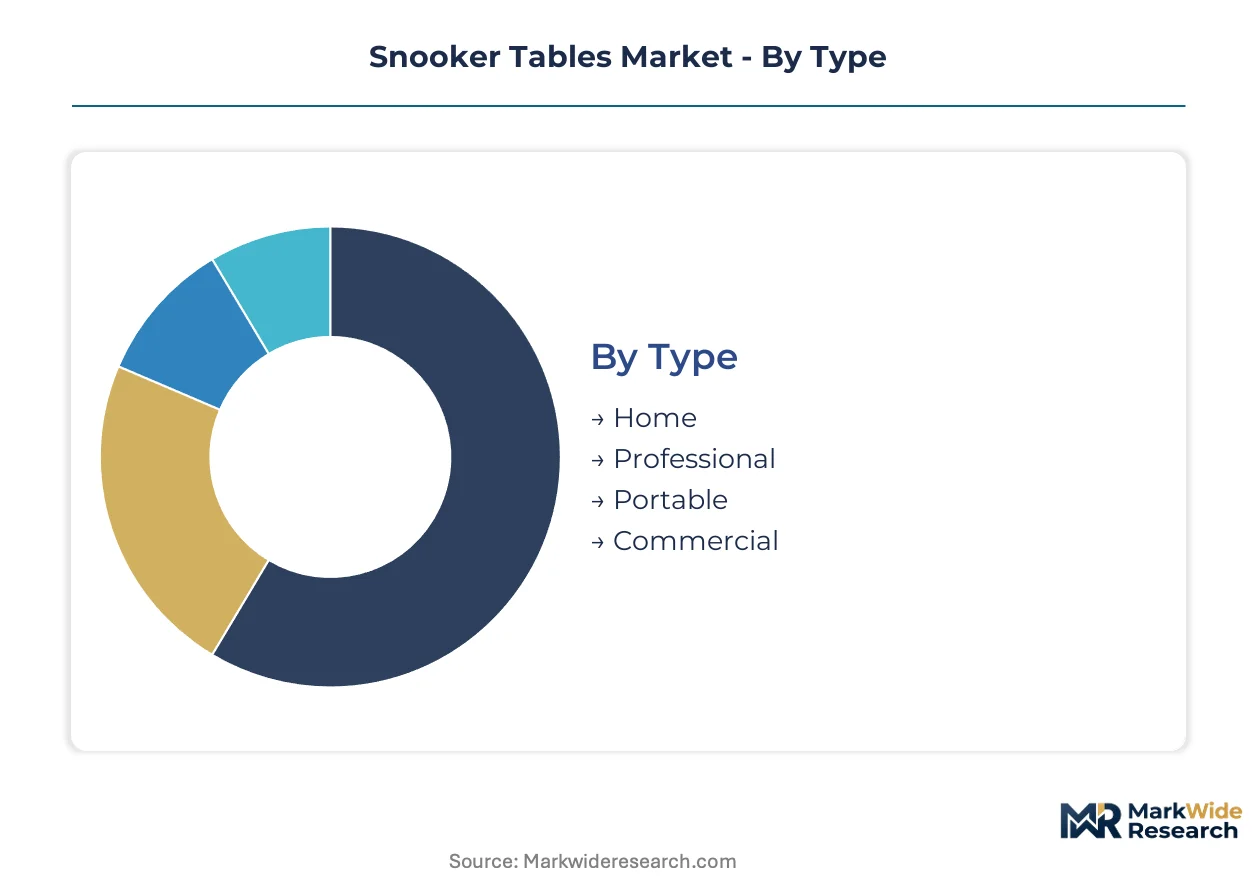
Snooker table purchasing decisions diverge sharply across installation contexts, from precision tournament specifications to space-constrained residential environments. Material selection and dimensional requirements cascade through pricing, logistics, and maintenance protocols in ways that reshape supplier economics and channel strategy.
Type:
Buyers prioritize installation permanence and play quality specifications when selecting table categories for specific venues.
- Professional:Tournament-grade tables feature precision-leveled slate beds with 0.1 millimeter tolerance calibration, requiring artisan assembly and specialized installation crews. Demand concentrates in China's tier-one cities where integrated sports complex developments specify proprietary dimensions during architectural design phases, absorbing extended lead times for custom fabrication.
- Commercial:Mid-tier installations in Southeast Asian recreational centers favor humidity-tolerant composite framing over traditional hardwood, with monsoon season exposure driving material substitution. These specifications balance durability requirements against capital expenditure constraints in high-traffic club environments.
- Home:Residential buyers emphasize space efficiency and aesthetic integration with interior design schemes.
- Portable:Knock-down frame engineering and lightweight substrates target recreational users facing spatial constraints.
Professional leads on scale; Commercial leads on momentum.
Material:
Cost tier positioning and environmental exposure tolerance determine substrate selection across installation categories.
- Wood:Traditional hardwood frames deliver dimensional stability and authentic aesthetic appeal for premium residential and heritage commercial installations. Italian and Brazilian slate quarry access consolidation is elevating raw material costs for solid-wood tournament-grade constructions, compressing margins for European manufacturers serving UK and German markets.
- Composite:Carbon-fiber reinforced polymer framing is consolidating share in high-humidity commercial installations across Southeast Asia, where supplier relationships are concentrating around specialized polymer compounders with sporting goods formulation experience. REACH compliance is forcing reformulation of surface coatings and requalification of adhesives in European distribution networks.
- MDF:Engineered wood substrates compete on price in entry-level residential and portable segments.
- Steel:Metal framing supports heavy-duty commercial applications requiring maximum structural rigidity.
Wood dominates premium positioning; Composite gains share fastest in commercial expansion zones.
Size:
Dimensional specifications correlate directly with slate sourcing costs, installation complexity, and end-use certification requirements.
- 12 ft:Full tournament dimensions command the highest margin pools due to artisan assembly requirements and precision calibration protocols. China's MIIT directives are streamlining domestic manufacturing quality classifications for these specifications, reducing certification friction for local producers supplying municipal tournament infrastructure investments.
- 9 ft:Intermediate dimensions serve serious amateur players and smaller commercial venues seeking competitive play experience without full-scale spatial commitments. Demand is expanding in China's tier-two cities where recreational club development is outpacing tournament-grade facility construction.
- 8 ft:Compact competitive dimensions fit residential game rooms and boutique hospitality installations.
- 7 ft:Reduced dimensions target space-constrained home recreational markets and portable applications.
12 ft commands margin concentration; 9 ft shows steepest expansion trajectory in emerging club infrastructure.
Accessory Type:
Aftermarket purchasing patterns follow table installation cycles and player skill progression trajectories.
- Cues:Shaft technology and tip composition differentiate performance tiers for competitive and recreational players. Professional-grade cue demand tracks tournament infrastructure development in China, where domestic manufacturing scales are accelerating replacement cycles.
- Lights:Specialized illumination systems eliminate shadow interference across full table surfaces. Specification consulting for integrated lighting is replacing traditional distributor-led sales in premium commercial segments, with facility designers in Shanghai and Beijing engaging manufacturers early in construction planning.
- Covers:Protective solutions extend cloth and frame lifespan in variable humidity environments.
- Chalk:Consumable replenishment drives recurring revenue in high-traffic commercial installations.
Cues anchor equipment attachment spending; Lights capture specification-influence value in new construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
British industrial heritage established snooker table manufacturing standards in the nineteenth century, with Sheffield and Birmingham workshops developing the precision slate-leveling techniques that define tournament-grade specifications today. This technical lineage now distributes across manufacturing clusters in Europe, Asia, and North America, each adapting heritage methods to local regulatory and demand conditions.
United Kingdom
Heritage manufacturers in the English Midlands sustain artisan assembly capacity for tournament-grade 12-foot tables, serving domestic club networks and export markets. UK REACH enforcement through ECHA restricts chromium-based wood preservatives in frame treatments, forcing reformulation of traditional finishing protocols. Birmingham and Sheffield retain specialized slate bed calibration expertise, though artisan bottlenecks constrain volume scaling for international orders.
China
Domestic manufacturing scales in Beijing and Shanghai supply municipal tournament infrastructure investments across tier-one cities, accelerating replacement cycles through integrated sports complex developments. MIIT GB standards streamline quality classifications for professional-grade tables, reducing certification friction for local producers. Beijing Xingwei Sports Goods anchors domestic volume through captive slate quarrying and frame fabrication integration.
Germany
Commercial club operators in Bavaria and North Rhine-Westphalia specify humidity-tolerant composite framing for high-traffic installations. CE marking governs structural safety and surface chemical emissions, with ECHA SVHC restrictions driving adhesive requalification timelines. Cologne and Munich host specification consultants engaging facility designers during early construction phases for integrated table dimensions.
United States
Residential and commercial buyers in California and the Northeast face CARB formaldehyde thresholds blocking entry for Asian-manufactured tables with MDF substrates. EPA restrictions on composite wood products shape import eligibility, concentrating distribution around domestic fabricators with compliant supply chains. Los Angeles and New York metropolitan areas drive demand for space-efficient portable configurations.
Singapore
Southeast Asian recreational centers specify carbon-fiber reinforced polymer framing to withstand monsoon season moisture exposure. Wiraka Pte Ltd. anchors regional distribution through specialized dealer networks capturing underserved commercial club demand. The city-state's logistics infrastructure positions it as a re-export hub for Malaysian and Indonesian club installations.
Snooker Tables Market Vendor Landscape
Premium-margin players sit above commodity-margin players across precision calibration and material authenticity dimensions, with tournament-grade 12-foot tables commanding structural margin advantages over portable and home segments. The vendor base organizes into three archetypes: heritage British manufacturers preserving artisan methods, Chinese integrated producers controlling upstream slate access, and Southeast Asian distributors specializing in humidity-tolerant composite specifications. Competitive moves concentrate on geographic expansion through regional dealer network cultivation and material substitution partnerships with polymer compounders.
Among heritage British manufacturers, Riley England and Birmingham Billiards Ltd. occupy positions representing artisan assembly traditions and Midlands industrial heritage. Beijing Xingwei Sports Goods Co. Ltd. exemplifies the integrated Chinese producer archetype with upstream slate quarrying control. Wiraka Pte Ltd. anchors the Southeast Asian distribution specialist tier, facilitating composite material penetration in monsoon-exposed commercial installations.
| Leading Market Players |
|---|
| Riley England |
| Wiraka Pte Ltd. |
| Snooker Alley |
| Beijing Xingwei Sports Goods Co. Ltd. |
| Brunswick Corporation |
| Diamond Billiard Products Inc. |
| Birmingham Billiards Ltd. |
| Ortmann Billiards |
| Real Billiard Ltd. |
| Others |
Supply Flow & Price Mechanics
Commercial club procurement clusters in China's tier-one cities anchor a three-tier pricing structure across premium, standard, and economy levels, with tournament-grade 12-foot specifications commanding structural margin advantages over knock-down portable configurations. This buyer concentration allows heritage manufacturers to sustain artisan-assembly premiums while forcing mid-tier competitors toward composite material substitution.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates tournament-grade slate constructions from MDF-based portable units, with certification level under MIIT GB standards and artisan calibration expertise serving as primary price differentiation drivers. Cost compression in the mid-tier commercial segment is intensifying because REACH-compliant coating reformulations extend requalification timelines. Home recreational buyers exhibit highest price sensitivity, while municipal tournament infrastructure programs absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
Single-source vulnerability sits with Italian and Brazilian slate quarrying operations, where licensing consolidation is concentrating extraction rights among fewer operators. Raw material sourcing draws from Brazilian slate deposits, Italian precision-stone quarries, and Chinese domestic slate integration, with carbon-fiber polymer compounding increasingly tethered to Southeast Asian petrochemical networks. Tariff exposure through CARB formaldehyde thresholds blocks Asian MDF substrate entry into California distribution channels. Distribution runs through specialized regional dealer networks rather than direct-to-venue fulfillment for non-premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Snooker table manufacturing operates as a regulatory compounder, with EU REACH SVHC expansions and China's MIIT GB standard alignment driving replacement demand across European and Asian commercial club networks simultaneously.
For Market Incumbents: Acquire captive slate quarrying assets in Brazil and Italy before licensing consolidation completes, securing backward integration into precision-bed raw material supply. Invest in heat-treated timber finishing protocols to preempt ECHA biocide restrictions on chromium-based preservatives. Defend against Southeast Asian composite-framing entrants by embedding specification consultants into Shanghai and Beijing sports complex developments during architectural design phases.
For New Entrants and Emerging Players: Specialized regional distributors in Malaysia and Indonesia represent the most accessible channel partner type for penetrating monsoon-exposed commercial club demand outside established European supply lines. Target portable segment penetration through knock-down frame engineering for space-constrained residential markets in US metropolitan areas facing CARB-compliant supply gaps. Pursue direct-to-venue specification consulting in China's tier-two cities where recreational club development outpaces tournament-grade facility construction.
For Investors and Strategic Acquirers: Heritage British manufacturers with artisan assembly traditions are the most active acquirer in this space, consolidating Midlands calibration expertise to serve international tournament infrastructure. Long-term viability hinges on slate quarry access control and polymer compounding partnerships for humidity-tolerant specifications. Watch for MIIT directive expansions into tier-two city procurement standards as the inflection signal for domestic Chinese volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slate Quarrying | Captive Italian and Brazilian stone access insulates margin structures from extraction licensing consolidation. |
| Composite Material Partnership | Carbon-fiber polymer compounding alliances with Southeast Asian suppliers address monsoon-exposed commercial demand. |
| Specification Consulting Expansion | Early-stage facility designer engagement in Shanghai and Beijing captures proprietary dimension integration opportunities. |
| REACH-Compliant Coating Reformulation | Bio-based finish qualification secures preferential procurement scoring in EU municipal recreational tenders. |
| Regional Dealer Network Cultivation | Singapore and Malaysia distribution specialization captures underserved Southeast Asian commercial club volume. |
Methodological Framework
Multiple input streams — primary interviews with slate quarry operators, sports complex facility designers, and commercial club procurement managers; secondary validation through MIIT directive filings, ECHA SVHC candidate list updates, and customs trade data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed tournament-grade table manufacturers, polymer compounders with sporting goods formulation experience, and regional distributor networks across Southeast Asia. Secondary sources included GB standards documentation, CARB emission threshold regulations, and municipal sports infrastructure procurement disclosures.
Data-stream reconciliation anchored the analytical framework across the projection horizon, with segmentation modeling disaggregating by table type, material substrate, dimensional specification, and accessory category. CAGRs were derived from installation volume trajectories and replacement cycle acceleration patterns, incorporating slate sourcing cost structures and artisan assembly capacity constraints as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to quarry access licensing decisions in Italy and Brazil, REACH SVHC list expansions affecting wood treatment protocols, and MIIT directive revisions streamlining domestic Chinese quality classifications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
China Toys Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Decompression Toys Market
Toys and Games
Anime Figure Blind Box Market
Toys and Games
Coaster Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
United States Toys Market
Toys and Games
Inflatable Toys Market
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Model Train Market
Toys and Games
Toy Building Blocks Market
Toys and Games
Fabric Toys Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Toy Collectibles Market