
 Autonomous Robot Toys Market | 2026-2036
Autonomous Robot Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Robot Toys Market Intelligence
The CE marking certification for toy safety is redrawing market access requirements for producers targeting the European Union. This standard mandates rigorous testing for electrical and material safety, influencing design and component sourcing. The LEGO Group leverages its extensive brand recognition and existing distribution channels to dominate the programmable robot segment. Sphero specializes in app-integrated robotic balls for educational and entertainment purposes, while UBTECH Robotics differentiates through its advanced humanoid robots for STEM learning.
Autonomous robot toys are interactive electronic devices engineered to perform actions without direct human control, utilizing onboard sensors and processors. These products often incorporate computer vision and sensor integration to navigate environments and respond to stimuli. Their primary purpose is to combine entertainment with educational outcomes in areas like cognitive development. Programmable robots and interactive pets represent the largest product type categories, while the educational robots segment shows the highest growth potential, particularly for early teens.
Compliance with regulations like the EU's RoHS directive, which restricts hazardous substances, and the US FCC's rules on radio frequency interference is mandatory. Global standards, such as those from the ISO, also influence material safety and manufacturing quality. These frameworks directly impact component selection and production costs for manufacturers. Stakeholders must now decide how to balance feature innovation with the rising complexity of multi-jurisdictional safety and data privacy compliance.
Market Dynamics
The central tension in the autonomous robot toys market is the push for advanced AI-driven features against the mounting complexity of global safety and data privacy regulations, such as the EU's CE marking and GDPR framework.
Growth Catalysts
- STEM Curriculum Integration:Government initiatives in the United States and Europe promoting technology in education are creating dedicated demand within schools and after-school programs for programmable robots.
- Advanced Sensor Technology:The falling cost and miniaturization of computer vision and lidar sensors enable more sophisticated environmental interaction, enhancing the educational and entertainment value of the toys.
- Parental Focus on Cognitive Skills:A strong consumer preference for toys that support cognitive development and problem-solving skills directly benefits the educational robots segment over traditional entertainment products.
Market Restraints
- High Component Costs:The price of specialized microprocessors, actuators, and high-resolution sensors remains a significant barrier, elevating the final product cost and limiting mass-market accessibility.
- Data Privacy Regulations:Compliance with stringent laws like Europe's GDPR and California's CCPA complicates the design of connected toys, adding development costs and legal risks.
- Competition from Digital Apps:Software-based educational applications on tablets and smartphones offer a lower-cost alternative, presenting a significant substitution threat for price-sensitive consumers.
Strategic Opportunities
- Therapeutic Applications:There is an emerging opportunity to design robots for use in pediatric therapy, assisting with social-emotional learning and cognitive behavioral therapy for children with special needs.
- Augmented Reality Integration:Combining autonomous robots with AR applications on smartphones can create immersive, mixed-reality learning experiences that differentiate products in a crowded market.
- Expansion in India:India's expanding middle class and strong governmental push for digital education under policies like the National Education Policy create a large, untapped market.
Industry Challenges
- Certification Bottlenecks:The lengthy and costly process for obtaining mandatory certifications, including the EU's CE marking for toy safety and US FCC approval for radio frequencies, can delay product launches.
- Intellectual Property Protection:Safeguarding proprietary AI algorithms and unique humanoid robot designs from reverse-engineering and infringement is a major operational challenge, particularly with global supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Robot Toys Market |
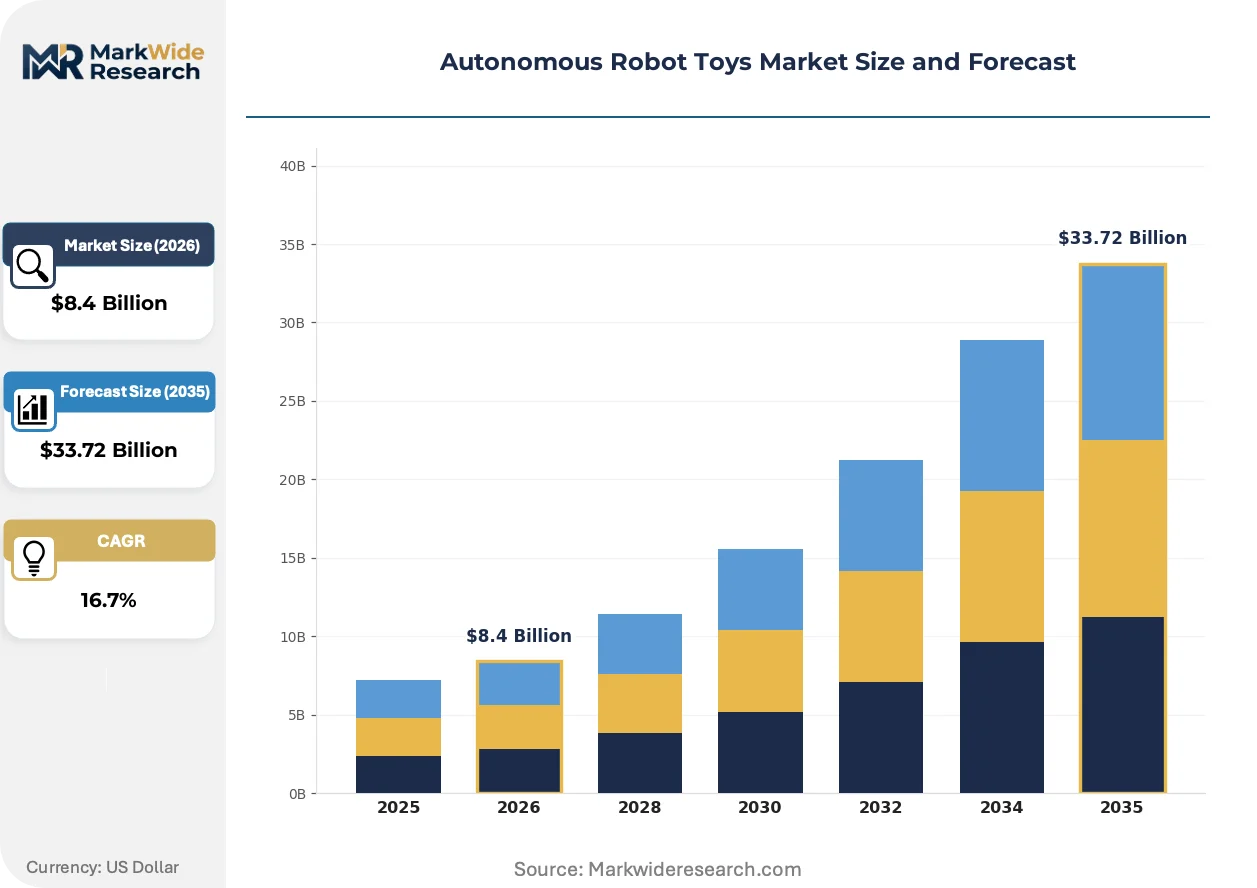
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Pets, Educational Robots, Puzzle Solvers, Action Figures, Programmable Robots, Robotic Vehicles Technology: Artificial Intelligence, Machine Learning, Voice Recognition, Gesture Control, Sensor Integration, Computer Vision Application: STEM Learning, Entertainment, Cognitive Development, Social Skills Training, Language Acquisition, Motor Skills Enhancement End User: Children Aged 3-6, Tweens Aged 7-12, Early Teens, Educational Institutions, Hobbyists, STEM Educators |
| Companies Covered | LEGO Group, Sphero, UBTECH Robotics, Parallax Inc., ArcBiotics, Dexter Industries, Fischertechnik GmbH, WowWee, Modular Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Robot Toys Market Strategic Shifts & Innovations
A fundamental shift toward embedded intelligence is redefining product capabilities. Onboard processing and machine learning are enabling robots to move from simple pre-programmed sequences to dynamic, responsive interactions that adapt to a child’s behavior and environment.
Edge AI, which performs computations directly on the device, is a key technological evolution. The educational robot segment for early teens is rapidly adopting this to power real-time navigation and personalization. On-device processing is supplanting cloud-dependent AI for core interactive features, mitigating latency and addressing parental concerns over data privacy.
The forthcoming EU AI Act is a significant regulatory development for the industry. This legislation will mandate risk assessments and strict compliance for AI systems, including those in toys that interact with children. Manufacturers targeting the European market are now proactively auditing their software and data governance frameworks to align with these emerging requirements.
Subscription models for new content are altering the traditional one-time purchase paradigm. This shift disrupts conventional retail channels by creating a continuous, direct-to-consumer relationship for delivering new learning modules and software updates. This trend is most prominent in the United States and Canada for advanced programmable robot kits.
Autonomous Robot Toys Market Segmentation
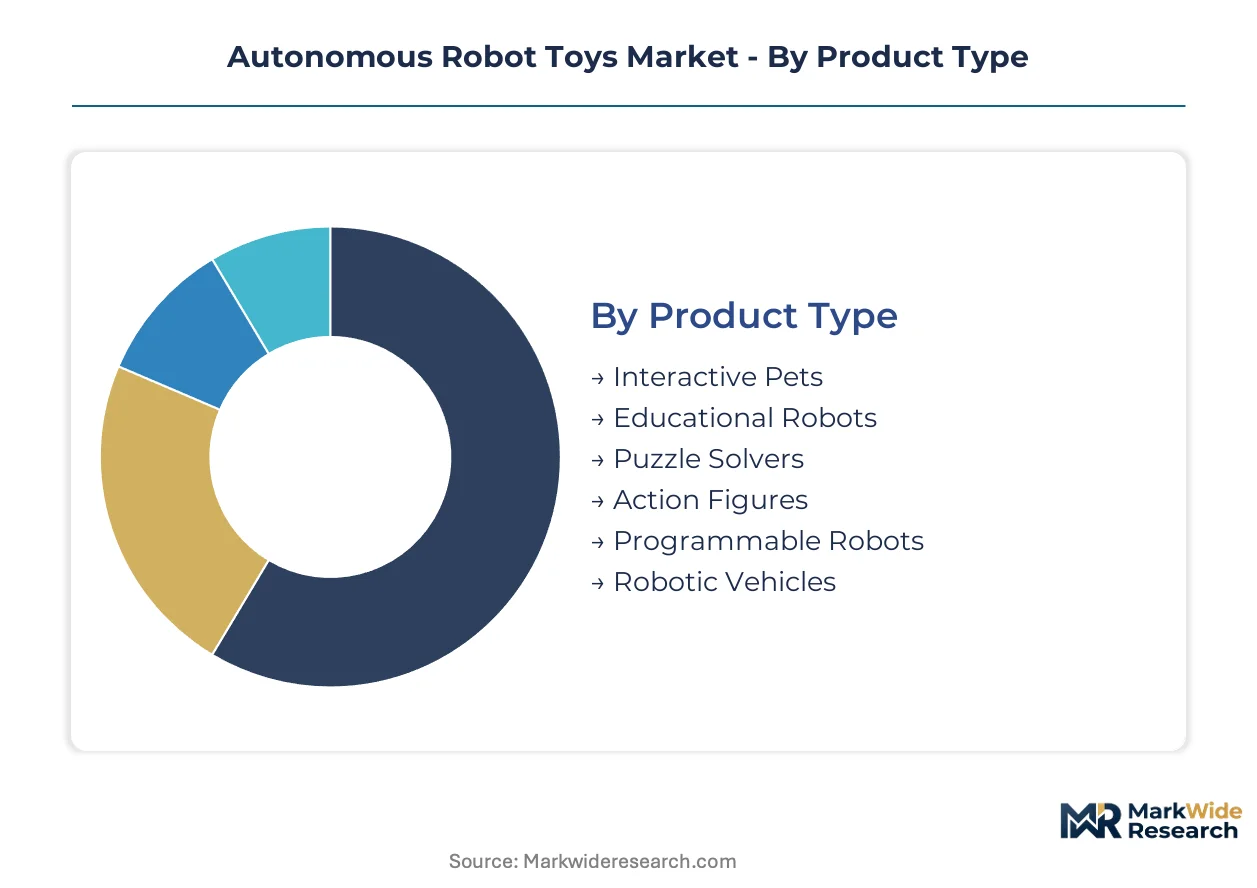
Understanding the autonomous robot toys market through segmentation reveals distinct value propositions and consumer behaviors. This detailed breakdown highlights specific product functionalities, underlying technological advancements, key applications, and target end-user groups. Strategic insights emerge from analyzing these segments, guiding product development and market entry efforts.
Product Type:
Margin pools within the product type segment often concentrate around advanced programmable robots and niche educational solutions requiring specialized software. These products command higher price points due to their complexity and educational value.
- Interactive Pets:These electronic companions simulate animal behavior, offering companionship and basic interaction through sensors. Demand for interactive pets remains consistent among younger children seeking emotional engagement.
- Educational Robots:Designed to teach coding, robotics, and STEM concepts through hands-on play. This segment shows the highest growth potential, particularly for early teens, driven by parental focus on cognitive development.
- Puzzle Solvers:Toys that challenge users with logic-based tasks, often incorporating autonomous movement or manipulation. These products appeal to consumers seeking cognitive stimulation.
- Action Figures:Autonomous action figures integrate basic movement and sound effects, providing dynamic play experiences. This segment caters to traditional toy markets with added technological features.
- Programmable Robots:Users can program these robots to perform custom sequences or tasks, fostering coding skills and creative problem-solving. The LEGO Group leverages strong brand recognition in this segment, dominating distribution channels.
- Robotic Vehicles:These include autonomous cars, drones, or other mobile platforms for racing, exploration, or task completion. Robotic vehicles offer dynamic entertainment and demonstrate engineering principles.
Programmable Robots holds installed capacity. Educational Robots is rotating up the share rankings.
Technology:
Supply concentration in the technology segment is heavily influenced by specialized component manufacturers for microprocessors and advanced sensors. These core technologies underpin the sophisticated capabilities of autonomous robot toys.
- Artificial Intelligence:AI capabilities enable robots to learn, adapt, and respond dynamically to user input and environmental changes. This technology powers real-time navigation and personalization, mitigating latency concerns.
- Machine Learning:Utilized for pattern recognition and predictive behavior, allowing robots to refine their interactions over time. On-device processing is supplanting cloud-dependent AI for core interactive features.
- Voice Recognition:This technology allows robots to understand and respond to spoken commands, enhancing interactive play experiences. Voice recognition improves user engagement for younger children.
- Gesture Control:Robots interpret and react to physical gestures, providing an intuitive and engaging control method. Gesture control offers a non-verbal interaction alternative.
- Sensor Integration:Incorporates various sensors like lidar for environmental mapping and obstacle avoidance, enabling autonomous navigation. The falling cost of these sensors enables more sophisticated environmental interaction.
- Computer Vision:Enables robots to "see" and interpret visual information, facilitating object recognition and facial tracking. Computer vision enhances educational and entertainment value.
Artificial Intelligence is gaining share fastest. Sensor Integration continues to drive product innovation.
Application:
Demand for specific applications is driven by the customer type, with educational institutions and parents prioritizing STEM learning and cognitive development features. Entertainment applications appeal to a broader consumer base.
- STEM Learning:Focuses on teaching science, technology, engineering, and mathematics principles through hands-on robot interaction. Government initiatives in the United States and Europe are creating dedicated demand for these products.
- Entertainment:Robots designed primarily for fun, games, and interactive play without explicit educational objectives. This segment combines engaging features with robust build quality.
- Cognitive Development:Toys engineered to enhance problem-solving, critical thinking, and memory skills in children. Parental focus on cognitive skills directly benefits this segment.
- Social Skills Training:Robots that facilitate interaction and communication, assisting children in developing social cues and empathy. Therapeutic applications are emerging in this area.
- Language Acquisition:Interactive robots designed to help children learn new languages through engaging exercises and pronunciation practice. These tools offer immersive linguistic experiences.
- Motor Skills Enhancement:Toys that encourage fine and gross motor skill development through manipulation and physical interaction. This application supports early childhood development.
STEM Learning sees the highest volume of new product introductions. Entertainment applications maintain broad consumer appeal.
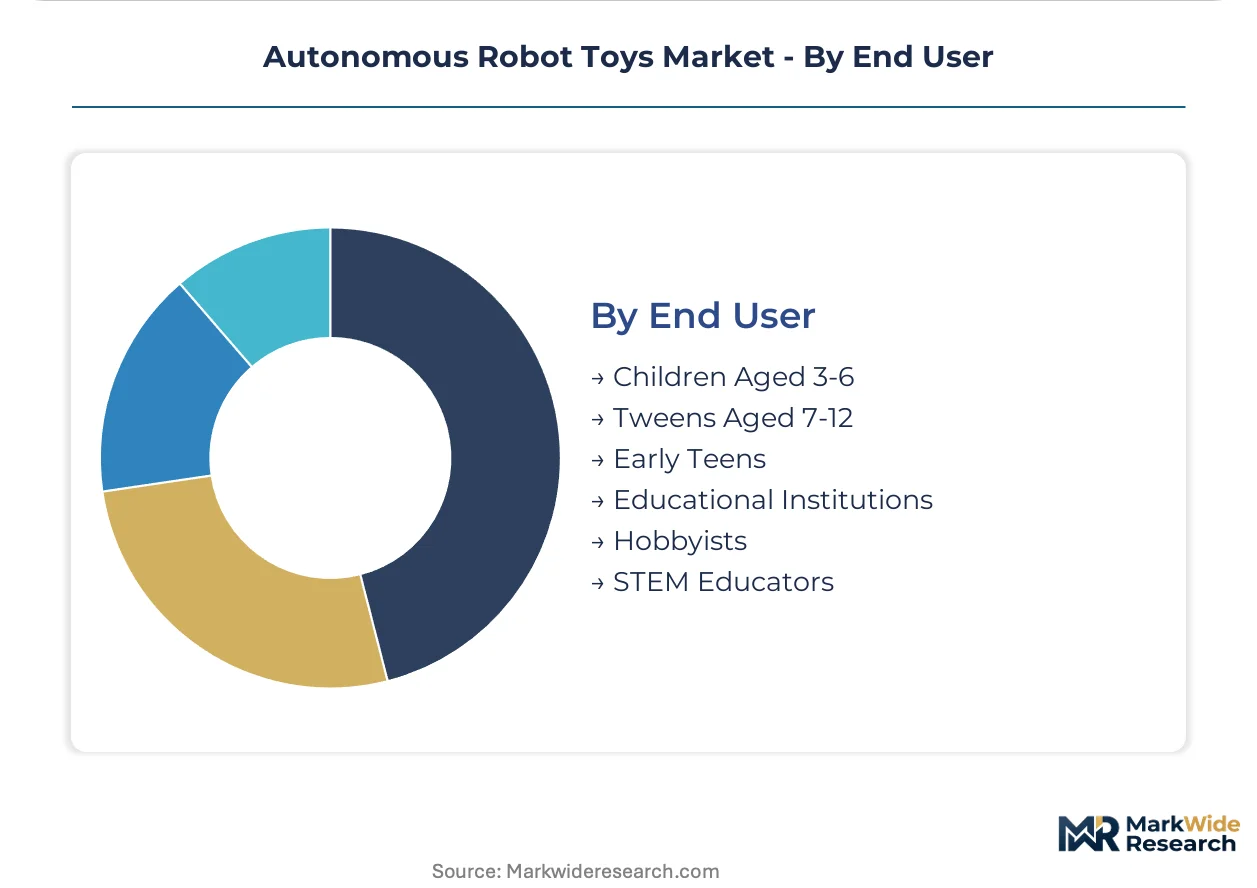
End User:
The cost tier for end-users varies significantly, with educational institutions and STEM educators often investing in higher-priced, feature-rich models. Individual consumers for younger age groups typically prefer more affordable options.
- Children Aged 3-6:Focus on simple, durable, and intuitive interactive robots promoting basic motor and cognitive skills. Safety certifications like CE marking are critical for this age group.
- Tweens Aged 7-12:Robots with more advanced programming capabilities and complex interactive features for engaging play. This group often seeks customizable and expandable toy systems.
- Early Teens:High-growth segment for sophisticated programmable robots and educational kits that teach advanced coding and robotics. This demographic shows significant interest in advanced AI features.
- Educational Institutions:Schools and after-school programs adopting programmable robots for curriculum integration. These institutions prioritize robust educational content and classroom management features.
- Hobbyists:Individuals who purchase advanced robots for personal projects, competitions, or in-depth learning. This group often seeks open-source platforms and customization options.
- STEM Educators:Professionals who use autonomous robots as teaching tools in formal and informal educational settings. They require reliable, curriculum-aligned, and easy-to-integrate solutions.
Early Teens represents a primary demand driver. Educational Institutions are increasingly integrating these solutions into their programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government initiatives in the United States and Europe promoting technology in education are creating dedicated demand for autonomous robot toys. These programs emphasize STEM learning, fostering a market environment where educational robots thrive. Global policies drive market expansion across diverse geographies.
United States
The United States market is driven by strong parental focus on cognitive skill development and widespread STEM curriculum integration. The US FCC's rules on radio frequency interference guide product design for connected toys. Silicon Valley and Boston serve as innovation hubs, attracting investment in advanced AI for educational robotics.
Germany
German consumers prioritize high-quality educational products, fostering demand for sophisticated programmable robots. Compliance with the EU's CE marking and RoHS directive ensures material and electrical safety standards. Bavaria's tech clusters, particularly around Munich, focus on precision engineering for robotic components.
India
India's expanding middle class and the National Education Policy create substantial demand for digital education tools. The BIS certification for consumer electronics influences market access for toy manufacturers. Bengaluru's IT sector is a growing hub for ed-tech startups developing localized content for robot toys.
Japan
Japanese parents value educational enrichment, driving interest in advanced AI-driven interactive toys. METI guidelines for product safety and digital content shape the development of new offerings. Tokyo's robotics research institutions collaborate on next-generation humanoid robot designs.
China
China's robust manufacturing base and increasing disposable income propel consumer spending on educational toys. GB standards for toy safety and hazardous substances dictate production processes. Shenzhen's extensive electronics supply chain supports rapid prototyping and mass production of autonomous robot components.
Autonomous Robot Toys Market Key Industry Players
Player mix skews toward a tiered structure, encompassing established toy manufacturers, specialized robotics firms, and innovative ed-tech startups. The market features global conglomerates alongside agile niche players. Strategic archetypes include traditional toy powerhouses leveraging brand recognition, and technology-focused specialists. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Within the established brand segment, LEGO Group exemplifies leveraging extensive distribution channels for programmable robots. Sphero represents a specialized approach, focusing on app-integrated robotic balls for educational and entertainment purposes. UBTECH Robotics anchors the advanced humanoid robot niche, differentiating through complex designs for STEM learning applications.
| Leading Market Players |
|---|
| LEGO Group |
| Sphero |
| UBTECH Robotics |
| Parallax Inc. |
| ArcBiotics |
| Dexter Industries |
| Fischertechnik GmbH |
| WowWee |
| Modular Robotics |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements for specialized microprocessors lock in both supply access and price visibility for autonomous robot toy manufacturers. These long-term contracts mitigate volatility in critical component sourcing.
Pricing Analysis
CE marking certification level creates the primary spread in autonomous robot toy pricing. The market operates on a hybrid model, combining per-unit transactional sales with subscription services for new content. Brand premium from established players like the LEGO Group also drives price differentiation. Pricing softness stems from competition from digital apps, making tweens aged 7-12 particularly price-sensitive, while educational institutions exhibit lower sensitivity.
Supply Chain Analysis
Long lead times for advanced AI chips necessitate strategic inventory management for autonomous robot toy manufacturers, with geographic supply concentration for microprocessors drawing from Taiwan and for precision components from Germany. The industry relies on specialized microprocessors, lidar sensors, and actuators as key raw materials. Single-source vulnerability for advanced AI chips represents a significant supply chain risk, impacting production timelines. Distribution runs through both direct-to-consumer channels for subscription models and established retail networks for physical products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous robot toys market is undergoing a high-growth disruption, driven by the integration of advanced AI capabilities and shaped by emerging legislation like the EU AI Act.
For Market Incumbents: Secure intellectual property for proprietary AI algorithms and unique humanoid robot designs to counter reverse-engineering threats. Deepen vertical integration into specialized sensor manufacturing to mitigate component cost volatility. These moves protect market share against agile ed-tech startups and ensure compliance with multi-jurisdictional safety standards like the EU's CE marking.
For New Entrants and Emerging Players: Certification fast-track for EU's CE marking and US FCC approval offers a streamlined path to market access. Target therapeutic applications for children with special needs, leveraging unmet demand in social-emotional learning. Partnerships with pediatric therapy centers or schools provide a direct-to-consumer go-to-market angle, bypassing traditional retail channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms offering subscription-based content and software updates for educational robots. The long-term viability remains strong, particularly in the STEM learning segment over the next decade. Acquisition targets should include specialists with proprietary AI for cognitive development and strong data privacy frameworks. A signal to watch is government spending trends on digital education infrastructure in emerging markets like India.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Diversification | Expands market reach by catering to diverse age groups and learning objectives. |
| Platform Integration | Enhances user experience by combining robot functionalities with augmented reality applications. |
| Strategic Partnership | Leverages brand recognition and distribution channels of established toy manufacturers for market penetration. |
| Geographic Expansion | Accesses new consumer bases, particularly in high-growth regions like India with supportive government policies. |
| Advanced Sensor R&D | Enables more sophisticated environmental interaction and personalized learning experiences for users. |
Research Approach
Operator-level perspectives from toy designers, AI engineers, STEM educators, and regulatory compliance officers anchored the qualitative base for this analysis. This primary research was triangulated with secondary validation from EU AI Act documents, US FCC filings, ISO standards, and company financial reports. Both bottom-up and top-down approaches were employed to ensure robust data integrity.
Sensitivity analysis informed the development of the market forecast across the modeling period. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and regional regulatory compliance. CAGRs were derived from historical data and industry projections, with key forecast inputs including STEM funding initiatives and specialized component cost trends.
Decision-makers should treat outputs as directional under base assumptions of a stable regulatory environment and consistent consumer spending; material deviation would warrant model refresh. Unforeseen data privacy legislation or rapid technological shifts in AI could significantly alter market dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Air Hockey Table Market
Toys and Games
Toy Cars Market
Toys and Games
Kid's Microphone Market
Toys and Games
Kids Toys Market
Toys and Games
Smart/AI Toys Market
Toys and Games
Robot Toys for Children Market
Toys and Games
Fabric Toys Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Inflatable Toys Market
Toys and Games
Bubble Tubes Market
Toys and Games
Remote Control Toys Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Games and Puzzles Market
Toys and Games
Bath Toy Market
Toys and Games
Indoor Bumper Cars Market
Toys and Games
Cat Toys Market