
 Eco-Friendly Toys Market | 2026-2036
Eco-Friendly Toys Market Size, Share, and Industry Trends Forecast 2026-2036
Eco-Friendly Toys Market Insights
The gap between premium certified wooden toys and lower-cost recycled-plastic alternatives is realigning shelf positioning and margin structures across retail channels. Lego anchors its position through captive manufacturing of plant-based polyethylene elements in Denmark and Mexico. Mattel differentiates via its PlayBack recycling program and commitments to bio-based packaging by specific target dates. Green Toys Inc. dominates the recycled-plastic tier through in-house production of food-safe HDPE vehicles and kitchen sets in California.
Eco-friendly toys are play products manufactured from sustainably sourced, non-toxic, biodegradable, or recycled materials, typically featuring water-based finishes and adhesives free of formaldehyde, phthalates, and heavy metals; their primary purpose is to deliver developmental play value while minimizing environmental impact and chemical exposure during critical childhood growth phases. Wood and bamboo segments command premium positioning due to FSC certification requirements and longer product lifecycles that support resale markets. Recycled plastic competes on price accessibility but faces margin pressure from feedstock volatility and batch consistency challenges. Online retail channels are capturing the fastest volume growth as direct-to-consumer brands bypass traditional toy store slotting fees and build subscription-based replenishment models.
ASTM F963 in the United States and EN71 in Europe set mandatory mechanical and chemical safety baselines that all market entrants must satisfy, while REACH restricts Substances of Very High Concern in coatings and colorants, effectively excluding uncertified Asian imports from premium European shelves. The EU Green Deal's circular economy action plan is extending producer responsibility requirements to toy packaging and end-of-life collection, forcing redesign of multi-material assemblies. Stakeholders must monitor how emerging state-level chemical disclosure laws in California and Maine cascade into de facto national compliance standards for manufacturers serving multiple distribution channels.
Market Dynamics
The EU Toy Safety Directive and REACH regulations are compressing formulation choices for coatings and plastics, forcing manufacturers to rebuild supply chains around certified bio-based feedstocks and water-based finishes.
Growth Catalysts
- REACH chemical restrictions:European regulators are banning phthalates and heavy metals in surface coatings, creating mandatory demand for reformulated water-based alternatives.
- Preschool parent segments:Early childhood development priorities are pulling non-toxic material specifications into mainstream retail assortments.
- German FSC-certified wooden toy traditions:Green consumerism in this market has established premium pricing power that subsidizes R&D across the category.
Market Restraints
- Recycled HDPE feedstock volatility:Post-consumer plastic bale prices swing with oil markets and municipal collection rates, compressing margins for recycled-plastic toy tiers.
- Asian import exclusion:Uncertified manufacturers face automatic disqualification from premium European shelves under SVHC documentation requirements.
- Batch consistency limitations:Recycled plastic color matching and mechanical property variation constrain aesthetic standardization.
Strategic Opportunities
- Subscription-based replenishment models:Direct-to-consumer brands are bypassing traditional toy store slotting fees through online channel capture.
- EU Green Deal circular economy mandates:Extended producer responsibility for packaging and end-of-life collection is forcing redesign of multi-material assemblies.
- Resale market infrastructure:Longer wooden toy lifecycles support secondary market platforms that extend brand touchpoints.
Industry Challenges
- Multi-material disassembly expertise:Circular economy compliance requires engineering talent capable of designing for end-of-life material separation.
- ASTM F963 and EN71 concurrent certification:Dual jurisdiction testing extends product development timelines and raises fixed compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco-Friendly Toys Market |
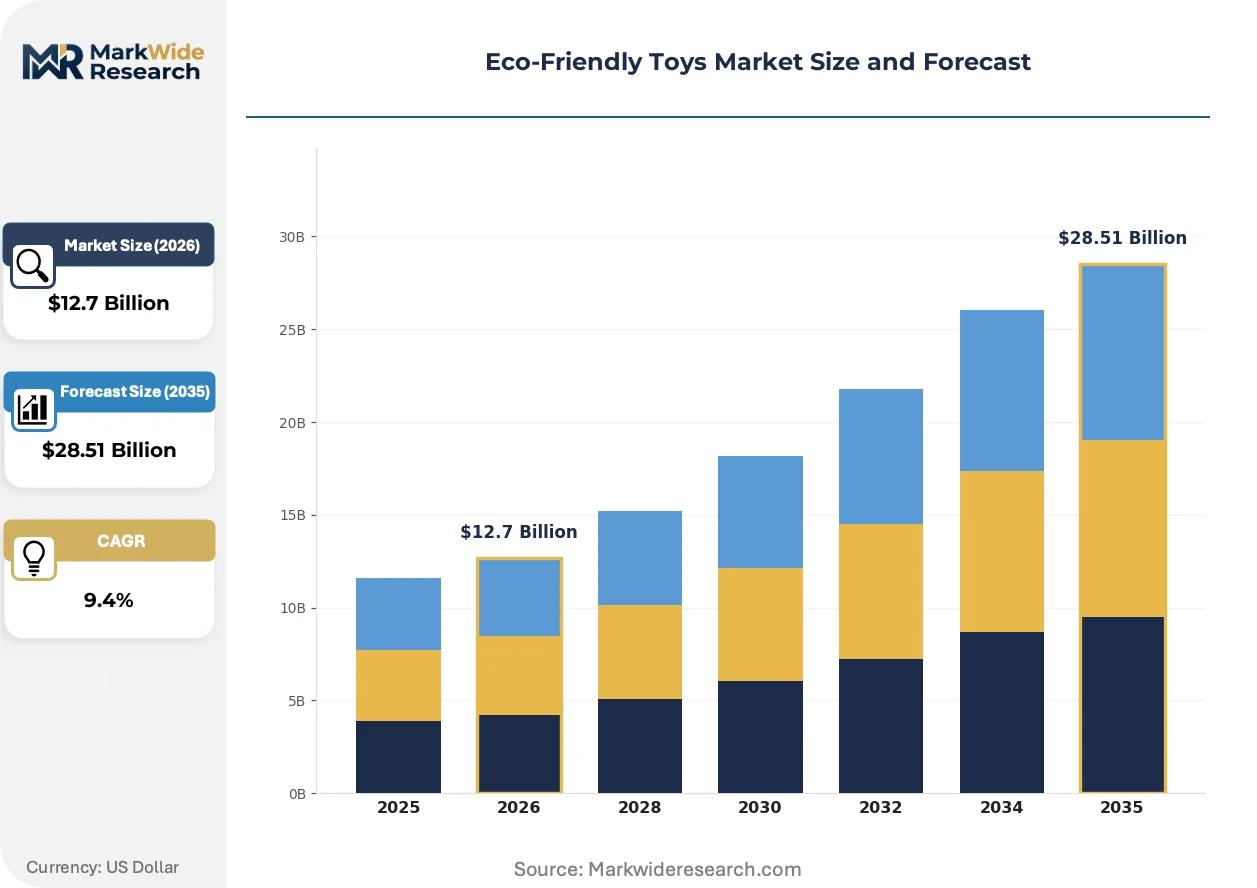
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Bamboo, Recycled Plastic, Organic Cotton Age Group: Infants, Toddlers, Preschoolers, School Age Sales Channel: Online Retail, Specialty Stores, Supermarkets, Toy Stores Certification: CE Mark, ASTM, EN71, FSC |
| Companies Covered | Green Toys Inc., Luke's Toy Factory, Lego, Wishbone, Begin Again, Mattel, Plan Toys, Pure Play Kids, Hasbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco-Friendly Toys Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape production economics, with automation and bio-based chemistry rewriting cost structures for compliant manufacturing.
Plant-based polyethylene formulation is automating the substitution of fossil-derived feedstocks in structural toy elements. Major manufacturers in Denmark and Mexico are scaling captive production of these biopolymers for integration into legacy molding infrastructure. The technology is automating compliance with EU Green Deal sourcing requirements while insulating supply chains from petrochemical price swings.
REACH Substances of Very High Concern listings are expanding quarterly, with ECHA adding new colorant and stabilizer chemistries to restricted substance inventories. Toy coating suppliers must now maintain dynamic formulation databases and rapid reformulation capabilities. Small and mid-tier Asian exporters are retreating from European distribution as documentation burdens intensify.
Certification-driven preference formation is restructuring retail assortment decisions. German and Scandinavian buyers now filter e-commerce search results by FSC and TÜV marks before price comparison. This behavior is concentrating volume with brands that have pre-invested in third-party validation, squeezing unverified competitors into discount channels.
Eco-Friendly Toys Market Segmentation
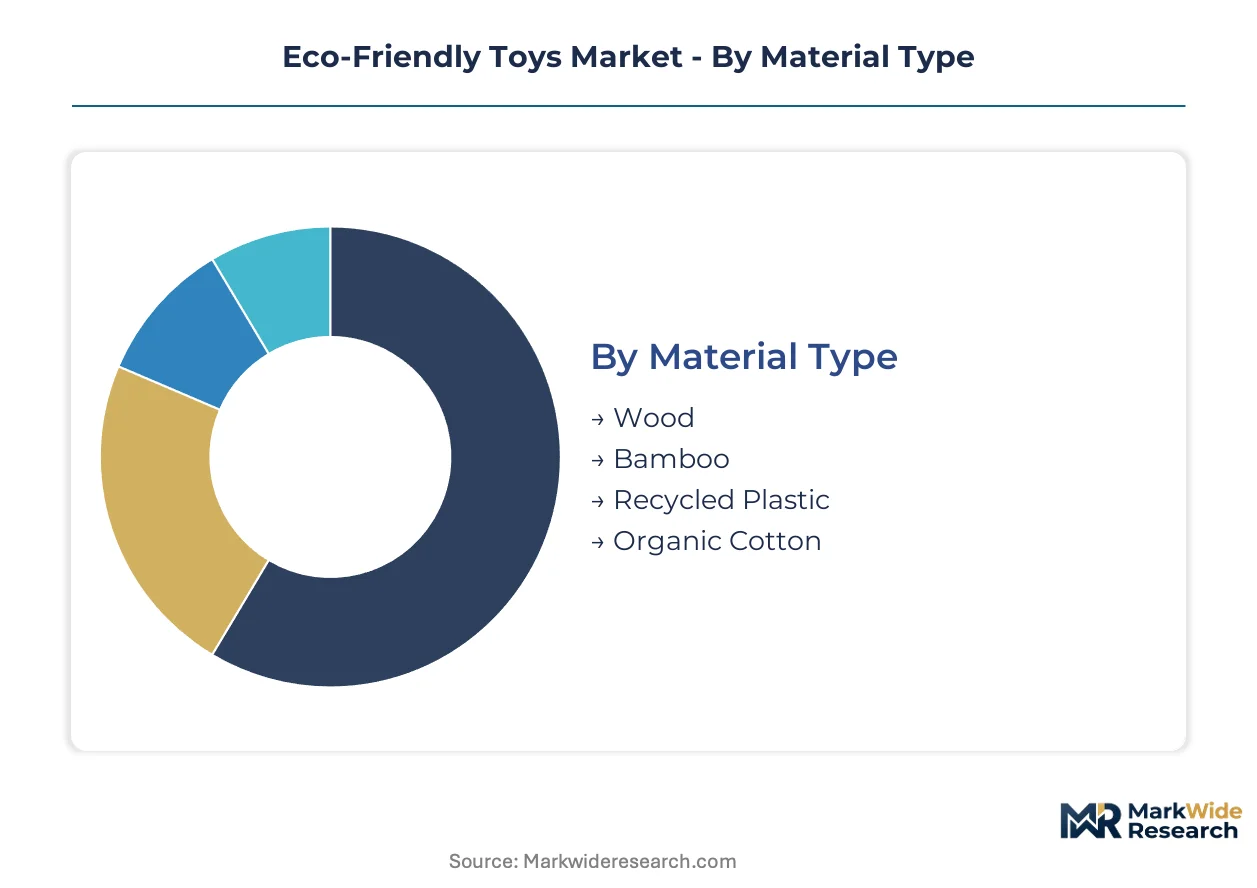
Segmentation in eco-friendly toys separates premium-certified wooden products from mass-market recycled-plastic alternatives, with each tier commanding distinct margin structures and retail channel strategies. Understanding these splits reveals where formulation investments concentrate versus where price accessibility drives volume.
Material Type:
Volume concentrates in recycled-plastic tiers while premium positioning anchors wood and bamboo segments with certification-linked pricing power.
- Wood:FSC-certified hardwoods and softwoods form the structural base of premium construction sets and educational toys. German and Scandinavian retail channels filter assortments aggressively for TÜV and FSC marks, creating automatic shelf exclusion for uncertified alternatives. Mature deployment sits with heirloom-quality building blocks and play kitchens. Newer deployment is concentrated in modular furniture-toy hybrids targeting extended use lifecycles.
- Bamboo:Rapid-renewal grass species processed into laminated sheet stock and solid turning blanks offer comparable durability to hardwoods with faster carbon payback. Chinese and Vietnamese processors dominate raw material supply, though European brands increasingly specify EU-Timber-Regulation-verified chain-of-custody documentation. Certification-driven preference formation is accelerating bamboo substitution in teething toys and infant grasping objects where mouth contact frequency is highest.
- Recycled Plastic:Post-consumer HDPE and PP reprocessed into food-safe vehicle and kitchen play sets competes on price accessibility. Feedstock volatility from municipal collection rate fluctuations compresses margins unpredictably.
- Organic Cotton:GOTS-certified fiber fills plush toys and fabric activity cubes, commanding premium positioning in infant segments where skin contact duration is longest.
Wood and bamboo together anchor the premium tier through certification infrastructure that recycled materials cannot yet replicate at scale.
Age Group:
Application requirements intensify material scrutiny as developmental vulnerability peaks in earliest years.
- Preschoolers:Children aged 3-5 years represent the steepest expansion trajectory as parental non-toxic priorities concentrate in early childhood development windows. Construction toys, role-play kitchens, and educational games in this bracket carry the strictest phthalate and heavy metal testing burdens under EN71-3 and ASTM F963 migration limits.
- Infants:Birth-to-12-month segments demand mouth-safe materials with zero formaldehyde emissions and saliva-resistant finishes. Teething toys and grasping rings in this category face REACH SVHC documentation requirements that exclude most uncertified Asian imports from European distribution.
- Toddlers:1-3 year age bracket balances durability needs against safety specifications for push toys and simple puzzles.
- School Age:6-12 year segments shift toward STEM kits and collectible construction systems where complexity tolerance rises and material contact duration falls.
Regulatory stringency peaks with infants, while volume concentration and growth velocity peak with preschoolers.
Sales Channel:
Channel economics separate direct-to-consumer subscription models from traditional retail slotting-fee structures.
- Online Retail:Direct-to-consumer platforms bypass toy store slotting fees and enable subscription-based replenishment models for consumable play components. German and UK consumers filter search results by certification marks before price comparison, concentrating volume with pre-validated brands.
- Specialty Stores:Curated independents and eco-focused chains command margin premiums through educated staff and tactile product interaction. These channels anchor brand positioning for wooden toy manufacturers seeking price integrity.
- Supermarkets:Mass-market grocery retail captures impulse purchases and gift-buying occasions with lower price points and reduced certification visibility.
- Toy Stores:Traditional specialty toy retail faces slotting fee pressure and assortment compression as online channels capture faster volume growth.
Online channels are gaining share fastest in subscription-compatible categories, while specialty stores defend margin in premium wooden segments.
Certification:
Compliance architecture determines market access with regional regulatory fragmentation creating testing cost multiplication.
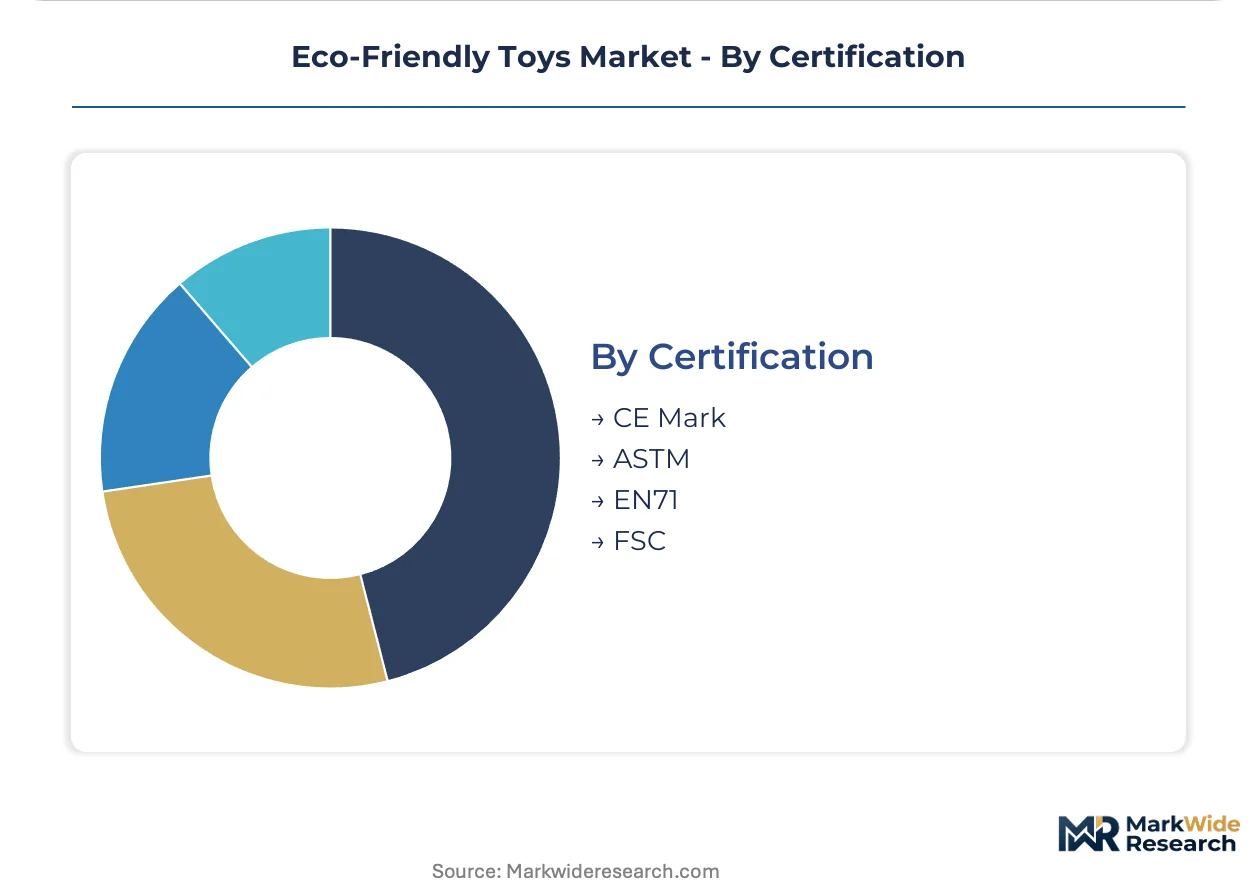
- EN71:European harmonized toy safety standard mandates mechanical, flammability, and chemical testing with EN71-3 migration limits for 19 elements. ECHA quarterly SVHC updates force dynamic formulation database maintenance among coating suppliers.
- FSC:Forest Stewardship Council chain-of-custody certification enables premium wooden toy positioning in German and Scandinavian markets where consumer filtering by sustainability marks is routine.
- CE Mark:Mandatory European conformity indicator for toy market access, backed by EN71 testing documentation and technical file maintenance.
- ASTM:US voluntary consensus standard F963 creates parallel testing requirements for manufacturers serving both jurisdictions, extending product development timelines.
Dual jurisdiction certification burdens fall heaviest on mid-tier manufacturers lacking dedicated compliance infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Billund anchors the highest-value production corridor through captive biopolymer manufacturing and integrated molding operations that supply European and North American distribution networks.
Germany
Parental demand for FSC-certified wooden construction sets and educational play systems drives premium-tier volume in Stuttgart and Nuremberg retail corridors. REACH Substances of Very High Concern listings force quarterly reformulation cycles among coating suppliers serving Bavarian toy manufacturers. The Swabian Jura region hosts precision woodturning clusters that supply heirloom-quality block systems to domestic and export markets.
United States
California and Maine state-level chemical disclosure laws cascade into de facto national compliance standards for manufacturers serving multi-channel distribution. ASTM F963 testing requirements parallel EN71 obligations for dual-jurisdiction exporters, extending product development timelines for mid-tier producers. The Los Angeles basin concentrates recycled-HDPE reprocessing capacity that feeds food-safe vehicle and kitchen set production for domestic consumption.
China
Guangdong and Zhejiang provinces process rapid-renewal bamboo into laminated sheet stock and solid turning blanks for European brand owners. EU Timber Regulation chain-of-custody documentation requirements exclude uncertified processors from premium distribution channels. The Pearl River Delta maintains specialized finishing facilities that apply water-based coatings compliant with EN71-3 migration limits.
Denmark
Captive plant-based polyethylene production in Jutland insulates supply chains from petrochemical price volatility while automating EU Green Deal sourcing compliance. ECHA quarterly SVHC updates drive dynamic formulation database maintenance among domestic chemical suppliers. Copenhagen-area design studios pioneer modular furniture-toy hybrids targeting extended use lifecycles and secondary market participation.
United Kingdom
Online retail channel capture accelerates in Greater London as direct-to-consumer brands bypass traditional toy store slotting fees through subscription-based replenishment models. CE marking and EN71 documentation requirements filter e-commerce search results by certification marks before price comparison. The Midlands region hosts third-party testing laboratories that serve continental European exporters seeking UKCA transition pathways.
Eco-Friendly Toys Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated manufacturers control biopolymer feedstocks and specialty fabricators concentrate on certified wooden craftsmanship. The market separates into three strategic archetypes: captive biopolymer molders, FSC-certified wood specialists, and recycled-plastic volume players. Consolidation pressure concentrates among mid-tier Asian exporters retreating from European distribution under intensifying documentation burdens. Dominant competitive moves include backward integration into bio-based feedstock production and geographic expansion through direct-to-consumer online channels.
Among integrated manufacturers with captive production capabilities, Lego exemplifies the biopolymer molder archetype through Denmark and Mexico-based operations. Green Toys Inc. occupies the recycled-plastic specialist position with California-based food-safe HDPE production. Mattel represents the diversified portfolio approach spanning multiple material tiers and certification levels.
| Leading Market Players |
|---|
| Green Toys Inc. |
| Luke's Toy Factory |
| Lego |
| Wishbone |
| Begin Again |
| Mattel |
| Plan Toys |
| Pure Play Kids |
| Hasbro |
| Others |
Pricing and Supply Chain Analysis
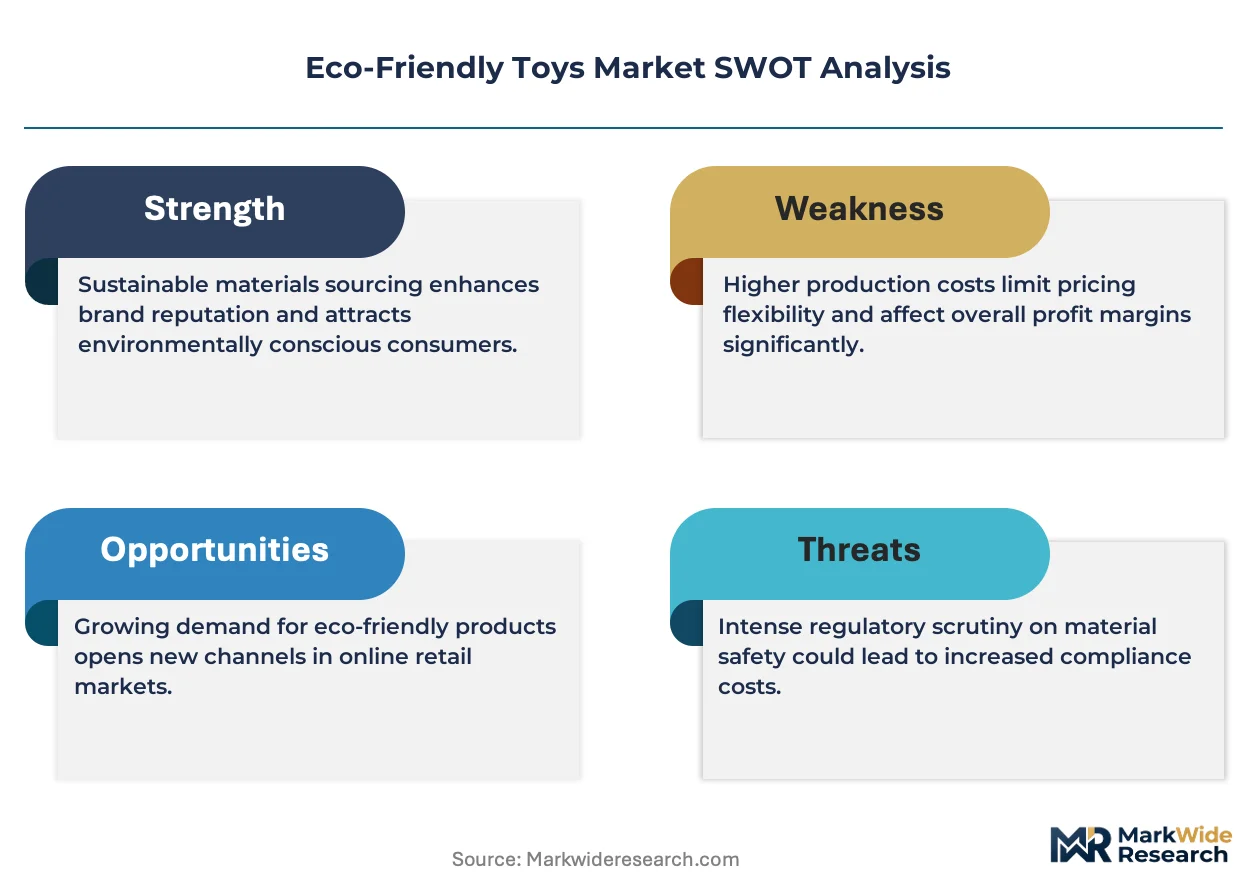
German FSC-certified wooden toy buyers anchor premium-tier pricing power through certification-filtered procurement that subsidizes R&D across the category while compressing margins for uncertified alternatives. REACH-driven reformulation cycles and feedstock volatility in recycled-plastic tiers create divergent cost structures that reshape competitive positioning across retail channels.
Pricing Analysis
Value-based pricing anchored to developmental safety outcomes dominates the preschool segment where parental non-toxic priorities command premium tolerance. Three-tier pricing structure across FSC-certified premium, EN71-compliant standard, and uncertified economy levels separates shelf positioning in German and Scandinavian retail. Cost compression in recycled-HDPE tiers intensifies because post-consumer bale prices swing with oil markets, squeezing volume players. Price sensitivity peaks among supermarket impulse buyers while specialty store shoppers tolerate certification premiums.
Supply Chain Analysis
Certification and qualification gating through EN71-3 migration limits and REACH SVHC documentation excludes uncertified Asian processors from premium European distribution. Manufacturing concentrates in Denmark for captive biopolymer production, Germany for precision woodturning clusters, and California for food-safe HDPE reprocessing. Raw material flows draw from FSC-certified Baltic forests, rapid-renewal Vietnamese bamboo plantations, and municipal post-consumer plastic collection systems. Single-source vulnerability sits with EU Timber Regulation chain-of-custody documentation that European brands require from Chinese processors. Distribution runs through direct-to-consumer online platforms that bypass traditional toy store slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a material-transition phase where plant-based polyethylene formulation displaces fossil-derived feedstocks in structural elements, rewriting cost structures for compliant manufacturing.
For Market Incumbents: Cement positioning through backward integration into bio-based feedstock production and captive certification infrastructure that emerging competitors cannot replicate at scale. Defend against direct-to-consumer subscription models by controlling specialty retail channel relationships where tactile product interaction sustains price integrity. Prioritize R&D investment in modular furniture-toy hybrids that extend use lifecycles and secondary market participation. For New Entrants and Emerging Players: Plant-based coating chemistry expertise offers entry into the reformulation service layer that REACH quarterly SVHC updates are forcing among Bavarian and Danish manufacturers. White-space concentrates in subscription-compatible consumable play components where replenishment models bypass slotting fee barriers. Target UK online retail channel capture through certification-mark-filtered search optimization that mirrors German consumer behavior. Go-to-market should anchor in third-party validation pre-investment that enables premium shelf positioning. For Investors and Strategic Acquirers: The window for entry favors mid-tier manufacturers with dedicated compliance infrastructure that can absorb retreating Asian export volume under intensifying documentation burdens. Long-term viability hinges on positioning ahead of EU Green Deal circular economy mandates that extend producer responsibility to packaging and end-of-life collection. Acquisition targets should demonstrate dynamic formulation database capabilities and rapid reformulation responsiveness to ECHA updates. Watch for inflection in state-level chemical disclosure law adoption beyond California and Maine that cascades into de facto national standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captive plant-based polyethylene production insulates against petrochemical volatility while automating EU Green Deal compliance. |
| Direct-to-Consumer Channel Expansion | Subscription-based replenishment models bypass traditional toy store slotting fees and build recurring revenue streams. |
| Certification Infrastructure Investment | FSC and TÜV pre-validation enables automatic shelf inclusion in German and Scandinavian retail filtering behavior. |
| Modular Product Architecture Development | Furniture-toy hybrids extend use lifecycles and enable secondary market platform participation for brand touchpoint extension. |
| Dynamic Formulation Database Maintenance | Rapid reformulation capabilities respond to quarterly REACH SVHC updates that exclude static competitors from European distribution. |
Research Methodology
Independent corroboration across primary interviews with toy manufacturing executives, coating supplier technical directors, specialty retail category buyers, and circular economy compliance officers underwrites the qualitative findings in this analysis. Secondary validation draws from ECHA SVHC registry updates, EU Timber Regulation documentation databases, FSC chain-of-custody certification records, and EN71 testing laboratory disclosures. Bottom-up demand modeling across age group and material type segments triangulates against top-down value chain analysis of biopolymer production capacity and recycled-plastic reprocessing throughput.
Comparable-period anchoring to historical certification adoption curves and regulatory implementation timelines shapes the projection horizon across the analysis window. Segmentation dimensions include material type, age group, sales channel, and certification tier with geographic regulatory cluster differentiation. CAGRs derive from elasticity-adjusted demand curves that weight parental non-toxic priority intensity against price accessibility thresholds in mass-market tiers. Forecast inputs incorporate REACH restriction expansion velocity and municipal post-consumer plastic collection rate variability.
Several conditions sit outside the modeled scope, including unforeseen ECHA acceleration of SVHC listings, abrupt shifts in oil-price-driven recycled feedstock economics, and state-level chemical disclosure law proliferation beyond current adoption patterns. Forecasts reflect assumptions about certification cost trajectories and consumer filtering behavior persistence that may revise under competitive entry or regulatory relaxation. Stakeholders should weight assumptions against their own operating context and compliance infrastructure capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Toy Building Blocks Market
Toys and Games
Orbital Action Jigsaw Market
Toys and Games
Playing Cards and Board Games Market
Toys and Games
Bubble Tubes Market
Toys and Games
Sustainable Toys Market
Toys and Games
Bounce House Market
Toys and Games
Ferret Toys Market
Toys and Games
Kids Toys Market
Toys and Games
US BDSM Sex Toys Market
Toys and Games
Board Games and Puzzles Market
Toys and Games
Claw Crane Machine Market
Toys and Games
Plush Toy Market
Toys and Games
Global Stem Toys Market
Toys and Games
Decompression Toys Market
Toys and Games
Kid's Microphone Market
Toys and Games
Bubble Blower Market