
 Toys and Games Market | 2026-2036
Toys and Games Market Size, Share, and Industry Trends Forecast 2026-2036
Toys and Games Market Intelligence
Expanded manufacturing capacity in Vietnam is reshaping competitive positioning among leading toy producers. This shift diversifies supply chains traditionally centered elsewhere. The LEGO Group sustains its market leadership through strong brand loyalty and a focus on its proprietary interlocking brick system. Hasbro leverages its extensive portfolio of intellectual property across games and action figures, while Mattel competes through iconic brands and a multi-channel retail strategy.
Toys and games encompass items designed for play, entertainment, or education, primarily for children but also for adults and collectors. These products are often manufactured from injection-molded plastics like ABS and polypropylene, and must adhere to strict material safety specifications regarding chemical content. Their primary purpose is to stimulate cognitive, social, and physical development. The market shows significant value in the Educational Toys and Construction Sets segments. Online Marketplaces are rapidly gaining share from traditional Specialty Retailers and Department Stores as the dominant distribution channel.
The industry operates under stringent safety regulations enforced by multiple bodies. In the United States, the CPSC mandates compliance with standards like ASTM F963, while the EU's Toy Safety Directive requires CE marking. Similarly, China enforces its own GB standards, creating a complex global compliance landscape for manufacturers. These rules dictate material composition, small-part warnings, and age-grading. Navigating the convergence of digital privacy rules and connected toy features presents the next critical challenge for developers and marketers.
Market Dynamics
The convergence of digital technology with physical playthings defines the market's central dynamic. This requires manufacturers to navigate complex data privacy regulations while developing integrated hardware and software, altering product design and marketing strategies.
Growth Catalysts
- Augmented Reality Integration:Fusing AR with physical toys creates interactive experiences, boosting engagement in educational products and extending their lifecycle.
- Institutional Adoption:The educator segment increasingly uses developmental toys for STEM curricula, creating a stable, non-seasonal B2B demand channel.
- Demand Concentration in China:China's expanding middle class shows strong preference for premium and educational toys, creating a primary geographic growth vector.
Market Restraints
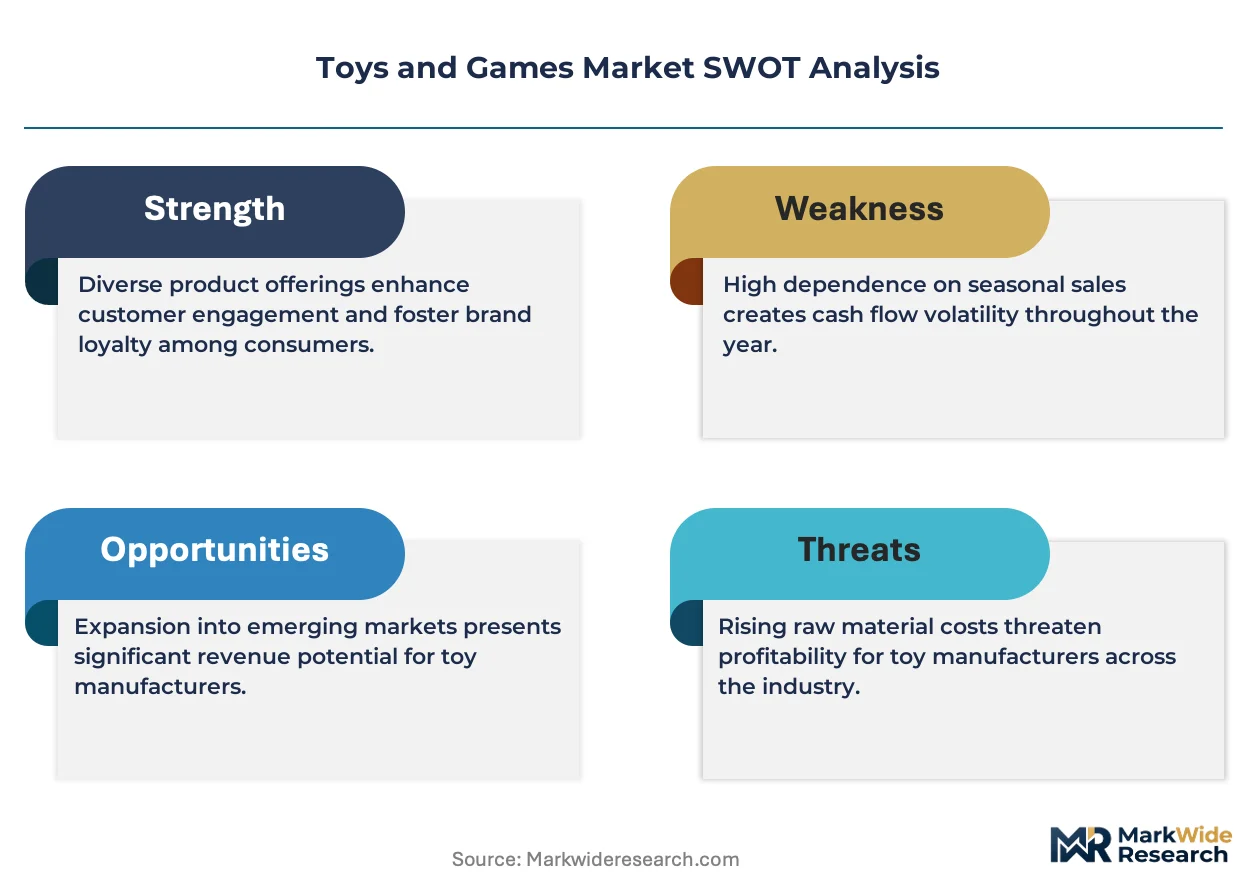
- Input Cost Volatility:Fluctuating prices for plastics like ABS and polypropylene directly impact manufacturing costs and compress producer margins.
- Regulatory Fragmentation:Divergent safety standards, including ASTM F963 in the US and the EU's Toy Safety Directive, create complex compliance burdens.
- Supply Chain Concentration:Over-reliance on manufacturing in a few Asian countries creates vulnerabilities to logistical disruptions and geopolitical risks.
Strategic Opportunities
- Connected Play Ecosystems:Integrating IoT sensors and companion apps with traditional toys creates opportunities for subscription services and personalized content.
- Adult Collector Market:The growing "kidult" segment presents an opportunity for high-margin construction sets, licensed replicas, and complex board games.
- Sustainable Materials:Developing toys from bio-plastics or recycled materials attracts environmentally conscious consumers and aligns with circular economy goals.
Industry Challenges
- Digital Privacy Compliance:For connected toys, navigating disparate data privacy laws like the EU's GDPR and the US's COPPA presents a significant legal and technical hurdle.
- Intellectual Property Licensing:Securing and managing licenses for entertainment franchises is costly and complex, creating high barriers for new entrants in the character-based toy segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toys and Games Market |
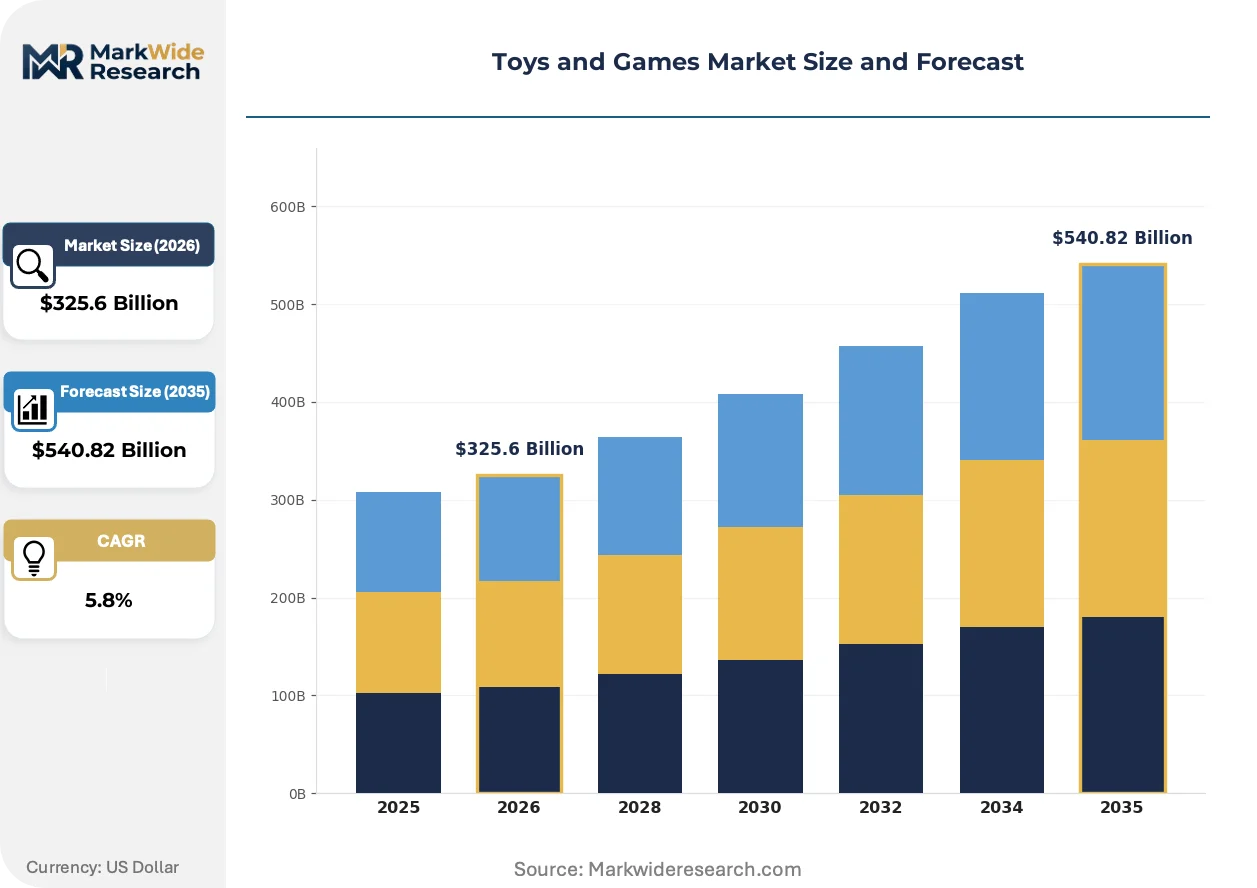
| Market Size in 2026 | $325.6 Billion |
| Market Size in 2035 | $540.82 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Figures, Educational Toys, Puzzles, Board Games, Remote Control Toys, Construction Sets Age Group: Infants, Toddlers, Preschoolers, Early School Age, Tweens, Teens Distribution Channel: Specialty Retailers, Online Marketplaces, Department Stores, Mass Merchandisers, Direct-to-Consumer End User: Children, Collectors, Educators, Hobbyists, Gift Buyers |
| Companies Covered | Spin Master, MGA Entertainment, The LEGO Group, VTech Holdings Ltd., Funko, Inc., Mattel, Bandai Namco Holdings Inc., Playmates Toys Limited, Hasbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toys and Games Market Strategic Shifts & Innovations
The market's evolution is driven by the dual forces of digitalization and sustainability. These trends compel manufacturers to innovate beyond physical product design, focusing on integrated digital experiences and responsible material science.
Connected play platforms integrate IoT sensors and software into traditional toys, enabling interactive feedback and adaptive content. Parents and educators adopt these tools to support personalized learning and track milestones. This integration is rendering obsolete the model of static, single-function toys without a digital component.
Heightened regulatory scrutiny, exemplified by the EU's Toy Safety Directive, imposes strict chemical and safety requirements under the CE marking framework. This increases compliance overhead and lengthens development timelines. The directive particularly affects smaller producers who must invest heavily in testing to access the European market.
Consumer purchasing is shifting from planned trips at specialty retail stores to discovery on large online marketplaces. This channel migration disrupts the traditional distribution model, reducing the influence of in-store merchandising. The trend is most advanced in North America and Western Europe.
Toys and Games Market Segmentation
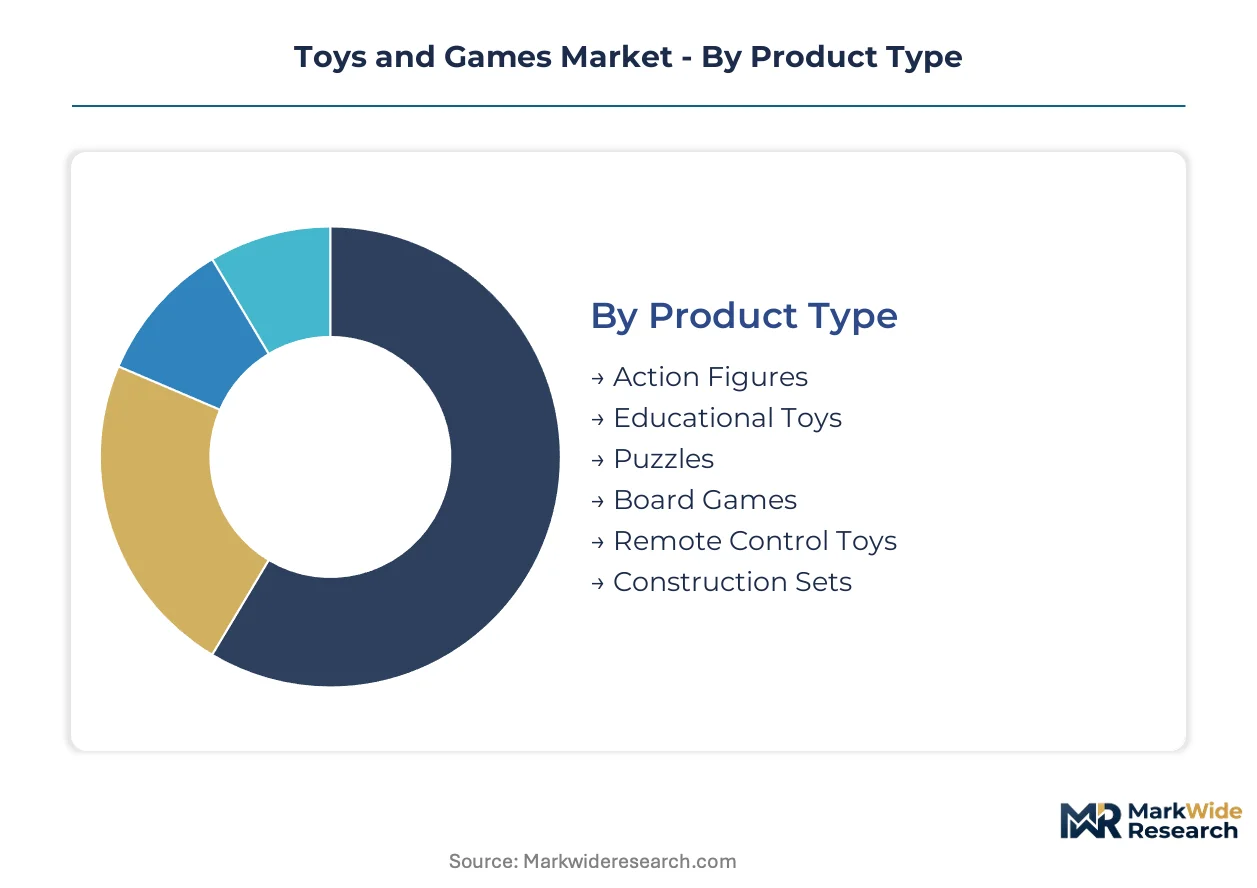
The Toys and Games market diversifies across product functionalities and consumer demographics, influencing manufacturing complexity and marketing approaches. Understanding these distinct segments is critical for producers to tailor offerings and distribution strategies effectively. This market analysis delineates key categories shaping demand and supply dynamics.
Product Type:
The intensity of after-sales service varies significantly across product types, driven by embedded technology and interactive features. Products with digital components often require software updates and technical support, impacting manufacturer resources and consumer satisfaction metrics.
- Educational Toys:These products are designed to stimulate cognitive, social, and physical development, often integrating STEM principles. Demand concentrates in the educator segment, driven by institutional adoption for curricula and personalized learning.
- Construction Sets:Featuring proprietary interlocking brick systems or modular components, these sets allow for creative assembly and reassembly. The adult collector market shows strong preference for complex sets, seeking intricate designs and licensed replicas.
- Action Figures:These articulated figurines represent characters from popular media franchises, appealing primarily to children and collectors.
- Puzzles:Ranging from simple jigsaws to complex 3D models, puzzles challenge problem-solving skills across various age groups.
- Board Games:Offering social interaction and strategic thinking, board games continue to attract families and adult enthusiasts.
- Remote Control Toys:These electronic vehicles or devices operate via remote control, providing interactive play experiences with varying degrees of complexity.
By volume, Action Figures lead. By growth pace, Educational Toys are ahead.
Age Group:
The cost tier for toys and games often correlates with the target age group, reflecting material complexity, safety requirements, and technological integration. Products for younger children prioritize durability and safety, while those for older groups may feature advanced electronics.
- Early School Age:Products for this group focus on foundational learning and skill development, often incorporating educational content. The segment drives demand for STEM-focused toys, influencing curriculum development in educational institutions.
- Tweens:This demographic increasingly seeks toys with digital integration and social connectivity, driving innovation in connected play ecosystems. Demand for interactive hardware and companion apps is high among this tech-savvy group.
- Infants:Toys for infants emphasize sensory stimulation and basic motor skill development, adhering to stringent safety standards.
- Toddlers:Products for toddlers focus on exploration, cause-and-effect learning, and early imaginative play.
- Preschoolers:This group engages with toys that foster creativity, role-playing, and early cognitive abilities.
- Teens:Older teens show preference for complex board games, collectibles, and advanced hobby kits.
This age segmentation highlights distinct developmental needs, with product design directly catering to cognitive and physical milestones.
Distribution Channel:
The functional application of each distribution channel dictates its strategic importance for toy manufacturers, influencing market reach and consumer engagement. Online platforms prioritize convenience and selection, while physical stores offer tactile experience and immediate gratification.
- Online Marketplaces:These digital platforms offer extensive product catalogs, competitive pricing, and direct-to-consumer shipping, rapidly gaining share as the dominant channel. Consumer purchasing shifts from traditional retail to discovery on these platforms, especially in North America.
- Specialty Retailers:These stores focus on curated selections, expert staff, and unique product experiences, serving niche markets and premium brands. While losing share, they remain important for product discovery and direct customer interaction.
- Department Stores:Offering a broad range of products, department stores provide convenience but face strong competition from online channels.
- Mass Merchandisers:Characterized by high volume and lower prices, these retailers serve a broad consumer base with popular toy lines.
- Direct-to-Consumer:Brands selling directly to consumers through their own websites allows for greater control over brand messaging and customer data.
The competitive landscape among distribution channels is consolidating, with online platforms exerting increasing influence over consumer purchasing habits.
End User:
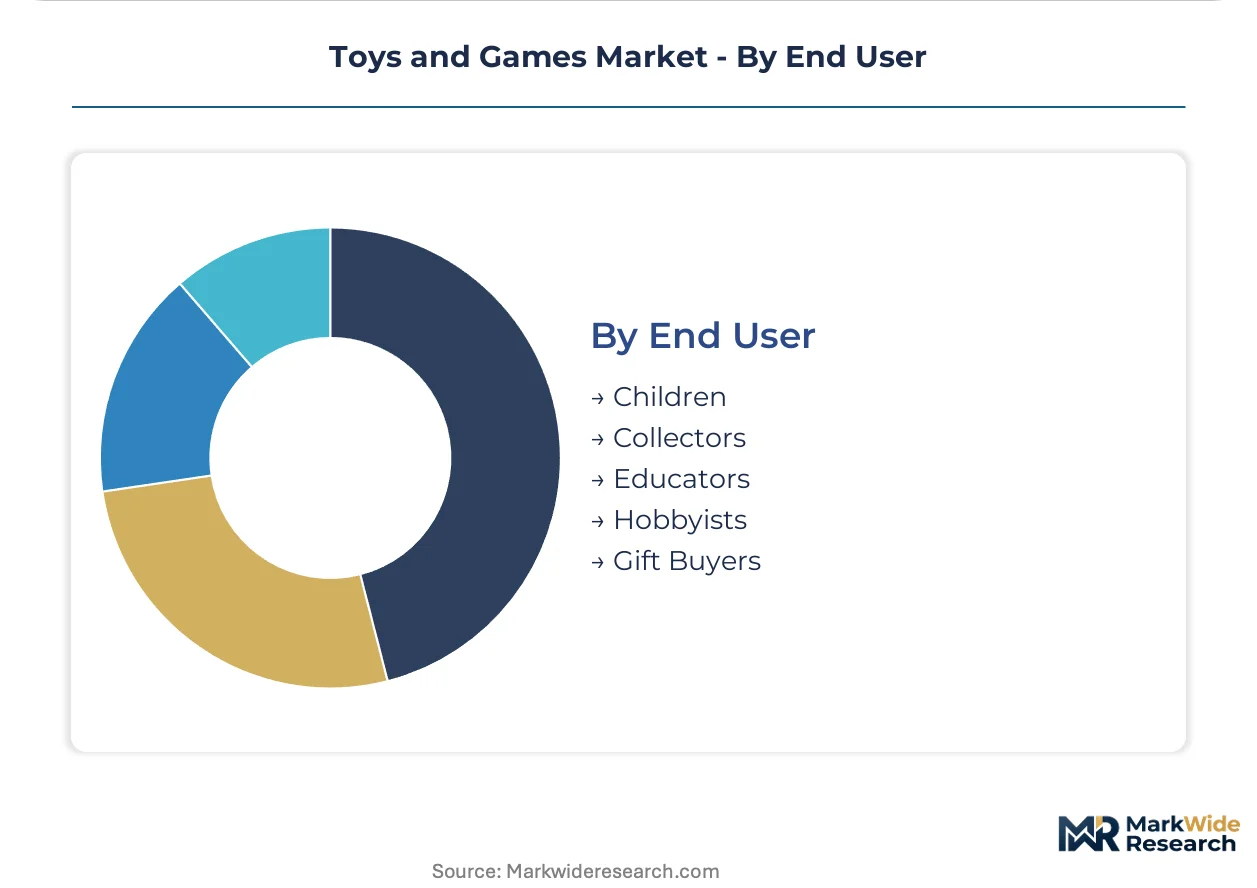
The volume of purchases varies significantly among end-user segments, reflecting distinct motivations and purchasing power within the toys and games market. Children represent the largest volume of direct consumption, while educators drive consistent institutional demand.
- Educators:This segment utilizes developmental toys for STEM curricula and personalized learning, creating a stable B2B demand channel. Institutional adoption of educational products provides consistent, non-seasonal purchasing patterns.
- Collectors:The growing "kidult" segment drives demand for high-margin construction sets, licensed replicas, and complex board games. This demographic seeks premium, often limited-edition, products for display and investment.
- Children:The primary end-user group, children drive demand for a wide array of toys for play and entertainment.
- Hobbyists:Individuals pursuing specific interests, such as model building or tabletop gaming, form a dedicated segment for specialized products.
- Gift Buyers:This segment purchases toys for others, often influenced by seasonal trends and marketing campaigns.
Understanding these end-user preferences is essential for manufacturers to align product development and marketing strategies effectively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global Toys and Games market exhibits diverse consumption patterns, with some regions prioritizing educational value while others focus on digital integration. China's expanding middle class drives demand for premium products, contrasting with the mature markets' emphasis on connected play. This differential impacts product development and distribution strategies globally.
China
China's expanding middle class shows strong preference for premium and educational toys, creating a primary geographic growth vector. The country's GB standards enforce strict material safety and quality requirements for all imported and domestically produced toys. Manufacturing hubs in the Pearl River Delta continue to innovate in production techniques and supply chain efficiency.
United States
American consumers increasingly seek toys with digital integration and interactive experiences, particularly in the tech-savvy tween demographic. The CPSC mandates compliance with safety standards like ASTM F963 to ensure product safety for children. Major toy companies headquartered in California and the Northeast drive innovation in connected play ecosystems.
Germany
German households prioritize durable and high-quality toys, influencing product design towards longevity and educational benefit. The EU's Toy Safety Directive requires CE marking, ensuring stringent chemical and safety requirements are met. Bavarian manufacturers often lead in sustainable material development and traditional craftsmanship.
Vietnam
Expanded manufacturing capacity in Vietnam is reshaping competitive positioning among leading toy producers, diversifying global supply chains. The Vietnamese government actively promotes foreign investment in manufacturing, creating favorable conditions for export-oriented industries. Production facilities around Ho Chi Minh City are becoming key centers for high-volume toy production.
Toys and Games Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The toys and games market features a mix of established global brands, innovative niche players, and large-scale contract manufacturers. Strategic archetypes include intellectual property holders, specialized educational toy developers, and mass-market producers focused on volume. Leading players frequently engage in portfolio diversification and strategic partnerships to expand market reach and integrate digital technologies into physical playthings.
On the premium-tier vector, The LEGO Group exemplifies market leadership through its proprietary interlocking brick system and strong brand loyalty. Hasbro, a major intellectual property holder, leverages its extensive portfolio across games and action figures. Mattel represents a competitor with iconic brands, utilizing a multi-channel retail strategy to reach diverse consumer segments. These companies anchor the market through continuous innovation in product design and engagement with evolving consumer preferences, particularly in digital integration and collectible markets.
| Leading Market Players |
|---|
| Spin Master |
| MGA Entertainment |
| The LEGO Group |
| VTech Holdings Ltd. |
| Funko, Inc. |
| Mattel |
| Bandai Namco Holdings Inc. |
| Playmates Toys Limited |
| Hasbro |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lane cost dynamics directly influence manufacturing concentration in Asia and downstream price differentiation across global toy markets. This interplay shapes both producer margins and consumer accessibility for various product tiers.
Pricing Analysis
Geographic price spreads reflect varying regulatory compliance costs and brand premiums across regions. The market primarily operates on a per-unit transactional pricing model, often augmented by licensing fees for character-based toys. Price differentiation drivers include brand equity, material safety certification (e.g., CE marking, ASTM F963), and the level of digital integration. Pricing softness stems from intense competition on online marketplaces and fluctuating input costs for plastics like ABS. Mass merchandiser consumers exhibit high price sensitivity, while adult collectors prioritize premium features and brand authenticity.
Supply Chain Analysis
Export-control regimes for advanced components, particularly those used in connected toys, limit technology flows and influence manufacturing locations. Supply concentration is prominent in China and Vietnam, which serve as major production hubs for injection-molded plastics. Raw material dependencies include ABS and polypropylene resins, along with specialized electronic components for interactive toys. Geopolitical risks and logistics chokepoints present a structural supply chain vulnerability. Downstream distribution runs through a hybrid model, with online marketplaces rapidly gaining share from traditional specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The toys and games market is experiencing a significant buyer-power shift, driven by the consolidation of purchasing influence within large online marketplaces.
For Market Incumbents:
Harden supply chain resilience by diversifying manufacturing capacity beyond single-country reliance, particularly into regions like Vietnam. Incumbents should invest heavily in proprietary digital ecosystems and content to counter the threat of generic product commoditization. Leveraging extensive intellectual property portfolios for cross-platform play experiences creates durable competitive advantages. Continuous innovation in material science and sustainable packaging also reinforces brand loyalty.
For New Entrants and Emerging Players:
Underpenetration in niche educational toy segments within developing economies offers significant market entry opportunities. Target the institutional educator segment with STEM-focused products that align with curriculum standards. A direct-to-consumer go-to-market strategy, leveraging digital marketing and community building, can bypass established retail channels. Focus on unique play patterns or sustainable material innovations to differentiate from mass-market offerings.
For Investors and Strategic Acquirers:
The EU's Toy Safety Directive reshapes the acquisition landscape, favoring companies with robust compliance frameworks and R&D in safe materials. Long-term viability rests with firms possessing strong intellectual property, advanced digital integration capabilities, or proven expertise in sustainable product development. Acquisition targets should include specialized technology firms in augmented reality or IoT for toys, and established educational toy brands. Investors should monitor evolving digital privacy legislation for connected toys as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Ecosystem Development | Integrates hardware and software for recurring revenue streams. |
| Sustainable Material Adoption | Attracts environmentally conscious consumers and meets regulatory goals. |
| Supply Chain Diversification | Mitigates geopolitical risks and input cost volatility. |
| IP Portfolio Expansion | Secures character-based revenue and broadens market appeal. |
| Educator Segment Partnerships | Establishes stable B2B demand and validates product efficacy. |
Research Approach
A spread of perspectives from toy manufacturers' R&D heads, online retail buyers, educational institution procurement officers, and material suppliers converged on the working assumptions. This primary research was validated against secondary data from industry reports, regulatory body publications (CPSC, EU Toy Safety Directive, China GB standards), and financial filings of public toy companies. The analysis utilized both bottom-up market sizing and top-down validation to ensure data integrity.
The analytical framework assessed demand drivers against supply capabilities across the projection horizon to model market evolution. Segmentation dimensions modeled included product type, age group, distribution channel, end-user, and regional economic growth patterns. Compound annual growth rates were calculated from historical trends and projected future market shifts. Key forecast inputs included plastic resin prices and consumer disposable income growth rates in primary markets like China.
Practitioners should monitor shifts in global trade policies, significant advancements in AR/VR technology, or major changes to digital privacy laws for early signals. Forecasts reflect assumptions regarding regulatory stability and technological adoption. Material shifts in consumer spending patterns or regulatory compliance frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Toy Collectibles Market
Toys and Games
Microwaveable Stuffed Animal Toys Market
Toys and Games
Glow Sticks Market
Toys and Games
Kids Fuse Beads Market
Toys and Games
Pre-School Games and Toys Market
Toys and Games
Arcade Games Machine Market
Toys and Games
Bubble Blower Market
Toys and Games
Sustainable Toys Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Baby Toys Market
Toys and Games
Plastic Toy Storage Market
Toys and Games
China Toys Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Global Toys Market
Toys and Games
Coaster Market