
 Board Games and Puzzles Market | 2026-2036
Board Games and Puzzles Market Size, Share, and Industry Trends Forecast 2026-2036
Board Games and Puzzles Market Outlook
Premium heirloom-grade specifications are rotating toward the center of manufacturer strategy as consumers prioritize durability and collectible value over disposable entertainment. Ravensburger AG leverages its German manufacturing heritage to sustain precision-cut puzzle quality across premium price bands. Hasbro Inc. anchors mass-market board game distribution through deep channel control in North American big-box retail. Asmodee Group differentiates through specialized hobby-game content and dominant positioning in European tabletop gaming communities.
Board games and puzzles comprise structured play systems employing printed cardstock, engineered wood fiberboard, thermoplastic tokens, and randomized or deterministic rule sets to deliver competitive or cooperative entertainment experiences. Manufacturing relies on precision die-cutting, offset lithography with food-safe inks, and injection molding to achieve dimensional tolerances critical for fit and finish. Strategy games command the strongest margin pools among product types due to recurring expansion content and community-driven network effects. Jigsaw puzzles occupy a mature but resilient position where adult-oriented piece counts and fine-art licensing sustain premium pricing. Family-targeted age segments generate the highest absolute volume through holiday gifting cycles and mass merchant placement.
The US Consumer Product Safety Commission enforces ASTM F963 toy safety standards that govern small-part thresholds and phthalate restrictions for components accessible to children under three. The European Chemicals Agency administers REACH substance restrictions affecting adhesive formulations and surface coatings used in printed game boards. California's Proposition 65 labeling requirements create additional compliance burdens for products distributed through US West Coast retail channels. Stakeholders must monitor evolving extended producer responsibility frameworks in France and Germany that could mandate recyclability disclosures and packaging reduction targets for toy and game manufacturers.
Market Dynamics
REACH substance restrictions from the European Chemicals Agency are forcing wholesale reformulation of adhesives and surface coatings across wooden puzzle and board game manufacturing, compressing supplier margins while accelerating certification timelines.
Growth Catalysts
- Multi-generational household entertainment spending:Family-oriented purchasing patterns are intensifying demand for cooperative gameplay formats that bridge age demographics.
- REACH compliance-driven material innovation:European regulatory pressure on phthalate-free inks and bio-based adhesives is stimulating investment in safer, premium-positioned product lines.
- German design-manufacturing cluster density:Concentrated expertise in precision die-cutting and fine-art licensing around Ravensburg creates knowledge spillovers benefiting adjacent producers.
Market Restraints
- Engineered wood fiberboard input volatility:Fluctuating pulp costs and freight surcharges compress margin pools for mid-tier puzzle manufacturers dependent on imported substrate.
- Injection molding supply concentration in East Asian toolmakers:Thermoplastic token and miniature production remains captive to a narrow supplier base, exposing lead time risks.
- California Proposition 65 labeling friction:Warning label mandates for West Coast distribution create SKU complexity and deter smaller publishers from national retail placement.
Strategic Opportunities
- Extended producer responsibility frameworks in France and Germany:Anticipated recyclability disclosure mandates create first-mover advantage for manufacturers with circular packaging capabilities.
- Adult-oriented jigsaw puzzle segment expansion:Fine-art licensing partnerships and elevated piece counts command sustained premium pricing in direct-to-consumer channels.
- ASTM F963 compliance as competitive moat:Small-part testing rigor for children's segments can differentiate mass-market entrants against low-cost imports lacking certification infrastructure.
Industry Challenges
- Precision die-cutting technician scarcity:Specialized tooling expertise for tight-tolerance cardboard and fiberboard work is aging out of the workforce faster than apprenticeship programs replenish capacity.
- Food-safe ink certification timelines:Offset lithography reformulation for saliva-resistant, migration-tested coatings extends new product development cycles by 4-8 months.
- Legacy ERP integration with traceability systems:Batch-level material tracking for REACH documentation conflicts with decades-old inventory management platforms at mid-sized publishers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Board Games and Puzzles Market |
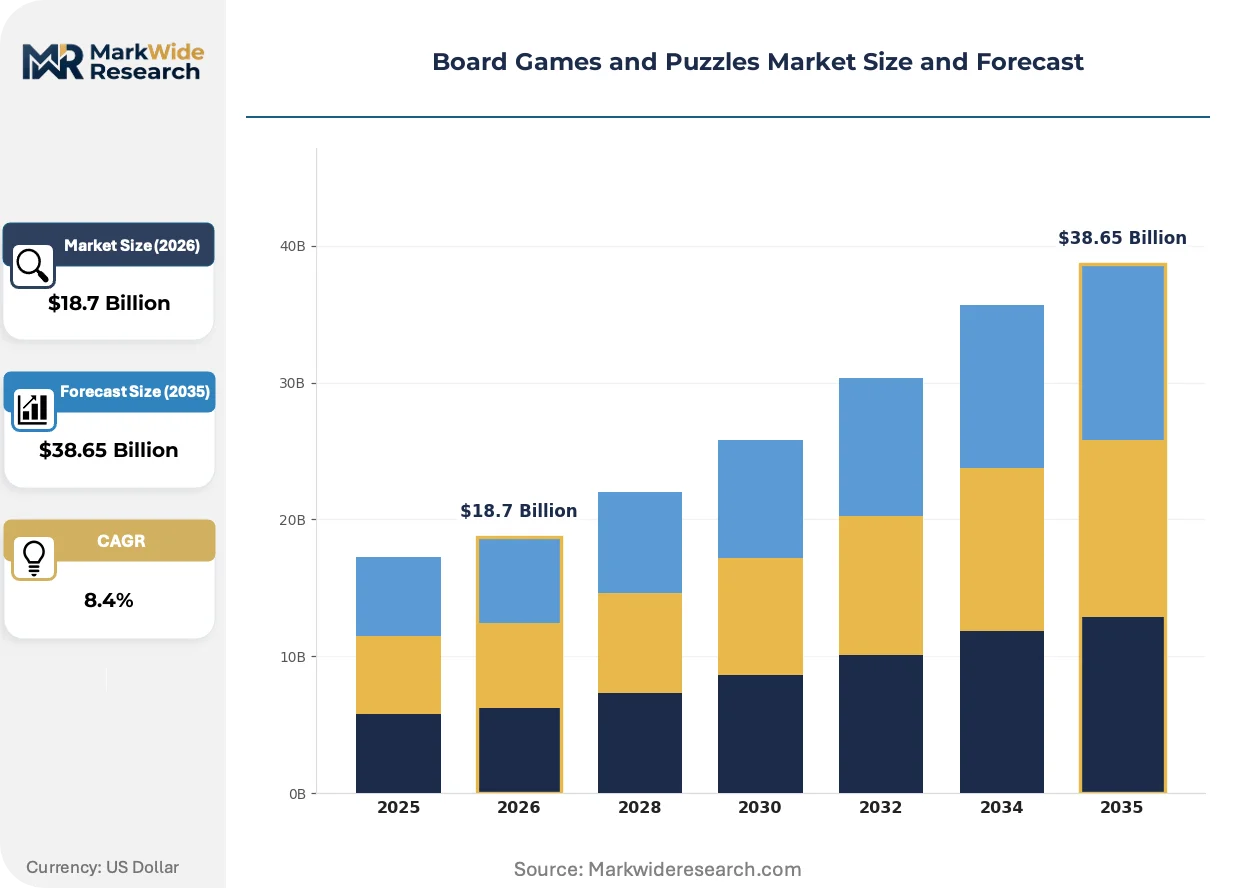
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board Games, Jigsaw Puzzles, Card Games, Strategy Games Component: Player Tokens, Dice, Cards, Game Boards Target Age Group: Children, Teens, Adults, Families Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Toy Stores |
| Companies Covered | Hasbro Inc., Mattel Inc., Asmodee Group, Ravensburger AG, Spin Master Corp., Buffalo Games, Ceaco Inc., Schmidt Spiele, Clementoni Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Board Games and Puzzles Market Strategic Shifts
Digital-physical hybrid formats and sustainable material substitutions are restructuring how publishers design, manufacture, and distribute tabletop entertainment systems across price tiers and age segments.
Laser-cut wooden components manufactured from FSC-certified birch plywood are supplanting traditional die-cut fiberboard in premium puzzle lines. Adult collectors and gift purchasers are absorbing 40-60% price premiums for heirloom-grade durability. This material shift is compressing volume throughput at conventional cardboard converters while elevating artisan workshop capacity.
REACH Annex XVII substance restrictions on heavy metals and persistent organic pollutants are tightening specifications for printed game board coatings and adhesive binders. German and French manufacturers are accelerating water-based lacquer adoption ahead of enforcement deadlines. Children's product segments face the steepest compliance cost escalation, prompting portfolio rationalization toward adult SKUs.
Direct-to-consumer subscription boxes and crowdfunding pre-order models are displacing traditional wholesale-retail placement for hobby-game launches. Dedicated tabletop enthusiasts are consolidating purchase decisions around community-validated titles before mass merchant adoption. This channel migration is most pronounced in English-language markets with established board game media ecosystems.
Board Games and Puzzles Market Segmentation
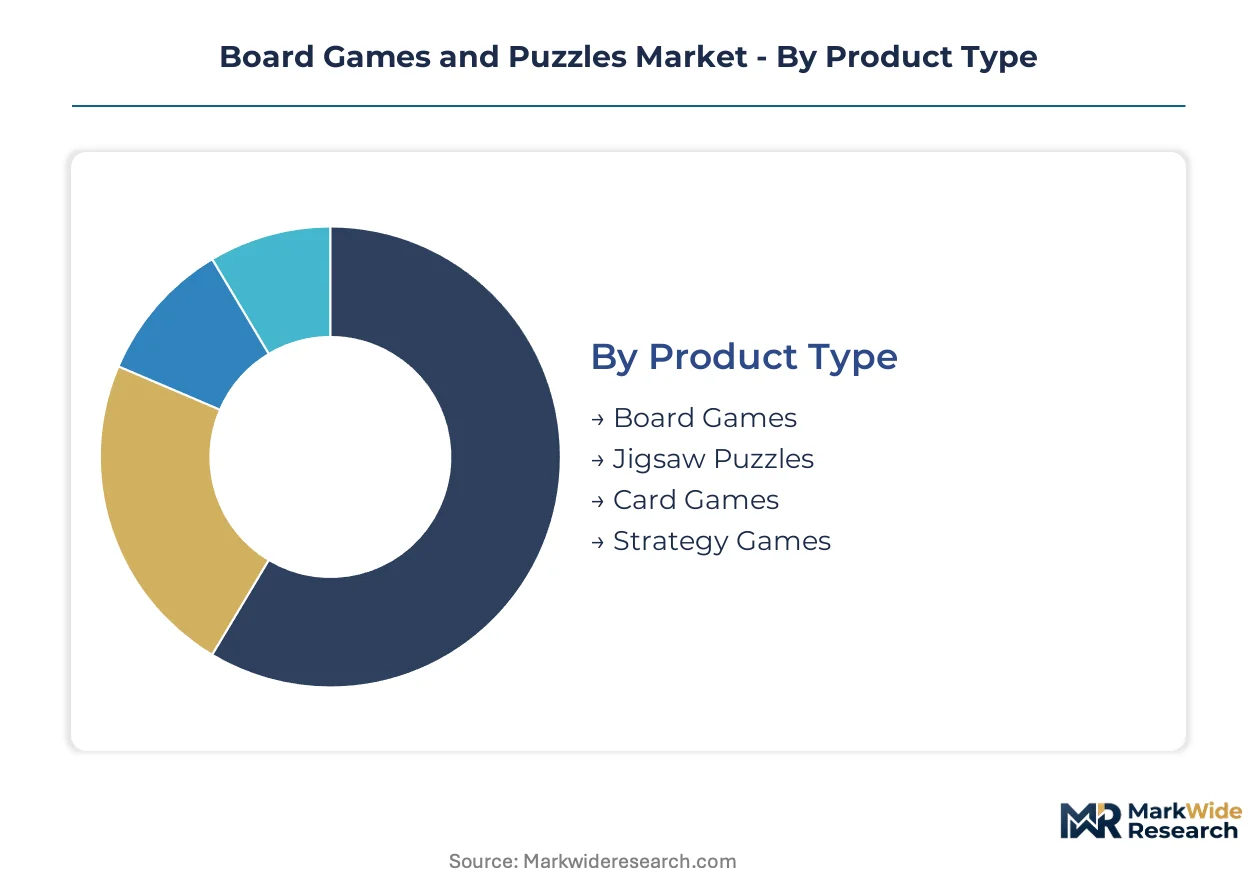
Segmentation in board games and puzzles reveals how margin pools concentrate in strategy-driven hobby formats versus mass-market family offerings. Understanding these divisions exposes where certification burdens, material costs, and channel power reshape profitability across publisher portfolios.
Product Type:
Margin pools concentrate in strategy games with recurring expansion content, while family board games and jigsaw puzzles compete on volume and licensing premiums.
- Strategy Games:Complex rule systems with modular expansion packs generate recurring revenue streams and community network effects. Hobby enthusiasts in Germany and the United States absorb premium pricing for titles with organized play ecosystems, though lengthy development cycles and small-batch manufacturing compress working capital efficiency.
- Jigsaw Puzzles:Precision die-cut fiberboard or laser-cut wooden assemblies featuring fine-art licensing command sustained price premiums in direct-to-consumer channels. Adult collectors in France and the United Kingdom drive demand for elevated piece counts and heirloom-grade durability specifications.
- Board Games:Mass-market family formats rely on holiday gifting cycles and mass merchant placement for volume throughput.
- Card Games:Portable, low-component formats suit travel and casual play with compressed manufacturing costs.
Strategy games hold installed capacity for expansion-driven revenue. Jigsaw puzzles are rotating up the share rankings through adult collector premiums.
Component:
Component selection determines compliance exposure, with printed substrates and thermoplastic tokens facing distinct regulatory pressures across European and North American markets.
- Game Boards:Printed cardstock or fiberboard substrates require REACH-compliant coatings and food-safe ink certification, extending European manufacturing timelines. German publishers absorb these costs through premium positioning, while mid-tier importers face margin compression from reformulation requirements.
- Cards:Durable cardstock with saliva-resistant finishes and migration-tested inks dominates hobby and family segments. French and Italian manufacturers lead in water-based lacquer adoption ahead of ECHA enforcement deadlines.
- Player Tokens:Thermoplastic or wooden markers vary by price tier and age-group safety thresholds.
- Dice:Standardized molded components face limited differentiation beyond custom engraving.
Game boards anchor regulatory compliance investment. Cards are climbing the fastest as publishers prioritize modular, expandable formats.
Target Age Group:
Age targeting shapes certification intensity, with children's segments demanding ASTM F963 small-part testing and REACH substance documentation that adult SKUs circumvent.
- Families:Multi-generational households concentrate purchasing power in cooperative formats bridging skill levels, particularly during fourth-quarter gifting cycles in the United States and Germany. REACH compliance costs and California Proposition 65 labeling create SKU complexity that favors larger publishers with dedicated regulatory infrastructure.
- Adults:Hobby enthusiasts and collectors sustain premium pricing for complex strategy titles and fine-art jigsaw puzzles through direct-to-consumer channels. Crowdfunding pre-order models in English-language markets validate titles before mass merchant adoption.
- Children:Strict safety testing requirements drive portfolio rationalization toward fewer, higher-volume SKUs.
- Teens:Transitional positioning between family and adult segments with hybrid gameplay preferences.
Families hold installed capacity for seasonal volume concentration. Adults are expanding most quickly through subscription and crowdfunding channel migration.
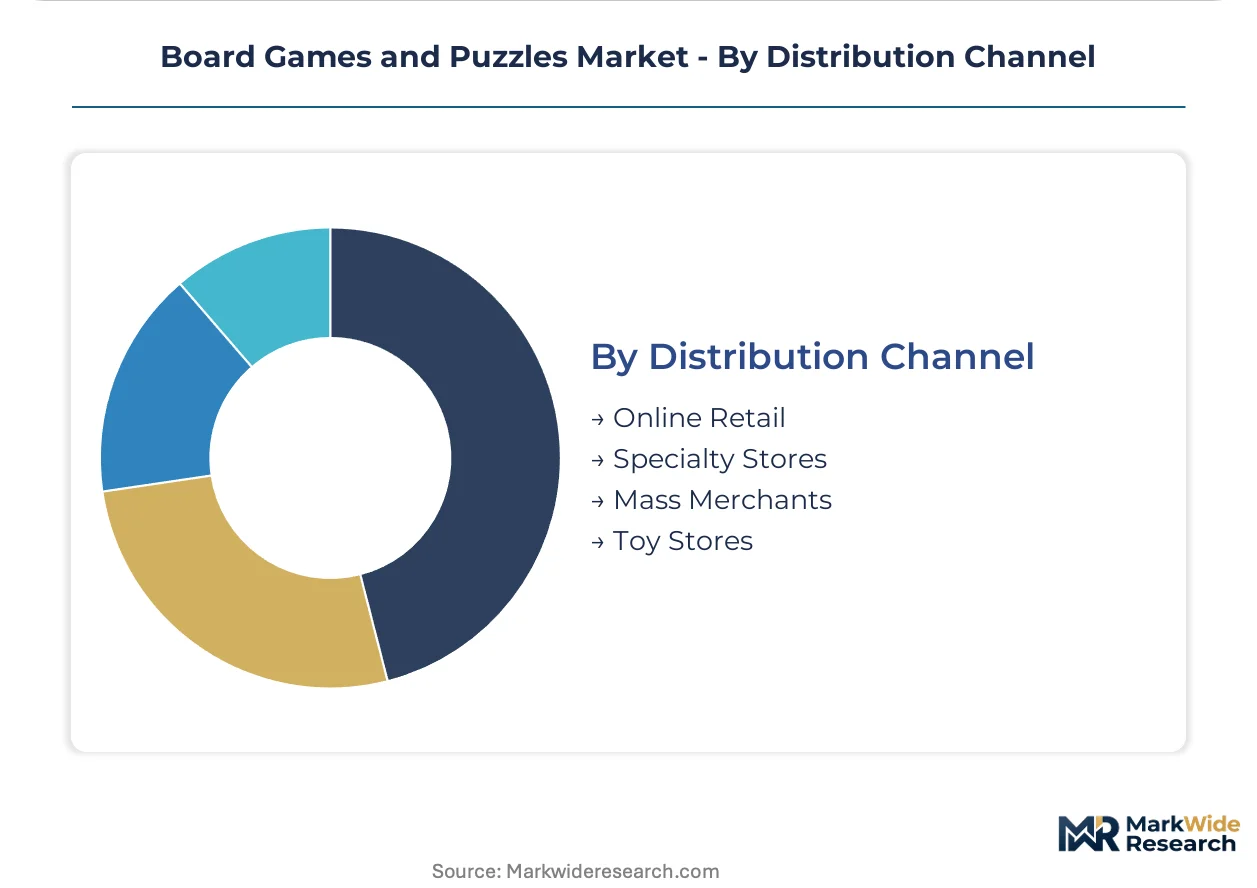
Distribution Channel:
Channel selection determines margin capture and brand positioning, with direct-to-consumer formats displacing traditional wholesale-retail placement for hobby-game launches.
- Online Retail:E-commerce platforms and publisher-direct storefronts capture full margin while enabling crowdfunding validation and subscription box models. German and United Kingdom enthusiasts consolidate purchase decisions around community-validated titles before mass adoption.
- Specialty Stores:Hobby-game retailers anchor organized play ecosystems and expansion pack sales through knowledgeable staff and tournament infrastructure. French and Belgian tabletop communities sustain independent store viability despite big-box competition.
- Mass Merchants:Big-box placement drives family-format volume but demands price compression and simplified packaging.
- Toy Stores:Seasonal gifting concentration with elevated safety certification requirements for children's SKUs.
Online retail holds installed capacity for direct margin capture. Specialty stores are rotating up the share rankings through community-driven network effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing expertise clusters in southern Germany where precision die-cutting heritage supports premium puzzle production. Ravensburg anchors this concentration with specialized tooling infrastructure. French and Italian converters supply complementary water-based coating capacity.
United States
Mass merchant channels drive seasonal volume concentration through holiday gifting cycles. The Consumer Product Safety Commission enforces ASTM F963 small-part thresholds and phthalate restrictions for children's segments. California's Proposition 65 labeling requirements create distribution friction for West Coast retail placement.
Germany
Multi-generational household spending sustains demand for cooperative gameplay formats bridging age demographics. The European Chemicals Agency administers REACH substance restrictions on adhesive formulations and surface coatings. Ravensburg hosts dense design-manufacturing clusters where fine-art licensing and precision tooling expertise concentrate.
France
Adult collectors absorb premium pricing for elevated piece counts and heirloom-grade durability specifications. Extended producer responsibility frameworks anticipate recyclability disclosure mandates for packaging reduction targets. Paris and Lyon anchor independent specialty retail networks sustaining organized play ecosystems.
United Kingdom
Direct-to-consumer subscription boxes and crowdfunding pre-order models displace traditional wholesale placement for hobby-game launches. Community-validated titles consolidate purchase decisions before mass merchant adoption. London and Manchester concentrate tabletop media ecosystems and independent publisher headquarters.
China
Injection molding supply concentration supports thermoplastic token and miniature production for global distribution. Tooling expertise in southern manufacturing zones exposes lead time risks from narrow supplier bases. Shenzhen and Dongguan clusters serve contract manufacturing relationships with European and North American publishers.
Board Games and Puzzles Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across premium and mass-market tiers. German manufacturers sustain precision-cut quality through heritage tooling infrastructure. Mass-market publishers anchor big-box retail distribution through deep channel control. Three archetypes dominate: heritage European specialists, North American mass-market anchors, and hobby-game community builders. Competitive moves concentrate on portfolio diversification toward adult collector segments and strategic partnerships for fine-art licensing.
Within the heritage specialist tier, Ravensburger AG and Schmidt Spiele exemplify precision manufacturing anchored in southern German clusters. Asmodee Group occupies a position representing community-driven hobby-game specialization across European tabletop ecosystems. Hasbro Inc. sits within the mass-market anchor archetype, leveraging scale-driven distribution infrastructure across North American retail channels.
| Leading Market Players |
|---|
| Hasbro Inc. |
| Mattel Inc. |
| Asmodee Group |
| Ravensburger AG |
| Spin Master Corp. |
| Buffalo Games |
| Ceaco Inc. |
| Schmidt Spiele |
| Clementoni Spa |
| Others |
Value Chain & Pricing Dynamics
Ninety-day die-cutting tool lead times from Ravensburg specialists concentrate pricing power among heritage German manufacturers while compressing margin pools for mid-tier publishers dependent on Asian substrate converters. REACH compliance costs and California Proposition 65 labeling create tiered cost structures that stratify competitive positioning across premium heirloom-grade and mass-market disposable segments.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European distribution channels, separating FSC-certified laser-cut birch assemblies from conventional fiberboard puzzles through certification-grade differentiation. Premium-mid-economy pricing differentiation reflects durability specifications and fine-art licensing premiums absorbed by adult collectors. Cost compression in mid-tier cardboard formats is intensifying because pulp input volatility and freight surcharges squeeze converters without vertical integration into substrate sourcing. Mass-market family segments exhibit highest price sensitivity during off-peak purchasing cycles, while hobby enthusiasts demonstrate inelastic demand for expansion-driven strategy titles.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes expose lead time risks for thermoplastic token production concentrated in Shenzhen and Dongguan manufacturing clusters. Engineered wood fiberboard supply draws from German and French converters with water-based coating adoption, while precision die-cutting tooling rests on southern German heritage infrastructure. Single-source vulnerability concentrates in East Asian injection molding for miniatures and player markers. Distribution runs through direct-to-consumer crowdfunding validation before mass merchant adoption in English-language markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across cooperative gameplay formats, adult collector segments, and subscription channel migration creates white-space opportunities for specialized entrants against consolidated mass-market anchors. Multi-generational household entertainment spending shifts are fragmenting demand into niche community-validated titles.
For Market Incumbents: Shield premium positioning through captive control over Ravensburg-area precision tooling infrastructure and accelerated water-based lacquer certification ahead of ECHA enforcement deadlines. Defend against crowdfunding-displaced hobby-game entrants by anchoring organized play ecosystems through specialty retail partnerships. Vertical integration into FSC-certified birch plywood sourcing secures heirloom-grade material pipelines.
For New Entrants and Emerging Players: ASTM F963 small-part testing fast-tracks entry into mass-market children's segments where certification infrastructure deters low-cost imports. White-space concentrates in adult-oriented jigsaw puzzles with elevated piece counts and fine-art licensing partnerships underserved by heritage German publishers. Direct-to-consumer subscription validation offers lowest-friction go-to-market path before mass merchant negotiation.
For Investors and Strategic Acquirers: Long-term, this sits as a community-anchored recurring-revenue play because expansion-driven strategy titles generate network effects and subscription retention unmatched by single-purchase family formats. Acquisition targets include mid-tier publishers with REACH-compliant coating capabilities and established crowdfunding validation track records. Signal to monitor: migration rate of hobby-game launches from Kickstarter validation to mass merchant adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Crowdfunding validation captures full margin before mass merchant price compression. |
| FSC-Certified Material Transition | Heirloom-grade birch plywood commands 40-60% price premiums from adult collectors. |
| REACH-Compliant Coating Investment | Water-based lacquer adoption ahead of ECHA deadlines secures European market access. |
| Specialty Retail Partnership Network | Organized play ecosystems anchor expansion pack sales and community retention. |
| Fine-Art Licensing Agreement | Elevated piece-count puzzles sustain premium pricing in direct-to-consumer channels. |
Study Parameters
The analysis maps strategy games, jigsaw puzzles, card games, and family board games, each validated through product development leads at heritage German manufacturers, specialty retail buyers in France and Belgium, and crowdfunding platform operators. Primary interviews with die-cutting tooling specialists, REACH compliance consultants, and pulp procurement managers combined with secondary validation from customs records, ECHA substance restriction databases, and tabletop media audience metrics. Bottom-up SKU-level volume aggregation and top-down macroeconomic adjustment ensured triangulation consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, component material, target age group, and distribution channel complexity. CAGRs derived from historical trajectory analysis and regulatory impact assessment incorporated REACH compliance cost pass-through rates and adult collector segment expansion patterns as industry-specific forecast inputs.
Underlying assumptions cover sustained multi-generational household entertainment spending and stable ECHA enforcement timelines, with deviation risk concentrated in pulp commodity volatility and East Asian logistics disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
China Playing Cards & Board Games Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Toys and Games Market
Toys and Games
Blind Box Toys Market
Toys and Games
Kids Recreational Services Market
Toys and Games
Autonomous Robot Toys Market
Toys and Games
Global Fidget Toys Market
Toys and Games
Kids Fuse Beads Market
Toys and Games
Animation Toys Market
Toys and Games
LAMEA Action Figure Toys Market
Toys and Games
Claw Machine Market
Toys and Games
Air Hockey Table Market
Toys and Games
Glow Sticks Market
Toys and Games
Snooker Tables Market
Toys and Games
Coaster Market
Toys and Games
US Sex Toys Market