
 India Wireless Speaker Market | 2026-2036
India Wireless Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
India Wireless Speaker Market Foresight
BIS certification under the Compulsory Registration Scheme is consolidating the cost-of-entry calculus for wireless speaker manufacturers entering India. HARMAN International India Pvt. Ltd. leverages its JBL brand equity to anchor premium positioning across metro retail channels. boAt competes aggressively on price-tier accessibility while sustaining volume leadership in the budget Bluetooth segment. Xiaomi Technology India Private Limited extends its ecosystem strategy by integrating wireless speakers with its broader IoT device portfolio.
India wireless speakers are audio output devices that operate without physical cable connections, typically employing Bluetooth protocols within the 2.4 GHz ISM band or Wi-Fi standards for higher-fidelity streaming and multi-room synchronization. These devices convert amplified electrical signals into acoustic output through electrodynamic drivers ranging from compact 40 mm units to larger 100 mm plus configurations, serving consumer entertainment, commercial ambient sound, and institutional presentation applications. Portable Speakers and Bluetooth Speakers dominate unit shipments due to their alignment with India's mobile-first consumption patterns and affordable price tiers. Smart Speakers represent the fastest-expanding connectivity segment as voice-assistant integration penetrates urban households, while Premium and Luxury price tiers concentrate margin pools among audiophile consumers and enterprise hospitality deployments.
BIS mandates under the Compulsory Registration Scheme and WPC frequency allocation rules govern product compliance, with BIS testing laboratories certifying electromagnetic compatibility and safety standards before market entry. The Ministry of Electronics and Information Technology's phased manufacturing program shapes local assembly economics by adjusting duty structures on imported components versus finished goods. Stakeholders must monitor how BIS expands its notified product list and how MEITY recalibrates import duties to determine whether captive manufacturing in India or component sourcing strategies deliver sustainable cost positions.
Market Dynamics
BIS mandates under the Compulsory Registration Scheme are compressing the competitive set by raising fixed compliance costs, forcing smaller assemblers toward contract manufacturing partnerships or exit. This regulatory tightening intersects with MEITY's phased manufacturing program to reshape sourcing economics for imported versus locally assembled units.
Growth Catalysts
- Bluetooth 5.3 protocol diffusion:Lower latency and improved power efficiency are extending playback duration in portable units, matching India's mobile-first consumption patterns where smartphone pairing dominates usage.
- PLI scheme incentives:MEITY's production-linked incentives for electronics manufacturing are attracting component suppliers to set up surface-mount technology lines in Tamil Nadu and Karnataka.
- Voice-assistant integration:Urban households in Mumbai and Delhi are adopting smart speakers for home automation control, creating pull-through demand for compatible wireless audio peripherals.
Market Restraints
- Neodymium magnet supply concentration:Driver magnet supply chains cluster in Chinese processing facilities, exposing assemblers to export restriction risk and price volatility.
- BIS testing laboratory capacity:Limited accredited facilities in Delhi, Mumbai and Bengaluru are extending certification timelines to 12-16 weeks, delaying product launches.
- Wired headphone substitution persistence:Audiophile segments and gaming applications continue preferring 3.5 mm or USB-C connected headsets for latency-sensitive use cases.
Strategic Opportunities
- Tier-2 and Tier-3 city penetration:Retail density remains thin in Indore, Lucknow and Coimbatore, creating whitespace for organized brands to establish exclusive distribution before local assemblers consolidate.
- Outdoor and adventure applications:IP67-rated rugged speakers for trekking and cycling communities represent an underdeveloped premium niche with attachable accessory ecosystems.
- MEITY duty structure arbitrage:Finished goods import duties exceeding component tariffs incentivize local PCB assembly and acoustic driver integration.
Industry Challenges
- Acoustic engineering talent scarcity:Driver tuning and enclosure design expertise concentrates in Bengaluru and Hyderabad, forcing brands to rely on outsourced original design manufacturers.
- BIS surveillance audit compliance:Post-certification factory inspections require maintaining traceable component documentation across multi-tier supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Wireless Speaker Market |
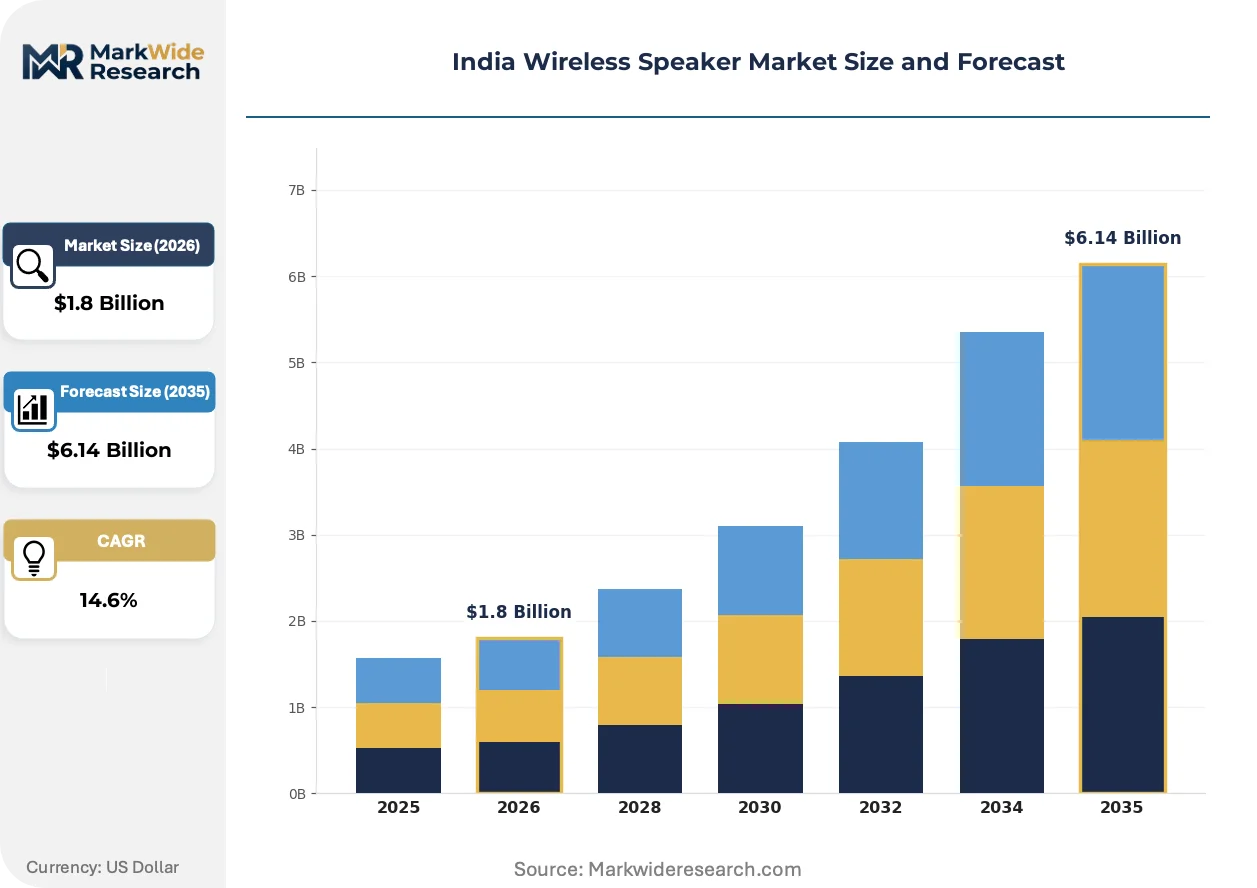
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Speakers, Smart Speakers, Soundbars, Bluetooth Speakers Connectivity: Bluetooth, Wi-Fi, NFC, AirPlay End User: Residential, Enterprises, Educational Institutions, Retailers Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Bose Corporation India Private Limited, Amazon Retail India Private Limited, HARMAN International India Pvt. Ltd. (JBL), Koninklijke Philips N.V., Xiaomi Technology India Private Limited, Sony India Private Limited, Samsung India Electronics Private Limited, Google India Private Limited, boAt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Wireless Speaker Market Shifts & Advancements
Codec and streaming protocol evolution is compressing the quality gap between wireless and wired audio reproduction. Manufacturers are racing to integrate spatial audio rendering and low-latency gaming modes before standardization freezes competitive differentiation.
LE Audio with its Auracast broadcast capability is electrifying accessibility applications and public venue deployments. Transit authorities in Delhi and Bengaluru are piloting hearing-aid-compatible broadcast systems in metro stations. This technology is compressing the installed base of legacy induction-loop assistive listening infrastructure while opening auxiliary revenue streams for speaker manufacturers through venue licensing.
BIS notification expansion under CRS Phase-VI is tightening electromagnetic compatibility testing requirements for wireless audio devices. The Bureau's revised IS 616 standards for audio equipment are forcing redesigns of power supply architectures. Premium and professional audio segments are responding fastest by pre-certifying platforms across multiple product generations.
Direct-to-consumer channel migration is fragmenting traditional electronics retail in Maharashtra and Karnataka. Urban buyers are researching specifications through short-form video platforms before purchasing through brand-owned storefronts. Metro appliance chains are responding by unbundling installation and extended warranty services to defend foot traffic against pure-play e-commerce fulfillment.
India Wireless Speaker Market Segmentation
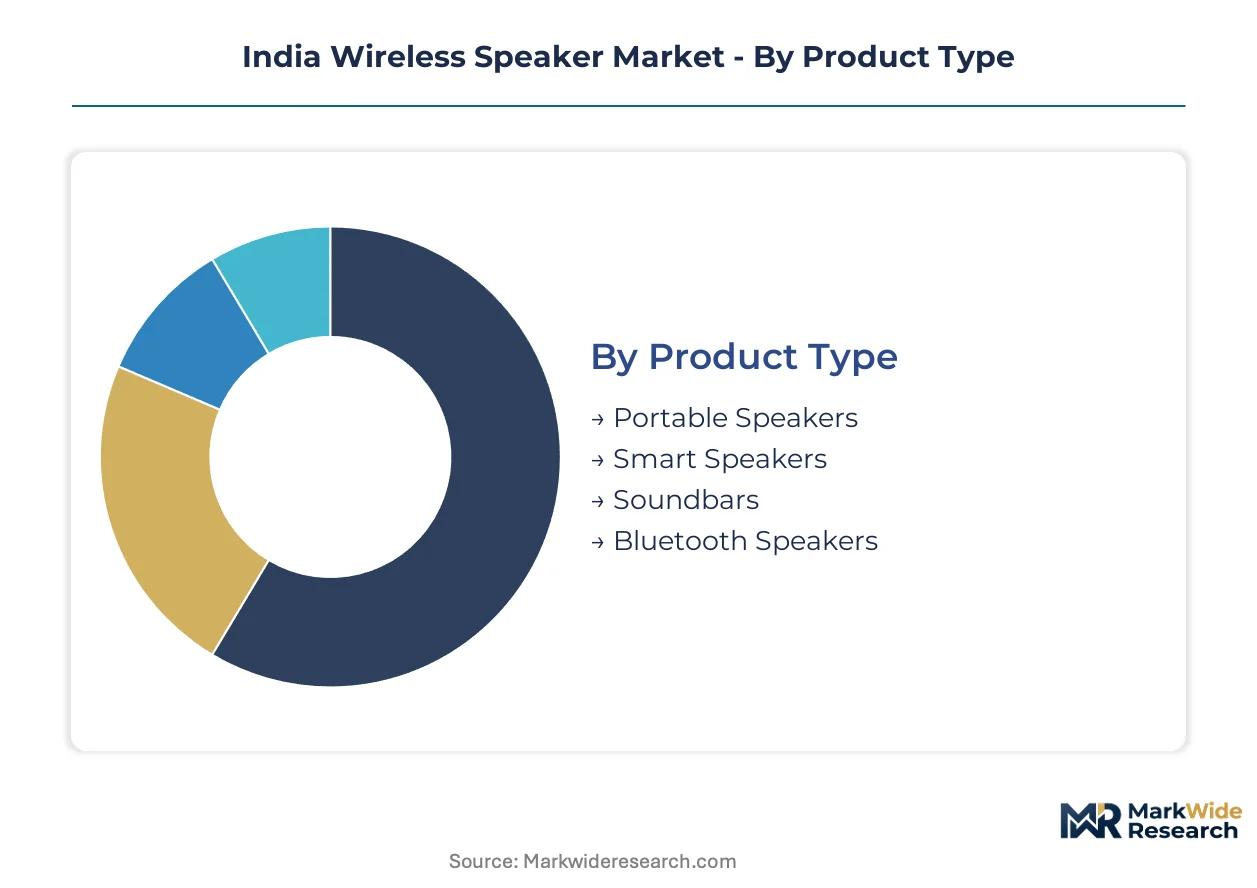
Wireless speaker segmentation in India reflects divergent integration strategies across consumer electronics ecosystems. Standalone portable units dominate mobility-driven use cases while embedded smart speakers penetrate home automation networks. Understanding these structural divides clarifies where component sourcing, certification investments, and channel economics concentrate.
Product Type:
Standalone portability versus fixed-installation integration defines how manufacturers architect driver configurations, power management, and enclosure acoustics for Indian households and commercial spaces.
- Portable Speakers:Battery-powered units with 40-100 mm electrodynamic drivers and sealed enclosures prioritize weight reduction and IP ratings for outdoor mobility. Demand clusters in Maharashtra and Karnataka where urban consumers pair smartphones with compact audio for commuting and travel use cases. Bluetooth 5.3 protocol adoption is extending playback duration to match India's mobile-first consumption patterns.
- Smart Speakers:Voice-assistant-enabled devices integrate far-field microphone arrays and Wi-Fi connectivity for home automation hub functionality. Penetration accelerates in Mumbai and Delhi NCR households where consumers control lighting, security, and climate systems through unified voice interfaces. BIS electromagnetic compatibility testing under CRS Phase-VI is compressing launch timelines for new entrants.
- Soundbars:Long-throw driver arrays with dedicated subwoofer channels deliver cinematic audio reproduction for flat-panel television installations.
- Bluetooth Speakers:Dedicated single-protocol devices emphasizing codec support and pairing stability for smartphone-centric audio consumption.
Volume placements concentrate in Portable Speakers; the faster expansion belongs to Smart Speakers.
Connectivity:
Protocol selection determines latency profiles, streaming fidelity, and ecosystem lock-in depth across Indian consumer segments.
- Bluetooth:Dominant 2.4 GHz ISM band protocol with A2DP and LE Audio codec support enables universal smartphone compatibility. boAt and Xiaomi anchor volume leadership through aggressive pricing of Bluetooth 5.0+ implementations. BIS frequency allocation compliance through WPC certification remains mandatory for all transmitters.
- Wi-Fi:Higher-bandwidth streaming enables lossless audio reproduction and multi-room synchronization across home networks. Premium positioning in Bengaluru and Hyderabad targets audiophile consumers demanding high-resolution codec support. MEITY's phased manufacturing program is reshaping local assembly economics for Wi-Fi module integration.
- NFC:Touch-pairing functionality accelerates connection establishment for hospitality and retail deployment scenarios.
- AirPlay:Apple ecosystem protocol enabling seamless streaming from iOS and macOS devices for premium residential installations.
Bluetooth captures dominant unit volumes; Wi-Fi is climbing the fastest among connectivity segments.
End User:
Application context shapes durability requirements, acoustic output specifications, and procurement decision-making authority across Indian market verticals.
- Residential:Individual and family consumption driving aesthetic design priorities and voice-assistant integration for home entertainment systems. Urban Maharashtra households in Mumbai and Pune represent the deepest penetration of multi-room audio configurations. Direct-to-consumer channel migration is fragmenting traditional electronics retail in these markets.
- Enterprises:Corporate meeting rooms, hospitality venues, and co-working spaces demand professional-grade acoustic output and centralized management platforms. Procurement concentrates through AV integrators in Bengaluru and Hyderabad where technology sector office buildouts sustain demand. IP67-rated ruggedization opens auxiliary revenue streams for outdoor venue licensing.
- Educational Institutions:Classroom and auditorium deployments prioritizing durability and simplified control interfaces for non-technical staff operation.
- Retailers:In-store ambient audio and promotional announcement systems requiring networked control and scheduled content playback.
Residential segment anchors absolute volume; Enterprise procurement is gaining share fastest through commercial real estate expansion.
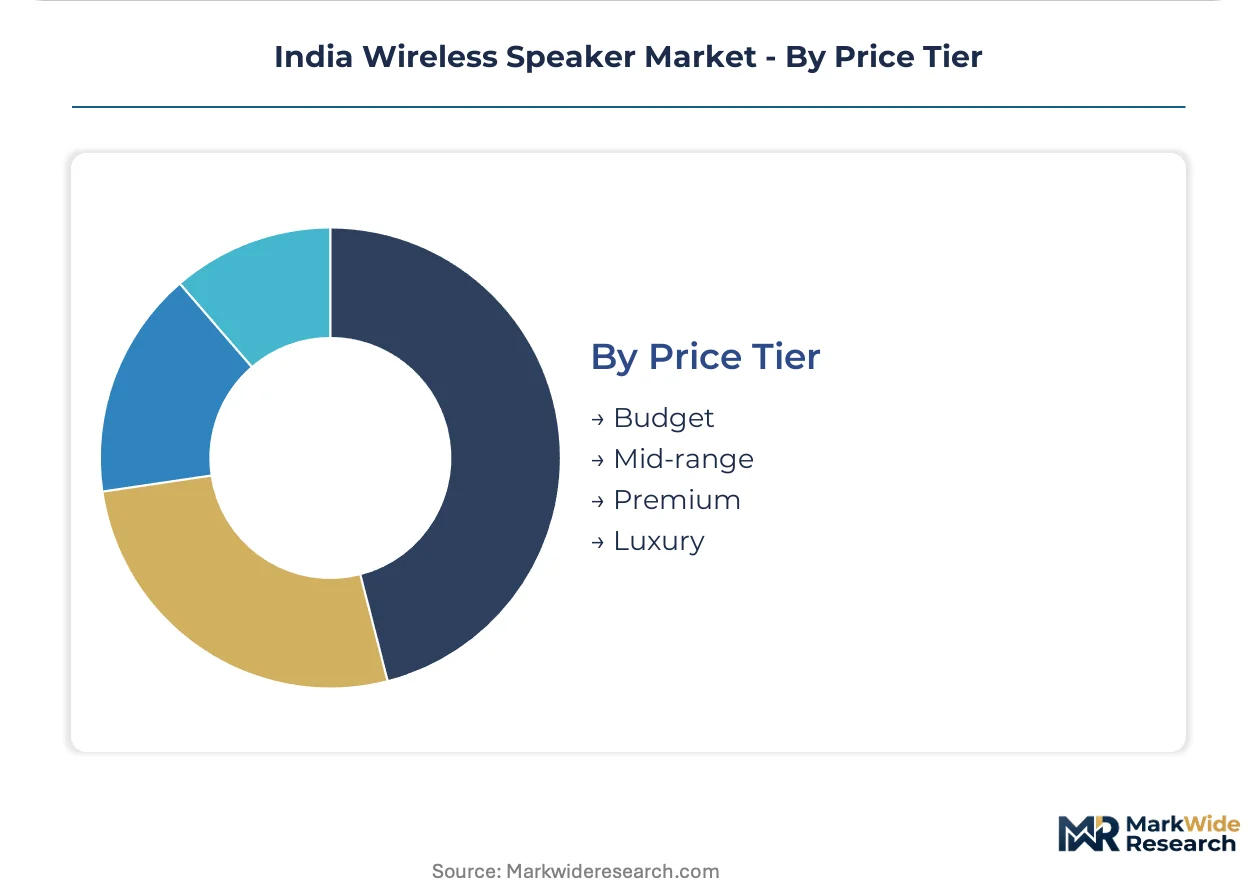
Price Tier:
Cost stratification aligns with certification grade investments, driver quality tiers, and brand equity premiums across Indian distribution channels.
- Budget:Entry-level implementations with basic Bluetooth connectivity and plastic enclosures targeting price-sensitive mass market penetration. boAt sustains volume leadership through aggressive tier-2 and tier-3 city distribution before local assemblers consolidate. BIS compliance costs represent proportionally higher burden at this price point, compressing margin structures.
- Mid-range:Enhanced driver configurations, metal enclosures, and codec diversity targeting upgrade cycles from first-time wireless audio adopters. HARMAN International's JBL brand defends this tier through retail channel presence in metro appliance chains. Extended warranty and installation services differentiate against pure-play e-commerce fulfillment.
- Premium:Audiophile-grade acoustic engineering with dedicated amplification and high-resolution streaming support for discerning consumers.
- Luxury:Design-forward statement pieces with bespoke materials and concierge service positioning for ultra-high-net-worth households and enterprise hospitality.
Budget tier dominates unit placements; Premium positioning shows steepest expansion trajectory among price segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturing clusters in Maharashtra and Karnataka concentrate wireless speaker assembly under the PLI scheme's duty arbitrage incentives. Tamil Nadu and Telangana are attracting component suppliers for surface-mount technology lines. Gujarat and Delhi-NCR complete the geographic spread with distinct logistics and retail channel advantages.
Maharashtra
Mumbai and Pune households drive premium smart speaker penetration for home automation integration. BIS certification mandates under CRS Phase-VI compress launch timelines for new entrants targeting these urban consumers. Thane and Nashik industrial corridors host contract manufacturers assembling Bluetooth units for tier-2 city distribution.
Karnataka
Bengaluru's technology workforce sustains demand for Wi-Fi-enabled multi-room audio systems with high-resolution codec support. The state's electronics manufacturing policy aligns with MEITY's phased manufacturing program to localize PCB assembly. Mysuru and Hubli-Dharwad are emerging as secondary logistics nodes for southern India fulfillment.
Tamil Nadu
Chennai's port infrastructure facilitates component import for driver magnet and enclosure assembly operations. PLI scheme incentives are attracting surface-mount technology suppliers to Sriperumbudur and Oragadam industrial belts. Coimbatore's retail density remains underpenetrated, creating whitespace for organized brand distribution expansion.
Telangana
Hyderabad's aerospace and defense electronics ecosystem supplies acoustic engineering talent for premium driver tuning. The state's electronics policy offers capital subsidies for testing laboratory accreditation to address BIS capacity bottlenecks. Medchal and Rangareddy districts are consolidating as alternative assembly locations to Karnataka.
Gujarat
Surat and Vadodara industrial zones leverage Mundra port connectivity for neodymium magnet and driver component imports. The state's special economic zone framework supports export-oriented manufacturing for Middle East and African markets. Ahmedabad's retail appliance chains anchor western India distribution for mid-range and budget tier placements.
India Wireless Speaker Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's wireless speaker market, creating a tiered structure where ecosystem players leverage cross-device integration while audio specialists defend acoustic engineering differentiation. The vendor set fragments across three strategic archetypes: multinational electronics conglomerates with portfolio breadth, domestic price-tier disruptors with distribution density, and contract manufacturers serving private-label demand. Competitive moves concentrate on local assembly partnerships to exploit MEITY duty differentials and exclusive retail channel arrangements to defend margin positions against direct-to-consumer migration.
Among multinational electronics conglomerates, HARMAN International India Pvt. Ltd. and Samsung India Electronics Private Limited occupy positions that exemplify premium-tier ecosystem integration, while Xiaomi Technology India Private Limited represents the price-accessibility archetype through ecosystem lock-in strategies. The domestic specialist tier includes boAt as an anchor for budget-tier volume leadership through tier-2 and tier-3 city penetration. These company patterns illustrate how competitive positioning stratifies across certification-grade investments, driver quality tiers, and channel economics rather than converging on uniform strategies.
| Leading Market Players |
|---|
| Bose Corporation India Private Limited |
| Amazon Retail India Private Limited |
| HARMAN International India Pvt. Ltd. (JBL) |
| Koninklijke Philips N.V. |
| Xiaomi Technology India Private Limited |
| Sony India Private Limited |
| Samsung India Electronics Private Limited |
| Google India Private Limited |
| boAt |
| Others |
Supply & Pricing Matrix
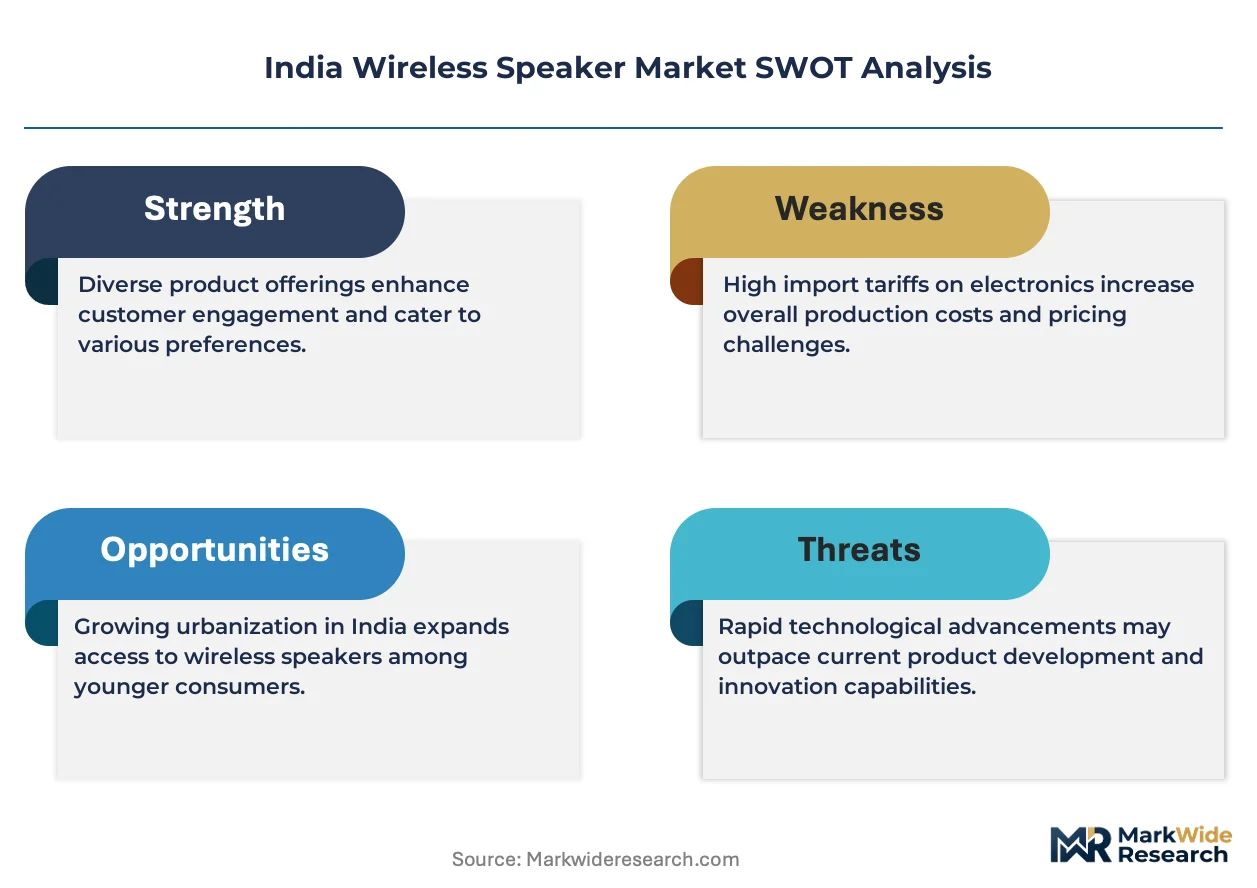
Neodymium oxide price volatility cascades through driver magnet procurement into finished speaker pricing tiers, compressing margins at the budget end while premium brands absorb cost spikes through brand equity buffers. BIS certification fees and testing laboratory queue times layer fixed costs that stratify market entry economics across compliance-grade tiers.
Pricing Analysis
Lead-time premiums reward brands with pre-certified platform inventories, while spot-market entrants face 12-16 week BIS testing delays that erode launch-window pricing power. Three-tier pricing structure across premium, standard, and economy levels separates JBL's retail-channel bundling from boAt's volume-scaled direct distribution and unbranded local assembler spot sales. Price differentiation hinges on certification grade and after-sales warranty depth. Pricing pressure stems from neodymium magnet cost pass-through and MEITY duty arbitrage squeezing import-dependent assemblers. Budget-tier buyers exhibit acute price sensitivity; premium residential segments prioritize acoustic performance and ecosystem integration over unit cost.
Supply Chain Analysis
Container freight rates from Shenzhen and Hong Kong ports determine landed cost structures for PCB assemblies and driver components entering Mundra and Chennai. Magnet supply concentrates in Chinese rare-earth processing facilities; driver diaphragm materials draw from Japanese and Taiwanese petrochemical feedstocks; enclosure plastics hinge on Saudi and UAE polymer suppliers. Single-source vulnerability in neodymium oxide refining exposes assemblers to export restriction risk. Distribution runs through Maharashtra and Karnataka electronics retail chains, with direct-to-consumer migration fragmenting traditional appliance dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS Compulsory Registration Scheme mandates function as a compliance moat, consolidating advantage among incumbents with captive testing relationships and platform pre-certification strategies.
For Market Incumbents: Anchor premium positioning through exclusive retail channel arrangements in Mumbai and Pune, defending against direct-to-consumer erosion by bundling installation and extended warranty services. Deepen backward integration into PCB assembly operations in Tamil Nadu PLI zones to exploit MEITY duty differentials versus finished goods imports. Counter emerging smart speaker ecosystem threats from Xiaomi and Google by accelerating spatial audio and low-latency gaming mode integration before codec standardization freezes differentiation. For New Entrants and Emerging Players: Capture whitespace in Coimbatore, Lucknow, and Indore retail corridors before organized brands establish exclusive distribution density. Target IP67-rated outdoor adventure speakers for trekking and cycling communities, an underdeveloped premium niche with attachable accessory ecosystem potential. Pursue contract manufacturing partnerships with established BIS-certified assemblers to bypass 12-16 week laboratory queue barriers. For Investors and Strategic Acquirers: The window for entry favors domestic price-tier disruptors with proven tier-2 and tier-3 distribution infrastructure and BIS certification track records. Long-term viability rests on PLI scheme alignment and local assembly economics resilience against component import duty fluctuations. Monitor BIS notification expansion under CRS Phase-VII as the inflection signal for compliance cost step-ups that will accelerate smaller assembler consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Local PCB Assembly Expansion | Exploits MEITY duty arbitrage between imported components and finished goods. |
| BIS Pre-Certification Investment | Compresses launch timelines against 12-16 week laboratory queue bottlenecks. |
| Tier-2 City Distribution Buildout | Captures whitespace in Indore, Lucknow, Coimbatore before competitor consolidation. |
| IP67 Outdoor Product Line Launch | Opens auxiliary revenue streams through trekking and cycling community targeting. |
| LE Audio Auracast Integration | Enables transit authority licensing opportunities in Delhi and Bengaluru metro pilots. |
Research Methodology
Multi-period observation of BIS certification queue durations, PLI scheme uptake rates, and neodymium oxide price indices anchored the trend analysis, supplemented by interviews with contract manufacturing executives, retail appliance chain category buyers, BIS testing laboratory directors, and MEITY policy implementation officers. Secondary validation drew from DGFT import duty notifications, BIS CRS Phase-VI technical standards, customs component trade records, and PLI scheme disbursement disclosures. Bottom-up assembly capacity modeling and top-down retail channel revenue triangulation converged on segment-level estimates.
Segment-weighting across product type, connectivity protocol, end-user vertical, and price tier distributions shaped volume and value projections across the analysis window. CAGRs derived from logistic diffusion curves for Bluetooth 5.3 protocol adoption and voice-assistant household penetration rates, calibrated against PLI scheme manufacturing capacity buildout trajectories and tier-2 city retail expansion velocity. Driver magnet supply constraints and BIS laboratory capacity bottlenecks fed scenario-adjusted forecast bands.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BIS notification expansion timing, rare-earth export policy shifts, and PLI scheme renewal terms. Forecasts reflect documented assumptions about protocol adoption curves and regulatory enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Wireless Audio Products Market
Audio Equipment
Gaming Earbuds Market
Audio Equipment
Speaker Driver Market
Audio Equipment
Global Wireless Audio Market
Audio Equipment
Hi-Fi Cartridges Market
Audio Equipment
Studio Headphones Market
Audio Equipment
Electronic Drums Market
Audio Equipment
Professional Audio-Visual Systems Market
Audio Equipment
Clip-On Headphones Market
Audio Equipment
India Consumer Speaker Market
Audio Equipment
Global Networked Audio Products Market
Audio Equipment
Canada Gaming Headsets Market
Audio Equipment
Motorcycle Audio Systems Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
Smart Audio System Market
Audio Equipment
Guitar Head Amplifiers Market