
 Tobacco Products Market | 2026-2036
Tobacco Products Market Size, Share, and Industry Trends Forecast 2026-2036
Tobacco Products Market Outlook
Younger adult consumers seeking reduced-risk alternatives is unwinding the traditional cigarette-heavy buyer base across mature markets. Philip Morris International leverages its IQOS heat-not-burn platform to anchor premium positioning in Japan and European cities. British American Tobacco competes through Vuse vaping products and Velo nicotine pouches, extending its portfolio beyond combustibles. Altria Group sustains Marlboro's dominance in the United States while navigating regulatory headwinds through strategic investments in oral nicotine.
Tobacco products encompass cured and processed leaf formulations engineered for combustion, heating, or oral absorption, with nicotine delivery calibrated through blending, curing, and filtration parameters. The primary commercial purpose centers on controlled alkaloid release for consumer satisfaction within regulated dosage frameworks. Cigarettes remain the mature revenue base across price tiers, though smokeless tobacco and heat-not-burn devices represent the fastest-expanding margin pools. E-commerce channels are capturing disproportionate growth in premium segments as direct-to-consumer regulations loosen in select jurisdictions.
FDA oversight through premarket tobacco product applications and the EU Tobacco Products Directive with its track-and-trace requirements reshape product standards and market access timelines. China's NMPA and SAMR enforce domestic manufacturing quotas and distribution controls that constrain foreign participation. Stakeholders must monitor evolving synthetic nicotine classifications and heat-not-burn tax parity debates as these determinations will recalibrate competitive positioning and capital allocation priorities.
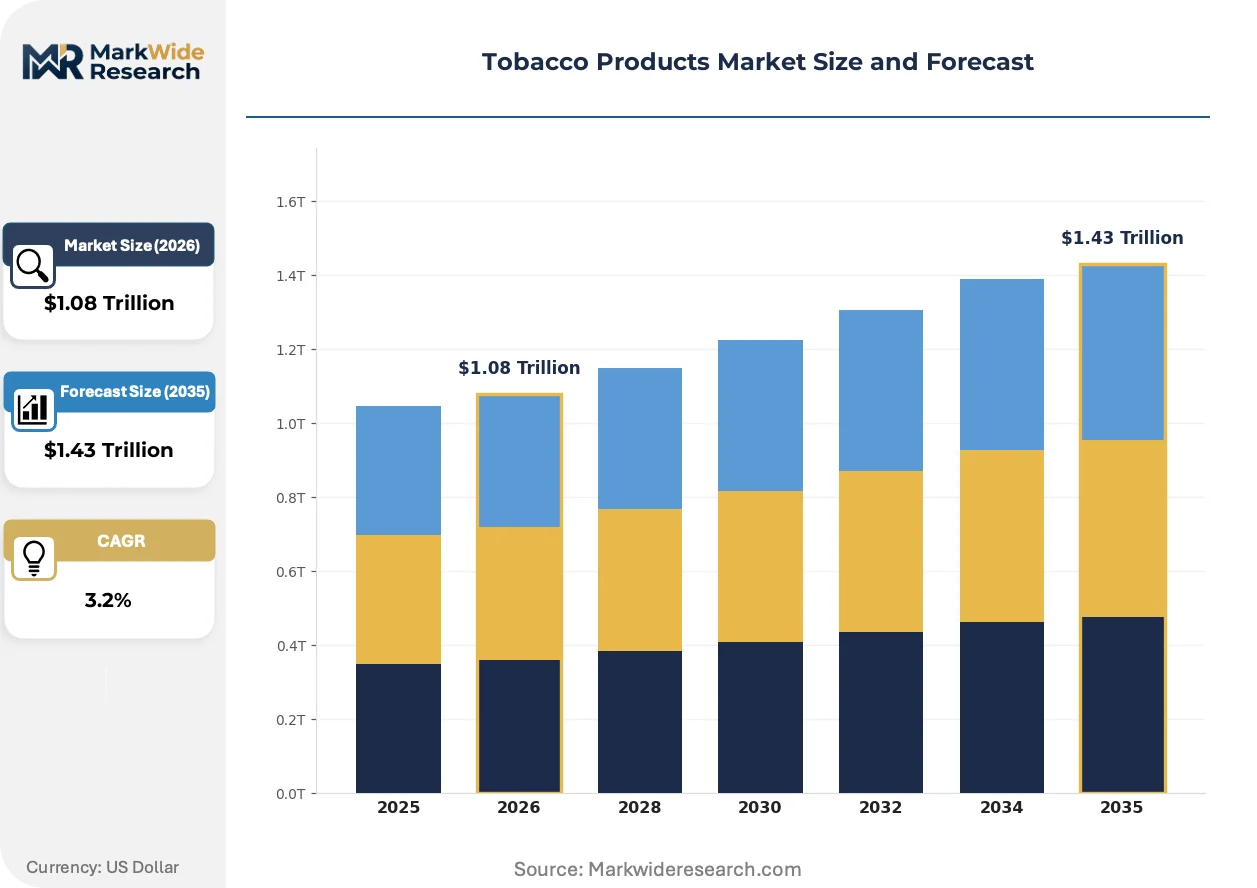
Market Dynamics
Heat-not-burn technology is fragmenting the traditional cigarette value chain as adult smokers in Japan, South Korea, and European capitals migrate toward controlled-temperature nicotine delivery systems that bypass combustion entirely.
Growth Catalysts
- EU Tobacco Products Directive enforcement:The track-and-trace mandate is accelerating legitimate channel consolidation while squeezing gray-market operators across member states.
- Oral nicotine pouch formulation advances:Synthetic nicotine stabilization patents are unlocking shelf-stable products for convenience retail penetration in Scandinavian and North American markets.
- China:State-controlled distribution quota reforms are permitting limited foreign heat-not-burn pilot programs in Hainan and selected free-trade zones.
Market Restraints
- Flue-cured tobacco leaf price volatility:Brazilian and Zimbabwean weather disruptions are compressing processor margins and forcing inventory hedging costs upward.
- FDA premarket tobacco product application backlog:Synthetic nicotine reclassification petitions are trapping novel products in 18-24 month review cycles without revenue certainty.
- Lithium-ion cell supply concentration:Heat-not-burn device manufacturers remain dependent on cylindrical battery formats from concentrated East Asian suppliers.
Strategic Opportunities
- Indonesia:The archipelago's 270 million population and limited heat-not-burn penetration present white-space expansion for next-generation product portfolios.
- Direct-to-consumer nicotine pouch subscriptions:Regulatory loosening in select US states is enabling recurring revenue models that bypass traditional wholesale markups.
- Biodegradable filter fiber convergence:Cellulose acetate replacement technologies aligned with EU Green Deal packaging mandates are opening premium positioning for sustainability-certified brands.
Industry Challenges
- Aerosol toxicology expertise scarcity:Heat-not-burn manufacturers struggle to recruit inhalation scientists capable of generating FDA-acceptable modified risk tobacco product evidence packages.
- Legacy ERP integration with serialization:EU track-and-trace compliance requires expensive middleware layers connecting decade-old manufacturing execution systems to government verification hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobacco Products Market |
| Market Size in 2026 | $1.08 Trillion |
| Market Size in 2035 | $1.43 Trillion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarettes, Cigars, Pipe Tobacco, Smokeless Tobacco End User: Adult Consumers, Retail Outlets, Online Platforms, Distributors Sales Channel: Supermarkets, Convenience Stores, Specialty Shops, E-commerce Price Tier: Premium, Mid-range, Economy, Discount |
| Companies Covered | Philip Morris International, British American Tobacco, Altria Group, Japan Tobacco International, Imperial Brands, KT&G, China National Tobacco Corporation, ITC Limited, Swedish Match, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobacco Products Market Strategic Shifts
Product chemistry and heating physics are converging to deliver nicotine satisfaction at lower combustion temperatures, while regulatory frameworks race to classify novel delivery mechanisms within existing tax and licensing architectures.
Induction heating coils paired with precision temperature algorithms are displacing resistive blade systems in premium heat-not-burn devices. Adult smokers in Tokyo and Milan are adopting these platforms for reduced odor and faster recharge cycles. The shift is compressing R&D timelines for blade-based incumbents while expanding patent litigation surface area.
REACH chemical authorization requirements for novel tobacco additives are forcing reformulation of European cigarette brands around restricted substance lists. Manufacturers are accelerating natural extract substitution programs to maintain flavor profiles. The directive's downstream impact concentrates most acutely on menthol and capsule variants previously dependent on synthetic cooling agents.
Subscription-based oral nicotine procurement is replacing convenience store impulse purchases among urban professionals in Stockholm and London. Digital-first brands are capturing lifetime value through flavor customization portals while traditional retail networks lose foot traffic. This behavioral pivot is most visible in Nordic markets where pouch category maturity preceded channel experimentation.
Tobacco Products Market Segmentation
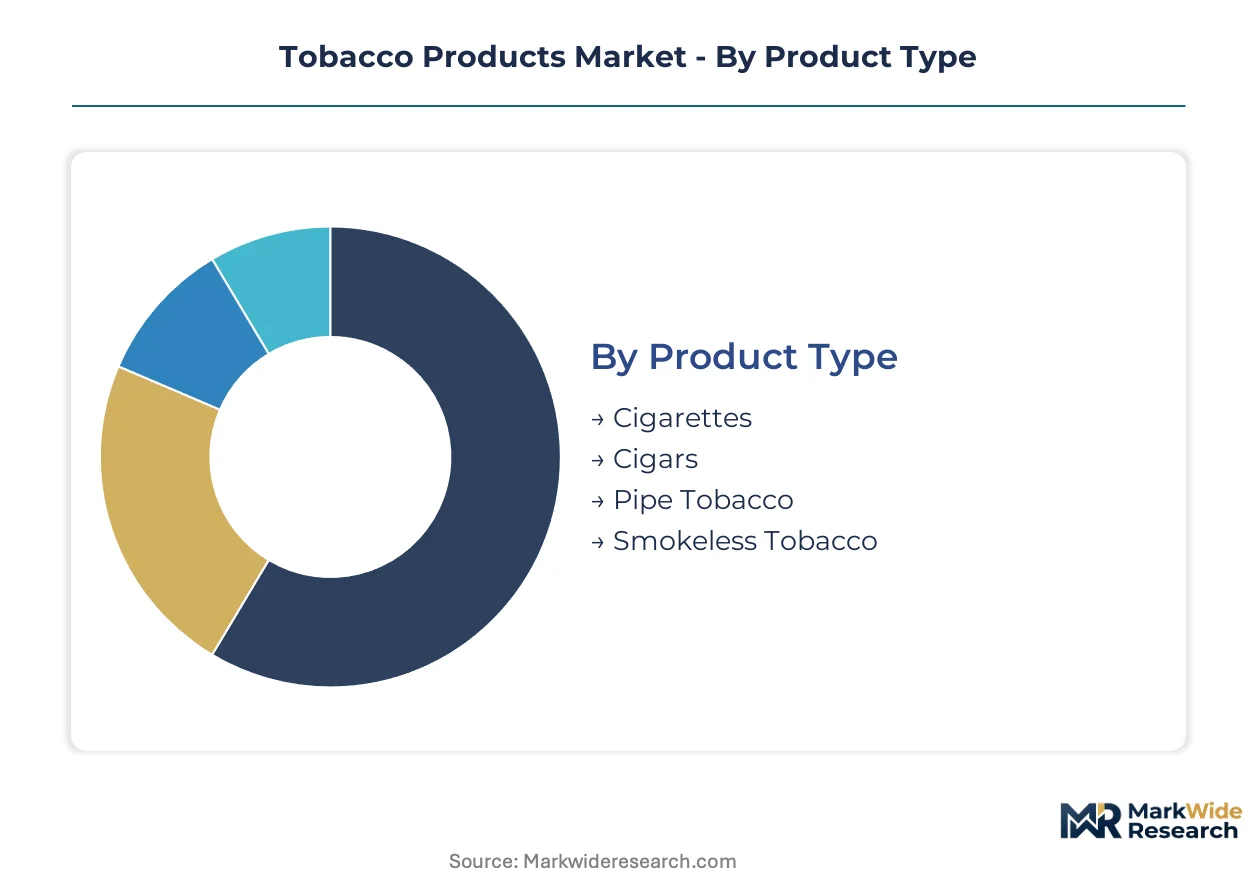
Tobacco product segmentation reveals how nicotine delivery formats, procurement channels, and price positioning fragment across regulatory environments and consumer risk preferences. Understanding these divides exposes where margin pools concentrate and which technology transitions reshape competitive boundaries.
Product Type:
Cigarettes dominate domestic consumption in China, India, and Indonesia while heat-not-burn and smokeless variants drive export-led growth in Japan, South Korea, and European markets.
- Cigarettes:Combustible paper-wrapped products delivering nicotine through tobacco leaf combustion with calibrated filtration and blending parameters. Demand concentrates in China under state-controlled distribution quotas, constrained by FDA premarket application requirements and EU Tobacco Products Directive track-and-trace mandates that extend market access timelines.
- Smokeless Tobacco:Oral and nasal formulations including snus, chewing tobacco, and modern nicotine pouches that bypass respiratory delivery entirely. Scandinavian markets anchor pouch category maturity while North American direct-to-consumer channels expand fastest amid loosening state-level regulations.
- Cigars:Hand-rolled and machine-made wrapped tobacco products positioned for ceremonial and occasional use occasions. Premium segments in Germany and Switzerland sustain artisan manufacturing.
- Pipe Tobacco:Loose-leaf or pressed blends for combustion in dedicated apparatus, retaining niche hobbyist demand in United Kingdom and Netherlands specialty retail.
Cigarettes hold the largest share; momentum sits with smokeless tobacco.
End User:
Procurement patterns split between direct adult consumer purchases and intermediated flows through retail networks, with digital platforms capturing disproportionate growth in premium segments.
- Adult Consumers:Individual purchasers of legal smoking age selecting products based on nicotine satisfaction, ritual habit, and perceived risk reduction. Japanese and Italian urban professionals are migrating toward heat-not-burn devices as primary consumption platforms.
- Online Platforms:Digital marketplaces and direct-to-consumer portals capturing subscription-based nicotine pouch growth in Stockholm and London while bypassing traditional wholesale markups.
- Retail Outlets:Physical points of sale including convenience stores and supermarkets where impulse purchases and brand loyalty drive volume.
- Distributors:Wholesale intermediaries managing state-controlled allocation systems in China and consolidated channel networks across EU member states.
Retail outlets hold the largest share; online platforms are climbing the fastest.
Sales Channel:
Channel economics diverge between high-frequency convenience transactions and lower-velocity premium experiences, with regulatory enforcement reshaping legitimate versus gray-market flows.
- Convenience Stores:High-traffic neighborhood outlets capturing impulse cigarette purchases and smokeless tobacco replenishment. EU track-and-trace mandates are squeezing independent operators while accelerating consolidation toward compliant chains.
- E-commerce:Digital channels enabling flavor customization and subscription procurement for oral nicotine products. Regulatory loosening in select US states permits recurring revenue models that bypass wholesale layers.
- Supermarkets:Mass retail formats with standardized pricing and prominent brand placement driving volume across economy and mid-range tiers.
- Specialty Shops:Curated retail environments for premium cigars, pipe tobacco, and heat-not-burn device demonstration in Tokyo and Milan.
Convenience stores hold the largest share; e-commerce is gaining share fastest.
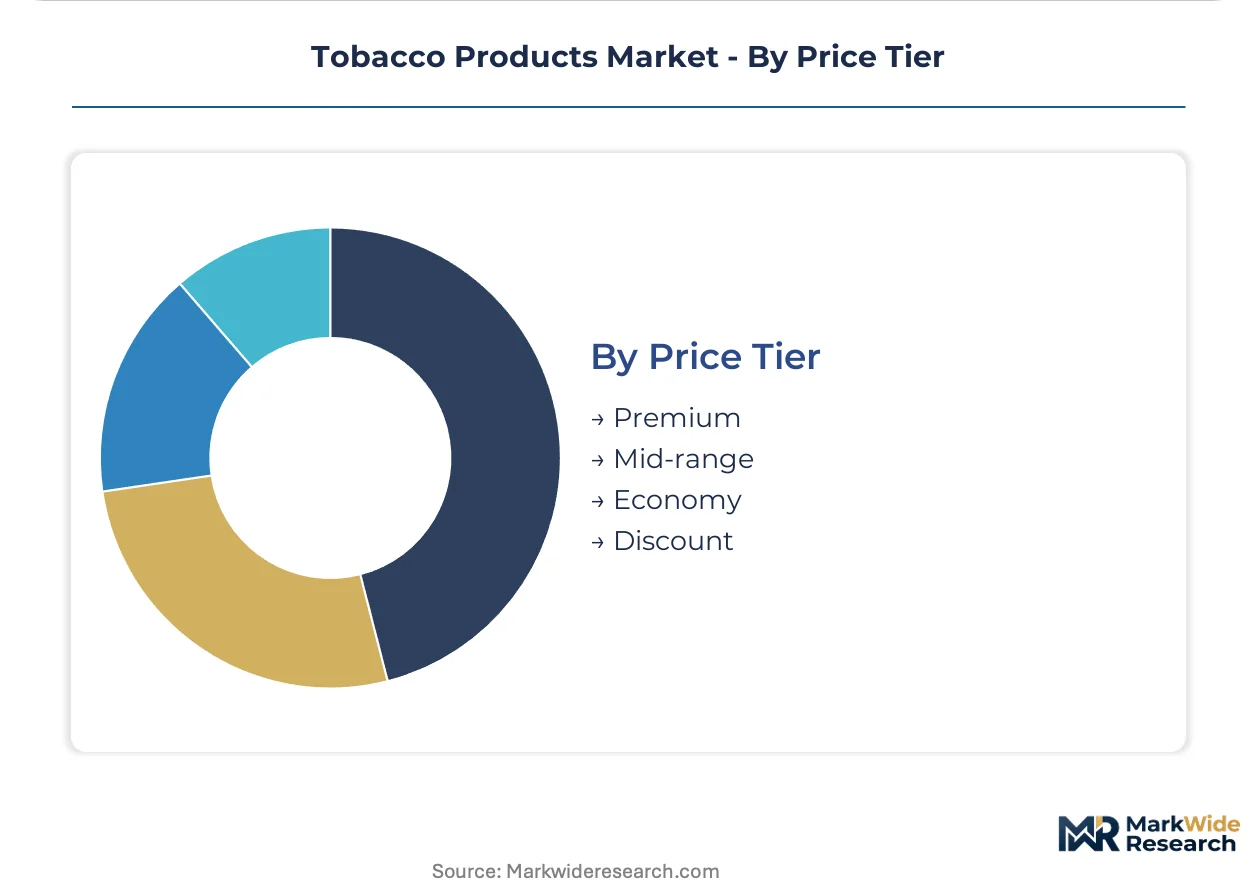
Price Tier:
Margin structures stratify across certification grades and volume scales, with sustainability credentials and reduced-risk positioning commanding premium extraction.
- Premium:Positioning built on heat-not-burn technology, biodegradable filters, and modified-risk claims supported by toxicology evidence packages. IQOS and similar platforms extract margin in Japan and European capitals through device-plus-consumable economics.
- Economy:Value-oriented combustible products serving price-sensitive demand in emerging markets with high youth affordability sensitivity. Brazilian and Zimbabwean leaf price volatility compresses processor margins at this tier.
- Mid-range:Standard brand portfolios balancing quality perception with accessibility, including Marlboro and Camel variants across conventional and reduced-risk extensions.
- Discount:Deep-value brands and private labels capturing residual demand in markets with significant tax-driven price escalation.
Premium holds the largest share; economy faces steepest margin pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Port container terminals and Yangtze River Delta logistics corridors underpin China's dominance in tobacco product distribution and manufacturing scale. State-controlled rail networks and bonded warehouse zones in Hainan Province enable controlled pilot programs for next-generation product imports. This infrastructure architecture shapes competitive access across Asia-Pacific markets.
China
Domestic cigarette consumption concentrates under state-controlled distribution quotas managed by SAMR and NMPA. Heat-not-burn pilot programs in Hainan free-trade zones test limited foreign market access. Manufacturing clusters in Yunnan Province supply flue-cured leaf to domestic processors while Shenzhen electronics fabricators produce device components for regional export.
United States
Marlboro brand loyalty and oral nicotine pouch adoption drive procurement patterns across convenience retail networks. FDA premarket tobacco product application requirements trap novel synthetic nicotine formulations in extended review cycles. North Carolina leaf processing facilities and Richmond, Virginia headquarters operations anchor domestic manufacturing concentration.
Japan
Heat-not-burn device penetration among urban professionals in Tokyo and Osaka exceeds mature market benchmarks. METI standards for reduced-risk product classification accelerate toxicology evidence requirements. Nagoya industrial corridors host precision heating component fabrication for premium device assembly.
Germany
EU Tobacco Products Directive track-and-trace mandates compress gray-market flows through legitimate wholesale consolidation. REACH chemical authorization requirements force menthol and capsule variant reformulation around restricted substance lists. Hamburg port logistics and Bavarian specialty retail clusters sustain premium cigar and pipe tobacco distribution.
Indonesia
Kretek cigarette manufacturing dominates domestic consumption with limited heat-not-burn penetration creating white-space expansion potential. Ministry of Health regulations on advertising and packaging evolve alongside excise tax adjustments. Java-based processing facilities and Jakarta distribution hubs manage archipelago-wide supply reaching 270 million consumers.
Tobacco Products Market Competitive Environment
Listed leaders compete with private specialists across portfolio diversification and geographic coverage dimensions. The vendor base concentrates around five multinational entities controlling heat-not-burn patents, oral nicotine formulations, and combustible brand portfolios. Strategic archetypes include integrated leaf-to-device operators, pure-play reduced-risk technology licensors, and state-backed domestic monopolists. Dominant competitive moves center on synthetic nicotine patent litigation and heat-not-burn device ecosystem lock-in through consumable subscription models.
Within the integrated multinational tier, Philip Morris International and British American Tobacco exemplify archetypes spanning combustible legacy positions and reduced-risk platform investments. Altria Group occupies a position anchoring domestic United States market presence through brand equity concentration. These entities represent contrasting strategic postures: one emphasizing international heat-not-burn penetration, the other navigating domestic regulatory headwinds through oral nicotine diversification.
| Leading Market Players |
|---|
| Philip Morris International |
| British American Tobacco |
| Altria Group |
| Japan Tobacco International |
| Imperial Brands |
| KT&G |
| China National Tobacco Corporation |
| ITC Limited |
| Swedish Match |
| Others |
Value Chain & Pricing Dynamics
Synthetic nicotine stabilization patents replacing conventional tobacco-derived alkaloid sourcing are simultaneously shifting procurement geography toward pharmaceutical-grade chemical manufacturers and compressing margin structures across mid-tier combustible brands. This substitution dynamic redistributes value capture from leaf processors to formulation specialists while forcing legacy operators to defend pricing power through device ecosystem lock-in.
Pricing Analysis
Volume-discount tiering structures dominate heat-not-burn consumables, with subscription-based procurement commanding 15-20% unit economics improvement over single-stick convenience retail. Pricing stratifies across premium, standard, and economy tiers where modified-risk certification status and biodegradable filter credentials extract measurable brand premiums. Cost compression in economy combustibles is intensifying because Brazilian and Zimbabwean flue-cured leaf volatility forces inventory hedging premiums onto processors. Price-sensitive demand concentrates in emerging market adult smokers under thirty, while Japanese and Italian urban professionals exhibit lowest sensitivity to device-plus-consumable bundled pricing.
Supply Chain Analysis
Port congestion across Shanghai-Ningbo and Shenzhen-Yantian corridors is elevating inbound logistics costs for precision heating components and lithium-ion cylindrical cells destined for device assembly facilities. Manufacturing concentration centers on China for electronics fabrication, Indonesia for kretek cigarette production, and Brazil for flue-cured leaf supply. Raw material dependencies include East Asian battery cell supply, Zimbabwean and Brazilian tobacco leaf, and pharmaceutical-grade synthetic nicotine precursors. Single-source vulnerability in cylindrical lithium-ion formats from concentrated East Asian suppliers presents structural risk. Distribution runs through state-controlled quota systems in China, consolidated wholesale networks across EU member states, and direct-to-consumer digital channels in select North American jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tobacco products trace a cyclical recovery pattern anchored to regulatory clarity timelines, with FDA premarket application resolution velocity serving as the primary cyclical driver determining capital redeployment confidence.
For Market Incumbents: Fortify heat-not-burn patent portfolios through aggressive litigation expenditure while accelerating toxicology evidence generation for modified-risk classification submissions. Synthetic nicotine reclassification uncertainty and emerging direct-to-consumer pouch competitors threaten combustible revenue bases. Backward integration into precision heating component fabrication secures supply continuity against East Asian battery concentration.
For New Entrants and Emerging Players: Subscription fulfillment infrastructure gaps where incumbents under-serve present immediate white-space opportunity. Indonesia's 270 million population with minimal heat-not-burn penetration offers the most penetrable geography for next-generation product introduction. Direct-to-consumer digital acquisition with flavor customization portals bypasses wholesale margin extraction entirely.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed oral nicotine specialists possessing FDA submission experience but lacking global distribution scale. Long-term viability across the next decade hinges on successful modified-risk classification attainment and heat-not-burn tax parity resolution. Watch FDA synthetic nicotine reclassification petitions as the critical inflection signal determining capital allocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Risk Tobacco Product Submission | FDA MRTP authorization unlocks premium pricing and marketing claims for heat-not-burn platforms. |
| Direct-to-Consumer Channel Launch | Subscription models bypass wholesale markups and capture lifetime value through flavor customization. |
| Synthetic Nicotine Patent Acquisition | Stabilization chemistry IP controls shelf-stable oral nicotine formulation economics. |
| Precision Heating Component Backward Integration | Captive supply of induction coils reduces dependency on East Asian cylindrical battery suppliers. |
| Biodegradable Filter Certification Program | EU Green Deal alignment opens premium positioning through sustainability credential differentiation. |
Study Parameters
A standing panel of heat-not-burn product managers, FDA regulatory affairs specialists, convenience store category buyers, and tobacco leaf procurement directors provided ongoing calibration throughout the study period. Primary interview intelligence combined with secondary validation against FDA premarket tobacco product application databases, EU Tobacco Products Directive track-and-trace compliance filings, and customs trade flow records. Bottom-up demand modeling triangulated against top-down macroeconomic consumption indicators.
Consistency checks validated volume and value outputs against external benchmarks including state-controlled distribution quota disclosures and device shipment disclosures from precision heating component suppliers. Segmentation dimensions spanned product type, price tier, sales channel, and regional regulatory cluster across the projection horizon. CAGRs derived from trend extrapolation of historical consumption patterns adjusted for technology substitution elasticity and regulatory access timeline probabilities. Forecast inputs incorporated FDA review cycle duration assumptions and EU REACH chemical authorization progression schedules.
Underlying assumptions cover stable regulatory classification frameworks for synthetic nicotine and heat-not-burn devices, with deviation risk concentrated in FDA reclassification petitions and EU tax parity determinations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Cigarette Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
E-Cigarette and Vaping Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Menthol Cigarette Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
West Africa Cigarettes Market