
 Cigar Tubes Market | 2026-2036
Cigar Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Cigar Tubes Market Outlook
Aftermarket customization and limited-edition packaging revenue is reconfiguring profit pools away from commodity tube supply. Phoenix Glass LLC leverages its artisanal glassblowing heritage to dominate premium collectible segments. Scandinavian Tobacco Group anchors European distribution through controlled retail networks. New Song Yi Aluminium Can Manufactory Co. Ltd. competes on metal-forming scale for mid-market volume contracts.
Cigar tubes are rigid cylindrical containers engineered to protect hand-rolled cigars from mechanical damage and humidity fluctuation, typically fabricated from borosilicate glass, anodized aluminum, or food-grade polymers with internal diameters ranging from 18 mm to 22 mm and lengths accommodating 38 mm to 150 mm formats. Metal tube demand leads volume due to aluminum's lightweight durability and cost-efficient deep-draw manufacturing, while glass segments command premium positioning through cork-closure artisanal designs. Closure type selection directly shapes margin architecture, with screw-cap aluminum tubes serving mass retail and cork-sealed glass variants capturing boutique channel markups.
FDA Center for Tobacco Products oversight and EU REACH chemical compliance frameworks govern material contact safety and traceability requirements for cigar tube substrates and finishes. ISO 9001 quality management certification shapes supplier qualification protocols for major tobacco distributors. Stakeholders must monitor evolving extended producer responsibility mandates and biodegradable material thresholds as regulatory pressure intensifies on single-use packaging formats.
Market Dynamics
Aluminum deep-draw manufacturing concentration in Guangdong and Zhejiang provinces is compressing unit economics for mid-market tube suppliers while premium glassblowers in Bohemia and Murano capture margin through scarcity positioning.
Growth Catalysts
- EU REACH chemical compliance frameworks:Food-grade anodized finishes meeting Substance of Very High Concern screening protocols unlock duty-free access to German and French duty-free retail channels.
- Premium cigar lounge expansion:Membership-based consumption venues in Miami, Dubai, and São Paulo drive demand for cork-sealed borosilicate presentation tubes as tableside service accessories.
- Aluminum alloy 6061-T6:Deep-draw forming advances enable 0.3mm wall thicknesses with hermetic screw-cap integration, reducing shipping weight for e-commerce fulfillment.
Market Restraints
- Raw material volatility:London Metal Exchange aluminum price swings above 15% annually destabilize contract pricing for volume buyers locked into 12-month supply agreements.
- Supply concentration risk:Borosilicate glass feedstock dependence on Schott AG and Corning Incorporated creates single-source vulnerability for artisanal tube producers.
- Substitution threat:Humidity-controlled travel humidors with integrated Boveda packs displace single-cigar tube use among frequent travelers.
Strategic Opportunities
- India cigar retail liberalization:State-level excise tax reductions in Karnataka and Maharashtra enable lounge licensing that pairs consumption with accessory sales.
- Biodegradable polymer mandates:EU Single-Use Plastics Directive enforcement creates first-mover advantage for polylactic acid tube developers meeting industrial composting standards.
- Direct-to-collector channels:NFT-authenticated limited editions sold through specialized auction platforms bypass traditional wholesale markups.
Industry Challenges
- Master glassblower scarcity:Traditional furnace craftsmanship training programs in Czech Republic and Italy graduate fewer than 40 qualified artisans annually.
- ISO 9001 certification timelines:18-month audit cycles delay supplier qualification for Scandinavian Tobacco Group and Imperial Brands distribution networks.
- Legacy ERP integration:Batch-level traceability requirements for FDA tobacco product regulations force replacement of paper-based production logs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cigar Tubes Market |
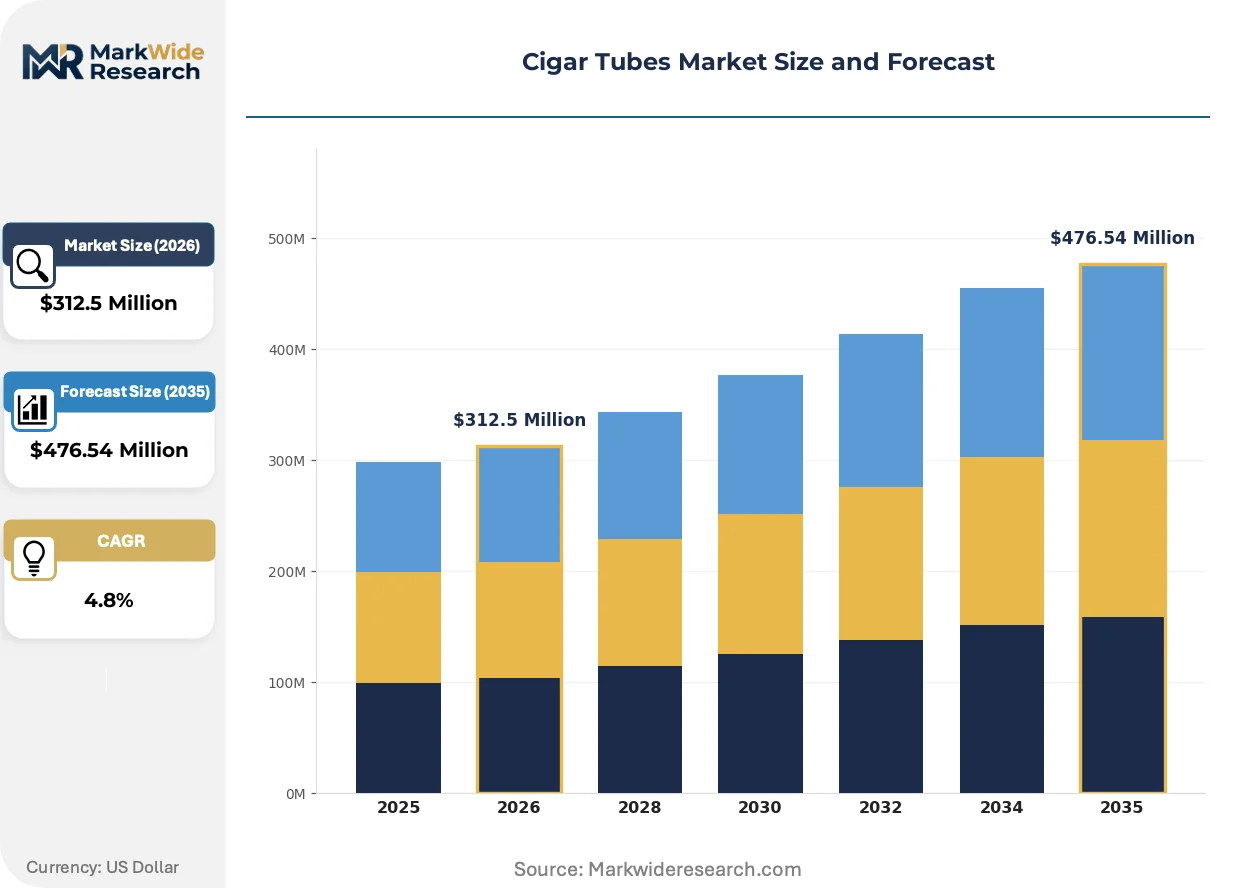
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Glass, Wood Size: Standard, King, Mini, Short Closure Type: Screw Cap, Slide Lid, Snap Fit, Cork End User: Retailers, Wholesalers, Distributors, Online Stores |
| Companies Covered | Phoenix Glass LLC, Adelphi Healthcare Packaging, New Song Yi Aluminium Can Manufactory Co. Ltd., ECMI Ltd, Montebello, Shenzhen Junen Packing Group, Imperial Brands, Scandinavian Tobacco Group, Altadis USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cigar Tubes Market Strategic Shifts
Material science convergence and regulatory stringency are fragmenting the supplier base into three capability tiers: commodity metal formers, certified polymer converters, and heritage glass ateliers.
Multi-layer vapor deposition is hybridizing aluminum tube interiors with ceramic-barrier coatings that eliminate metallic taste transfer while preserving deep-draw manufacturing economics. Boutique cigar manufacturers in Nicaragua and Honduras are specifying these hybrid tubes for limited releases. The technology is compressing the performance gap between metal utility and glass purity.
EU extended producer responsibility mandates for packaging waste are forcing substrate selection changes ahead of 2025 reporting thresholds. Metal tube producers face end-of-life collection cost allocation that favors reusable designs. German distributors are responding with deposit-return programs for premium aluminum formats.
Collector behavior now prioritizes provenance documentation over brand heritage alone. Auction platforms and verified resale marketplaces are displacing traditional tobacconist channels for rare tube acquisitions. This shift concentrates liquidity in United States and United Kingdom secondary markets.
Cigar Tubes Market Segmentation
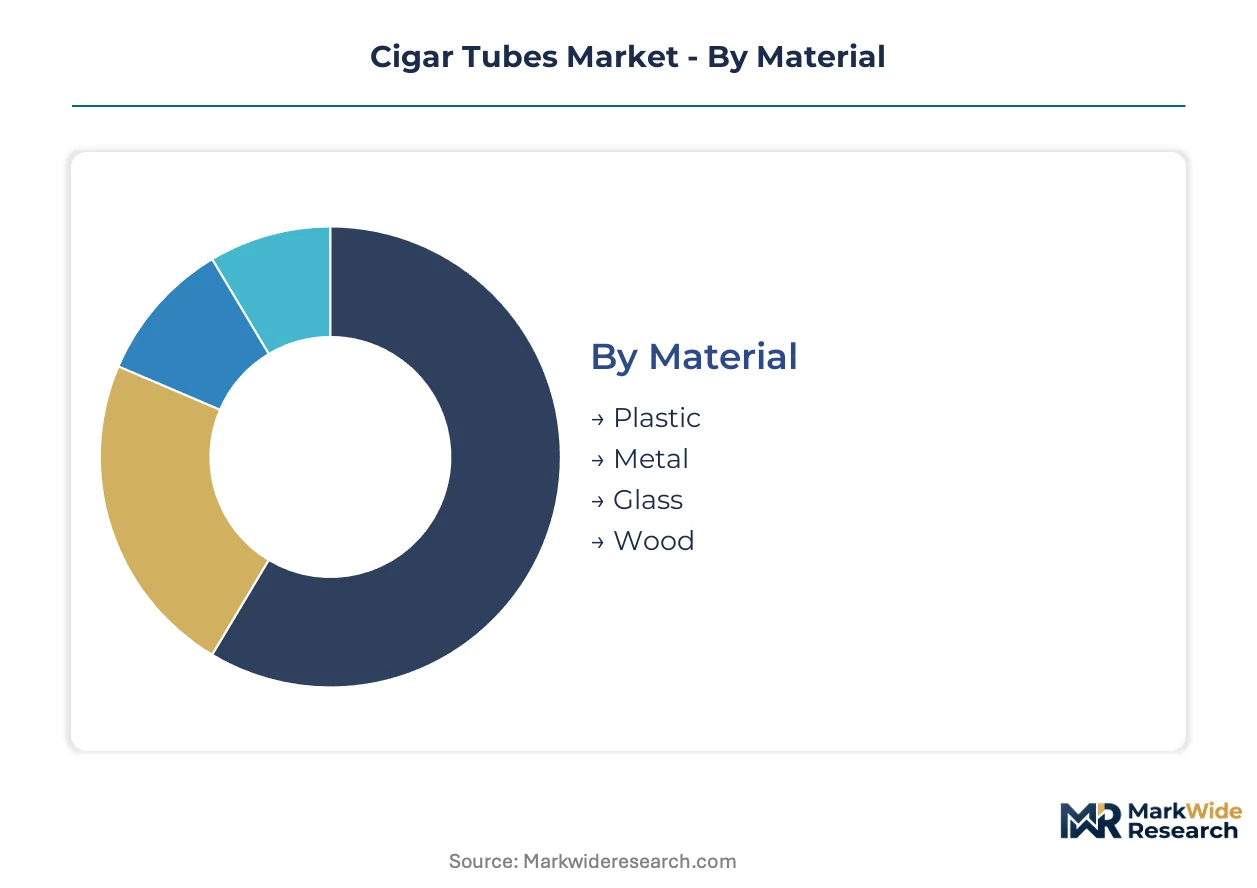
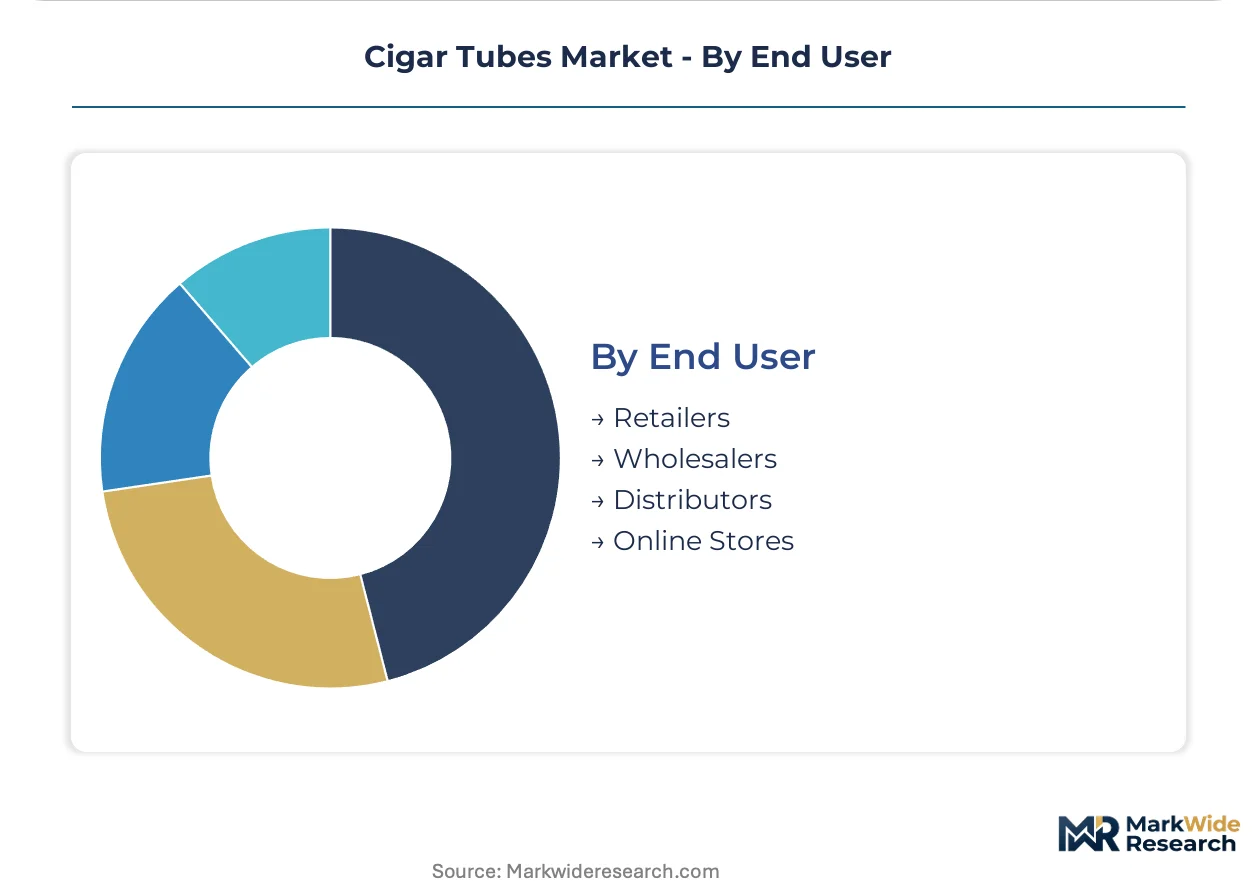
Cigar tube purchasing decisions cascade from material selection through distribution channel, with each tier imposing distinct compliance burdens and margin structures. Suppliers configure production lines around these segment intersections rather than treating them as independent variables.
Material:
Use-case spectrum spans mass-market disposability through heirloom collectibility, with substrate choice locking in regulatory pathway and end-of-life obligation.
- Metal:Deep-drawn aluminum alloys, primarily 6061-T6, deliver 0.3mm wall thickness with hermetic screw-cap integration. Volume concentrates in German and United States duty-free retail channels where REACH-compliant anodized finishes unlock shelf access.
- Glass:Borosilicate tubes with cork closures command tableside service placement in Miami and Dubai premium lounges. Master glassblower scarcity in Bohemia and Murano constrains output, preserving margin through artificial supply limitation.
- Plastic:Food-grade polymers serve single-use hospitality applications in price-sensitive markets.
- Wood:Cedar-lined tubes target humidor-adjacent storage for aging-focused collectors.
The dominant share belongs to Metal, while Glass is closing the gap fastest through lounge channel expansion.
Size:
Format dimensions correlate directly with cigar ring gauge popularity and regional smoking duration preferences.
- Standard:Accommodates 42-50 ring gauge cigars in 125-150mm lengths, matching the most common hand-rolled formats from Nicaragua and Honduras. United States tobacconists stock this format as the default recommendation for gift purchases.
- King:Extended 180mm+ chambers house Churchill and Double Corona formats prevalent in European ceremonial smoking occasions. German distributors specify King tubes for corporate hospitality programs.
- Mini:Compact 38-75mm formats align with cigarillo and small cigar growth in convenience retail.
- Short:Robusto and Petit Corona dimensions capture commuter-oriented consumption in urban transit corridors.
Standard formats generate the highest absolute volume, though King sizes carry the steepest per-unit margin expansion.
Closure Type:
Sealing mechanism selection determines hermetic performance, user experience, and manufacturing capital intensity.
- Screw Cap:Aluminum-threaded closures enable repeatable opening cycles without seal degradation. E-commerce fulfillment networks in the United States prioritize screw-cap tubes for shipping durability.
- Cork:Natural bark closures signal artisanal provenance and support secondary market authentication. Collector auction platforms in London and New York grade tube condition partly by cork integrity.
- Slide Lid:Rectangular aluminum extrusions offer one-handed operation for mobile use cases.
- Snap Fit:Polymer integral hinges minimize component count for disposable hospitality tubes.
Screw Cap maintains volume leadership, yet Cork is expanding most quickly through provenance-focused collector behavior.
End User:
Channel structure fragments procurement specifications across inventory velocity, customization depth, and compliance documentation requirements.
- Retailers:Brick-and-mortar tobacconists in the United States and Germany demand batch-level traceability documentation for FDA and REACH compliance. These buyers specify mixed-material assortments to cover price-tier breadth.
- Online Stores:Direct-to-consumer platforms prioritize lightweight aluminum formats that minimize dimensional weight shipping penalties. Returns handling protocols favor screw-cap durability over cork fragility.
- Wholesalers:Volume aggregators in Guangdong province consolidate multi-brand orders for emerging market redistribution.
- Distributors:Scandinavian Tobacco Group and Imperial Brands networks impose ISO 9001 certification as a non-negotiable qualification threshold.
Retailers command the largest current share, while Online Stores are gaining share fastest through collector marketplace displacement of traditional tobacconist channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity diverges sharply across geographies: collectors in the United States and Germany absorb premium markups with minimal volume sensitivity, while price-conscious buyers in emerging markets treat aluminum tubes as interchangeable commodities.
United States
Premium cigar lounge membership growth in Miami and New York City sustains demand for cork-sealed borosilicate presentation formats. FDA Center for Tobacco Products oversight mandates batch-level traceability documentation that favors ISO 9001-certified suppliers. Phoenix Glass LLC leverages its artisanal glassblowing heritage to dominate collectible segments through scarcity positioning.
Germany
Duty-free retail channels at Frankfurt and Munich airports specify REACH-compliant anodized aluminum tubes for volume procurement. EU REACH Substance of Very High Concern screening protocols lock out non-compliant Asian suppliers from German distribution networks. Stuttgart-based industrial designers collaborate with Bohemian glass ateliers on limited-edition releases.
China
Deep-draw aluminum manufacturing concentrates in Guangdong and Zhejiang provinces, compressing unit economics for mid-market tube supply. The country's national tobacco regulator enforces material contact safety standards that parallel FDA frameworks. Shenzhen Junen Packing Group anchors Pearl River Delta production capacity for export-oriented contracts.
United Kingdom
Verified resale marketplaces in London displace traditional tobacconist channels for rare tube acquisitions among collectors. The Medicines and Healthcare products Regulatory Agency maintains vigilance over food-contact material claims in accessory packaging. Edinburgh-based auction platforms grade cork integrity as a condition metric, reinforcing provenance documentation priorities.
United Arab Emirates
Dubai premium lounge expansion drives tableside service accessory demand for cork-sealed presentation formats. The Ministry of Health and Prevention regulates tobacco product adjacencies including packaging materials. Jumeirah district hospitality procurement favors lightweight aluminum screw-cap designs for poolside service durability.
Cigar Tubes Market Competitive Environment
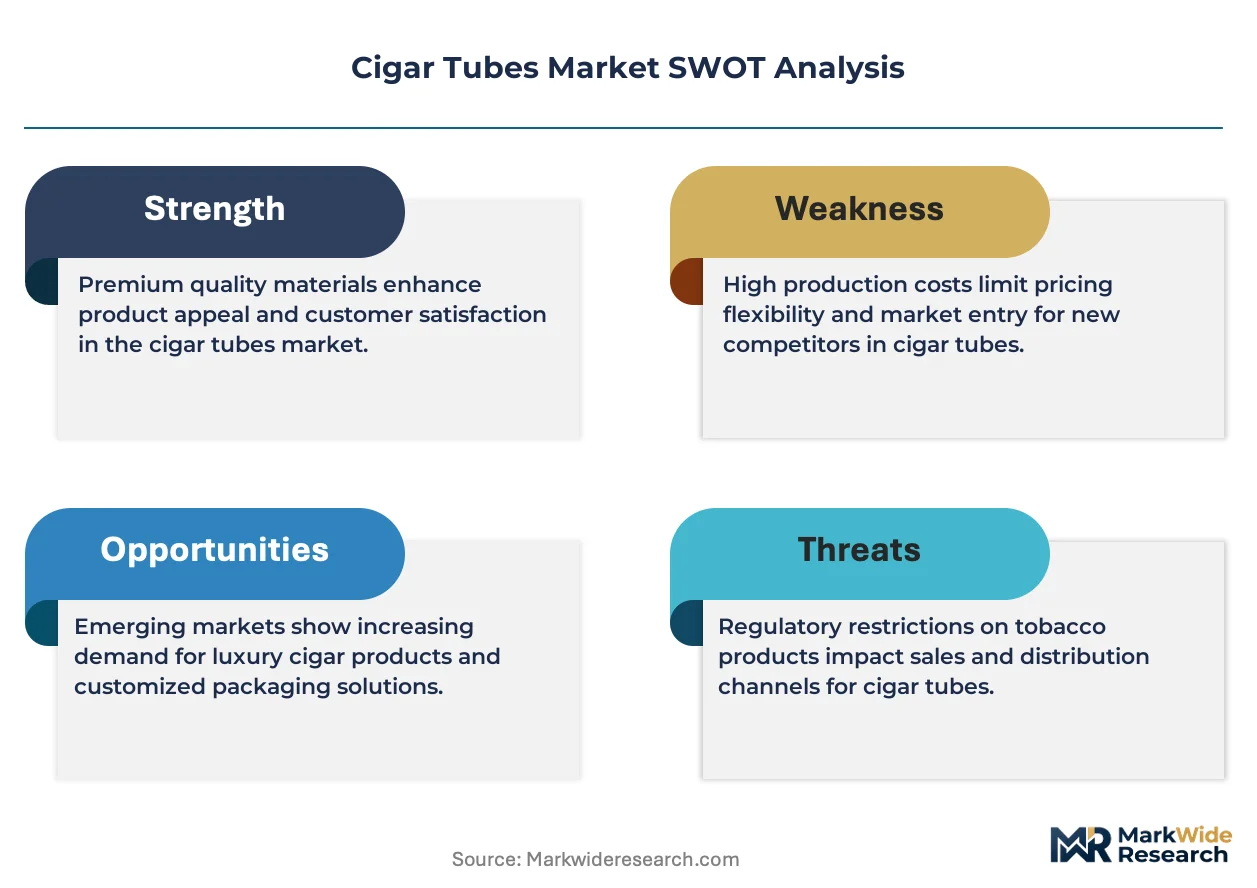
Capability concentration sits with heritage glass ateliers; scale advantage sits with Guangdong-based metal formers. The supplier base organizes into three capability tiers: commodity aluminum deep-draw specialists, certified polymer converters, and master-craftsman glass studios. Two strategic archetypes dominate competitive positioning—scarcity-driven artisanal producers and cost-optimized volume manufacturers. Capacity expansion and geographic licensing partnerships represent the dominant competitive moves as suppliers seek to bridge capability gaps.
Among North American heritage producers, Phoenix Glass LLC exemplifies the artisanal scarcity archetype through its furnace-craft positioning. New Song Yi Aluminium Can Manufactory Co. Ltd. anchors the scale-driven tier with its Zhejiang-based metal-forming operations. Scandinavian Tobacco Group occupies a hybrid position, leveraging controlled retail networks to integrate backward into captive tube supply.
| Leading Market Players |
|---|
| Phoenix Glass LLC |
| Adelphi Healthcare Packaging |
| New Song Yi Aluminium Can Manufactory Co. Ltd. |
| ECMI Ltd |
| Montebello |
| Shenzhen Junen Packing Group |
| Imperial Brands |
| Scandinavian Tobacco Group |
| Altadis USA |
| Others |
Value Chain & Pricing Dynamics
Guangdong and Zhejiang province manufacturing clusters compress unit economics for aluminum deep-draw tube suppliers while preserving pricing power for Bohemian and Murano glass ateliers constrained by master craftsman scarcity. This geographic bifurcation between scale-driven metal forming and scarcity-positioned artisanal production locks in divergent margin architectures across the value chain.
Pricing Analysis
Aftermarket customization and limited-edition packaging revenue drives lifetime value capture away from commodity tube supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by material substrate and closure complexity, with cork-sealed borosilicate variants commanding boutique channel markups against screw-cap aluminum mass retail positioning. Cost compression in mid-market aluminum segments intensifies because London Metal Exchange feedstock volatility destabilizes contract pricing for volume buyers. Price-sensitive emerging market distributors treat aluminum tubes as interchangeable commodities, while United States and German collectors absorb premium markups with minimal volume sensitivity.
Supply Chain Analysis
Upstream borosilicate glass feedstock dependence on Schott AG and Corning Incorporated creates single-source vulnerability for artisanal tube producers drawing from German and United States specialty glass manufacturers. Aluminum alloy 6061-T6 supply rests on deep-draw forming capacity concentrated in Guangdong and Zhejiang provinces, with anodized finishing chemicals sourced from REACH-compliant European chemical suppliers. Distribution runs through Scandinavian Tobacco Group and Imperial Brands controlled retail networks for premium segments, while Guangdong-based volume aggregators consolidate multi-brand orders for emerging market redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward collector auction platforms and verified resale marketplaces that displace traditional tobacconist channels, fragmenting procurement concentration and enabling direct-to-collector pricing power.
For Market Incumbents: Insulate premium positioning by deepening captive supply relationships with Bohemian and Murano glass ateliers before master craftsman scarcity worsens. Secure ISO 9001 certification renewals ahead of Scandinavian Tobacco Group and Imperial Brands supplier qualification cycles to defend distribution access against emerging polymer converters. For New Entrants and Emerging Players: India state-level lounge licensing in Karnataka and Maharashtra offers underpenetrated white-space for accessory bundling with consumption venue expansion. Target polylactic acid tube development for EU Single-Use Plastics Directive compliance as a first-mover sustainability angle, pairing with German industrial designers for limited-edition credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage glass ateliers with furnace-craft scarcity and NFT-authentication capability integration. Long-term viability hinges on provenance documentation infrastructure rather than brand heritage alone. Watch auction platform liquidity concentration in United States and United Kingdom secondary markets as inflection indicator for channel displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Master Craftsman Apprenticeship Program | Borosilicate glass ateliers in Bohemia and Murano secure pipeline against artisan scarcity. |
| REACH-Compliant Anodized Finish Certification | Aluminum suppliers unlock duty-free access to German and French retail channels. |
| NFT-Authenticated Limited Edition Launch | Direct-to-collector platforms bypass traditional wholesale markups for rare tube releases. |
| Polylactic Acid Biodegradable Tube Development | EU Single-Use Plastics Directive compliance creates first-mover advantage in sustainable packaging. |
| ISO 9001 Certification Acceleration | Supplier qualification for Scandinavian Tobacco Group distribution networks shortens audit timelines. |
Study Parameters
A spread of perspectives from master glassblowers in Czech Republic and Italy, aluminum deep-draw plant managers in Guangdong, premium lounge operators in Miami and Dubai, and procurement leads at Scandinavian Tobacco Group converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA Center for Tobacco Products guidance documents, EU REACH Substance of Very High Concern screening protocols, ISO 9001 certification databases, and customs trade data for aluminum alloy imports. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material substrate, closure type, format size, end-user channel, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for lounge channel expansion velocity and collector marketplace displacement patterns. Industry-specific forecast inputs incorporated London Metal Exchange aluminum price volatility assumptions and master glassblower graduation rates from traditional furnace craftsmanship programs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by NFT-authentication platform entrants or rapid EU biodegradable mandate acceleration would shift outcomes. Cross-checking against verified resale marketplace transaction volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
E-Cigarette and Vaping Market
Tobacco Products
Menthol Cigarette Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Cigarette Market
Tobacco Products
Tobacco Products Market
Tobacco Products
North America E-Cigarette Market
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
GCC E-Cigarette Market