
 E-Cigarette and Vaping Market | 2026-2036
E-Cigarette and Vaping Market Size, Share, and Industry Trends Forecast 2026-2036
E-Cigarette and Vaping Market Analysis
Pod-modular bundling is restructuring how consumers enter and upgrade within the category, shifting purchase behavior from single-device transactions toward ecosystem lock-in. British American Tobacco leverages its Vuse platform to sustain recurring revenue through proprietary pod compatibility. Philip Morris International anchors its IQOS transition strategy in heated-tobacco ecosystems that compete directly with liquid-based alternatives. Altria Group, Inc. navigates regulatory complexity through minority stakes and distribution partnerships rather than full vertical ownership.
E-cigarettes and vaping devices constitute battery-powered aerosol delivery systems that heat nicotine-containing e-liquids—typically propylene glycol, vegetable glycerin, flavorants, and nicotine salts—to temperatures between 200°C and 250°C for inhalation without combustion. The primary commercial purpose centers on reduced-risk nicotine consumption relative to conventional tobacco combustion. E-liquids command disproportionate margin pools due to repeat purchase frequency and flavor customization, while vaping devices face hardware commoditization pressure from Chinese original equipment manufacturers. Distribution through online stores dominates volume for experienced users seeking variety, though specialty shops retain premium positioning through hands-on device customization and coil-building services.
The FDA exercises premarket tobacco product application authority over nicotine delivery systems, while the EU Tobacco Products Directive mandates maximum nicotine concentrations and refill container sizes; China's SAMR governs domestic manufacturing standards under GB specifications. These frameworks fragment product availability across jurisdictions, forcing manufacturers to maintain parallel SKU portfolios. Stakeholders must monitor pending flavor prohibitions and synthetic nicotine classification rulings that could eliminate entire product categories or redirect demand toward heated-tobacco alternatives.
Market Dynamics
Pod-modular bundling is restructuring how consumers enter and upgrade within the category, shifting purchase behavior from single-device transactions toward ecosystem lock-in. This structural force concentrates margin capture in consumable pods while commoditizing hardware manufacturing.
Growth Catalysts
- Flavor customization:Young adult users drive repeat purchase frequency through personalized e-liquid formulations, creating sustained demand velocity in convenience retail channels.
- FDA premarket tobacco product application pathway:Regulatory clarity for compliant manufacturers creates competitive moats against non-compliant imports, consolidating shelf space at major retailers.
- Heated-tobacco convergence:IQOS-style platforms expand the addressable user base beyond traditional combustible smokers, broadening category legitimacy.
Market Restraints
- Propylene glycol supply concentration:Chinese chemical manufacturers dominate feedstock production, exposing formulators to input cost volatility and trade friction.
- Nicotine salt technical limitation:Benzoic acid formulations face stability degradation at temperature extremes, constraining product shelf life in uncontrolled retail environments.
- EU Tobacco Products Directive nicotine caps:Maximum concentration limits compress margin pools in European markets, forcing portfolio rationalization.
Strategic Opportunities
- Synthetic nicotine reclassification uncertainty:Pending FDA rulings on non-tobacco-derived nicotine could open regulatory arbitrage windows for first-mover manufacturers.
- Specialty vape shop channel innovation:Hands-on coil-building services and device customization retain premium positioning against online commoditization.
- United Kingdom regulatory divergence:Post-Brexit standards flexibility permits product configurations banned in EU markets, creating export manufacturing advantages.
Industry Challenges
- Aerosol toxicology certification timelines:Premarket application requirements demand multi-year longitudinal studies, compressing product development cycles.
- Coil resistance standardization delays:Incompatible threading and power specifications across device ecosystems fragment aftermarket parts demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Cigarette and Vaping Market |
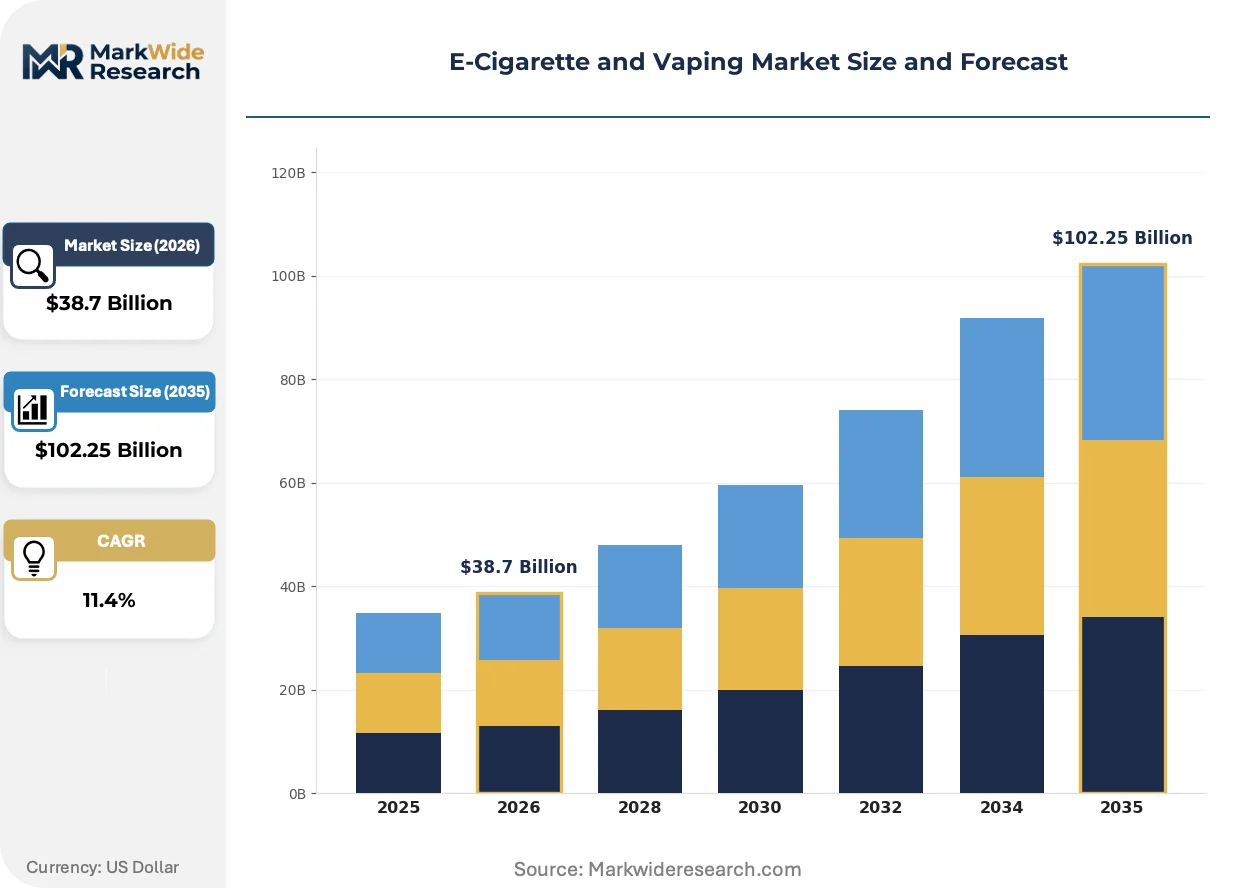
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-Cigarettes, Vaping Devices, E-Liquids, Accessories User Demographics: Young Adults, Smokers, Health-Conscious Individuals, Recreational Users Distribution Channel: Online Stores, Specialty Shops, Convenience Stores, Supermarkets Flavor Profile: Tobacco, Menthol, Fruity, Dessert |
| Companies Covered | Altria Group, Inc., British American Tobacco, Imperial Brands, Philip Morris International Inc., Japan Tobacco Inc., JUUL Labs, Inc., R.J. Reynolds Vapor Company, RELX Technology, SMOK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Cigarette and Vaping Market Emerging Trajectories
Three forces are actively reshaping competitive positioning in nicotine delivery: ceramic heating elements, synthetic nicotine classification debates, and convenience channel migration. Each trend reconfigures where value accrues across the value chain.
Ceramic coil technology is rewriting thermal efficiency benchmarks in pod-based systems. Premium device manufacturers are adopting porous ceramic substrates to eliminate metallic taste and extend coil lifespan. This material shift is compressing replacement part revenue while enabling higher-temperature flavor profiles that differentiate proprietary pod formats.
REACH chemical registration requirements in Europe are forcing reformulation of flavorant portfolios. E-liquid manufacturers must substitute restricted aromatic compounds with compliant alternatives or withdraw SKUs from EU markets. Heated-tobacco products face parallel scrutiny, redirecting R&D investment toward aerosol characterization studies.
Young adult users are consolidating purchases through convenience store chains with locked tobacco cabinets. This channel migration displaces independent vape shops in volume terms while concentrating distribution power with retail conglomerates. The United States exhibits the most pronounced shift, where regulatory enforcement against online sellers accelerates brick-and-mortar capture.
E-Cigarette and Vaping Market Segmentation
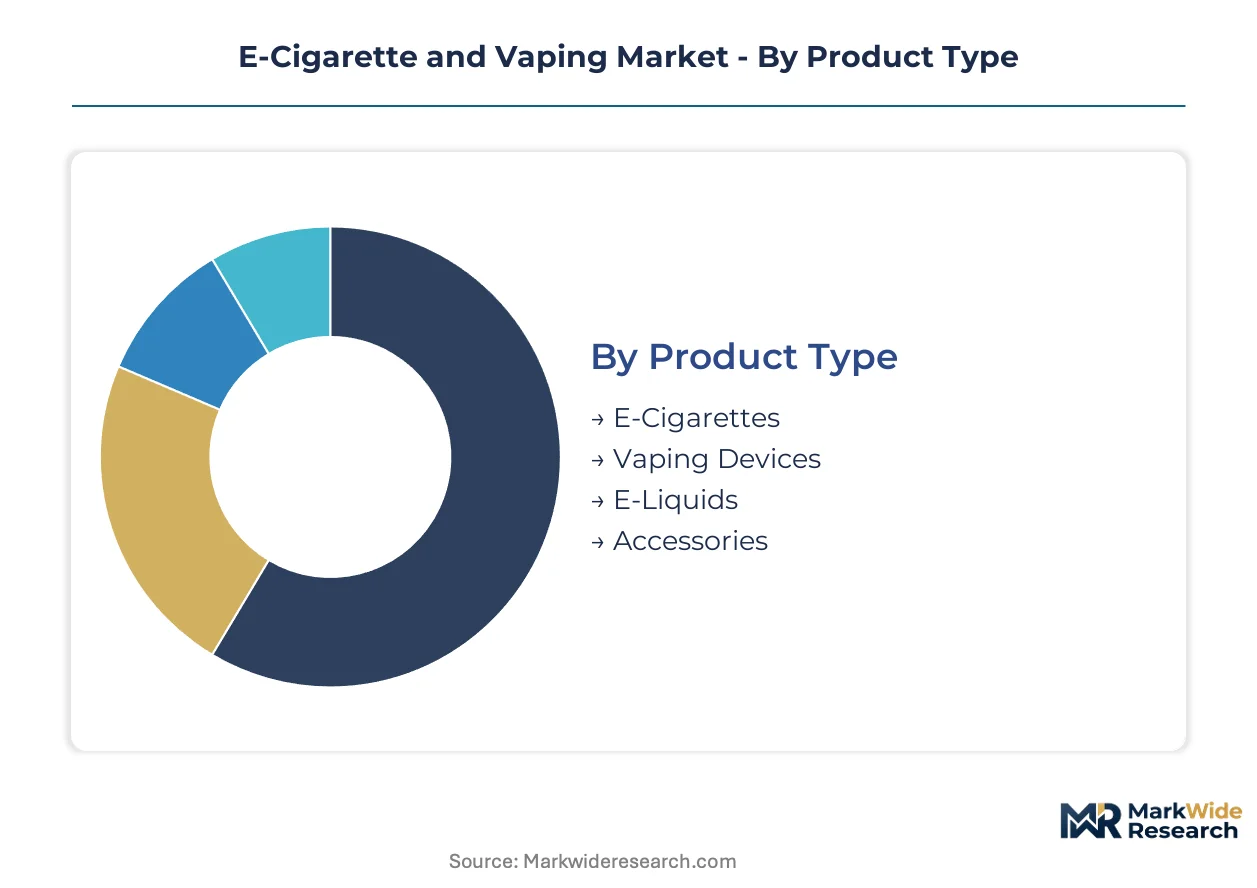
Segmentation in the E-Cigarette and Vaping Market reveals how upgrade cycles and replacement frequency concentrate margin capture differently across hardware, consumables, and channel access. Each dimension exposes distinct pricing power and regulatory exposure.
Product Type:
Replacement cycles define how value migrates between durable hardware and recurring consumables.
- E-Cigarettes:Closed-system devices with integrated power management and fixed output wattage dominate entry-level adoption. Demand clusters in the United States among smokers transitioning from combustibles, constrained by FDA premarket authorization timelines that limit new entrant competition.
- Vaping Devices:Modular open systems with variable voltage control and interchangeable atomizers command premium positioning. Adoption concentrates among experienced users in the United Kingdom seeking customization, driven by post-Brexit regulatory flexibility permitting higher-output configurations banned in EU markets.
- E-Liquids:Propylene glycol and vegetable glycerin formulations with nicotine salt or freebase delivery.
- Accessories:Replacement coils, batteries, and charging apparatus.
E-Liquids sits at the top of the volume ranking, with Vaping Devices climbing the fastest.
User Demographics:
Cost tier stratification separates premium wellness positioning from mass-market nicotine substitution.
- Young Adults:Users aged 18-25 prioritize flavor variety and device aesthetics over longevity. This cohort drives repeat purchase velocity in convenience retail channels, though flavor restrictions in select US states compress available SKU ranges.
- Smokers:Current combustible tobacco users seeking reduced-risk alternatives. Demand concentrates in China where domestic manufacturers optimize for throat-hit replication, supported by SAMR manufacturing standards that streamline domestic approval pathways.
- Health-Conscious Individuals:Users prioritizing ingredient transparency and third-party testing.
- Recreational Users:Non-dependent consumers attracted to social and sensory experience.
Smokers dominates current volume, with Young Adults expanding most quickly.
Distribution Channel:
Geographic concentration of channel power determines which stakeholders capture end-user relationships.
- Online Stores:Direct-to-consumer platforms with subscription replenishment and flavor variety. Volume concentrates among experienced users in the United States, though FDA enforcement against unapproved product listings accelerates channel shift toward brick-and-mortar verification.
- Specialty Shops:Staff-assisted retail with coil-building services and device customization. Premium positioning persists in the United Kingdom where independent retailers leverage MHRA notification guidance to curate compliant product ranges.
- Convenience Stores:Locked-cabinet tobacco sections with limited flavor selection.
- Supermarkets:Mass-market retail with standardized pod-system offerings.
Online Stores leads volume currently, with Convenience Stores gaining share fastest.
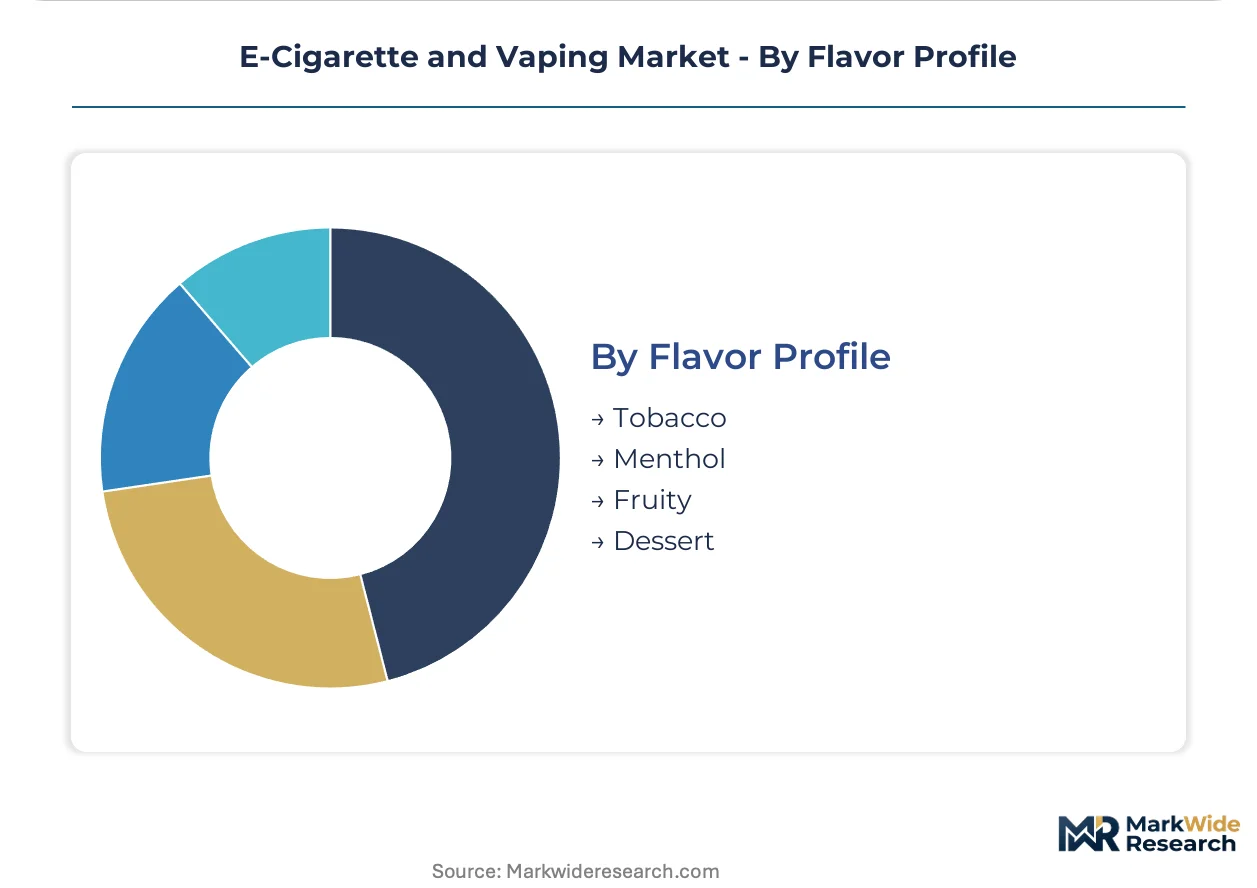
Flavor Profile:
Margin structure varies sharply between regulated core flavors and restricted specialty formulations.
- Tobacco:Standardized formulations replicating combustible taste profiles. Demand anchors in EU markets where Tobacco Products Directive nicotine caps force flavor simplification, with manufacturers prioritizing shelf-stable recipes for retail compliance.
- Menthol:Cooling-agent formulations with crystalline additive suspension. Concentrated demand in the United States persists despite municipal bans, driven by consumer preference for sensory masking and perceived smoothness.
- Fruity:Ester-based aromatic compounds with glycerin carrier optimization.
- Dessert:Vanillin and lactone flavorants with sweetness modulation.
Tobacco holds the volume lead, with Fruity facing steepest regulatory compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The e-cigarette industry traces its commercial origins to China in the early 2000s, where Hon Lik developed the first modern vaping device. Shenzhen subsequently emerged as the manufacturing nucleus, supplying hardware to markets worldwide. Today, regulatory divergence across major economies fragments product availability and shapes competitive positioning.
United States
Young adult users drive flavor variety demand through convenience retail channels, with locked tobacco cabinets displacing independent vape shops in volume terms. FDA premarket tobacco product application authority creates competitive moats for compliant manufacturers while compressing shelf space for non-compliant imports. California and New York State enforce municipal flavor prohibitions that redirect demand toward tobacco-menthol formulations.
China
Domestic manufacturers optimize device output for throat-hit replication targeting combustible smokers transitioning to reduced-risk alternatives. SAMR governs manufacturing standards under GB specifications that streamline domestic approval pathways while restricting export product configurations. Shenzhen industrial clusters concentrate OEM production capacity, exposing formulators to propylene glycol feedstock cost volatility.
United Kingdom
Post-Brexit regulatory flexibility permits higher-output vaping configurations banned in EU markets, creating export manufacturing advantages for domestic device producers. MHRA notification guidance enables independent retailers to curate compliant product ranges with hands-on coil-building services. London and Manchester anchor specialty shop networks that retain premium positioning against online commoditization.
Germany
REACH chemical registration requirements force e-liquid manufacturers to substitute restricted aromatic compounds with compliant alternatives or withdraw SKUs entirely. ECHA oversight of flavorant portfolios redirects R&D investment toward aerosol characterization studies. North Rhine-Westphalia industrial zones concentrate distribution infrastructure serving cross-border EU demand.
Japan
Heated-tobacco platforms expand addressable user bases beyond traditional combustible smokers, with IQOS-style devices competing directly with liquid-based alternatives. PMDA and METI coordinate on reduced-risk product classification pathways that diverge from pharmaceutical nicotine regulation. Tokyo and Osaka metropolitan areas concentrate early-adopter demand for ceramic heating element technologies.
E-Cigarette and Vaping Market Vendor Landscape
Premium-margin players sit above commodity-margin players across hardware manufacturing tiers, with proprietary pod compatibility sustaining recurring revenue against OEM commoditization pressure. The vendor base stratifies between multinational tobacco conglomerates with ecosystem lock-in strategies and Chinese original equipment manufacturers competing on unit cost. Three archetypes dominate: closed-system platform operators, open-system modular suppliers, and heated-tobacco convergence specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with minority stakes substituting for full vertical ownership where regulatory complexity elevates risk.
Within the multinational tobacco tier, British American Tobacco and Philip Morris International exemplify ecosystem-centric positioning through proprietary platform strategies. Altria Group, Inc. occupies a distinct structural position, navigating regulatory complexity through distribution partnerships and minority equity arrangements rather than captive manufacturing. RELX Technology represents the Chinese OEM archetype, with Shenzhen-based production capacity supplying global hardware demand.
| Leading Market Players |
|---|
| Altria Group, Inc. |
| British American Tobacco |
| Imperial Brands |
| Philip Morris International Inc. |
| Japan Tobacco Inc. |
| JUUL Labs, Inc. |
| R.J. Reynolds Vapor Company |
| RELX Technology |
| SMOK |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up Chinese OEM specialists concentrate Shenzhen manufacturing capacity, translating feedstock cost volatility into asymmetric pricing power that compresses margin pools for branded device marketers while sustaining hardware commoditization pressure.
Pricing Analysis
Subscription-based pod replenishment models dominate revenue architecture, locking consumers into recurring consumable purchases at premium per-milliliter rates while subsidizing initial hardware acquisition. Price differentiation hinges on flavor complexity tiers and FDA premarket authorization status, with compliant SKUs commanding shelf-space premiums against gray-market alternatives. Cost compression in open-system hardware is intensifying because Shenzhen OEMs flood export channels with interchangeable 510-threaded devices. Smokers transitioning from combustibles exhibit highest price sensitivity, while experienced users seeking coil-building customization tolerate premium positioning.
Supply Chain Analysis
Propylene glycol feedstock rests on Chinese petrochemical producers, with vegetable glycerin co-sourced from Malaysia and Indonesia palm oil derivatives. Ceramic heating element substrates draw from Japanese specialty ceramics manufacturers, while lithium-ion cells for rechargeable devices center on South Korean and Chinese battery suppliers. Single-source vulnerability concentrates in benzoic acid for nicotine salt formulations, where pharmaceutical-grade suppliers face regulatory qualification bottlenecks. Distribution runs through Shenzhen export hubs into regional fulfillment networks serving convenience retail chains and online direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market depend on ceramic coil technology maturation reducing replacement frequency, while premium-tier pod systems capture recurring revenue through proprietary format lock-in.
For Market Incumbents: To counter FDA premarket application backlogs compressing compliant SKU availability, accelerate backward integration into ceramic substrate manufacturing and secure captive nicotine salt supply through pharmaceutical-grade benzoic acid partnerships. Channel control through locked-cabinet convenience retail placement sustains shelf-space moats against online gray-market erosion. For New Entrants and Emerging Players: Health-conscious individuals seeking third-party tested e-liquids represent an underserved buyer archetype with premium tolerance and regulatory alignment incentives. White-space targets include UK specialty shop channels leveraging MHRA notification guidance for compliant curation, and synthetic nicotine formulations pending FDA classification clarity. Go-to-market positioning should emphasize ingredient transparency certification and subscription replenishment models. For Investors and Strategic Acquirers: Valuations sit cheapest among open-system hardware OEMs facing commoditization pressure, while proprietary pod-platform operators command ecosystem-premium multiples. Long-term viability framing favors heated-tobacco convergence specialists with PMDA reduced-risk classification pathways and ceramic heating element IP portfolios. Watch FDA synthetic nicotine rulings as inflection indicator for regulatory arbitrage window timing.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating Element Adoption | Porous ceramic substrates eliminate metallic taste and extend coil lifespan, compressing aftermarket replacement revenue. |
| Flavor Portfolio Reformulation | REACH-compliant aromatic compound substitutions enable continued EU market access amid ECHA registration deadlines. |
| Pod-Modular Ecosystem Expansion | Proprietary compatibility lock-in sustains recurring consumable revenue against hardware commoditization pressure. |
| Convenience Channel Capture | Locked-cabinet retail placement displaces independent vape shops in volume terms and concentrates distribution power. |
| Synthetic Nicotine Prepositioning | Non-tobacco-derived nicotine formulations pending FDA classification open regulatory arbitrage windows for first movers. |
Methodological Framework
Coverage spans the United States, China, the United Kingdom, Germany, and Japan, with primary inputs from each market combining structured interviews with e-liquid formulation chemists, convenience retail category buyers, regulatory affairs specialists at multinational tobacco conglomerates, and independent vape shop operators with secondary validation against FDA premarket tobacco product application databases, MHRA notification guidance publications, SAMR GB specification filings, ECHA REACH registration records, and customs trade flow data. Bottom-up SKU-level volume builds triangulate with top-down manufacturer revenue estimates.
Rate-of-change decomposition separates volume growth from pricing dynamics and mix-shift effects across the projection horizon. Segmentation dimensions modeled include product type, user demographic cohort, distribution channel, and flavor profile category, with additional granularity on ceramic versus metallic heating element technology adoption. CAGRs derive from regression analysis against regulatory approval timelines and channel migration patterns, incorporating propylene glycol feedstock cost indices and nicotine salt formulation stability parameters as industry-specific forecast inputs.
Underlying measurement precision varies by segment; FDA-authorized product categories carry tighter precision than pending-application SKUs, while online channel volume estimates reflect greater uncertainty than brick-and-mortar retail audit data. Forecasts reflect assumptions on regulatory enforcement intensity and flavor prohibition scope that could revise trajectory materially. A small set of named triggers—FDA synthetic nicotine classification, EU Tobacco Products Directive revision timing, and China SAMR export standard adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Homemade Cigars Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Menthol Cigarette Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Cigarette Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Luxury Cigarette Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Electronic Cigarette Atomizer Market