
 Laboratory Ware Market | 2026-2036
Laboratory Ware Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Ware Market Intelligence
REACH compliance in Europe is rebalancing the cost-of-entry calculus for laboratory ware manufacturers seeking access to EU pharmaceutical supply chains. Thermo Fisher Scientific leverages its vertically integrated resin-to-product pipeline to absorb these regulatory costs without margin erosion. Merck KGaA anchors its competitive position through analytical-grade certification programs that exceed baseline REACH requirements. Corning Incorporated dominates borosilicate glassware supply through captive melting operations in North America and Asia.
Laboratory ware encompasses vessels, instruments, and apparatus constructed from glass, polymer, silicone, or metal substrates, engineered to precise thermal and chemical tolerance specifications for controlled experimental environments. Borosilicate glass withstands thermal shock up to 165°C differential, while fluoropolymer plastics deliver inert surfaces for trace metal analysis at parts-per-trillion detection limits. Glassware retains the largest revenue share across product types due to irreplaceable optical clarity and thermal stability in titration and distillation workflows. Pharmaceutical companies represent the fastest-expanding end user segment as outsourced CDMOs multiply their consumable throughput per manufacturing campaign.
FDA container closure guidance, EU REACH substance restrictions, and ISO 17025 laboratory accreditation standards collectively elevate material traceability and documentation burdens across the value chain. EPA Good Laboratory Practice requirements extend these compliance obligations to environmental testing laboratories handling hazardous sample matrices. Stakeholders must monitor evolving biocompatibility testing protocols for novel polymer formulations before committing capital to specialized molding capacity.
Market Dynamics
Biologics manufacturing expansion is restructuring laboratory ware procurement, as contract development organizations multiply their consumable throughput and demand analytical-grade certification that exceeds baseline regulatory thresholds.
Growth Catalysts
- CDMO Consumable Surge:Outsourced biopharma manufacturing campaigns are multiplying per-site consumable volumes as campaigns shorten and batch frequencies rise.
- REACH Substance Restrictions:ECHA's expanding SVHC candidate list is forcing material requalification, creating replacement demand for compliant polymer formulations.
- Trace Metal Analysis:Fluoropolymer plastics with parts-per-trillion inertness are penetrating environmental testing workflows as EPA Good Laboratory Practice requirements tighten.
Market Restraints
- Borosilicate Supply Concentration:Captive melting operations in North America and Asia limit third-party glassware availability during capacity crunches.
- Resin Cost Volatility:Fluoropolymer feedstock prices fluctuate with petrochemical cycles, compressing margins for specialized molding operations.
- ISO 17025 Documentation Burden:Laboratory accreditation standards extend material traceability requirements through multi-tier supply chains, lengthening qualification timelines.
Strategic Opportunities
- India Biopharma Cluster:CDSCO's streamlined manufacturing approvals are attracting biologics investment in Hyderabad and Bengaluru, creating localized consumable demand.
- Cell Therapy Workflows:Closed-system single-use assemblies are displacing open glassware in aseptic processing, opening polymer design contracts.
- Sustainability Mandates:EU Green Deal circularity requirements are rewarding suppliers with take-back programs and bio-based material certifications.
Industry Challenges
- Analytical Chemist Shortage:Specialized expertise in extractables and leachables testing is scarce, bottlenecking new product qualification.
- Multi-Site Harmonization:Biopharma manufacturers struggle to standardize consumable specifications across United States, Germany, and China facilities.
- Biocompatibility Testing Backlogs:Novel polymer formulations face extended ISO 10993 evaluation queues before specialized molding capacity commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Ware Market |
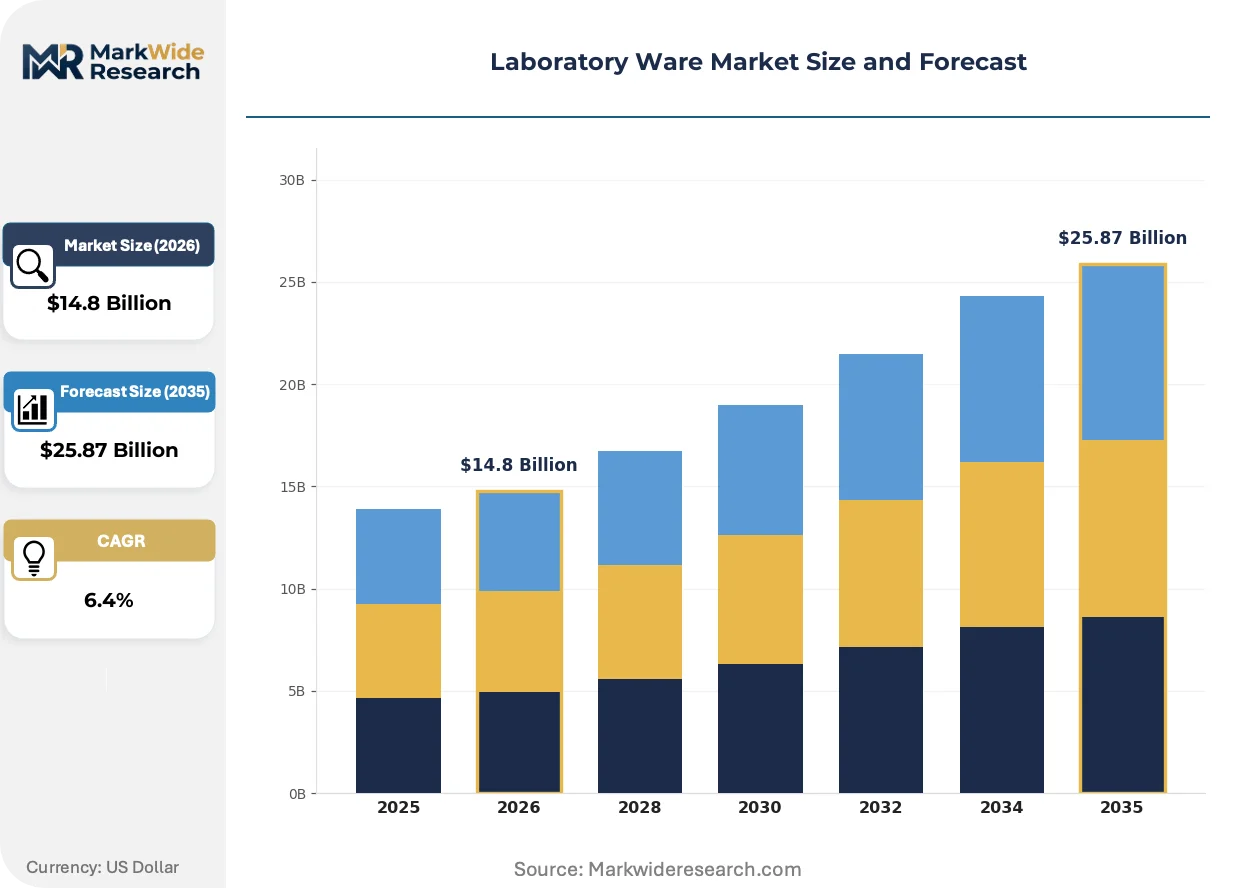
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glassware, Plastics, Silicone, Metal Application: Biological Research, Chemical Analysis, Quality Control, Material Testing End User: Academic Institutions, Pharmaceutical Companies, Environmental Labs, Clinical Laboratories Grade: Analytical Grade, Reagent Grade, Industrial Grade, USP Grade |
| Companies Covered | Agilent Technologies, Merck KGaA, Thermo Fisher Scientific, Sartorius, Eppendorf, Corning Incorporated, Avantor, PerkinElmer, DWK Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Ware Market Strategic Shifts & Innovations
Material science convergence with regulatory science is compressing product development cycles, as suppliers engineer substrates that anticipate certification requirements rather than react to them.
Fluoropolymer-coated glass hybrids are overtaking pure borosilicate in high-throughput screening applications. Pharmaceutical quality control laboratories in the United States are adopting these composites at pace to eliminate thermal shock failures during automated handling. The technology is overtaking traditional glassware in workflows where robotic transfer speeds exceed manual tolerance limits.
EU REACH substance restrictions are accelerating material substitution timelines. ECHA's 2023 expansion of per- and polyfluoroalkyl substance scrutiny is forcing reformulation of low-retention pipette tips and storage vessels. German analytical laboratories are responding by consolidating supplier relationships with vendors holding pre-validated alternative polymer portfolios.
Consolidated procurement through group purchasing organizations is compressing vendor margins while expanding contract volumes. CDMOs in China are aggregating consumable demand across multiple manufacturing campaigns, displacing site-level purchasing autonomy. This concentration is most visible in Shanghai and Suzhou biopharma clusters, where preferred supplier agreements now cover 80% of standard ware categories.
Laboratory Ware Market Segmentation
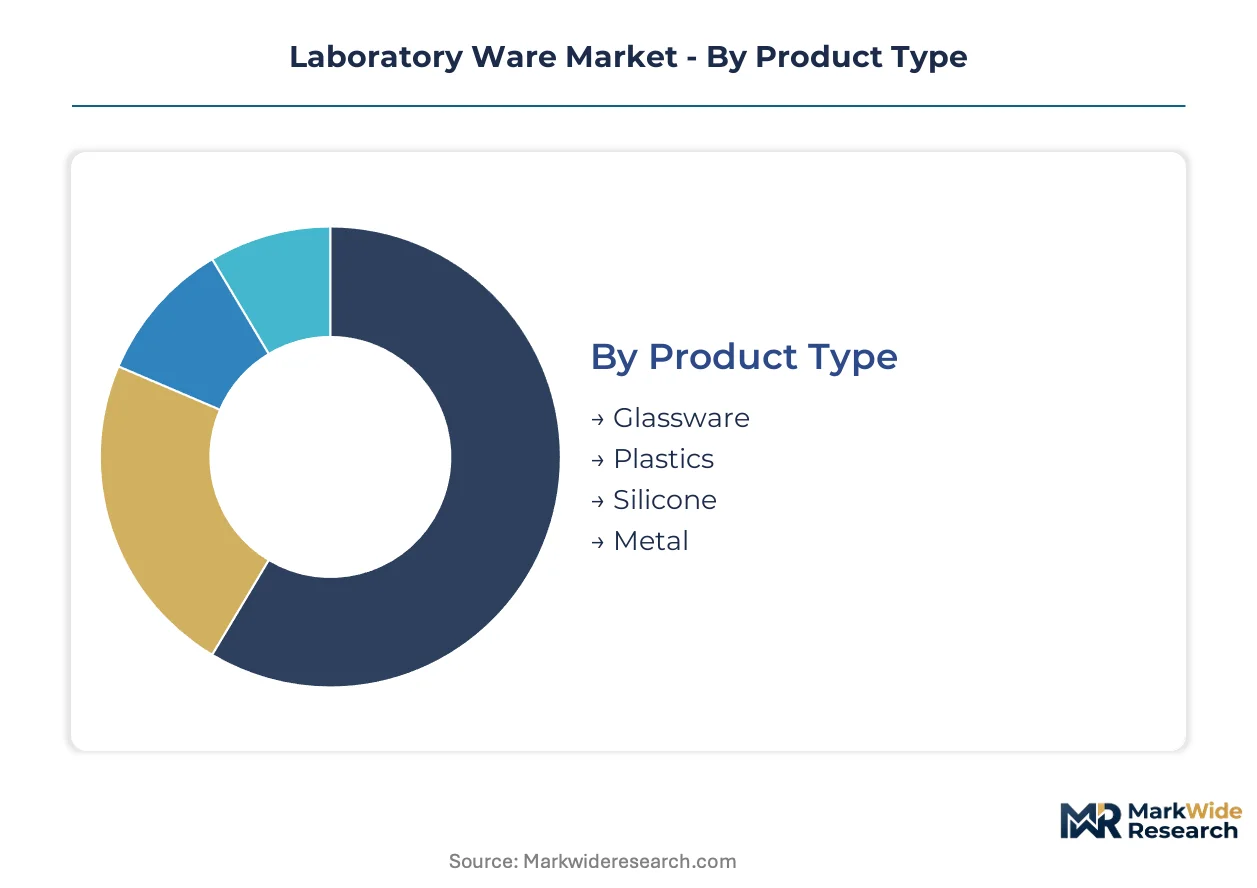
Laboratory ware segmentation reflects divergent technical specifications across end-use workflows. Material selection, certification grade, and application environment collectively determine procurement patterns and supplier relationships.
Product Type:
Buyers differentiate primarily by thermal tolerance requirements and chemical inertness needs.
- Glassware:Borosilicate formulations withstand thermal shock differentials up to 165°C, sustaining optical clarity for titration and distillation workflows. Pharmaceutical quality control laboratories in the United States favor these vessels for automated handling protocols where visual inspection remains mandatory.
- Plastics:Fluoropolymer substrates deliver parts-per-trillion inertness for trace metal analysis, with polymer formulations reformulating rapidly under ECHA per- and polyfluoroalkyl substance scrutiny. Environmental testing laboratories facing EPA Good Laboratory Practice tightening are migrating toward pre-validated alternative polymer portfolios.
- Silicone:Elastomeric seals and gaskets provide biocompatibility for cell therapy closed-system assemblies.
- Metal:Stainless steel apparatus serves high-pressure reactor applications and metal-catalyzed synthesis workflows.
Volume sits with Glassware; growth tilts toward Plastics.
Application:
Workflow specificity dictates material certification depth and documentation burden.
- Biological Research:Cell culture vessels and single-use assemblies require ISO 10993 biocompatibility validation. CDMOs in China are consolidating procurement across Shanghai and Suzhou clusters, with preferred supplier agreements now covering standard ware categories.
- Chemical Analysis:Extractables and leachables testing protocols create qualification bottlenecks. Analytical chemist scarcity extends timelines for novel substrate validation in German and United States pharmaceutical laboratories.
- Quality Control:Batch release testing demands analytical-grade certification exceeding baseline regulatory thresholds.
- Material Testing:Mechanical and thermal property characterization utilizes specialized fixtures and environmental chambers.
Biological Research commands the largest procurement volumes; Quality Control is climbing the fastest as outsourced manufacturing expands.
End User:
Procurement sophistication varies sharply by organizational scale and regulatory exposure.
- Academic Institutions:Budget-constrained purchasing prioritizes standard-grade consumables with minimal certification documentation. United States research universities are consolidating vendor relationships through group purchasing organizations to compress per-unit costs.
- Pharmaceutical Companies:Analytical-grade certification and multi-site harmonization requirements dominate procurement specifications. Biopharma manufacturers struggle to standardize consumable specifications across United States, Germany, and China facilities simultaneously.
- Environmental Labs:EPA Good Laboratory Practice compliance extends material traceability through hazardous sample matrices.
- Clinical Laboratories:Diagnostic workflow standardization favors high-throughput compatible vessel formats.
Pharmaceutical Companies generate the steepest expansion trajectory; Academic Institutions retain the broadest installed base.
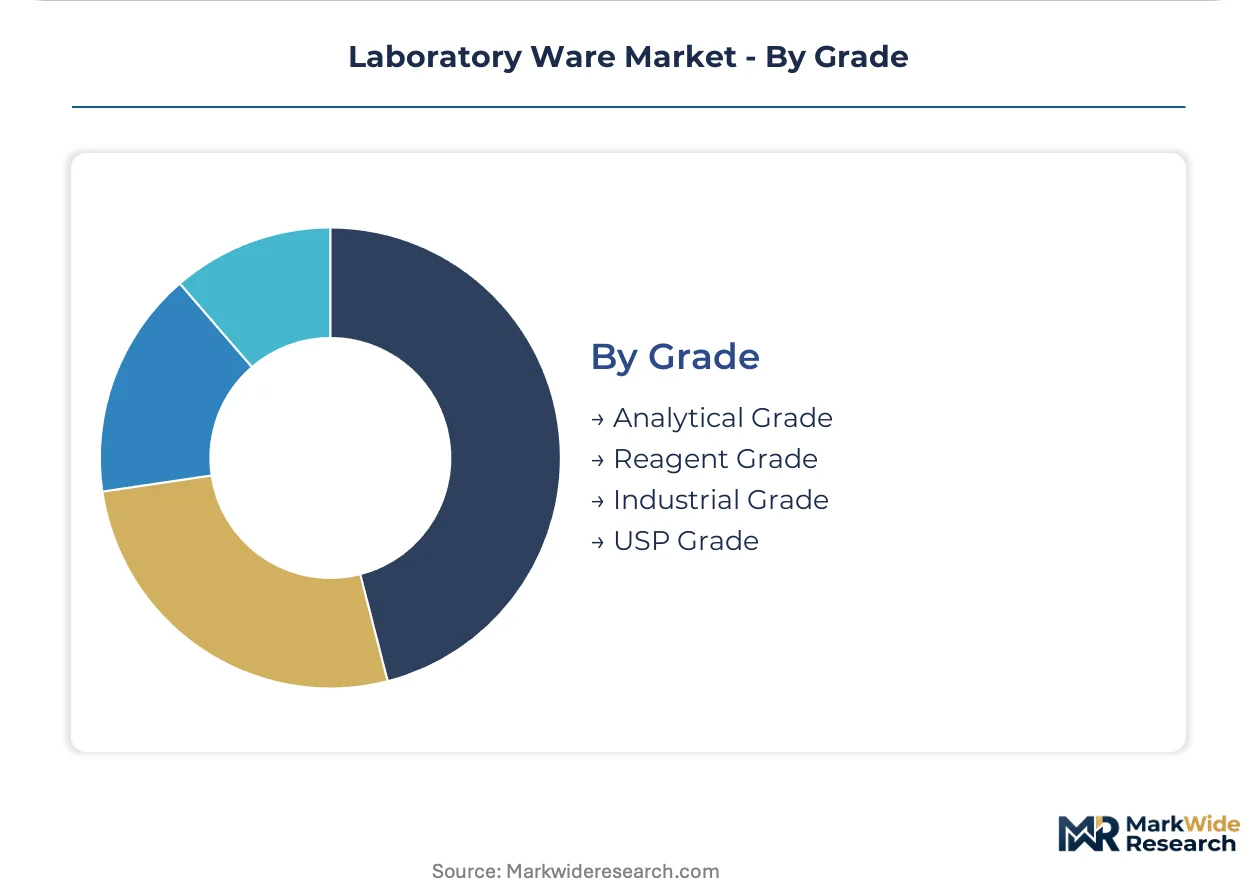
Grade:
Certification tier directly correlates with documentation burden and supplier qualification intensity.
- Analytical Grade:Ultra-low background contamination specifications support parts-per-trillion detection workflows. ECHA REACH substance restrictions are forcing material requalification, creating replacement demand for compliant formulations that exceed baseline thresholds.
- USP Grade:United States Pharmacopeia compliance is mandatory for pharmaceutical manufacturing contact materials. FDA container closure guidance tightening is elevating material traceability requirements through multi-tier supply chains.
- Reagent Grade:Standard purity specifications serve routine laboratory preparation and storage functions.
- Industrial Grade:Bulk process applications tolerate broader tolerance ranges at reduced unit cost.
Analytical Grade captures premium pricing; USP Grade is gaining share fastest as biologics manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China, Germany, and the United States concentrate biopharma manufacturing capacity and drive laboratory ware procurement intensity. FDA, EMA, and NMPA regulatory convergence is elevating certification requirements across these jurisdictions. CDMO clustering in specific metros is reshaping regional demand patterns.
United States
Biologics manufacturing expansion in Massachusetts and North Carolina is multiplying consumable throughput per site. FDA container closure guidance tightening is forcing material requalification across pharmaceutical supply chains. The Greater Boston cluster hosts the densest concentration of CDMOs demanding analytical-grade certification exceeding baseline thresholds.
Germany
ECHA REACH substance restrictions are accelerating polymer reformulation timelines for laboratory ware suppliers. The country's national pharmaceutical regulator enforces extractables and leachables documentation burdens that exceed EU baseline requirements. The Rhine-Main region around Frankfurt anchors analytical-grade glassware demand from contract research organizations serving EMA-regulated trials.
China
NMPA streamlined manufacturing approvals are attracting biologics investment to Shanghai and Suzhou biopharma clusters. The national medical products administration is harmonizing biocompatibility testing protocols with FDA and EMA standards. Yangtze River Delta CDMOs are consolidating procurement through preferred supplier agreements covering standard ware categories.
India
CDSCO manufacturing approval streamlining is drawing biologics investment to Hyderabad and Bengaluru. The Central Drugs Standard Control Organization is aligning biocompatibility requirements with ISO 10993 international standards. Telangana's Genome Valley cluster is generating localized demand for cell therapy closed-system assemblies displacing open glassware.
Switzerland
Swissmedic's stringent biologics oversight is sustaining premium-tier procurement from Basel-area pharmaceutical headquarters. The national pharmaceutical regulator mandates material traceability documentation that exceeds EMA baseline requirements. The Basel-Landschaft canton concentrates analytical-grade consumable demand from global biopharma decision centers.
Laboratory Ware Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across certification tiers and material categories. The market structures around three player archetypes: vertically integrated resin-to-product pipelines, analytical-grade certification specialists, and regional fabrication networks serving standard-grade demand. Consolidation pressure concentrates in analytical-grade segments where documentation burdens favor scale. Dominant competitive moves include captive melting capacity expansion and pre-validated alternative polymer portfolio assembly.
Among diversified conglomerates with vertically integrated pipelines, Thermo Fisher Scientific and Merck KGaA exemplify archetypes absorbing regulatory compliance costs without margin erosion. Corning Incorporated anchors borosilicate glassware supply through captive melting operations spanning North America and Asia. These three entities represent distinct strategic positions: resin-to-product integration, certification program depth, and substrate-specific manufacturing scale.
| Leading Market Players |
|---|
| Agilent Technologies |
| Merck KGaA |
| Thermo Fisher Scientific |
| Sartorius |
| Eppendorf |
| Corning Incorporated |
| Avantor |
| PerkinElmer |
| DWK Life Sciences |
| Others |
Cost & Logistics Intelligence
CDMO procurement consolidation across United States, Germany, and China biopharma clusters is compressing vendor margins while expanding contract volumes, creating a pricing structure where analytical-grade certification commands substantial premiums over standard-grade alternatives. The dominance of group purchasing organizations in Shanghai, Suzhou, and Boston is shifting negotiation leverage toward buyers with multi-site harmonization requirements.
Pricing Analysis
Expedited lead-time premiums separate analytical-grade borosilicate glassware from standard inventory, with pharmaceutical quality control laboratories in Massachusetts and North Carolina paying material surcharges for thermal shock-resistant vessels meeting automated handling protocols. Three-tier pricing structure across analytical, USP, and reagent certification levels reflects documentation burden differentials, while resin cost volatility in fluoropolymer feedstocks is intensifying margin pressure for specialized molding operations serving environmental testing workflows. Academic institutions through group purchasing organizations exhibit highest price sensitivity; biopharma manufacturers with FDA container closure compliance mandates show lowest.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Shanghai, and Boston anchor hub-and-spoke patterns serving CDMO clusters with just-in-time replenishment. Manufacturing concentrates in United States, Germany, and China, with captive borosilicate melting operations in North America and Asia limiting third-party availability during capacity crunches. Supply chains draw from petrochemical feedstocks for fluoropolymer formulations and silica sand for glassware substrates. Single-source vulnerability around specialized resin grades poses structural risk. Distribution runs through authorized distributor networks with direct OEM relationships for analytical-grade certification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laboratory ware market is transitioning from open glassware to closed-system single-use polymer assemblies in cell therapy workflows, with fluoropolymer-coated glass hybrids displacing pure borosilicate in high-throughput screening applications.
For Market Incumbents: Cement analytical-grade certification depth as the primary defensive moat against resin-to-product integrators by expanding pre-validated alternative polymer portfolios ahead of ECHA per- and polyfluoroalkyl substance restrictions. Add captive melting capacity in India to serve Hyderabad and Bengaluru biopharma clusters before localized supply chains mature. For New Entrants and Emerging Players: Bio-based material certifications offer entry wedge into EU Green Deal circularity requirements, with sustainability-mandated take-back programs representing the most penetrable white-space in German analytical laboratory procurement. Target CDSCO-aligned manufacturing approvals in Telangana's Genome Valley with ISO 10993 pre-validated silicone assemblies for cell therapy closed-system contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional fabrication networks serving standard-grade demand in India and China, where NMPA and CDSCO harmonization is elevating documentation burdens faster than local compliance infrastructure can adapt. Watch biocompatibility testing backlog clearance rates as the inflection signal for specialized molding capacity utilization recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-validated Alternative Polymer Portfolio Assembly | ECHA REACH substance restrictions are forcing material requalification timelines that favor suppliers with compliant formulations ready for deployment. |
| Captive Borosilicate Melting Capacity Expansion | Corning's North American and Asian operations demonstrate how captive supply insulates against third-party availability crunches during demand surges. |
| ISO 10993 Biocompatibility Certification Investment | Cell therapy closed-system assemblies require validation that exceeds baseline regulatory thresholds in United States and EU markets. |
| Regional Distribution Center Localization | CDMO procurement consolidation in Shanghai and Suzhou clusters rewards suppliers with hub-and-spoke logistics anchored in Yangtze River Delta. |
| EU Green Deal Circular Economy Program | Take-back programs and bio-based material certifications differentiate vendors in German analytical laboratory procurement decisions. |
Research Approach
Document review covered FDA container closure guidance filings, ECHA SVHC candidate list expansions, and ISO 17025 accreditation standards, complemented by interviews with biopharma procurement directors, CDMO operations managers, analytical-grade certification specialists, and environmental testing laboratory compliance officers. Secondary validation drew from EPA Good Laboratory Practice documentation, NMPA manufacturing approval records, and customs data on fluoropolymer resin imports. Bottom-up consumable throughput modeling triangulated against top-down market sizing across material categories.
Historical volume trajectories cross-referenced against expert panel input on biologics manufacturing expansion rates shaped the analytical framework across the projection horizon. Segmentation dimensions included material substrate, certification grade tier, end-use application workflow, and regional regulatory cluster alignment. CAGRs derived from elasticity modeling against biopharma capital expenditure cycles and CDMO campaign frequency trends, with extractables and leachables testing capacity constraints factored as supply-side ceiling variables.
Several conditions sit outside the modeled scope, including unforeseen ECHA substance restriction accelerations, abrupt petrochemical feedstock price dislocations, and pandemic-scale disruptions to biopharma manufacturing continuity. Forecasts reflect documented assumptions on regulatory harmonization pace and CDMO clustering evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Paint Tester Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market