
 Hair Oil Market | 2026-2036
Hair Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Oil Market Analysis
Fragmentation across digital-native buyers is realigning how hair oil brands allocate marketing spend and distribution resources. Marico leverages its rural distribution depth to sustain volume leadership in coconut oil segments. L'Oreal S.A. competes through salon-exclusive treatment oils that command premium positioning. Dabur India Ltd anchors its portfolio with amla-based heritage formulations that dominate ayurvedic hair care shelves.
Hair oil comprises lipid-based formulations—typically triglyceride-rich vegetable oils, mineral oils, or essential oil blends—applied to hair shafts and scalps for moisturization, protection, and structural repair. Manufacturing involves cold-pressing or solvent extraction followed by refinement, with active botanical infusions requiring controlled temperature processing to preserve volatile compounds. Natural oil segments lead volume due to coconut and argan oil familiarity, while lightweight formulations represent the fastest-growing structural category as consumers reject heavy residue. Salon application channels capture disproportionate margin pools through professional-grade pricing and stylist recommendation authority.
India's BIS cosmetic standards mandate heavy metal limits and preservative disclosures that constrain formulation flexibility for domestic producers. EU REACH regulations and ECHA chemical safety classifications restrict certain mineral oil grades and synthetic fragrance components, forcing reformulation investments for export-oriented manufacturers. Stakeholders must monitor evolving clean-label certification schemes and ingredient blacklist expansions that will determine market access eligibility across major trade corridors.
Market Dynamics
Professional salon channels are consolidating recommendation authority, redirecting consumer purchase decisions toward treatment-grade formulations and compressing traditional retail margin structures for mass-market brands.
Growth Catalysts
- EU REACH chemical disclosure mandates:Ingredient transparency requirements are accelerating clean-label investments and opening premium positioning for brands with verifiable botanical sourcing.
- Coconut oil familiarity in South Asian households:Generational usage patterns sustain volume baselines while creating cross-selling opportunities for specialized scalp treatments.
- Cold-pressing equipment advances:Controlled-temperature processing preserves volatile active compounds, enabling functional claims that command price premiums in professional channels.
Market Restraints
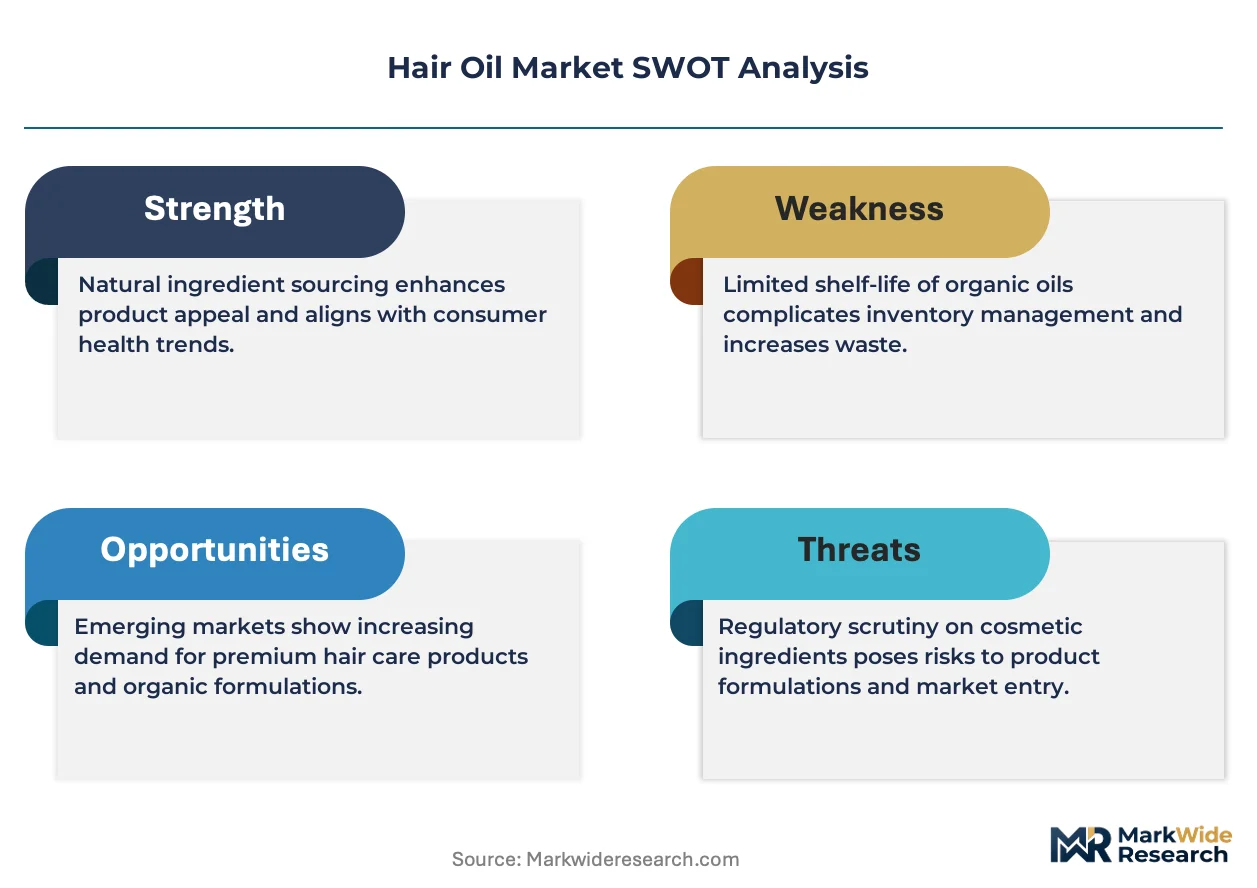
- Argan kernel supply concentration in Morocco:Single-origin dependency exposes formulations to harvest volatility and geopolitical logistics friction.
- BIS heavy metal testing costs:Domestic Indian producers face compliance expenditure that erodes margins on economy-tier products.
- Silicone serum substitution in styling routines:Instant-gratification hair care alternatives capture trial budgets from oil treatments requiring extended application time.
Strategic Opportunities
- Tier-2 Indian cities:Underpenetrated urban corridors beyond Mumbai and Delhi present whitespace for ayurvedic heritage brands with localized distribution partnerships.
- Direct-to-consumer subscription models:Recurring revenue structures bypass retail slotting fees and capture lifetime value from regimen-committed users.
- ECHA-approved upcycled ingredient streams:Circular economy certifications unlock sustainability positioning and preferential placement in EU clean-beauty retail.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging traditional ayurvedic knowledge and modern stability science commands premium compensation that strains R&D budgets.
- Multi-jurisdiction label harmonization:Divergent INCI disclosure requirements between BIS, FDA, and EU cosmetic regulations force SKU fragmentation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Oil Market |
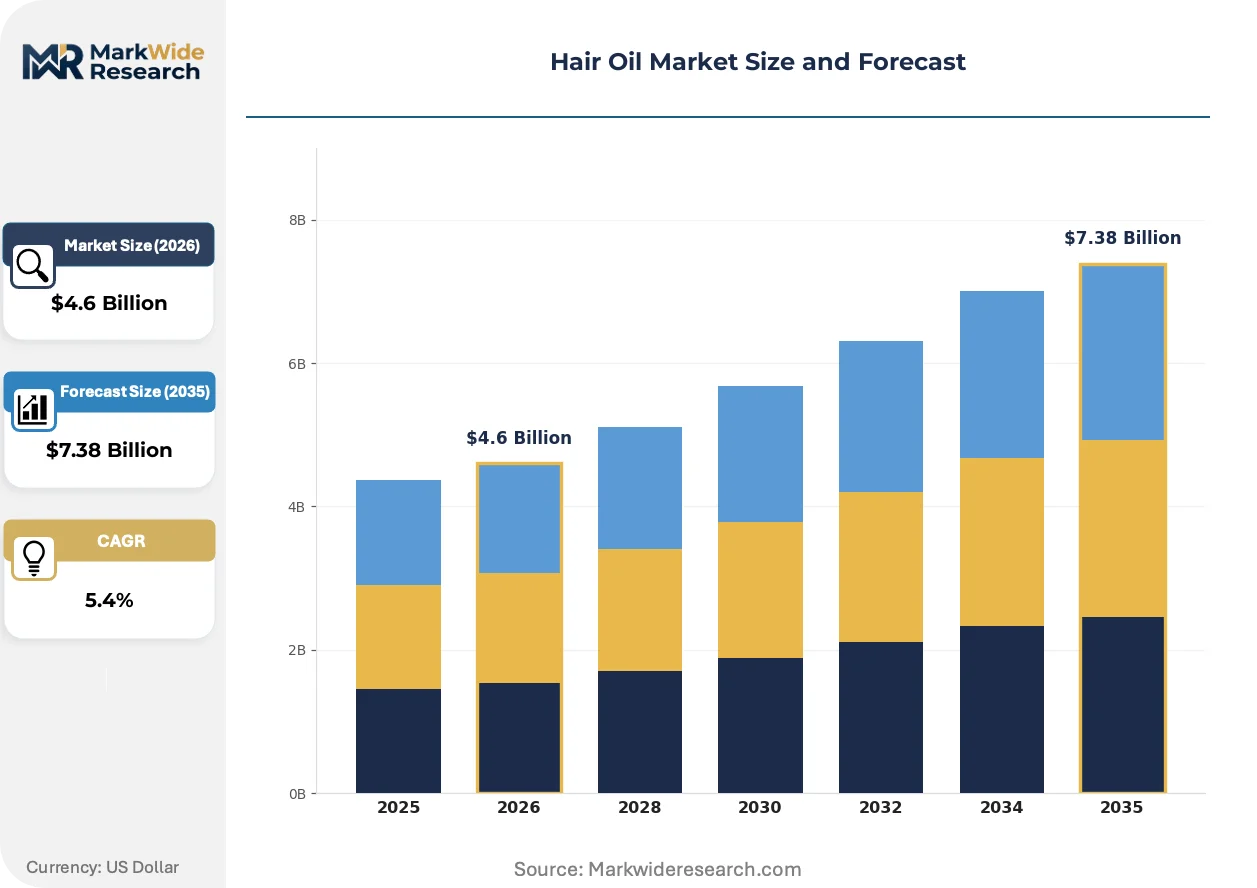
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $7.38 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Oil, Mineral Oil, Herbal Oil, Aromatherapy Oil Formulation: Lightweight, Heavyweight, Moisturizing, Non-Greasy Application: Hair Treatment, Styling, Split End Repair, Conditioning Customer Type: Salons, Retail Customers, Professionals, Online Shoppers |
| Companies Covered | Marico, Procter & Gamble, Dabur India Ltd, Patanjali Ayurved, Henkel AG, Emami Group, L'Oreal S.A., Coty Inc., Hindustan Unilever Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Oil Market Emerging Trajectories
Formulation science and channel economics are converging to redefine how hair oil products reach end users and justify price positioning through demonstrable performance claims.
Encapsulation technology is rewriting delivery efficiency benchmarks in scalp treatment formulations. Salon professionals in Seoul and São Paulo are adopting lipid nanoparticle systems that enhance active penetration without residue accumulation. This precision targeting is compressing the performance gap between home-use and in-clinic hair therapies.
India's BIS cosmetic safety standards are mandating preservative disclosure thresholds that exceed previous voluntary industry guidelines. Domestic manufacturers must reformulate legacy products or sacrifice retail shelf presence in organized trade. Export-oriented suppliers are consolidating testing protocols to satisfy simultaneous EU REACH and BIS compliance.
Stylists are becoming the primary purchase influencers for treatment-grade oils, displacing traditional advertising and retail merchandising. Salon-exclusive distribution locks in professional recommendation revenue streams that mass-market brands cannot replicate. This channel capture is most pronounced in Mumbai, Dubai, and Jakarta where appointment-based hair care consumption concentrates.
Hair Oil Market Segmentation
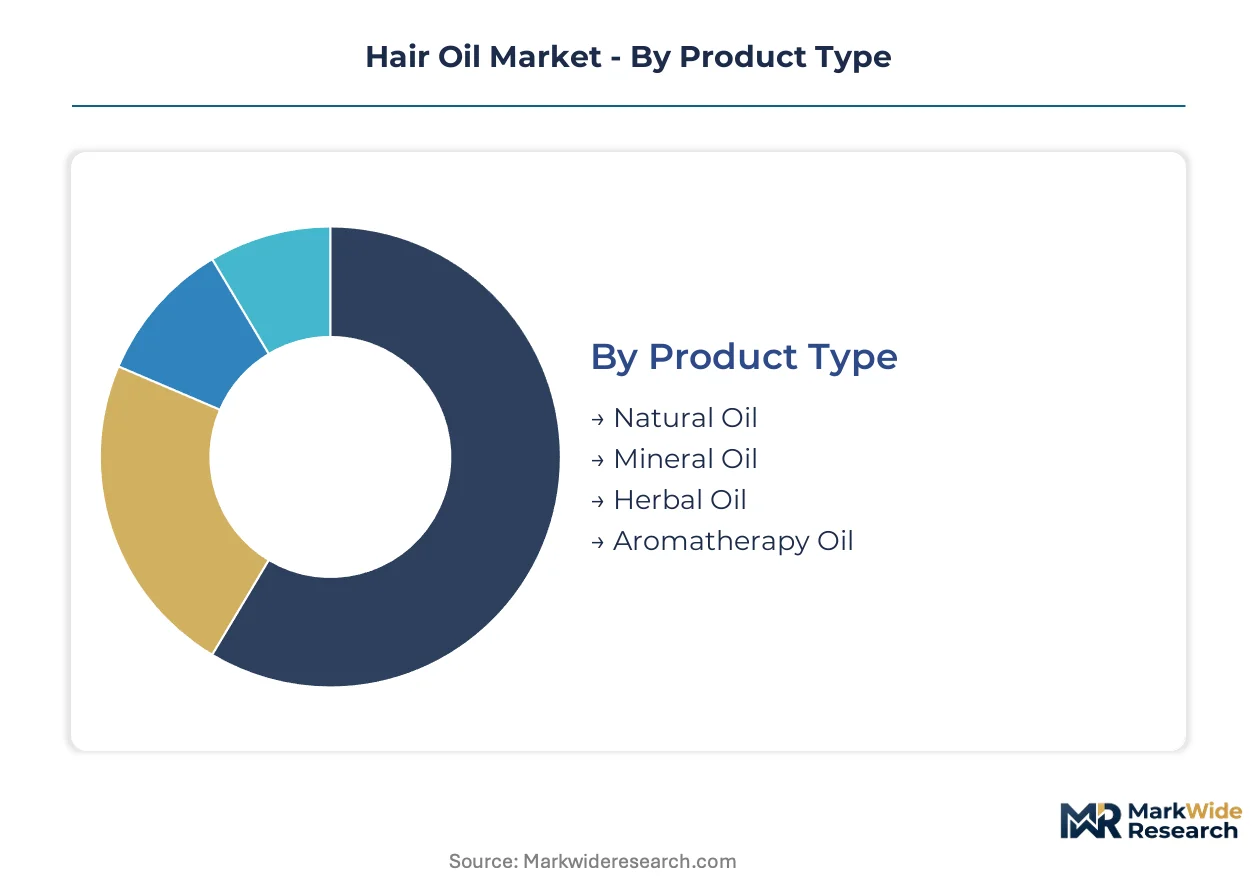
Hair oil manufacturers navigate divergent compliance pathways depending on segment positioning. Product chemistry determines whether BIS cosmetic standards, EU REACH disclosure mandates, or salon-grade professional certifications govern market access.
Product Type:
BIS heavy metal testing applies universally, though natural and herbal segments face additional botanical sourcing documentation under EU REACH.
- Natural Oil:Triglyceride-rich vegetable bases—coconut, argan, jojoba—require cold-pressed extraction documentation for clean-label positioning. Indian households sustain volume leadership through generational coconut oil usage, while Moroccan argan supply concentration creates procurement vulnerability for export-dependent brands.
- Mineral Oil:Refined petroleum distillates deliver occlusive barrier properties at economy price points. ECHA chemical safety classifications restrict certain grades in EU formulations, forcing reformulation investments or market exclusion for non-compliant producers.
- Herbal Oil:Ayurvedic infusions of amla, brahmi, and bhringraj demand preservative disclosure thresholds exceeding legacy industry guidelines. BIS mandates are compressing retail shelf presence for uncompliant domestic manufacturers.
- Aromatherapy Oil:Essential oil blends—lavender, rosemary, tea tree—target scalp wellness positioning with volatile compound preservation requirements.
Natural oil sits at the top of the volume ranking, with herbal oil climbing the fastest.
Formulation:
Processing temperature controls and emulsion stability science separate cost tiers, with lightweight systems commanding premium manufacturing investment.
- Lightweight:Lipid nanoparticle and microemulsion technologies enable rapid absorption without residue accumulation. Seoul and São Paulo salon professionals are adopting these systems for precision scalp targeting that bridges home-use and in-clinic performance.
- Heavyweight:Dense occlusive bases—castor oil, thick mineral oil blends—deliver overnight intensive treatment for damaged hair structures. Indian rural distribution networks sustain volume through economy positioning, though silicone serum substitution threatens trial budgets.
- Moisturizing:Humectant-oil hybrids combine glycerin or panthenol with lipid bases for hydration-locked styling preparation.
- Non-Greasy:Dry oil formulations using volatile silicones or fast-absorbing esters target male grooming and professional daytime use cases.
Heavyweight formulations retain the largest installed base, though lightweight systems are gaining share fastest through salon channel adoption.
Application:
End-use purpose determines channel economics, with treatment-grade applications capturing disproportionate margin pools through stylist recommendation authority.
- Hair Treatment:Therapeutic formulations targeting alopecia, dandruff, or chemical damage repair require clinical claim substantiation. Dubai and Jakarta appointment-based consumption concentrates demand for professional-grade treatment oils that mass-market brands cannot replicate.
- Styling:Pre-heat application and finishing serums compete directly with silicone-based alternatives for instant-gratification positioning.
- Split End Repair:Polymer-oil complexes seal cuticle fractures temporarily between trims, driving repeat purchase frequency.
- Conditioning:Rinse-out and leave-in detangling formulations compete with cream conditioners for shower shelf space.
Conditioning commands the broadest household penetration, with hair treatment expanding most quickly through professional channel capture.
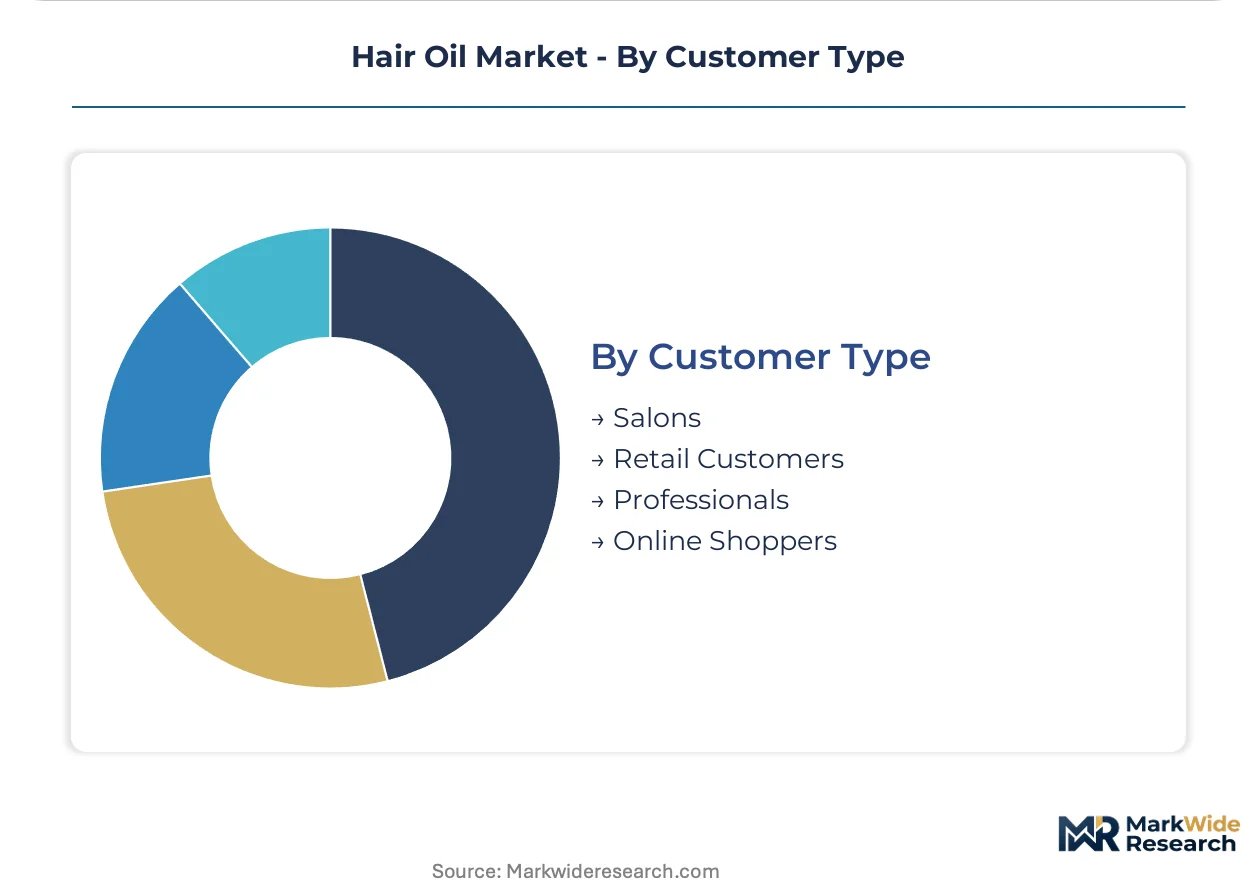
Customer Type:
Procurement authority and purchase frequency vary sharply across buyer categories, with subscription economics favoring direct-to-consumer models for regimen-committed users.
- Salons:Professional-exclusive distribution locks in stylist recommendation revenue streams. Mumbai salon clusters demonstrate concentrated appointment-based consumption where treatment-grade pricing authority exceeds retail margins.
- Retail Customers:Mass-market shelf presence depends on BIS-compliant labeling and organized trade slotting fees that erode economy-tier profitability.
- Professionals:Freelance stylists and trichologists purchasing bulk treatment supplies represent high-volume, price-sensitive procurement.
- Online Shoppers:Direct-to-consumer subscription models bypass retail intermediaries and capture lifetime value from ayurvedic heritage brand loyalists.
Retail customers generate the highest absolute transaction volume, with online shoppers following the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India commands heritage brand loyalty through ayurvedic formulations, while Brazil's salon culture drives professional-grade oil consumption. This contrast illustrates how cultural hair care traditions shape divergent market development trajectories across geographies.
India
Coconut oil generational usage sustains mass-market volume baselines, while urban millennials accelerate demand for natural scalp treatments. BIS cosmetic safety standards mandate heavy metal limits and preservative disclosures that constrain domestic formulation flexibility. Mumbai salon clusters concentrate appointment-based consumption where stylist recommendation authority redirects purchase decisions toward treatment-grade products.
United States
Clean-label certification schemes and ingredient transparency preferences open premium positioning for botanical-sourced formulations. FDA cosmetic regulations govern labeling claims while state-level disclosure laws in California exceed federal minimums. Los Angeles and New York metro areas host direct-to-consumer brand headquarters that bypass traditional retail intermediaries through subscription economics.
Brazil
São Paulo's dense salon network professionalizes hair oil application, compressing mass-market retail margins through stylist channel capture. ANVISA cosmetic regulations require stability testing documentation that elevates compliance costs for imported formulations. The city's appointment-based consumption concentrates disproportionate margin pools in treatment-grade professional products.
Germany
EU REACH chemical disclosure mandates and ECHA safety classifications restrict certain mineral oil grades, forcing reformulation investments for export-dependent producers. KBA and federal consumer protection standards reinforce ingredient blacklist expansions that determine retail access eligibility. Hamburg and Düsseldorf industrial clusters concentrate contract manufacturing capacity serving clean-beauty certification requirements.
Morocco
Argan kernel supply concentration exposes global formulations to harvest volatility and geopolitical logistics friction. The country's national standards body maintains geographic indication protections for argan oil exports that command price premiums in European and Asian markets. Casablanca processing facilities anchor the upstream supply chain for international cosmetic brands seeking provenance documentation.
Hair Oil Market Vendor Landscape
Indian producers anchor the heritage ayurvedic tier; European specialists hold salon-exclusive positioning through professional-grade certification. Market structure fragments across three competitive layers: mass-market volume leaders with rural distribution depth, premium treatment-grade brands capturing stylist recommendation revenue, and direct-to-consumer challengers exploiting subscription economics. Strategic archetypes include ayurvedic heritage houses, multinational salon-channel operators, and digital-native clean-label entrants. Dominant competitive moves encompass geographic expansion into underpenetrated tier-2 corridors and portfolio diversification toward lightweight formulation technologies.
Within the heritage ayurvedic tier, Marico and Dabur India Ltd exemplify volume leadership through rural distribution infrastructure and amla-based formulation dominance respectively. L'Oreal S.A. occupies a position representing multinational salon-channel specialization, leveraging professional recommendation authority to command premium pricing outside mass retail structures. These three anchors illustrate how competitive positioning stratifies across distribution model rather than product chemistry alone.
| Leading Market Players |
|---|
| Marico |
| Procter & Gamble |
| Dabur India Ltd |
| Patanjali Ayurved |
| Henkel AG |
| Emami Group |
| L'Oreal S.A. |
| Coty Inc. |
| Hindustan Unilever Limited |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in Morocco's argan processing sector anchor upstream supply discipline while compressing margin capture for downstream brands lacking captive sourcing. Sovereign-backed cooperatives in the Souss-Massa region enforce volume allocation protocols that tether international pricing to harvest cycles and export quota negotiations.
Pricing Analysis
Capacity additions in India's coconut crushing corridor are reshaping price floors for economy-tier natural oils while premium argan segments retain elevation through Moroccan geographic indication enforcement. Three-tier pricing structure across premium, standard, and economy levels separates salon-exclusive treatment formulations from mass retail coconut oils and unbranded bulk supply. Price differentiation rests on cold-press certification documentation and BIS heavy metal compliance tiering. Pricing pressure stems from silicone serum substitution in styling routines eroding trial budgets for extended-application oil treatments. Retail customers in organized trade exhibit highest price sensitivity; Mumbai salon clusters demonstrate lowest sensitivity due to stylist recommendation authority.
Supply Chain Analysis
Single-source vulnerability sits with Moroccan argan kernel supply exposing global formulations to harvest volatility and geopolitical logistics friction. Upstream concentration centers on Morocco, India, and Indonesia for argan, coconut, and palm-derived base oils respectively. Raw material dependencies draw from seasonal nut harvests, cold-pressing equipment availability, and botanical preservative sourcing. Supply chain risk manifests through regulatory restriction as EU REACH and BIS disclosure mandates force reformulation investments or market exclusion. Distribution runs through professional salon channels capturing disproportionate margin pools alongside traditional retail networks and accelerating direct-to-consumer subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's BIS compliance costs and Germany's ECHA certification premiums creates margin capture opportunities for dual-registered producers with consolidated testing protocols.
For Market Incumbents: Deepen backward integration into Moroccan argan cooperatives to secure volume allocation priority ahead of harvest volatility. Anchor salon-exclusive distribution in Mumbai and São Paulo clusters to lock in stylist recommendation revenue streams against silicone serum substitution threats. Invest in cold-pressing equipment advances to preserve volatile compound claims that command professional channel premiums. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable channel archetype for ayurvedic heritage formulations targeting regimen-committed urban millennials. Tier-2 Indian cities beyond Mumbai and Delhi present whitespace for localized distribution partnerships with ayurvedic credibility. Launch with lightweight lipid nanoparticle formulations bridging home-use and in-clinic performance claims to differentiate from incumbent heavy residue legacy products. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic Indian manufacturers facing BIS reformulation costs without export-oriented pricing power. Long-term viability across the analysis window favors dual-registered producers with simultaneous EU REACH and BIS compliance infrastructure already amortized. Target acquisition archetypes include ayurvedic heritage houses with underexploited tier-2 distribution and clean-label certification investments nearing completion. Watch ECHA ingredient blacklist expansions as the signal for preferential retail access eligibility inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Salon-Exclusive Distribution Lock-In | Mumbai and São Paulo stylist networks capture recommendation authority that mass retail cannot replicate. |
| Cold-Press Certification Investment | BIS and EU REACH documentation requirements elevate compliance costs that filter non-compliant competitors. |
| Direct-to-Consumer Subscription Launch | Recurring revenue structures bypass organized trade slotting fees and capture lifetime value from heritage brand loyalists. |
| Argan Cooperative Backward Integration | Moroccan geographic indication protections enforce provenance documentation that commands price premiums in European markets. |
| Lightweight Formulation R&D Pivot | Lipid nanoparticle technology bridges home-use and in-clinic performance gaps for Seoul and São Paulo salon adoption. |
Methodological Framework
Multiple input streams — primary interviews with formulation chemists and salon procurement heads, secondary validation through BIS filing databases and EU REACH registration dossiers, customs trade records — were reconciled to construct segment-level demand estimates. Conversations with brand managers at heritage ayurvedic houses, category buyers at organized retail chains, and technical directors at contract manufacturing facilities informed channel economics and pricing dynamics. Bottom-up volume aggregation across product type, formulation, and application segments was cross-checked against top-down macro consumption patterns.
Data-stream reconciliation applied analytical frameworks modeling natural versus mineral versus herbal oil chemistry pathways, lightweight versus heavyweight formulation absorption profiles, and salon versus retail versus online customer procurement behaviors throughout the forecast period. CAGRs were derived from trend extrapolation of generational usage patterns, urban millennial natural product preferences, and professional channel capture trajectories. Industry-specific forecast inputs incorporated BIS regulatory implementation timelines and ECHA chemical safety classification update cycles.
Revisions become necessary when Moroccan harvest volatility disrupts argan supply allocation, when silicone serum substitution accelerates beyond current trajectory assumptions, or when clean-label certification scheme expansions reshape retail access eligibility. Forecasts reflect documented assumptions about regulatory implementation pacing and channel migration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Hair Edge Tamer Market
Hair Care
Chile Hair Care Market
Hair Care
Australia Hair Care Market
Hair Care
Hair Clay Market
Hair Care
South Korea Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
Hair Care Market
Hair Care
Global Professional Hair Care Market
Hair Care
Professional Hair Care Products Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Artificial Hair Integration Market
Hair Care
Hair Dye Market
Hair Care
Canada Hair Care Market
Hair Care
Sweden Hair Care Market