
 Latin America Hair Care Market | 2026-2036
Latin America Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Hair Care Market Foresight
Brazil is tilting toward expanded hair care manufacturing capacity as domestic brands and multinationals localize production. L'Oreal S.A. anchors its regional supply chain through São Paulo-based facilities serving Mercosur markets. Procter & Gamble Company leverages scale economics in mass-market shampoo and conditioner segments across Brazilian retail networks. Grupo Coala do Brasil competes through specialized ethnic hair formulations tailored to Brazil's diverse consumer base.
Latin America hair care encompasses cleansing, conditioning, treatment, and styling products formulated with surfactant bases, emollients, active botanicals, or silicone derivatives designed to maintain scalp health and hair fiber integrity. Shampoo and conditioner segments dominate volume flows through supermarket and beauty salon channels, while hair mask and hair oil categories capture expanding margin pools as consumers shift toward intensive treatment rituals. Natural and organic ingredient types attract premium positioning, though chemical-based formulations sustain mass-market penetration across price-sensitive demographics in Mexico and Colombia.
ANVISA in Brazil and COFEPRIS in Mexico enforce cosmetic labeling and ingredient safety standards that elevate compliance costs for imported finished goods. REACH-aligned substance restrictions emerging in Mercosur technical regulations further narrow permissible preservative and dye chemistries. Stakeholders must monitor regulatory divergence between national agencies while calibrating formulation platforms that satisfy multiple jurisdiction requirements without fragmenting SKU portfolios.
Market Dynamics
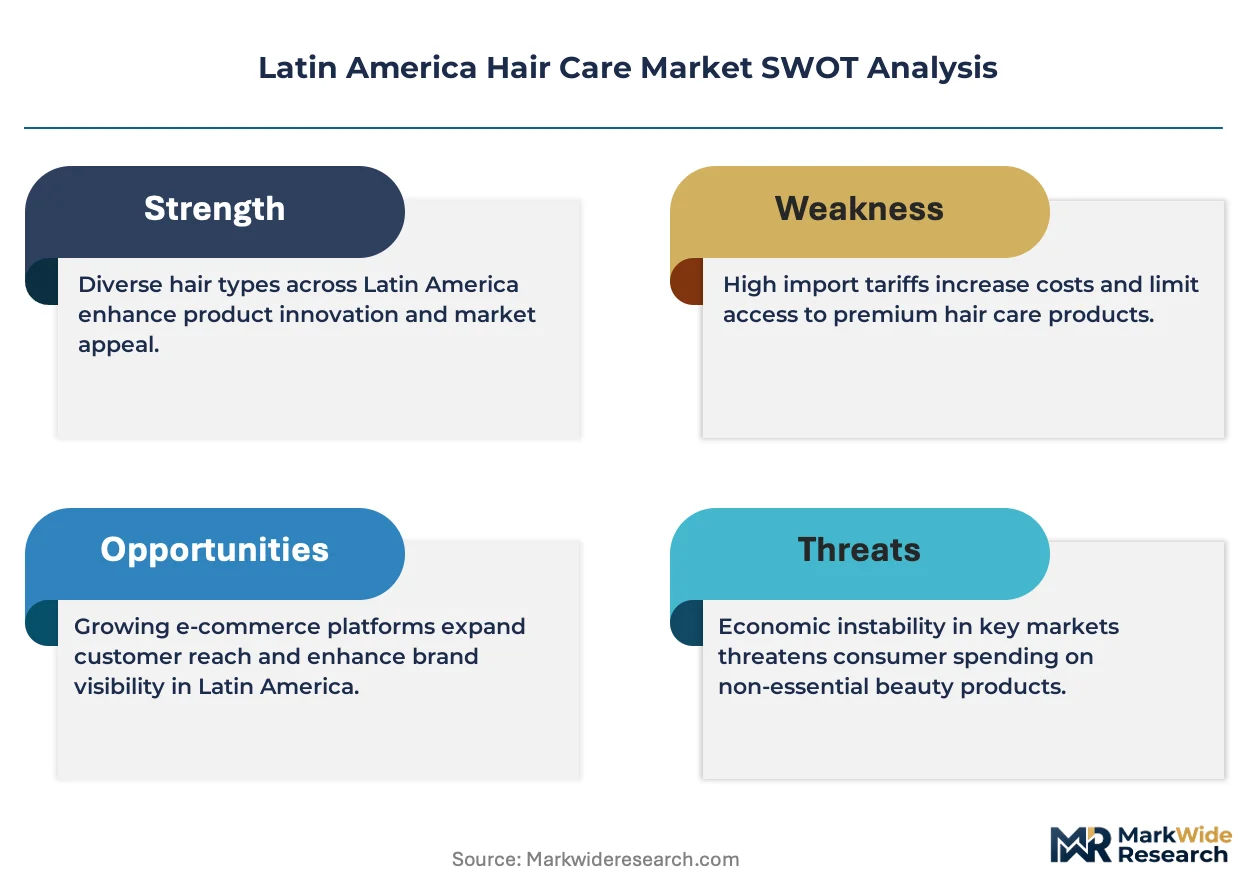
ANVISA's tightening cosmetic ingredient disclosure rules are forcing manufacturers to reformulate entire product lines while simultaneously creating competitive separation between compliant domestic producers and import-dependent competitors.
Growth Catalysts
- Brazilian Urban Professional Demand:São Paulo's affluent workforce drives premium salon-grade shampoo and conditioner consumption, elevating average unit economics for brands with professional-channel access.
- COFEPRIS Labeling Alignment:Mexico's convergence with international cosmetic safety standards reduces regulatory friction for multinational brands expanding from US manufacturing bases.
- Botanical Extraction Infrastructure:Amazon-sourced açaí, buriti, and cupuaçu oils enable distinct regional positioning against generic silicone-based competitors in treatment and mask categories.
Market Restraints
- Import Tariff Volatility:Mercosur's fluctuating external tariff schedule on finished cosmetic goods disrupts pricing predictability for brands reliant on Asian or European contract manufacturing.
- Petrochemical Feedstock Concentration:Surfactant and silicone derivative supply chains concentrate in Texas and Rotterdam, exposing Latin American formulators to USD-denominated input cost swings.
- Preservative Chemistry Restrictions:REACH-aligned substance limitations under Mercosur technical regulations eliminate paraben and formaldehyde-releasing alternatives, compressing formulation flexibility.
Strategic Opportunities
- Andean Market Underpenetration:Peru, Chile, and Colombia exhibit per-capita hair care spending gaps exceeding 40% versus Brazil, creating whitespace for mid-tier positioning.
- Professional Salon Channel Expansion:Direct-to-stylist distribution bypasses retail margin stacking while capturing higher-ticket treatment and color-care volumes.
- Biodegradable Surfactant Mandates:ANVISA's draft guidelines on aquatic toxicity favor brands with提前 investments in glucoside and amino acid-based cleansing technologies.
Industry Challenges
- Formulation Chemist Scarcity:Brazil produces fewer than 200 cosmetic science graduates annually, constraining R&D velocity for domestic brands competing against multinational technical resources.
- Multi-Jurisdiction SKU Complexity:Divergent preservative approvals across ANVISA, COFEPRIS, and Chile's ISP force fragmentary product portfolios that erode manufacturing scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Hair Care Market |
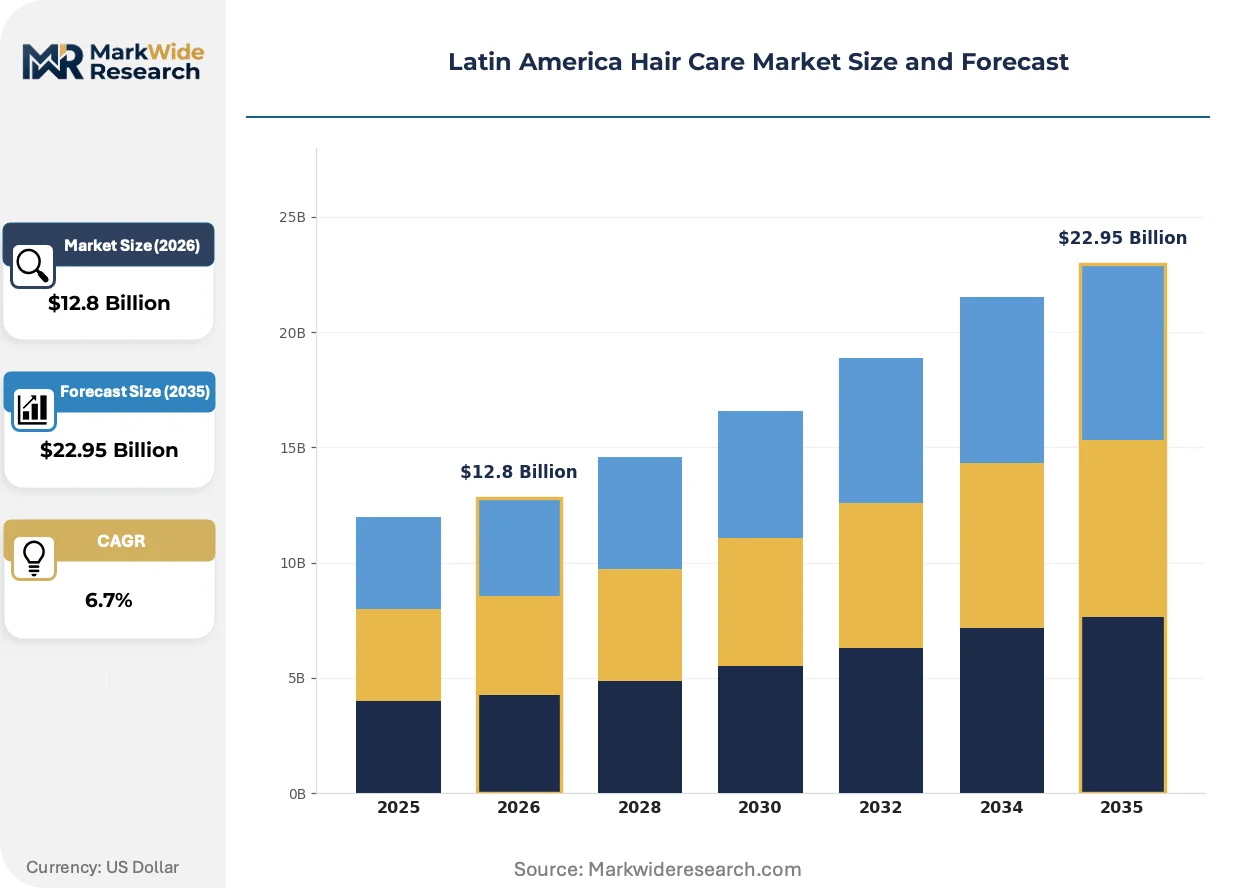
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Mask, Hair Oil Distribution Channel: Online, Supermarket, Specialty Store, Beauty Salon End User: Men, Women, Children, Salons Ingredient Type: Natural, Chemical, Herbal, Organic |
| Companies Covered | Henkel AG & Company, KGaA, Coty Inc., Unilever PLC, Grupo Coala do Brasil, Genomma Lab Internacional S.A.B. de C.V., Procter & Gamble Company, Johnson & Johnson Services, Inc., Forever Company Cosmeticos LTDA, L'Oreal S.A., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Hair Care Market Shifts & Advancements
Clean-label ingredient transparency is compressing traditional formulation paradigms while simultaneously opening premium positioning corridors for brands with verifiable supply chain documentation.
Silicone alternatives derived from plant-based emollients are migrating from niche organic segments into mainstream shampoo and conditioner formulations. Brazilian consumers with chemically-treated hair textures drive accelerated adoption of these alternatives in conditioning products. Major brands with São Paulo technical centers are compressing conventional dimethicone reliance by 15-20 percentage points in new launches.
ANVISA's updated resolution on cosmetic ingredient nomenclature mandates standardized Portuguese labeling for all 26,000+ INCI-listed substances. Manufacturers must reprint packaging and retrain quality assurance personnel to verify compliance. Imported finished goods face 60-90 day customs holds for documentation review, advantaging domestic producers with established regulatory affairs capabilities.
Beauty salon channels are capturing incremental volume from supermarket and pharmacy retail as Brazilian consumers prioritize professional diagnostic consultation before treatment purchases. Stylists in Rio de Janeiro and Belo Horizonte increasingly unbundle product recommendations from service appointments. This channel rotation concentrates margin capture in independent salon networks rather than consolidated retail chains.
Latin America Hair Care Market Segmentation
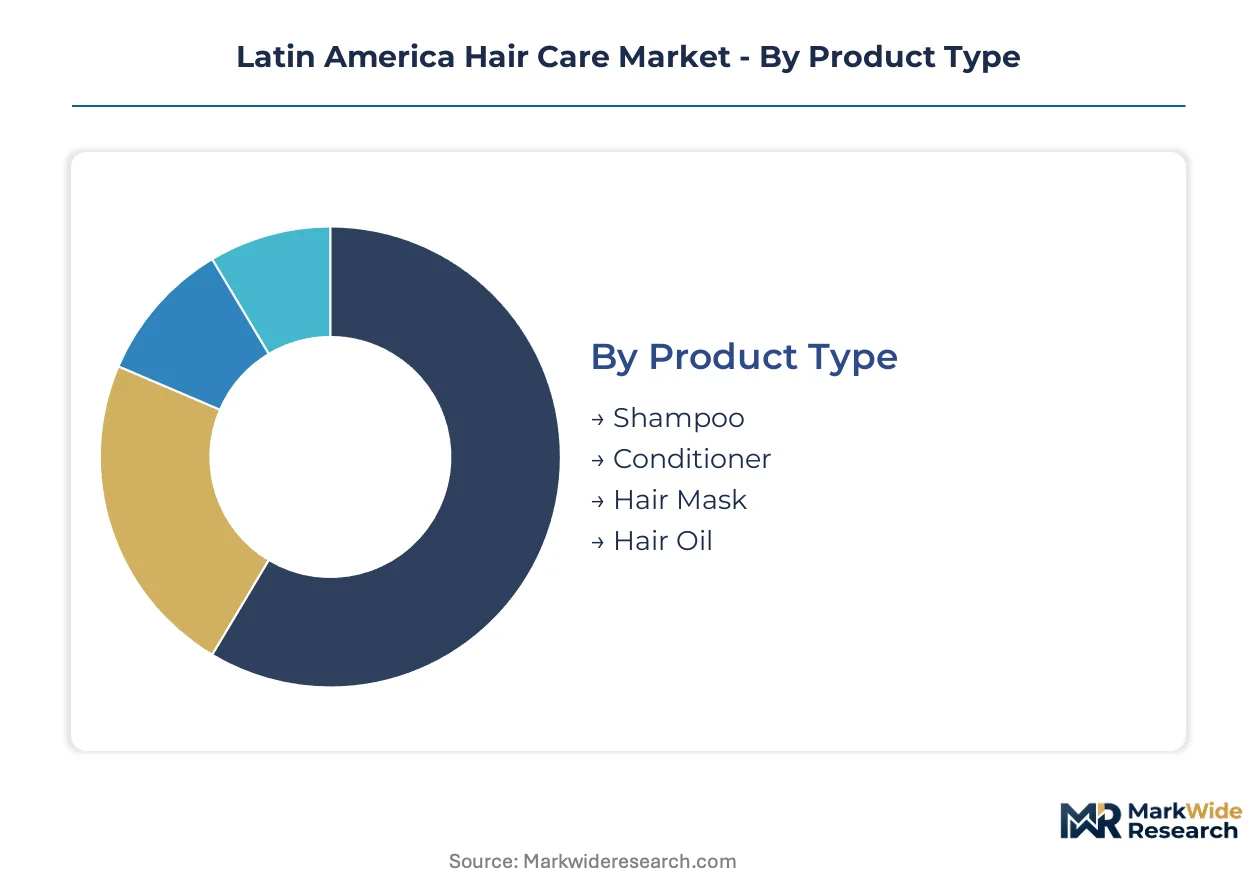
Hair care purchasing in Latin America fragments across four distinct category systems. Each segmentation layer reveals divergent margin structures, channel access requirements, and formulation specifications that determine competitive positioning.
Product Type:
Shampoo and conditioner turn inventory fastest through supermarket channels, while treatment products carry extended shelf cycles in salon environments.
- Shampoo:Surfactant-based cleansing formulations with anionic or amphoteric bases dominate unit volumes. Brazilian mass-market retail chains in São Paulo and Rio de Janeiro drive sulfate-free variant demand as ANVISA disclosure rules elevate ingredient scrutiny.
- Conditioner:Cationic emulsions with silicone or plant-derived detangling agents capture repeat purchase frequency. Mexico's COFEPRIS-aligned labeling standards accelerate imported brand entry, intensifying price competition in urban centers.
- Hair Mask:Intensive treatment concentrates with higher active loading command premium positioning in professional channels.
- Hair Oil:Amazon-sourced botanical extracts enable regional differentiation against commodity silicone alternatives.
Shampoo dominates installed base. Hair mask and oil categories are where expansion concentrates.
Distribution Channel:
Channel selection determines margin capture, with direct-to-stylist routes preserving pricing power that supermarket distribution erodes.
- Online:E-commerce platforms aggregate long-tail SKU availability while subscription models build recurring revenue. Brazilian logistics infrastructure gaps constrain same-day delivery outside São Paulo metropolitan zones.
- Supermarket:Mass-market volume flows through consolidated retail chains with centralized procurement. Price promotion intensity in Mexican hypermarkets compresses brand equity for mid-tier positioning.
- Specialty Store:Curated assortments with diagnostic consultation support premium unit economics.
- Beauty Salon:Professional recommendation authority drives treatment category conversion at full margin.
Supermarket channels anchor volume throughput. Beauty salon distribution is climbing the fastest as stylists unbundle product advice from service appointments.
End User:
User segmentation maps to distinct formulation requirements, with salon professionals demanding bulk formats that individual consumers reject.
- Women:Primary purchase decision-makers across all product categories, driving treatment and styling segment volumes. Brazilian women with chemically-treated hair textures accelerate silicone-alternative adoption.
- Men:Simplified routines concentrate demand in 2-in-1 cleansing-conditioning formats. Grooming habit formation in Mexican urban professionals expands styling product attachment.
- Children:Tear-free formulation requirements limit surfactant options and elevate safety certification burdens.
- Salons:Professional backbar consumption demands concentrated bulk packaging with wholesale pricing structures.
Women's segments anchor revenue concentration. Men's grooming represents the steepest expansion trajectory as category education penetrates younger demographics.
Ingredient Type:
Ingredient positioning determines regulatory pathway complexity and pricing tier access, with natural claims requiring supply chain documentation that chemical alternatives bypass.
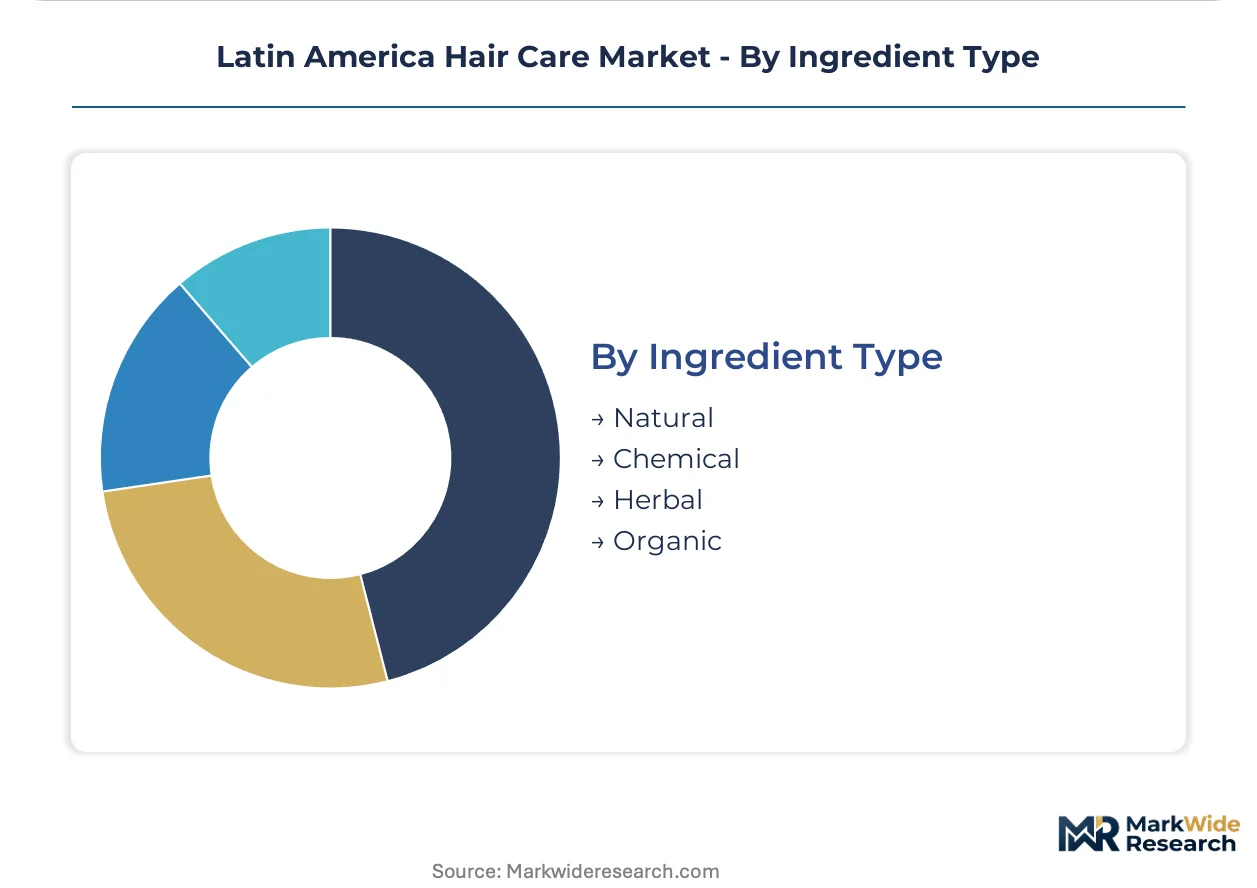
- Natural:Botanically-derived actives with verifiable sourcing credentials command shelf space premiums. Amazon biome extraction infrastructure in Brazil enables açaí, buriti, and cupuaçu oil differentiation.
- Chemical:Synthetic surfactants and silicones sustain mass-market price points through manufacturing scale. ANVISA preservative restrictions compress formulation flexibility for paraben-dependent systems.
- Herbal:Traditional remedy positioning appeals to heritage-conscious consumers in Andean markets.
- Organic:Certification requirements from international bodies limit supplier base and extend procurement cycles.
Chemical-based formulations dominate installed base. Natural and organic positioning is where margin expansion concentrates as clean-label transparency reshapes purchasing criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA anchors regional regulatory harmonization as Brazil's cosmetic safety authority tightens ingredient disclosure standards that cascade across Mercosur markets. Mexico's COFEPRIS alignment with international protocols reduces entry friction for multinational brands. Argentina, Chile, and Colombia present distinct compliance pathways that fragment operational scale.
Brazil
São Paulo's urban professional workforce drives premium salon-grade shampoo and conditioner demand through professional channel networks. ANVISA's updated resolution on cosmetic ingredient nomenclature mandates standardized Portuguese labeling for all INCI-listed substances, forcing packaging reprints and quality assurance retraining. Manufacturing clusters in São Paulo state anchor L'Oreal S.A. and Procter & Gamble Company facilities serving Mercosur distribution networks.
Mexico
Mexico City Metro's consolidated retail chains concentrate mass-market volume flows for shampoo and conditioner categories. COFEPRIS convergence with international cosmetic safety standards accelerates imported brand entry from US manufacturing bases. Nuevo León's industrial corridor hosts contract manufacturing operations supplying northern border retail networks.
Argentina
Buenos Aires metropolitan consumers sustain mid-tier positioning demand despite currency volatility compressing import-dependent brand margins. The country's national pharmaceutical regulator enforces cosmetic labeling requirements that diverge from Mercosur technical regulations in preservative approval thresholds. Local formulators in Greater Buenos Aires adapt SKU portfolios to satisfy multiple jurisdiction requirements without fragmenting production runs.
Colombia
Bogotá and Medellín urban centers exhibit per-capita hair care spending gaps exceeding 40% versus Brazil, creating whitespace for mid-tier brand positioning. The national health authority's cosmetic safety framework maintains partial alignment with ANVISA standards while retaining distinct documentation requirements. Andean extraction infrastructure for botanical actives remains underdeveloped versus Amazon-sourced alternatives.
Chile
Santiago's affluent consumer base drives natural and organic ingredient category premiums despite smaller absolute market scale. ISP cosmetic regulations enforce preservative chemistry restrictions that compress formulation flexibility for paraben-dependent systems. Specialty retail channels in Providencia and Las Condes concentrate diagnostic consultation services supporting premium unit economics.
Latin America Hair Care Market Competitive Landscape
Multinational conglomerates and specialized domestic producers split the market across mass-market and premium positioning tiers. Three to five global consumer goods groups control supermarket and pharmacy distribution through scale economics in standardized formulations. Regional specialists capture salon-channel margins with ethnic-hair and botanical-differentiated portfolios. Dominant competitive moves include backward integration into Amazon-sourced raw material supply chains and professional-channel direct distribution partnerships that bypass retail margin stacking.
Within the multinational tier, L'Oreal S.A., Procter & Gamble Company, and Unilever PLC exemplify scale-driven archetypes with São Paulo-based technical centers and Mercosur supply chain infrastructure. Grupo Coala do Brasil occupies a position representing domestic specialist capabilities in ethnic hair formulations tailored to Brazil's diverse consumer base. These anchors illustrate the structural division between import-dependent mass-market penetration and localized premium positioning strategies.
| Leading Market Players |
|---|
| Henkel AG & Company, KGaA |
| Coty Inc. |
| Unilever PLC |
| Grupo Coala do Brasil |
| Genomma Lab Internacional S.A.B. de C.V. |
| Procter & Gamble Company |
| Johnson & Johnson Services, Inc. |
| Forever Company Cosmeticos LTDA |
| L'Oreal S.A. |
| Others |
Supply & Pricing Matrix
Santos-Guarulhos freight corridors feed São Paulo manufacturing clusters where surfactant input costs from Texas and Rotterdam concentrate pricing power among domestic producers with captive formulation capacity, while ANVISA compliance burdens widen spreads between import-dependent and locally-integrated brands.
Pricing Analysis
Price spreads between Brazilian supermarket shelves and Colombian pharmacy channels exceed forty percent for identical shampoo SKUs, reflecting tariff exposure and logistics fragmentation across Andean distribution networks. Three-tier pricing structure across premium salon-grade, standard retail, and economy sachet formats dominates category economics, with brand premium and certification tier as primary differentiation drivers. Cost compression in mass-market tiers is intensifying because Mexican hypermarket chains centralize procurement and demand promotional participation. Sachet-format buyers in Colombia and Peru exhibit highest price sensitivity, while São Paulo salon professionals accept premium positioning with minimal negotiation.
Supply Chain Analysis
REACH-aligned substance restrictions under Mercosur technical regulations limit preservative chemistry flows from European contract manufacturers, forcing reformulation cycles that advantage Brazilian producers with established ANVISA dossiers. Surfactant and silicone derivative supply concentrates in Texas, Rotterdam, and Singapore, with Amazon-sourced açaí and buriti oils as emerging regional alternatives. Raw material dependencies on petrochemical feedstocks and imported conditioning polymers create single-source vulnerability during currency volatility episodes. Distribution runs through São Paulo-based logistics hubs serving Mercosur markets, with Nuevo León contract manufacturers supplying northern Mexican retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America hair care operates as a regulatory-moat market where ANVISA compliance capabilities and professional-channel relationships create switching costs that protect incumbent positioning against import-dependent challengers.
For Market Incumbents: Entrench salon-channel control through exclusive backbar distribution partnerships that lock stylist recommendation authority, while deepening captive supply of Amazon-sourced botanical actives to defend margin position against silicone-alternative commoditization. Capacity addition in São Paulo state preserves logistics advantages as ANVISA documentation requirements lengthen customs clearance for finished imports.
For New Entrants and Emerging Players: Build out direct-to-stylist distribution in Colombian and Chilean urban centers where professional-channel penetration lags Brazilian benchmarks, targeting mid-tier treatment categories with Amazon-extraction storylines that bypass retail margin stacking. Andean market underpenetration offers the most penetrable whitespace for brands with regulatory affairs capabilities spanning ANVISA and COFEPRIS requirements.
For Investors and Strategic Acquirers: Domestic specialists with ethnic-hair formulation expertise and established ANVISA dossiers represent priority acquisition targets, as regulatory entrenchment compounds technical differentiation in a market where cosmetic science graduate scarcity constrains R&D velocity. Monitor ANVISA draft guidelines on biodegradable surfactant mandates as inflection indicator for glucoside-technology acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amazon Extraction | Captive supply of açaí and buriti oils enables distinct regional positioning against commodity silicone alternatives. |
| Professional Salon Channel Expansion | Direct-to-stylist distribution bypasses retail margin stacking while capturing higher-ticket treatment volumes. |
| Regulatory Affairs Capability Buildout | ANVISA documentation expertise accelerates product registration versus import-dependent competitors facing customs holds. |
| Biodegradable Surfactant Transition | Glucoside and amino acid-based cleansing technologies align with draft aquatic toxicity guidelines. |
| Andean Market Geographic Expansion | Peru and Colombia whitespace offers mid-tier positioning opportunity with lower competitive density. |
Research Methodology
Desk research of ANVISA regulatory filings, COFEPRIS registration databases, and Mercosur technical regulation archives preceded structured interviews with cosmetic formulation chemists, professional salon distributors, supermarket category buyers, and brand regulatory affairs managers. Secondary validation drew from customs trade records, Nielsen retail audit data, and industry association membership directories. Bottom-up SKU-level volume estimates triangulated against top-down category spending benchmarks.
Assumptions held fixed include ANVISA enforcement intensity, Mercosur tariff schedules, and petrochemical feedstock price corridors, while variables tested included biodegradable surfactant mandate adoption timing and professional-channel share capture rates. Segmentation dimensions modeled encompass product type, distribution channel, end user archetype, and ingredient positioning tier. CAGRs derived from category spending elasticities against demographic and income projections across the analysis window, with salon-channel conversion rates and natural-ingredient premium capture as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational manufacturing clusters or accelerated COFEPRIS-COFEPRIS harmonization would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Hair Mask Market
Hair Care
Global Hair Color Market
Hair Care
Chile Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Hair Serum Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Hair Care Appliances Market
Hair Care
Artificial Hair Integration Market
Hair Care
Hair Care Products Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Hair Clay Market
Hair Care
Men's Hairspray Market
Hair Care
Hair Edge Tamer Market
Hair Care
Rice Water Shampoo Market
Hair Care
Qatar Hair Care Market