
 Hair Care Products Market | 2026-2036
Hair Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Care Products Market Outlook
Mass retail and e-commerce distribution is fragmenting as direct-to-consumer platforms and specialized subscription boxes capture younger demographics. L'Oréal sustains its position through upstream control over active ingredient supply chains. Procter & Gamble leverages massive manufacturing scale to dominate entry-level shampoo and conditioner segments. Unilever differentiates via geographic diversification across emerging and mature markets simultaneously.
Hair care products encompass formulations designed to cleanse, condition, protect, or modify hair fiber structure, typically containing surfactants, emollients, proteins, and functional actives at pH ranges between 4.5 and 6.5 to maintain cuticle integrity. Their primary commercial purpose centers on consumer grooming maintenance, aesthetic enhancement, and damage mitigation from thermal or chemical stress. Shampoo retains the largest volume share but generates thinner margins than hair oil and mask treatments positioned as intensive repair solutions. Natural and organic ingredient types are expanding fastest as clean-label preferences reshape procurement patterns across salon and retail channels.
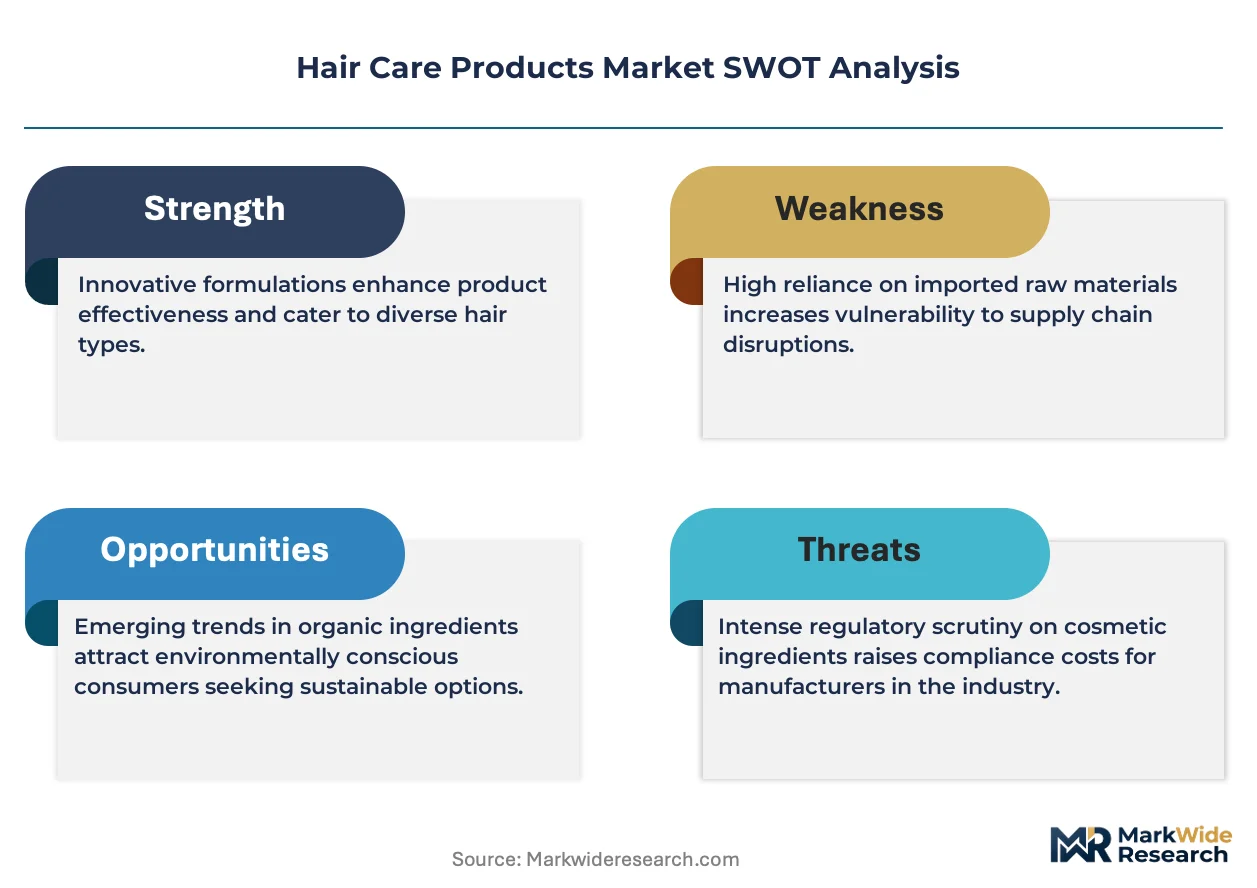
The FDA oversees cosmetic safety labeling and ingredient disclosure requirements in the United States, while REACH governs chemical substance authorization across European manufacturing and import flows. India's BIS certification mandates product quality benchmarks for imported and domestically produced formulations, creating compliance costs that favor established multinationals over local entrants. Stakeholders must monitor evolving preservative bans and biodegradability standards that will determine which ingredient portfolios retain market access across major economies.
Market Dynamics
Professional salon channels are absorbing premium formulations as service-based hair treatments expand, while REACH chemical restrictions redirect R&D budgets toward compliant ingredient portfolios across European manufacturing flows.
Growth Catalysts
- EU REACH Framework:Restrictions on certain chemical preservatives accelerate reformulation investments toward biodegradable surfactants and plant-derived actives. Manufacturers with early compliance capture shelf space as retailers preempt enforcement.
- Urbanization in India:Rising disposable incomes elevate daily hair care routines into specialized regimens spanning pre-wash oils, bond-building treatments, and scalp-focused serums. Metro markets drive per-capita consumption multiples above rural benchmarks.
- Biotechnology-enabled proteins:Fermentation-derived keratin analogs and peptide complexes replace animal-sourced ingredients, unlocking clean-label positioning without performance trade-offs.
Market Restraints
- Palm oil and coconut oil volatility:Input cost swings compress margin stability for mass-market shampoo and conditioner portfolios dependent on tropical agricultural supply chains.
- Preservative approval timelines:ECHA's prolonged safety assessments for novel biocidal actives delay product launches by 18-36 months versus conventional chemistries.
- Waterless format substitution:Solid shampoo bars and powder concentrates threaten liquid format volume in environmentally conscious consumer segments.
Strategic Opportunities
- Direct-to-consumer subscriptions:Personalized regimens based on diagnostic quizzes and recurring delivery models capture younger demographics outside traditional retail.
- India BIS certification:Compliance infrastructure investments by multinationals create barriers against unorganized local competitors in premium tiers.
- Scalp microbiome science:Convergence of dermatological research and cosmetic formulation opens clinical-positioning white space between pharmaceutical and beauty channels.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise bridging cosmetic science and regulatory toxicology commands premium compensation, constraining mid-tier manufacturer expansion.
- Legacy ERP integration:Batch manufacturing execution systems require costly retrofitting to support mass-customization and traceability demands from clean-label retailers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Care Products Market |
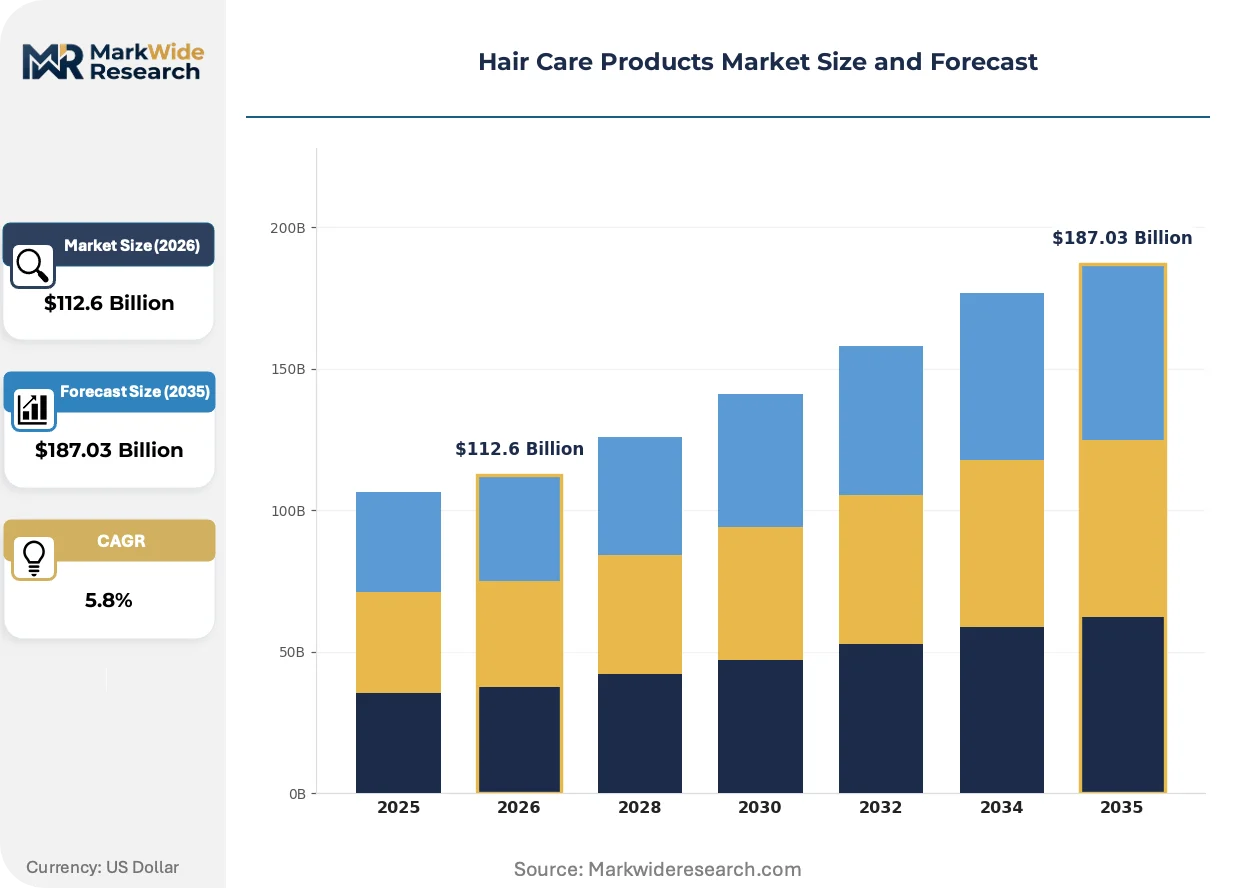
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $187.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Hair Mask Ingredient Type: Natural, Organic, Chemical, Synthetic Application: Damage Repair, Moisturizing, Styling, Color Protection End User: Women, Men, Children, Salons |
| Companies Covered | L'Oréal, Procter & Gamble, Unilever, Henkel, The Estée Lauder Companies, Kao Corporation, Johnson & Johnson, Shiseido, Coty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Care Products Market Strategic Shifts
Active ingredient transparency and biotechnology-derived replacements are compressing traditional supply chain advantages while reshaping procurement criteria across salon and retail channels.
Biotechnology-derived proteins and peptides are collapsing the performance gap between synthetic and naturally sourced conditioning actives. Salon professionals and prestige brands adopt fermentation-derived alternatives at accelerated pace as consumer skepticism toward animal sourcing hardens. This shift compresses margins for conventional specialty chemical suppliers while rewarding vertically integrated biotech platforms with captive manufacturing.
REACH authorization requirements for chemical substances govern manufacturing and import flows across European markets, with downstream effects on global formulation standards. The industrial consequence forces multinational portfolios toward unified ingredient lists that satisfy the strictest jurisdiction. Hair mask and treatment categories face disproportionate impact given their higher active loadings and preservative complexity.
Subscription-based personalization models disrupt traditional retail replenishment cycles by locking consumers into algorithm-curated regimens. Direct-to-consumer platforms and specialized boxes displace mass-market aisle browsing among demographics under 35. This pattern concentrates most visibly in US and UK metropolitan markets where delivery infrastructure and digital payment penetration support seamless recurring commerce.
Hair Care Products Market Segmentation
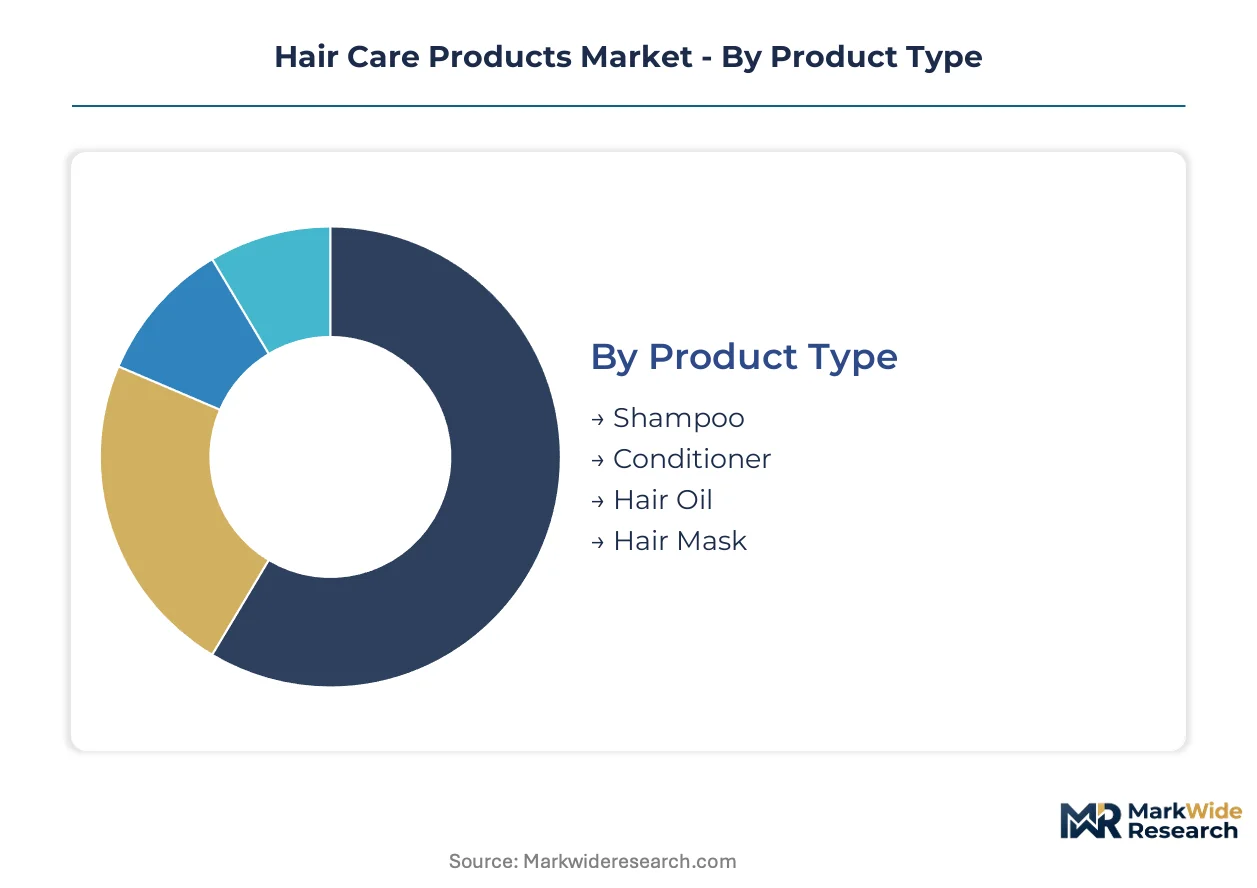
Segmentation in hair care reveals how formulation chemistry, distribution channel, and demographic targeting fragment purchasing behavior. Manufacturers configure R&D and marketing investments differently across these dimensions, with ingredient sourcing and end-user channel commanding disproportionate strategic attention.
Product Type:
Volume concentration across the four product categories reflects usage frequency, margin structure, and salon channel penetration depth.
- Shampoo:Surfactant-based cleansing formulations operate at pH 4.5-6.5 to preserve cuticle integrity while removing sebum and environmental residue. Daily consumption in Indian metro markets sustains the largest absolute volume position, though per-unit margins compress against treatment-grade alternatives.
- Conditioner:Cationic surfactant and silicone emulsion systems deposit conditioning films onto the hair shaft. Professional salon channels in Germany and France absorb premium silicone-free and bond-building variants as service-based treatments expand.
- Hair Oil:Pre-wash lipid treatments with coconut, argan, or fermented oil bases. Indian BIS certification requirements favor established multinationals over local entrants in premium tiers.
- Hair Mask:Intensive conditioning treatments with higher active loadings and extended contact times. REACH preservative restrictions disproportionately impact this category given its formulation complexity.
Shampoo holds installed capacity. Hair mask is rotating up the share rankings.
Ingredient Type:
Procurement patterns across the four ingredient classifications are compressing traditional supply chain advantages while reshaping retailer acceptance criteria.
- Natural:Plant-derived actives including botanical extracts and cold-pressed oils without synthetic modification. Clean-label preferences in US direct-to-consumer channels accelerate SKU proliferation.
- Organic:Certified cultivation and processing standards with third-party verification. EU REACH framework restrictions on certain chemical preservatives redirect R&D budgets toward compliant organic portfolios.
- Chemical:Conventional synthetic surfactants, silicones, and preservative systems. ECHA's prolonged safety assessments for novel biocidal actives delay product launches versus conventional chemistries.
- Synthetic:Laboratory-engineered polymers and conditioning agents. Biotechnology-enabled fermentation-derived alternatives are displacing petroleum-based synthetics in prestige brand formulations.
Natural ingredient processing holds installed capacity. Organic certification is rotating up the share rankings.
Application:
Functional positioning across the four benefit platforms determines pricing architecture and channel placement strategy.
- Damage Repair:Protein-enriched and bond-building formulations targeting chemically treated or thermally stressed hair. Biotechnology-derived keratin analogs replace animal-sourced ingredients for clean-label positioning.
- Moisturizing:Humectant and emollient systems addressing dryness from environmental exposure or over-cleansing. Subscription-based personalization models capture younger demographics with diagnostic-driven regimen curation.
- Styling:Fixative polymers, texturizers, and shaping agents. Solid format substitution threatens liquid styling product volume in environmentally conscious UK and US consumer segments.
- Color Protection:UV filters and antioxidant systems preserving artificial pigment deposition. Professional salon channels absorb premium formulations as color service frequency rises.
Moisturizing holds installed capacity. Damage repair is rotating up the share rankings.
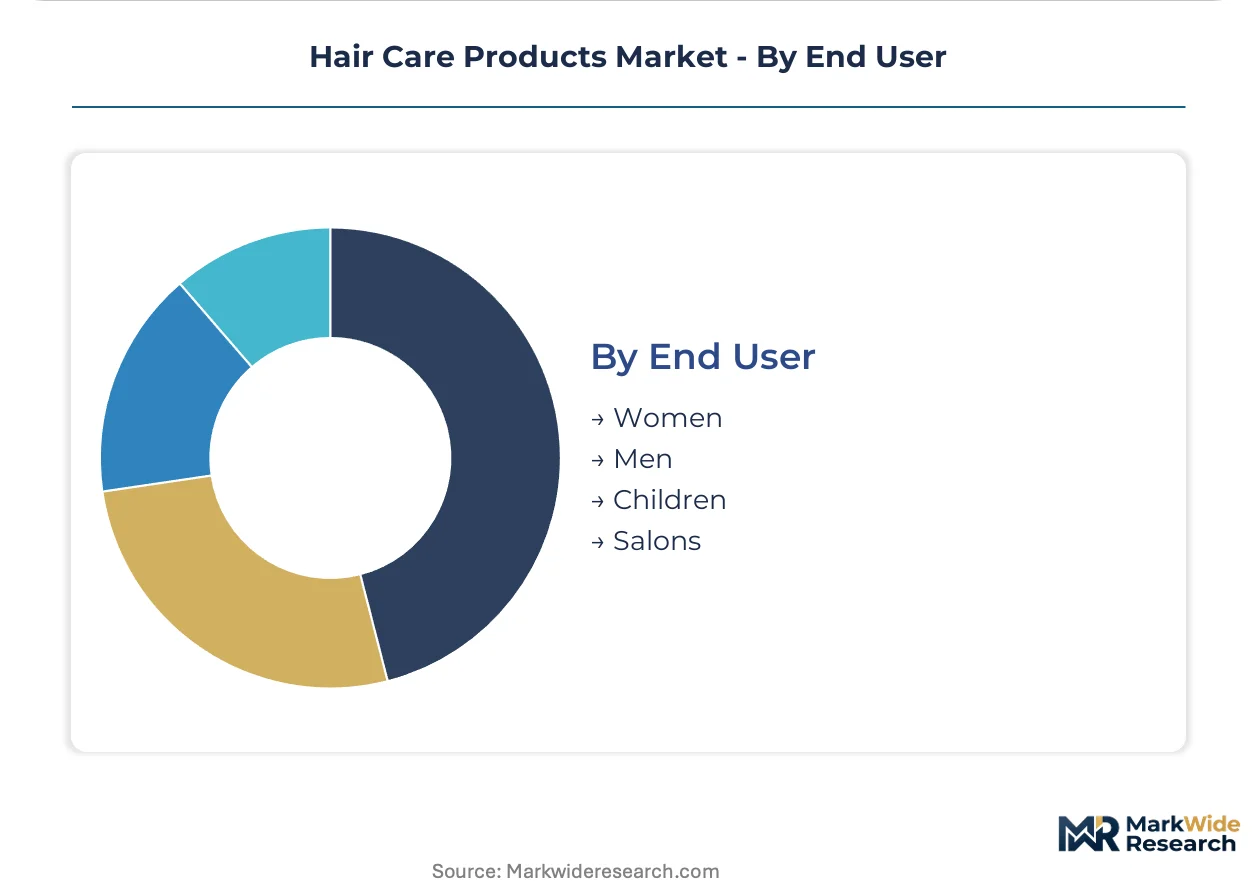
End User:
Customer type segmentation governs packaging format, fragrance development, and retail versus professional channel allocation.
- Women:The traditional core demographic with specialized regimens spanning multiple product categories. Indian urbanization and rising disposable incomes elevate daily routines into multi-step systems.
- Men:Simplified formats with functional positioning around scalp health and styling efficiency. Direct-to-consumer platforms capture this segment outside traditional mass-market retail browsing.
- Children:Mild surfactant systems with tear-free formulations and allergen-controlled fragrance palettes. BIS quality benchmarks create compliance costs favoring established multinationals.
- Salons:Professional-only formulations with higher concentrations and service-integrated application protocols. Scalp microbiome science opens clinical-positioning white space between pharmaceutical and beauty channels.
Women holds installed capacity. Salons is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cosmetic labeling requirements anchor the United States as the reference jurisdiction for ingredient disclosure standards, while BIS certification in India and REACH authorization in Germany collectively shape multinational formulation strategies across three distinct regulatory poles.
United States
Direct-to-consumer subscription platforms capture younger demographics through algorithm-curated regimens in metropolitan markets. FDA oversight of cosmetic safety labeling mandates ingredient disclosure without pre-market approval, enabling faster SKU turnover than pharmaceutical-adjacent categories. Los Angeles and New York anchor clean-label brand incubation, with fermentation-derived actives displacing conventional silicones in prestige salon channels.
Germany
Professional salon networks absorb premium silicone-free conditioners as service-based treatments expand across Cologne and Düsseldorf. ECHA's prolonged safety assessments for novel biocidal actives delay product launches versus conventional chemistries. The Rhine-Ruhr industrial corridor concentrates contract manufacturing for REACH-compliant preservative systems serving pan-European distribution.
India
Urbanization in Mumbai and Delhi elevates daily hair care routines into multi-step systems spanning pre-wash oils and scalp-focused serums. BIS certification mandates quality benchmarks for imported formulations, creating compliance costs that favor established multinationals over unorganized local competitors. Metro markets drive per-capita consumption multiples above rural benchmarks.
Japan
Scalp microbiome research converges with cosmetic formulation to open clinical-positioning white space between pharmaceutical and beauty channels. METI guidance on biotechnology-derived ingredients accelerates adoption of fermentation-based keratin analogs. Osaka and Tokyo prefectures concentrate R&D facilities for peptide complex development serving Asian export markets.
Brazil
Natural ingredient demand accelerates SKU proliferation for botanical extracts and cold-pressed oils across São Paulo and Rio de Janeiro retail networks. ANVISA cosmetic registration requirements extend timelines for novel preservative introduction versus US or Asian pathways. The Southeast industrial belt houses formulation facilities serving Mercosur trade bloc distribution.
Hair Care Products Market Competitive Environment
Multinational conglomerates and specialized regional formulators split the market across distinct capability tiers. Consolidation pressure concentrates upstream active ingredient supply and downstream salon distribution networks. Three archetypes dominate: vertically integrated beauty conglomerates controlling raw material sourcing, mid-tier manufacturers competing on BIS or REACH compliance infrastructure, and direct-to-consumer platforms leveraging diagnostic personalization. Competitive moves center on backward integration into fermentation-derived actives and geographic licensing partnerships for regulatory market access.
Within the vertically integrated tier, L'Oréal and Procter & Gamble exemplify divergent scale strategies. L'Oréal occupies a position emphasizing upstream control over biotechnology-enabled protein supply chains. Procter & Gamble anchors the mass-market volume tier through manufacturing scale advantages in entry-level shampoo and conditioner segments. Unilever sits within a hybrid archetype balancing geographic diversification across emerging and mature markets simultaneously.
| Leading Market Players |
|---|
| L'Oréal |
| Procter & Gamble |
| Unilever |
| Henkel |
| The Estée Lauder Companies |
| Kao Corporation |
| Johnson & Johnson |
| Shiseido |
| Coty |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Southeast Asian surfactant production facilities is compressing spot prices for cleansing bases while simultaneously eroding supplier leverage in contract negotiations, forcing formulators toward longer-term offtake commitments to secure volume guarantees.
Pricing Analysis
Price spreads between German salon-grade formulations and Indian mass-market alternatives exceed threefold multiples when normalized for volume. Pricing stratifies across premium, standard, and economy tiers, with certification grade under EU REACH and BIS quality benchmarks driving differentiation. Cost compression in mass-market shampoo portfolios is intensifying because palm oil and coconut oil input volatility feeds directly into margin pressure. Professional salon channels exhibit lowest price sensitivity; entry-level daily-use consumers in rural Indian markets demonstrate highest elasticity.
Supply Chain Analysis
Export-control restrictions on biotechnology-derived peptide manufacturing equipment limit flows from Japanese and German precision-engineering suppliers into emerging production hubs. Raw material sourcing draws from Indonesian palm plantations, Indian coconut processing cooperatives, and Brazilian botanical extract operations. Single-source vulnerability concentrates in fermentation-derived keratin analog capacity anchored in Osaka and Tokyo prefectures. Distribution runs through professional salon networks, mass retail chains, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise bridging cosmetic formulation science and regulatory toxicology commands compensation premiums that constrain mid-tier manufacturer expansion, creating structural bottlenecks in R&D staffing and compliance infrastructure deployment.
For Market Incumbents: Pre-empt formulation chemist scarcity through captive training partnerships with Mumbai and Delhi technical institutes before competitor salary escalation locks talent pools. Defend margin position by accelerating backward integration into fermentation-derived actives in Japanese R&D corridors, insulating against specialty chemical supplier margin compression.
For New Entrants and Emerging Players: Establish a beachhead in scalp microbiome-positioned treatments where dermatological credibility gaps separate pharmaceutical and beauty channels. Target direct-to-consumer subscription models in US metropolitan markets with diagnostic-driven personalization engines, bypassing retail slotting fee barriers that favor established multinationals.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated biotech platforms with captive manufacturing of fermentation-derived proteins, given clean-label substitution tailwinds. Long-term viability hinges on regulatory compliance infrastructure that satisfies REACH, BIS, and FDA disclosure requirements simultaneously. Watch ECHA preservative approval timelines as inflection signals for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Actives Integration | Fermentation-derived keratin analogs unlock clean-label positioning without performance trade-offs in prestige salon channels. |
| REACH Compliance Infrastructure | Early preservative reformulation investments capture shelf space as EU retailers preempt enforcement actions. |
| Direct-to-Consumer Platform Launch | Algorithm-curated subscription regimens displace mass-market aisle browsing among demographics under 35. |
| BIS Certification Investment | Quality benchmark compliance creates barriers against unorganized local competitors in Indian premium tiers. |
| Scalp Microbiome R&D Partnership | Convergence of dermatological research and cosmetic formulation opens clinical-positioning white space. |
Study Parameters
Desk research of customs trade records, BIS certification databases, and ECHA substance authorization filings preceded structured interviews with formulation chemists, regulatory affairs directors, salon distribution network managers, and procurement leads at multinational personal care manufacturers. Primary fieldwork captured procurement pattern shifts across professional and retail channels. Secondary validation drew from SEC 10-K disclosures, EU customs import flows, and Indian retail audit data. Bottom-up SKU-level modeling and top-down category value triangulation ensured cross-verification.
Assumptions held fixed include regulatory enforcement timelines under REACH and BIS frameworks, palm oil agricultural yield patterns, and biotechnology fermentation capacity expansion curves across the analysis window. Segmentation dimensions spanned product type, ingredient certification grade, application benefit platform, and end-user channel. CAGRs derived from volume trajectory modeling against per-capita consumption benchmarks in metro versus rural Indian markets, with biotechnology adoption curves and subscription commerce penetration serving as industry-specific inputs.
Stress conditions across palm oil price volatility bands, ECHA approval timeline delays, and direct-to-consumer churn rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and agricultural supply chain continuity. Cross-checking against Nielsen retail audit data and salon channel inventory surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Relaxer Market
Hair Care
India Hair Care Market
Hair Care
Protein Shampoo Market
Hair Care
Israel Hair Care Market
Hair Care
Hair Tonic Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Malaysia Shampoo Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Mexico Hair Care Market
Hair Care
Hair Care Market
Hair Care
France Haircare Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Rice Water Shampoo Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Global Professional Hair Care Market