
 Middle East and Africa Hair Care Market | 2026-2036
Middle East and Africa Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hair Care Market Foresight
South African contract manufacturers is decoupling from imported finished goods dependency as local blending capacity expands across Gauteng and Western Cape provinces. L'Oréal S.A. leverages its Johannesburg distribution hub to control premium salon channel access across Southern Africa. Unilever PLC anchors mass-market shampoo volumes through deep wholesale networks in Nigeria and Kenya. Procter & Gamble Co. competes on dermatologist-endorsed formulations targeting scalp health concerns prevalent in arid climates.
Middle East and Africa hair care encompasses formulations designed to cleanse, condition, treat, and style human hair, typically incorporating surfactant systems at pH 4.5–6.5, emollients, and active ingredients tailored to textured hair porosity and regional water hardness profiles. Shampoos and conditioners sustain the largest revenue base due to habitual replenishment cycles, while hair oils capture expanding margin pools as consumers shift toward heritage botanical formulations. Professional end users represent the fastest-growing demand segment as salon culture deepens in Lagos, Nairobi, and Dubai. Sulfate-free and herbal formulations are gaining shelf space as ingredient literacy rises among urban millennials.
South Africa's National Regulator for Compulsory Specifications enforces mandatory safety standards on cosmetic imports, while Saudi Arabia's SFDA mandates halal certification for hair care products distributed through domestic retail channels. These frameworks elevate compliance costs for new entrants but protect established suppliers with certified local production. Nigeria's National Agency for Food and Drug Administration and Control intensifies port inspections for undeclared chemical actives, reshaping import logistics for multinational brands. Stakeholders must monitor evolving halal certification reciprocity between Gulf Cooperation Council states and North African export hubs to optimize regional manufacturing allocation.
Market Dynamics
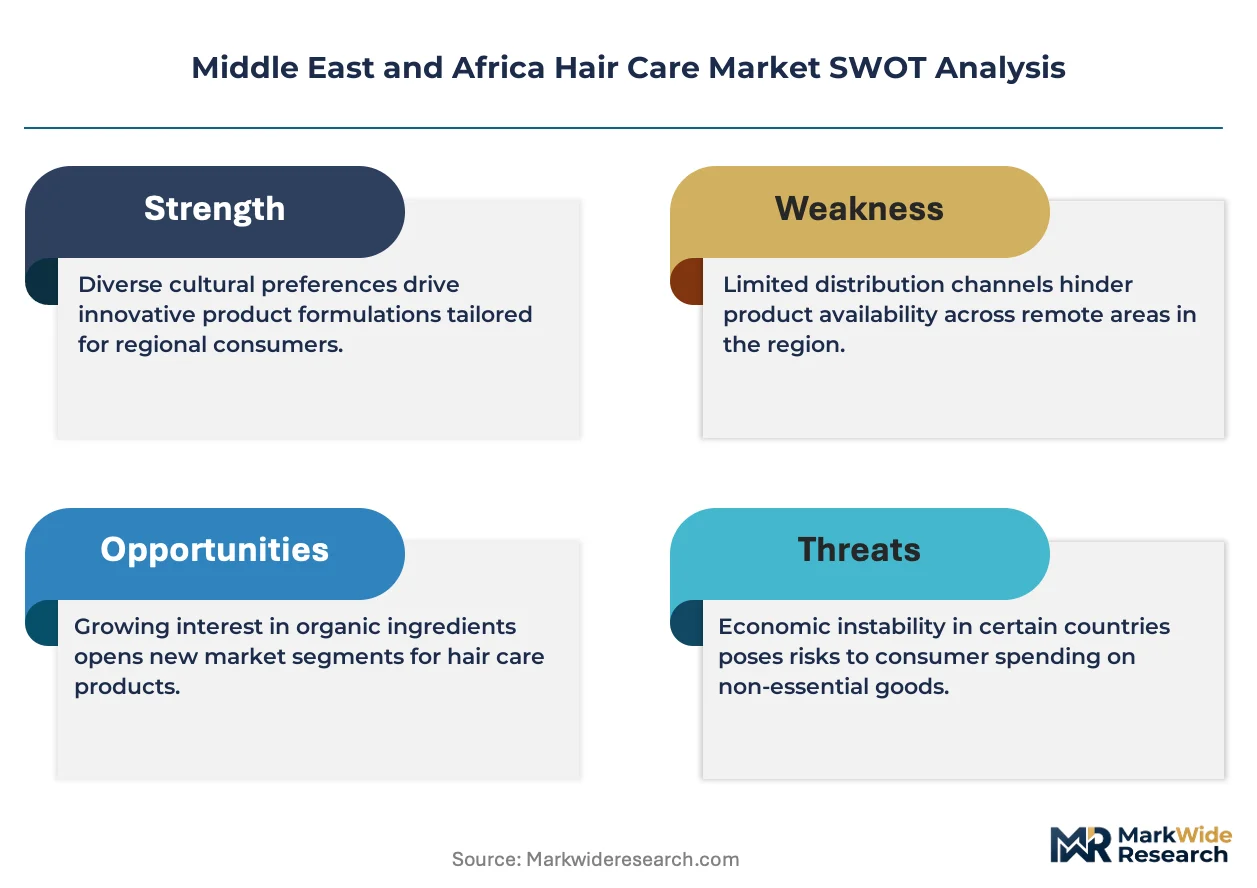
Professional salon channel expansion across Lagos, Nairobi, and Dubai is compressing traditional retail distribution timelines and forcing reformulation priorities toward stylist-grade performance standards.
Growth Catalysts
- Halal certification mandates:Saudi Arabia's SFDA requires halal verification for all domestic retail hair care distribution, creating certified production premiums that Gulf Cooperation Council reciprocity agreements extend across regional export corridors.
- Textured hair specialization:Formulation chemistry adapted to high-porosity curl patterns and hard water mineral content is capturing professional salon commitments in South Africa's Gauteng province.
- Heritage botanical revival:Consumer ingredient literacy in Nigeria's urban centers is pulling shelf space toward shea, argan, and moringa oil formulations with traceable African sourcing.
Market Restraints
- Import dependency concentration:Finished goods still flow through Durban and Lagos ports where NAFDAC inspection backlogs create three-to-six-week customs delays for undeclared active ingredients.
- Water hardness formulation costs:Chelating agent requirements for calcium and magnesium binding add 12-18% to raw material bills in high-mineral groundwater zones across the Sahel.
- Sulfate-free stability limits:Alternative surfactant systems compromise preservative efficacy, shortening shelf life and complicating ambient-temperature distribution in climates exceeding 40°C.
Strategic Opportunities
- Ethiopian manufacturing greenfield:Underdeveloped local blending capacity and rising middle-class consumption in Addis Ababa create first-mover advantages for regional production hubs serving Horn of Africa distribution.
- Salon channel verticalization:Direct-to-stylist education and exclusive professional SKUs bypass wholesale margin stacking while locking in stylist recommendation authority.
- South African contract manufacturing scale:Gauteng and Western Cape blending facilities are decoupling from imported finished goods as technical capabilities reach export-grade certification standards.
Industry Challenges
- Cosmetic chemist scarcity:Formulation expertise for textured hair science and halal compliance auditing concentrates in Johannesburg and Dubai, creating talent acquisition bottlenecks for mid-market entrants.
- Multi-jurisdiction certification lag:Sequential approvals across Nigeria's NAFDAC, South Africa's NRCS, and Saudi Arabia's SFDA extend product launch timelines by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hair Care Market |
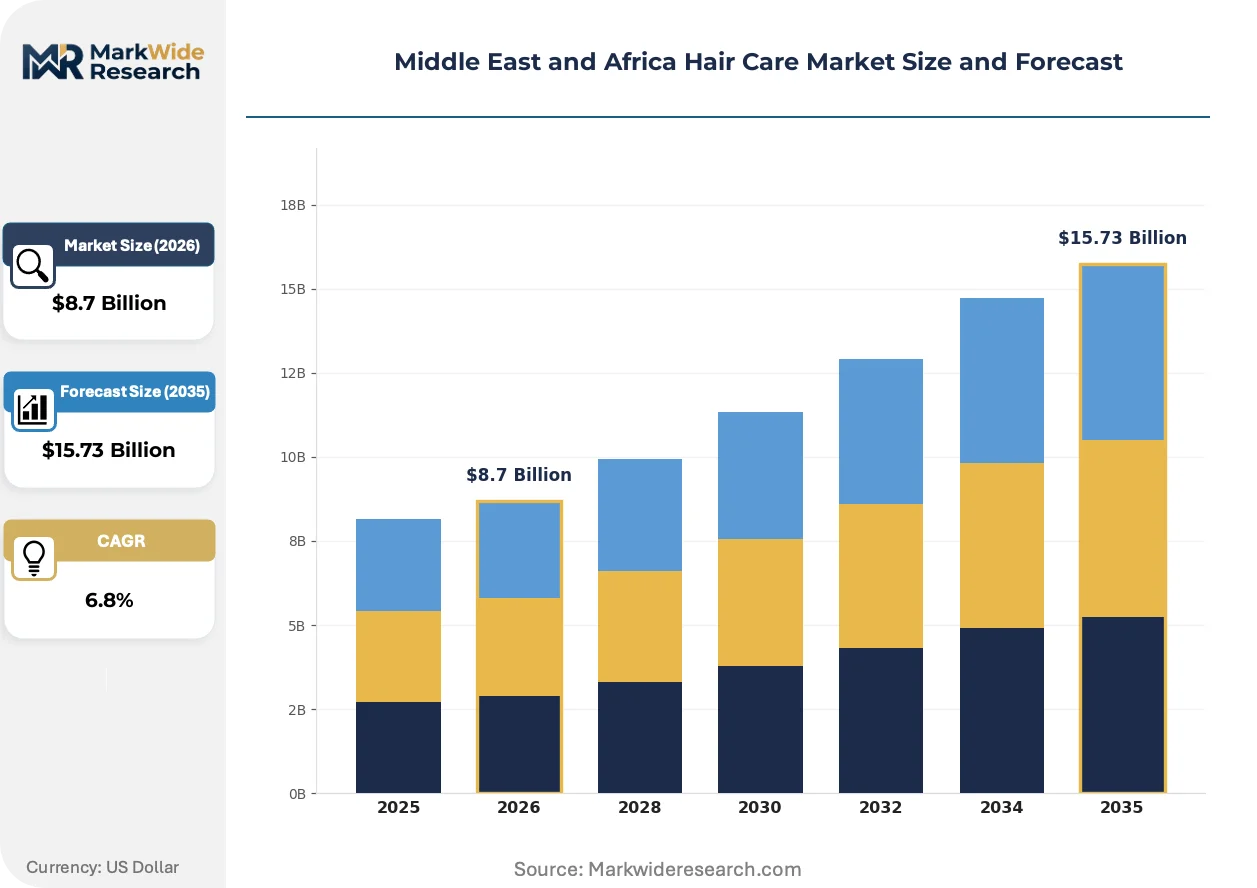
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products End User: Women, Men, Children, Professionals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Formulation: Organic, Sulfate-Free, Herbal, Chemical |
| Companies Covered | Henkel AG & Co. KGaA, Johnson & Johnson, L'Oréal S.A., Dabur International, Marico Ltd., Procter & Gamble Co., Kao Corporation, Twincare International, Unilever PLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hair Care Market Shifts & Advancements
Formulation science and distribution architecture are diverging sharply between mass-market scale plays and premium heritage-positioned brands, with technology adoption pacing splitting along professional-versus-retail channel lines.
Biomimetic lipid complexes are integrating into conditioner bases to replicate sebum distribution patterns on high-porosity hair shafts. Professional stylists in Dubai and Lagos salons are specifying these systems for color-treated textured hair at three times the rate of retail consumers. The technology is integrating moisture-retention benchmarks into B2B procurement specifications that mass-market brands struggle to meet without price-point compression.
South Africa's National Regulator for Compulsory Specifications is tightening mandatory ingredient disclosure thresholds under updated consumer protection frameworks. Compliance costs for full traceability documentation are filtering smaller importers from pharmacy and supermarket listings. Multinational suppliers with Johannesburg-based technical teams are absorbing these requirements faster than direct exporters, consolidating shelf access in premium retail tiers.
Urban millennial buyers are unbundling styling product purchases from shampoo replenishment cycles, treating oils and edge controls as discretionary fashion accessories rather than functional necessities. This fragmentation is compressing brand loyalty half-lives and elevating influencer-driven trial rates in Nigeria's Lagos-Ibadan corridor and Kenya's Nairobi metropolitan zone. Digital-native brands with direct-to-consumer logistics are capturing this behavior shift faster than traditional wholesale-dependent incumbents.
Middle East and Africa Hair Care Market Segmentation
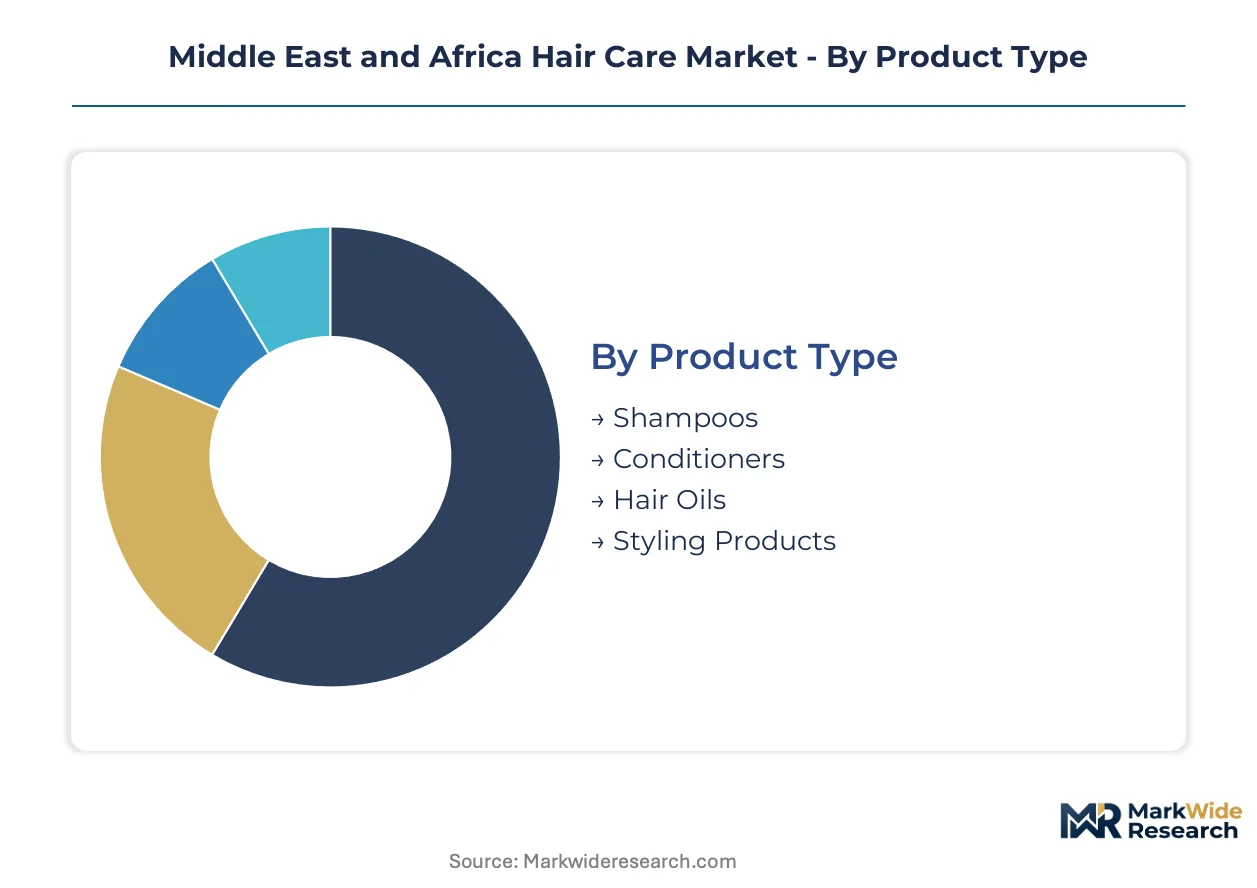
Hair care purchasing patterns across the Middle East and Africa fragment sharply between ritual-driven daily use and occasion-based styling investments. Segmentation reveals where formulation investments translate into margin capture versus volume throughput.
Product Type:
Purchase frequency and price sensitivity diverge dramatically between cleansing staples and treatment-oriented products.
- Shampoos:Surfactant-based cleansing formulations dominate household replenishment cycles across Nigerian urban centers and South African townships. Mass-market sachet packaging in Lagos and Nairobi sustains volume leadership despite thin margins.
- Conditioners:Cationic emulsion systems with tailored slip agents for high-porosity textures command professional salon specifications in Dubai and Johannesburg. Stylist endorsement authority in these markets elevates price realization above retail channels.
- Hair Oils:Heritage botanical formulations with traceable African sourcing capture premium positioning in Nigeria's middle-class segments.
- Styling Products:Edge controls and curl definers concentrate demand in professional salon backbars across Lagos and Nairobi.
Volume sits with Shampoos; growth tilts toward Hair Oils.
End User:
Gendered purchasing rituals and professional service dependencies create distinct channel requirements.
- Women:Multi-step regimen adherence drives the full product spectrum from cleansing through treatment, with textured hair specialization commanding formulation premiums in South Africa's Gauteng province and Nigeria's urban centers.
- Men:Beard care convergence with scalp treatments is expanding SKU relevance in Saudi Arabian and UAE retail, though purchase frequency remains below female household rates.
- Children:Tear-free formulation requirements dominate purchasing criteria in pharmacy channels across the region.
- Professionals:Salon operators in Lagos, Nairobi, and Dubai specify performance-grade systems with stylist education support, representing the steepest expansion trajectory among end-user categories.
Women anchor current revenue; Professionals expand most quickly.
Distribution Channel:
Channel selection determines margin structure and brand positioning authority.
- Online Retail:Direct-to-consumer logistics with influencer-driven trial mechanics are capturing urban millennial fragmentation in Nigeria's Lagos-Ibadan corridor and Kenya's Nairobi metropolitan zone.
- Supermarkets:Mass-market shampoo and conditioner volumes flow through deep wholesale networks anchored by Unilever's Nigeria and Kenya operations.
- Pharmacies:Dermatologist-endorsed scalp health formulations concentrate in South African pharmacy tiers with tightened NRCS disclosure compliance.
- Specialty Stores:Premium heritage botanical positioning with traceable sourcing claims occupies dedicated retail space in Dubai and Johannesburg.
Supermarkets hold volume dominance; Online Retail gains share fastest.
Formulation:
Ingredient literacy and certification requirements are restructuring competitive access.
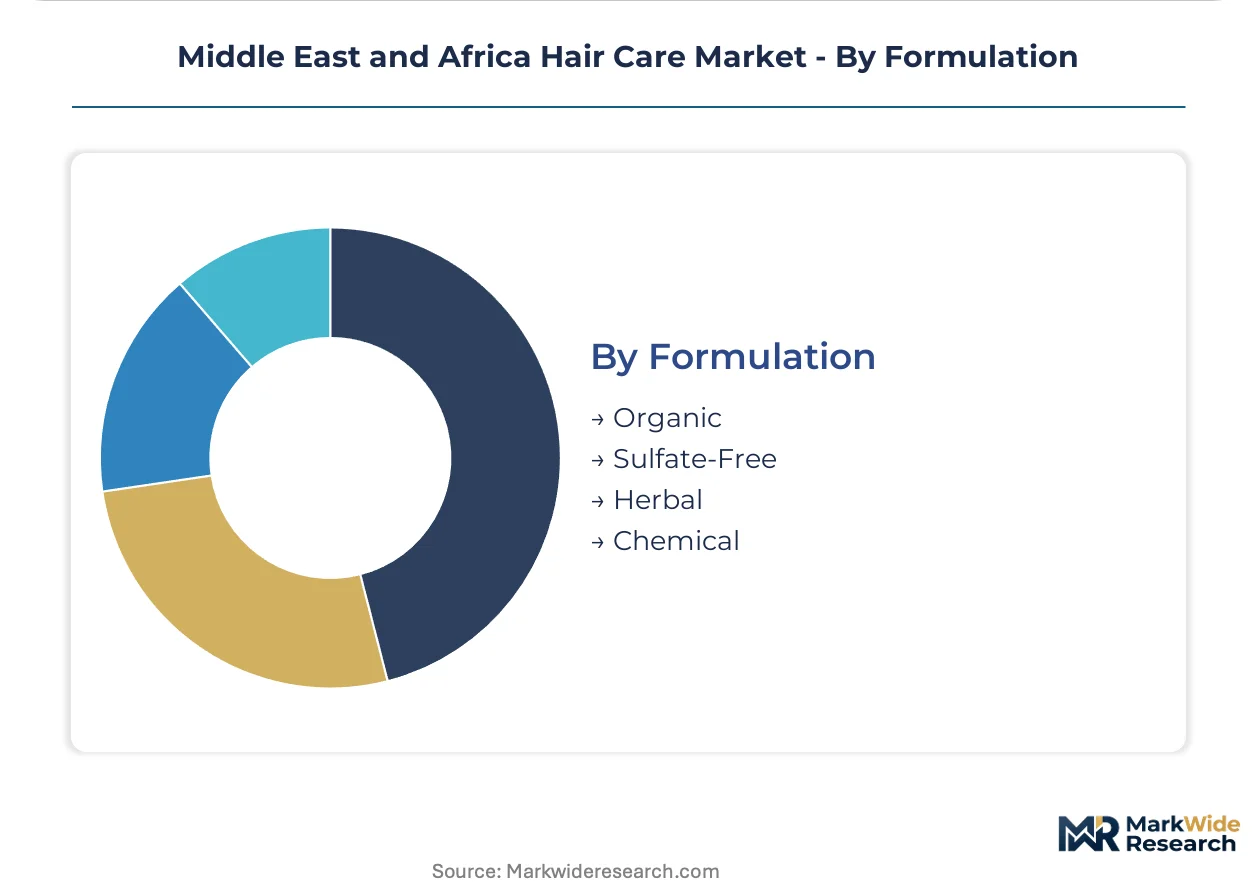
- Organic:Agricultural input traceability with EU-equivalent certification standards limits supplier pools but commands shelf space in South African premium retail.
- Sulfate-Free:Alternative surfactant systems face preservative stability challenges in ambient-temperature distribution across climates exceeding 40°C, complicating mass-market penetration.
- Herbal:Shea, argan, and moringa oil formulations with African sourcing narratives capture Nigerian urban millennial preference.
- Chemical:Conventional surfactant systems retain cost advantages in price-sensitive mass-market segments across the Sahel.
Chemical formulations retain volume leadership; Herbal alternatives climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shea butter cooperatives in Burkina Faso and Mali supply the botanical feedstock anchoring heritage oil formulations across Nigerian and South African premium tiers. Argan oil extraction clusters in southwestern Morocco sustain ingredient pipelines for Dubai and Johannesburg specialty retail channels.
South Africa
Professional salon channel expansion in Gauteng province drives stylist-grade conditioner demand. The National Regulator for Compulsory Specifications enforces tightened ingredient disclosure thresholds under updated consumer protection frameworks. Johannesburg-based technical teams absorb compliance costs faster than direct exporters, consolidating shelf access in premium pharmacy and supermarket tiers.
Nigeria
Urban middle-class consumers in Lagos and Ibadan drive premium hair oil and styling product purchases with unbundled regimen behavior. The National Agency for Food and Drug Administration and Control intensifies port inspections for undeclared chemical actives, reshaping import logistics for multinational brands. Lagos-Ibadan corridor digital-native brands capture influencer-driven trial mechanics faster than wholesale-dependent incumbents.
Saudi Arabia
Beard care convergence with scalp treatments expands SKU relevance in male grooming segments. The Saudi Food and Drug Authority mandates halal certification for all domestic retail hair care distribution, creating certified production premiums. Riyadh and Jeddah retail channels enforce verification standards that Gulf Cooperation Council reciprocity agreements extend across regional export corridors.
United Arab Emirates
Dubai salon culture deepens professional end-user demand for biomimetic lipid complex formulations. The Ministry of Health and Prevention oversees cosmetic safety standards aligned with halal certification requirements. Dubai International Airport free zone logistics anchor regional distribution hubs serving re-export corridors into East African markets.
Kenya
Nairobi metropolitan zone consumers fragment styling product purchases toward discretionary fashion accessory positioning. The Pharmacy and Poisons Board regulates cosmetic ingredient safety with evolving alignment to East African Community harmonization protocols. Mombasa port throughput constraints push brands toward direct-to-consumer logistics bypassing traditional wholesale networks.
Middle East and Africa Hair Care Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue heritage botanical positioning and direct-to-consumer channel capture. Market structure tilts toward multinational concentration in mass-market shampoo and conditioner volumes, with regional specialists carving margin pools in professional salon and premium heritage segments. Three archetypes dominate: scale-driven fast-moving consumer goods conglomerates, textured-hair formulation specialists, and digital-native direct-to-consumer brands. Competitive moves concentrate on backward integration into African botanical sourcing and exclusive professional SKU development with stylist education support.
Within the scale-driven tier, L'Oréal S.A. and Unilever PLC exemplify multinational infrastructure leverage, while Procter & Gamble Co. anchors dermatologist-endorsed scalp health positioning. Among heritage botanical specialists, Dabur International and Marico Ltd. occupy positions tied to traceable African and South Asian oil sourcing narratives. These groupings illustrate how competitive advantage separates between supply chain control over raw material origins and distribution depth through wholesale or direct channels.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Johnson & Johnson |
| L'Oréal S.A. |
| Dabur International |
| Marico Ltd. |
| Procter & Gamble Co. |
| Kao Corporation |
| Twincare International |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Shea butter and argan oil feedstock costs cascade through heritage botanical tiers into premium retail positioning across Nigerian and South African markets, while chelating agent expenses for hard water adaptation compress margins in mass-market shampoo formulations distributed through Lagos and Nairobi wholesale networks.
Pricing Analysis
Stylist education and certification support bundled into professional-grade SKUs separate salon channel pricing from unbundled retail sachets. Three-tier pricing structure across premium heritage oils, standard salon-grade systems, and economy mass-market cleansers reflects formulation complexity and halal certification investment. Price erosion runs through economy tiers as local contract manufacturers in Gauteng province expand blending capacity and displace imported finished goods. Professional end users exhibit lowest price sensitivity due to stylist recommendation authority and performance-grade specification requirements.
Supply Chain Analysis
Botanical oil supply rests on Burkina Faso and Mali shea cooperatives alongside southwestern Morocco argan extraction clusters. Surfactant systems and preservative packages draw from Indian and Chinese specialty chemical producers. Single-source vulnerability concentrates in heritage oil traceability documentation required for South African NRCS compliance and Saudi SFDA halal verification. Distribution runs through Dubai International Airport free zone logistics hubs serving re-export corridors into East African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as players pursue captive supply of traceable African botanical feedstocks to secure heritage positioning premiums and certification compliance.
For Market Incumbents: Hedge against digital-native brand displacement by acquiring direct-to-consumer logistics capabilities in Nigeria's Lagos-Ibadan corridor and Kenya's Nairobi metropolitan zone. Lock in stylist recommendation authority through exclusive professional SKU development with embedded education support. Accelerate backward integration into shea and argan sourcing clusters to defend margin position against heritage botanical specialists.
For New Entrants and Emerging Players: Begin with Ethiopian manufacturing greenfield opportunities where underdeveloped local blending capacity meets rising Addis Ababa middle-class consumption. Target professional salon verticalization in Lagos, Nairobi, and Dubai where stylist-grade performance specifications command price premiums above mass-market tiers. Deploy influencer-driven trial mechanics to capture unbundled styling product purchases from fragmented urban millennial regimens.
For Investors and Strategic Acquirers: Gulf Cooperation Council halal certification reciprocity expansion is the leading indicator that regional manufacturing allocation optimization will consolidate competitive advantage. Five-to-ten year viability favors suppliers with certified local production across multiple jurisdiction approvals. Acquisition target archetype: textured-hair formulation specialists with Johannesburg or Dubai technical teams and existing NAFDAC or SFDA registration pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into African Botanical Sourcing | Captive shea and argan supply secures traceability documentation for NRCS and SFDA compliance. |
| Professional Salon Channel Verticalization | Direct-to-stylist education locks in recommendation authority and bypasses wholesale margin stacking. |
| Halal Certification Investment | SFDA verification enables premium positioning across Gulf Cooperation Council retail corridors. |
| Direct-to-Consumer Logistics Buildout | Influencer-driven trial mechanics capture fragmented urban millennial unbundled purchase behavior. |
| Local Contract Manufacturing Scale-Up | Gauteng and Western Cape blending facilities displace imported finished goods dependency. |
Research Methodology
Trade customs records, retail audit databases, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews involving cosmetic chemists, salon chain procurement managers, brand managers at heritage botanical specialists, and NAFDAC compliance officers. Bottom-up volume triangulation across product type and end-user segments was reconciled with top-down value estimates derived from channel margin structures and certification cost absorption rates.
Historical trendline analysis of replenishment cycle frequencies and professional salon adoption curves informed projection modeling across the analysis window. Segmentation dimensions included product type, end user category, distribution channel, and formulation certification tier. CAGRs were derived from fitted growth curves adjusted for regulatory approval timeline constraints and port inspection backlog impacts on import logistics.
Underlying measurement precision varies by segment; shampoo volume estimates carry tighter precision than hair oil premium tier projections due to fragmented direct-to-consumer channel opacity. Forecasts reflect assumptions regarding halal certification reciprocity progression and Ethiopian manufacturing greenfield development pace. A small set of triggers—NAFDAC inspection protocol intensification, Gulf Cooperation Council regulatory harmonization shifts, and shea cooperative supply consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Care Appliances Market
Hair Care
Japan Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Hair Spray Market
Hair Care
Organic Hair Care Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Hair Mask Market
Hair Care
Hair Relaxer Market
Hair Care
Men's Hairspray Market
Hair Care
Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Global Shampoo Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Italy Hair Care Market
Hair Care
Sweden Hair Care Market