
 South Africa Hair Care Market | 2026-2036
South Africa Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Hair Care Market Outlook
Salon procurement in South Africa is consolidating as franchise chains and multi-location operators expand their share of professional product purchasing. Unilever PLC leverages its broad manufacturing scale to supply both retail and trade channels with consistent volume. L'Oréal SA anchors its position through specialized professional-grade lines targeted at licensed stylists. AfroBotanics differentiates by concentrating on indigenous ingredient sourcing and textured-hair formulations tailored to South African consumers.
South Africa hair care encompasses cleansers, conditioners, styling preparations, and treatment oils formulated with surfactant systems, emollients, active botanicals, and pH-balanced bases designed to cleanse, condition, protect, or style human hair across diverse curl patterns and environmental exposures. Shampoo and conditioner together occupy the largest volume share, reflecting habitual consumption frequency and broad demographic penetration. Hair oil registers the fastest structural expansion, driven by textured-hair consumers seeking moisture retention and scalp health benefits. Specialty Stores command elevated margin pools by offering curated assortments and consultation services that justify premium positioning.
South Africa's National Regulator for Compulsory Specifications mandates compliance with SANS standards for cosmetic safety, while the Department of Health oversees labeling and ingredient disclosure under the Foodstuffs, Cosmetics and Disinfectants Act. These frameworks elevate barrier costs for new entrants but reinforce quality trust among consumers navigating complex ingredient claims. Stakeholders must monitor evolving enforcement intensity around formaldehyde-releasing preservatives and sulfate restrictions, as regulatory tightening could force accelerated reformulation cycles across both mass and premium portfolios.
Market Dynamics
Salon franchise consolidation across Gauteng and Western Cape provinces is compressing wholesale margins while concentrating procurement power among multi-location operators. This structural concentration is forcing reformulation priorities and reshaping how professional-grade products reach licensed stylists.
Growth Catalysts
- Professional channel expansion:Franchise salon chains in Johannesburg and Cape Town are standardizing product protocols across locations, creating predictable volume pipelines for compliant suppliers.
- SANS 15503 enforcement:South Africa's National Regulator for Compulsory Specifications mandates cosmetic safety testing that elevates quality trust among ingredient-conscious consumers.
- Textured-hair specialization:Moisture-retention formulations targeting curl patterns common in the domestic population are expanding addressable demand beyond generic mass-market SKUs.
Market Restraints
- Import dependency for surfactants:Key cleansing agents remain sourced from Asian chemical manufacturers, exposing formulators to freight cost volatility and currency fluctuation.
- Compliance cost escalation:The Foodstuffs, Cosmetics and Disinfectants Act requires extensive documentation and testing cycles that extend new product launch timelines.
- Water scarcity constraints:Persistent drought conditions in Western Cape province limit manufacturing throughput and elevate utility costs for production facilities.
Strategic Opportunities
- Underserved rural provinces:Limpopo and Eastern Cape exhibit low salon penetration relative to population density, creating whitespace for mobile service and direct-to-stylist distribution models.
- Indigenous ingredient valorization:Marula oil and rooibos extract sourcing partnerships with agricultural cooperatives can anchor premium positioning and supply security.
- E-commerce platform specialization:Curated online retailers offering virtual texture analysis and regimen matching are capturing trial-oriented consumers outside traditional retail catchments.
Industry Challenges
- Licensed stylist certification gaps:Formal training programs for textured-hair specialization remain limited, constraining the professional channel's ability to deliver consistent service quality.
- Cold chain integrity for actives:Temperature-sensitive botanical extracts require refrigerated transport infrastructure that is unevenly distributed across secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Hair Care Market |
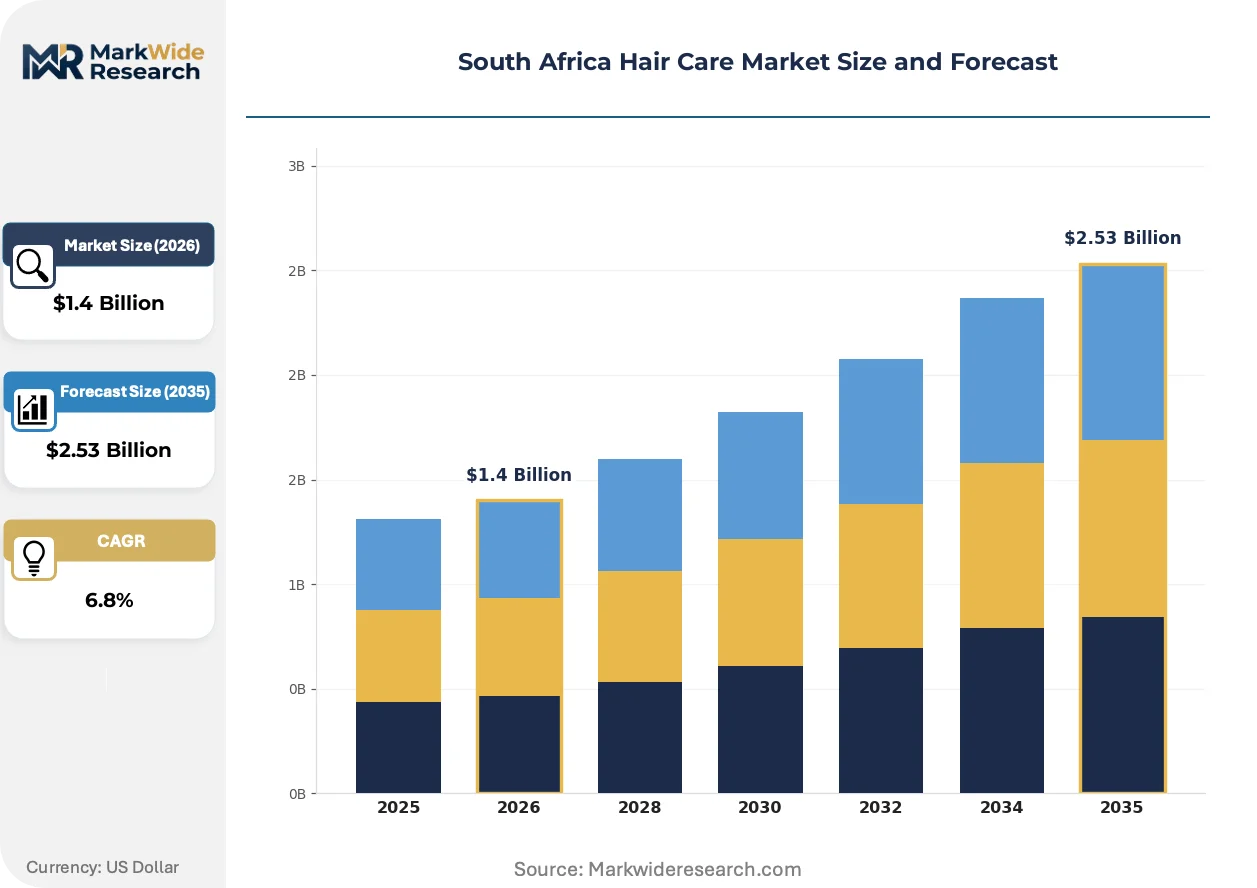
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Styling Gel, Hair Oil End User: Women, Men, Children, Salons Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Drugstores Price Tier: Premium, Mid-range, Budget, Economy |
| Companies Covered | Unilever PLC, L'Oréal SA, Procter & Gamble, Amka Products, Marico Limited, AfroBotanics, Nilotiqa, Kao Corporation, Godrej Consumer Products Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Hair Care Market Strategic Shifts
Formulation science and channel architecture are converging to reshape how South African consumers access hair care. Three distinct vectors are compressing legacy mass-market models while elevating specialized alternatives.
Biotechnology-derived ceramides are replacing petrolatum in moisture-seal formulations. Premium brands targeting textured-hair consumers are adopting these lipids at accelerated pace. The technology is integrating into professional treatment protocols that command service premiums in Johannesburg salons.
South Africa's Department of Health is intensifying scrutiny of formaldehyde-releasing preservatives under amended Foodstuffs, Cosmetics and Disinfectants Act guidelines. This regulatory pressure is forcing accelerated reformulation cycles among mass-market shampoo manufacturers. Formaldehyde-free claims are becoming table stakes for shelf placement in major retail chains.
Specialty retailers with consultation services are capturing preference share from hypermarket beauty aisles. These curated environments offer texture analysis and regimen customization that justifies price premiums. Cape Town and Pretoria exhibit the fastest channel shift toward experiential retail formats.
South Africa Hair Care Market Segmentation
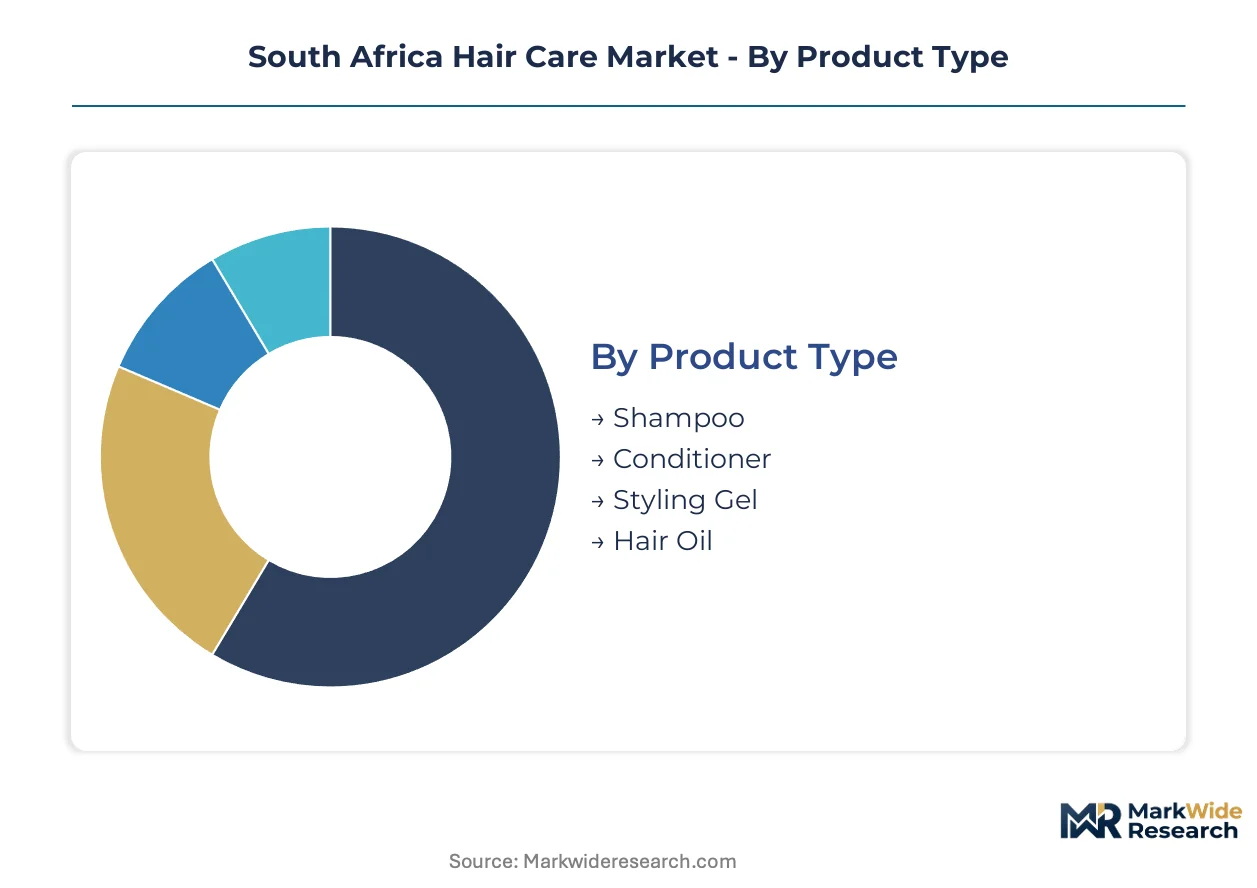
Hair care segmentation in South Africa reflects distinct consumption rituals across curl types, professional service tiers, and retail channel preferences. Understanding these divides reveals where formulation investment and distribution capital generate returns.
Product Type:
Standalone cleansing and conditioning products dominate habitual purchase cycles, while styling and treatment formats embed into specialized regimens with distinct margin profiles.
- Shampoo:Surfactant-based formulations with pH-balanced systems cleanse scalp and hair across daily and weekly wash frequencies. Gauteng households drive volume concentration through high urban penetration and established hygiene routines. SANS 15503 compliance elevates formulation costs but reinforces quality trust in mass retail.
- Conditioner:Cationic emulsions deposit conditioning agents onto cuticle layers for detangling and moisture retention. Western Cape consumers show elevated per-capita consumption driven by textured-hair demographics and salon professional recommendations. Water scarcity constraints in the region periodically disrupt manufacturing throughput.
- Styling Gel:Polymer-thickened hold formulations for curl definition and edge control.
- Hair Oil:Botanical lipid treatments targeting moisture retention and scalp health; marula and indigenous seed oils anchor premium positioning.
Shampoo leads volumes today; hair oil is gaining share fastest.
End User:
Consumption splits between individual household purchasers and institutional procurement channels with divergent price sensitivity and loyalty patterns.
- Women:Primary decision-makers for household hair care portfolios across all product categories. Johannesburg and Pretoria urban clusters concentrate spending on premium textured-hair specialized lines with consultation support.
- Men:Growing addressable segment for grooming-oriented shampoos and styling products. Cape Town metropolitan area shows fastest adoption of male-targeted SKUs through barbershop and specialty retail channels.
- Children:Gentle-formulation cleansers with tear-free surfactant systems.
- Salons:Professional-grade bulk procurement for service protocols; franchise consolidation in Gauteng compresses wholesale margins while concentrating volume.
Women anchor absolute demand; salons are expanding procurement value fastest.
Distribution Channel:
Channel selection determines margin capture and consumer relationship depth, with digital and experiential formats displacing legacy mass retail.
- Online Stores:E-commerce platforms with virtual texture analysis and regimen matching tools. Limpopo and Eastern Cape rural consumers access specialized assortments unavailable in local retail catchments.
- Supermarkets:High-frequency traffic drives mass-market shampoo and conditioner volume. Hypermarket beauty aisles face preference erosion as consumers migrate toward consultation-enabled environments.
- Specialty Stores:Curated assortments with in-person texture analysis and stylist consultation.
- Drugstores:Pharmacy-affiliated retail with dermocosmetic positioning and scalp treatment focus.
Supermarkets retain volume leadership; specialty stores are climbing the fastest.
Price Tier:
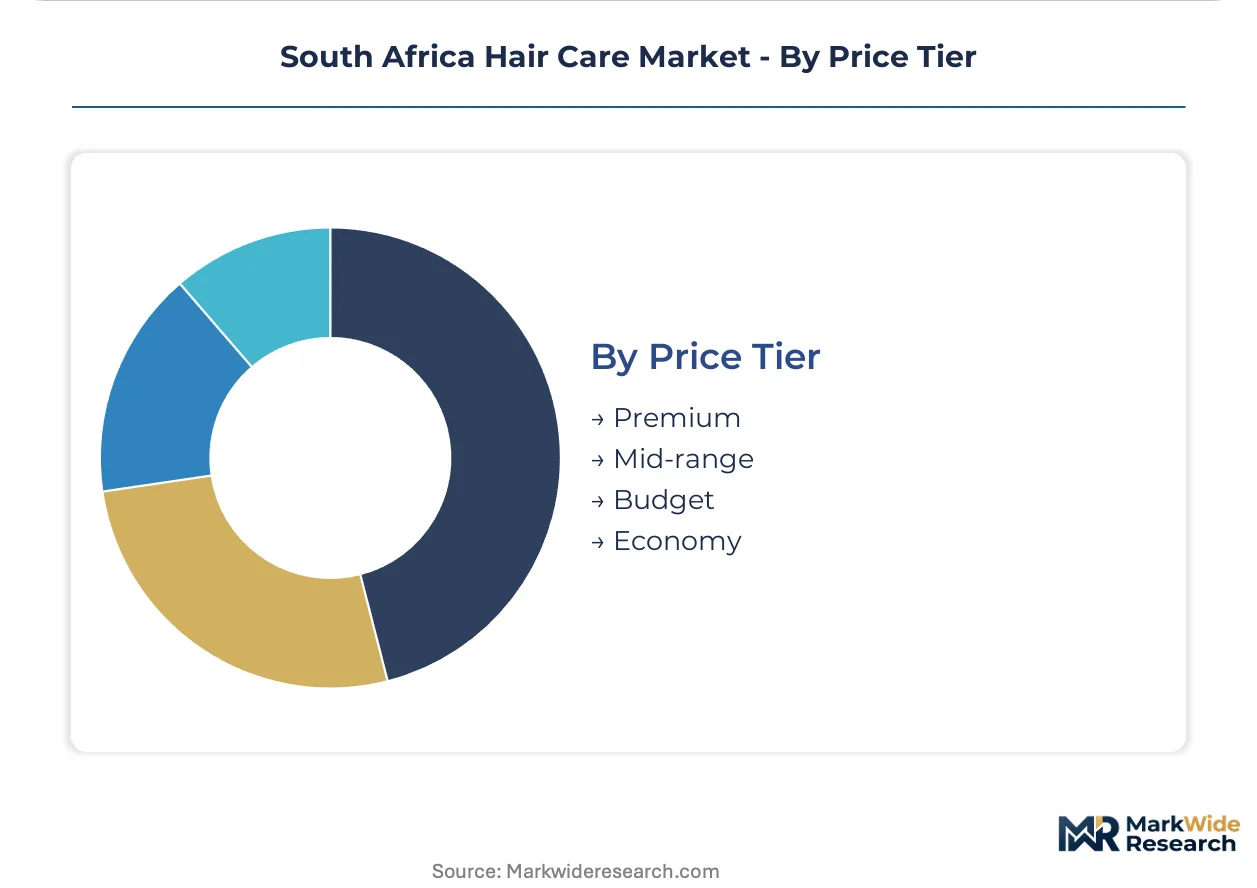
Pricing stratification aligns with ingredient sourcing depth, certification rigor, and channel service intensity rather than pure brand premium.
- Premium:Biotechnology-derived ceramides and indigenous botanical extracts with SANS compliance documentation. Johannesburg premium salons and specialty retailers concentrate demand through service-embedded selling.
- Mid-range:Mass-market brands with professional line extensions and retail-scale distribution. Pretoria and Cape Town urban centers balance quality perception with price accessibility.
- Budget:Standard surfactant formulations with basic conditioning for price-sensitive household procurement.
- Economy:Value-positioned bulk formats and private label alternatives for rural and low-income urban segments.
Mid-range commands the broadest penetration; premium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's hair care demand concentrates in coastal and inland economic corridors, with provincial variations in consumption patterns and distribution infrastructure shaping market access.
Gauteng
Johannesburg and Pretoria anchor the highest per-capita hair care spending nationally, driven by dense urban populations and established salon networks. The National Regulator for Compulsory Specifications enforces SANS 15503 cosmetic safety standards that elevate compliance costs for products entering this market. Franchise salon chains in Sandton and Centurion are consolidating procurement power, compressing wholesale margins while creating volume pipelines for compliant suppliers.
Western Cape
Cape Town metropolitan consumers show elevated conditioner consumption linked to textured-hair demographics and professional stylist recommendations. Persistent drought conditions trigger water scarcity constraints that periodically disrupt manufacturing throughput at local production facilities. The city's Atlantic Seaboard and Southern Suburbs clusters concentrate specialty retail with consultation-enabled experiential formats.
KwaZulu-Natal
Durban's port infrastructure positions the province as a key entry point for imported surfactants and active ingredients sourced from Asian chemical manufacturers. The Department of Health's Foodstuffs, Cosmetics and Disinfectants Act oversight extends to coastal distribution hubs, requiring extensive documentation for inbound shipments. Pinetown industrial zones host blending and packaging operations serving regional retail networks.
Eastern Cape
Port Elizabeth and East London exhibit salon penetration rates below national averages relative to population density, creating whitespace for mobile service models. Limited cold chain infrastructure for temperature-sensitive botanical extracts constrains distribution of premium treatment formulations. Direct-to-stylist distribution partnerships are emerging as alternative channel architectures in this underserved corridor.
Limpopo
Rural consumers in Polokwane and surrounding districts access specialized hair care assortments primarily through e-commerce platforms with virtual texture analysis tools. Agricultural cooperatives in the province supply marula oil and indigenous seed extracts to premium formulators seeking supply security. Mobile retail units and community-based stylists are bridging distribution gaps left by sparse permanent retail infrastructure.
South Africa Hair Care Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across South Africa's hair care market, creating a tiered structure where scale advantages clash with agility and local relevance. Multinational consumer goods groups leverage manufacturing breadth and retail shelf access, while indigenous ingredient specialists carve defensible positions through textured-hair formulation expertise. Two strategic archetypes dominate: global brand houses with professional-grade line extensions, and regional botanical-centric challengers with agricultural supply partnerships. Competitive moves center on franchise salon chain procurement contracts and indigenous ingredient sourcing alliances with agricultural cooperatives.
Within the diversified multinational tier, Unilever PLC and L'Oréal SA exemplify scale-driven market presence through broad retail and trade channel coverage. Among regional specialists, AfroBotanics occupies a position anchored in indigenous ingredient valorization and textured-hair formulation focus. These three companies represent contrasting competitive vectors: manufacturing scale and distribution breadth versus agricultural supply integration and demographic specialization.
| Leading Market Players |
|---|
| Unilever PLC |
| L'Oréal SA |
| Procter & Gamble |
| Amka Products |
| Marico Limited |
| AfroBotanics |
| Nilotiqa |
| Kao Corporation |
| Godrej Consumer Products Limited |
| Others |
Value Chain & Pricing Dynamics
Biotechnology-derived ceramide adoption in moisture-seal formulations is simultaneously elevating raw material costs and concentrating supplier power among specialized lipid manufacturers serving Johannesburg's premium salon networks. This production-method transition compresses margins for mass-market formulators while rewarding early movers with SANS 15503-compliant supply partnerships.
Pricing Analysis
Capacity additions in KwaZulu-Natal's chemical processing zones are reshaping price floors for surfactant-based cleansers. Three-tier pricing structure across premium, standard, and economy levels stratifies by SANS compliance documentation and indigenous ingredient content. Price differentiation hinges on certification grade and volume scale. Cost compression in the budget tier intensifies because import-dependent surfactant costs fluctuate with currency volatility. Rural consumers in Limpopo exhibit highest price sensitivity; franchise salon chains in Gauteng demonstrate lowest.
Supply Chain Analysis
Surfactant supply rests on Indian and Chinese specialty chemical producers, with marula oil sourcing anchored in Limpopo agricultural cooperatives. Key inputs include cationic conditioning agents, pH-balancing systems, and temperature-sensitive botanical extracts. Single-source vulnerability concentrates in Asian surfactant imports exposed to freight cost spikes. Distribution runs through Johannesburg-based wholesalers serving retail chains, with direct-to-stylist models emerging in Eastern Cape whitespace corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's hair care market functions as a geographic-arbitrage play: SANS 15503 compliance costs in Gauteng run substantially higher than Eastern Cape enforcement intensity, creating cost-advantaged manufacturing relocation incentives.
For Market Incumbents: Cement procurement lock-ins with consolidating franchise salon chains before competitors capture standardized protocol contracts. Deepen backward integration into marula oil sourcing through agricultural cooperative partnerships to defend against indigenous ingredient specialists. Prioritize cold chain infrastructure investment for temperature-sensitive actives before distribution gaps harden.
For New Entrants and Emerging Players: Launch via direct-to-stylist distribution models in Eastern Cape and Limpopo corridors where salon penetration lags population density. Target mobile service partnerships and e-commerce platforms with virtual texture analysis as the most penetrable channel architecture. Emphasize indigenous ingredient valorization to differentiate from multinational mass-market portfolios.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional botanical-centric challengers with agricultural supply partnerships but limited retail scale. Long-term viability across the analysis window favors specialists with captive ingredient sourcing and SANS compliance infrastructure. Watch franchise salon procurement consolidation velocity as the key inflection signal for professional channel dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Indigenous Ingredient Sourcing Partnership | Marula oil alliances with Limpopo cooperatives secure supply and anchor premium positioning. |
| SANS 15503 Compliance Investment | Documentation infrastructure unlocks shelf placement in major Johannesburg retail chains. |
| Franchise Salon Procurement Contract | Standardized protocol adoption across Gauteng multi-location operators creates predictable volume. |
| Cold Chain Infrastructure Buildout | Refrigerated transport for botanical extracts enables premium treatment distribution beyond coastal hubs. |
| E-commerce Platform Specialization | Virtual texture analysis tools capture trial-oriented consumers in rural provinces with sparse retail. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement spanned brand managers at multinational consumer goods groups, procurement leads at consolidating franchise salon chains, category buyers at specialty retailers, and supply planners at indigenous ingredient formulators. Secondary validation drew from SANS 15503 regulatory filings, Department of Health enforcement records, Nielsen retail audit data, and customs import documentation for surfactant shipments. Bottom-up volume modeling and top-down macroeconomic anchoring were triangulated for consistency.
Segment-weighted projections applied product type, end user, distribution channel, and price tier dimensions across the modeling period. CAGRs were derived from historical trajectory analysis and forward-looking demand elasticity estimates. Inputs included salon franchise expansion pipelines, e-commerce penetration curves, and regulatory enforcement intensity variations by province.
Forecast precision tightens around the base case; tail outcomes carry wider variance under drought-induced manufacturing disruption or accelerated sulfate restriction enforcement. Projections reflect documented assumptions about franchise consolidation velocity and import cost trajectories. A small set of named triggers warrants ongoing watch: cold chain infrastructure buildout pace, agricultural cooperative partnership formation, and SANS 15503 audit frequency adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Canada Hair Care Market
Hair Care
Global Shampoo Market
Hair Care
Men's Hairspray Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
Hair and Scalp Care Market
Hair Care
Hair Spray Market
Hair Care
Qatar Hair Care Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Rice Water Shampoo Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Israel Hair Care Market
Hair Care
Global Professional Hair Care Market
Hair Care
Global Hair Color Market
Hair Care
Hair Mask Market
Hair Care
Hair Tonic Market