
 Home Scales Market | 2026-2036
Home Scales Market Size, Share, and Industry Trends Forecast 2026-2036
Home Scales Market Foresight
Asian contract manufacturers is decoupling from branded Western vendors as component costs and logistics complexity reshape sourcing strategies. Tanita leverages in-house sensor calibration to sustain precision advantages across medical and consumer lines. Withings competes through deep software-hardware integration, while Garmin anchors its position among athletic user bases with GPS-linked body composition tracking.
Home scales are electromechanical weighing instruments that measure body mass or food weight through strain gauge sensors or spring mechanisms, typically resolving to 0.1 kg precision for body scales and 1 gram for kitchen variants, serving health monitoring, dietary management, and commercial portion control purposes. Smart scales incorporating Bluetooth and Wi-Fi connectivity represent the fastest-expanding technology tier as data synchronization with fitness apps creates stickier user relationships. Mechanical scales persist in price-sensitive segments but carry thinning margin pools, while digital kitchen scales among nutritional professionals command higher average selling prices through gram-level accuracy requirements.
The FDA regulates body composition claims on consumer scales sold in the United States, constraining how manufacturers market bioelectrical impedance analysis features, while EU REACH compliance governs substance restrictions in electronics assemblies affecting sensor housings and circuit boards. Japan's METI enforces measurement accuracy certifications that create non-tariff barriers for uncertified imports. Stakeholders must monitor whether emerging biometric capabilities trigger medical device reclassification in major jurisdictions, as this would fundamentally alter approval costs and competitive dynamics.
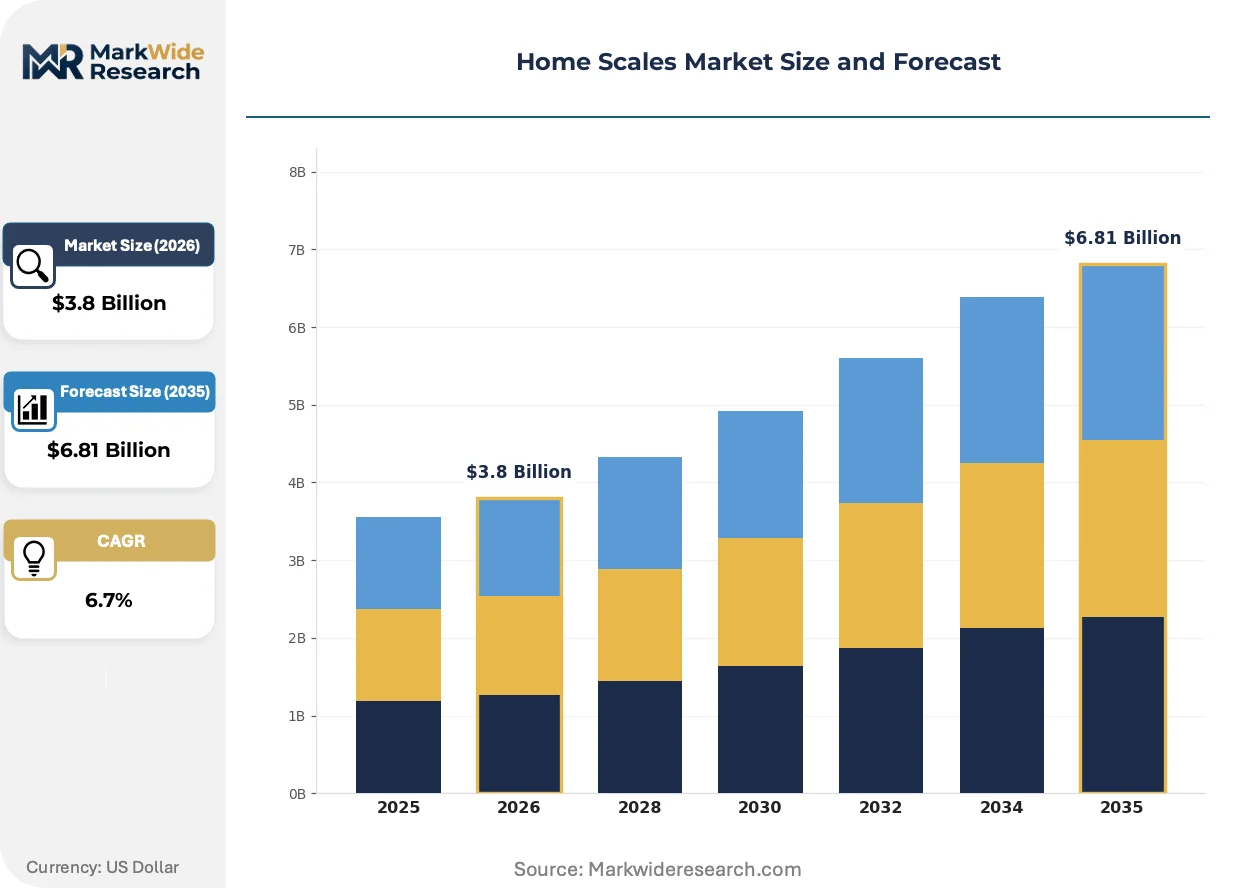
Market Dynamics
Connected fitness ecosystems are pulling smart scales into households faster than standalone purchases, while Europe's Ecodesign requirements force power system redesigns that eliminate standby waste. This dual pressure from demand-side platform integration and supply-side regulatory compliance defines current competitive positioning.
Growth Catalysts
- Platform Integration:Fitness apps from Apple Health to MyFitnessPal create data synchronization dependencies that lock users into hardware ecosystems. Smart scales with Bluetooth and Wi-Fi connectivity capture recurring engagement through automated logging.
- REACH Compliance:EU substance restrictions in electronics assemblies accelerate sensor housing material upgrades, pushing manufacturers toward certified supply chains that command premium positioning in German retail channels.
- Bioelectrical Impedance:Body composition analysis features expand addressable use cases beyond weight tracking into metabolic health monitoring, attracting nutritional professionals and athletic training facilities.
Market Restraints
- Strain Gauge Concentration:Asian contract manufacturers dominate precision sensor production, creating sourcing vulnerability as logistics complexity and component costs reshape procurement strategies.
- FDA Claim Constraints:United States marketing restrictions on body composition accuracy claims limit how manufacturers position bioelectrical impedance features, compressing differentiation space in North American channels.
- Mechanical Substitution:Spring-based scales persist in price-sensitive segments with thinning margin pools, constraining revenue expansion in emerging markets where digital adoption lags.
Strategic Opportunities
- German Premium Channel:Health-conscious consumers and strong retail infrastructure in Germany support digital scale adoption at higher average selling prices, particularly for medical-grade precision variants.
- Kitchen Professional Segment:Nutritional professionals and commercial food service operations demand gram-level accuracy that commands pricing premiums unavailable in consumer body scale markets.
- METI Certification Arbitrage:Japan's measurement accuracy requirements create non-tariff barriers that certified manufacturers can leverage to exclude uncertified competitors from high-integrity Asian markets.
Industry Challenges
- Sensor Calibration Expertise:In-house precision calibration capabilities remain scarce, forcing reliance on specialized technicians or automated systems that require substantial capital investment.
- Medical Device Reclassification Risk:Emerging biometric capabilities may trigger regulatory reclassification in major jurisdictions, fundamentally altering approval timelines and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Scales Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Scales, Mechanical Scales, Smart Scales, Kitchen Scales End User: Households, Fitness Enthusiasts, Nutritional Professionals, Health Clubs Technology: Bluetooth Enabled, Wi-Fi Enabled, Sensor Technology, Traditional Capacity: Up to 150 kg, Up to 200 kg, Up to 250 kg, Others |
| Companies Covered | Tanita, Philips, Taylor USA, Soehnle, Withings, Omron Healthcare, Garmin, Salter, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Scales Market Shifts & Advancements
Hardware-software integration is accelerating as scale manufacturers compete through data platform stickiness rather than standalone device margins. Three developments are compressing traditional competitive boundaries.
Multi-frequency bioelectrical impedance analysis is converging with cloud-based metabolic modeling to enable segmental body composition tracking. Athletic training facilities and sports medicine clinics are adopting these systems at accelerating rates. This convergence is compressing the boundary between consumer wellness devices and clinical assessment tools, forcing manufacturers to choose certification paths.
Europe's Ecodesign requirements are eliminating standby power consumption in connected scales, mandating redesigned power management systems. Manufacturers must reengineer circuit boards and sensor activation protocols to comply. German and French retail channels are responding by delisting non-compliant inventory ahead of enforcement deadlines.
Direct-to-consumer subscription models are displacing traditional retail distribution for premium connected scales. Hardware margins compress while recurring revenue from data analytics services expands. This shift is most visible in United States urban markets where fitness platform integration drives replacement cycles shorter than device functional lifespans.
Home Scales Market Segmentation
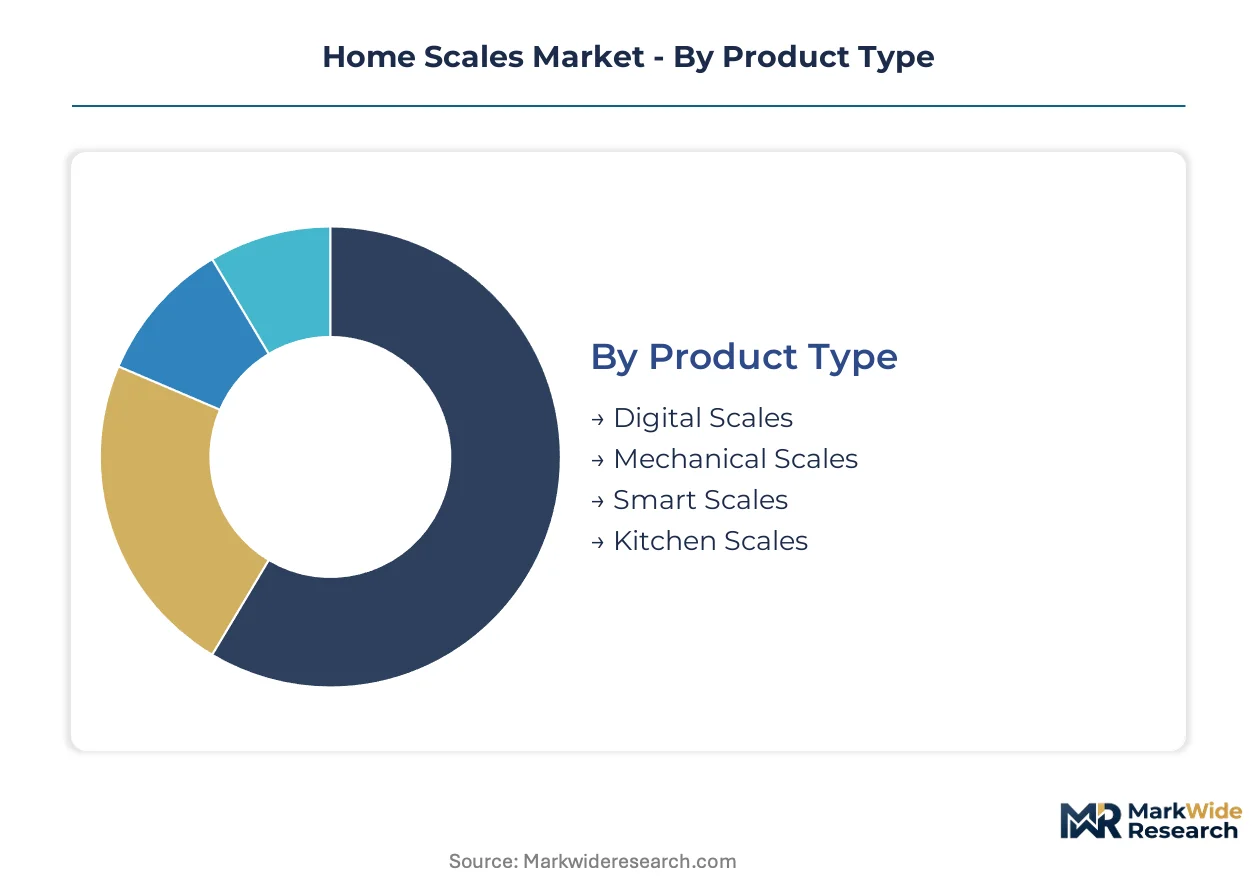
Home scales manufacturers face divergent capital requirements across product architectures, with sensor calibration infrastructure and connectivity modules driving investment thresholds. Segmentation reveals how capital intensity concentrates in precision electronics while mechanical alternatives sustain lower barriers to entry.
Product Type:
Smart scales demand the heaviest upfront capital outlays for embedded systems development and cloud platform integration, while mechanical variants require minimal tooling investment beyond spring fabrication and dial assembly.
- Smart Scales:Embedded Bluetooth and Wi-Fi modules enable real-time data synchronization with Apple Health, MyFitnessPal, and Garmin Connect ecosystems. Fitness enthusiasts in Germany and the United States drive replacement cycles shorter than functional lifespans as platform lock-in intensifies.
- Digital Scales:Strain gauge sensors with LCD displays deliver 0.1 kg precision without connectivity overhead. Households across price-sensitive European markets favor these units where Ecodesign standby power mandates have forced circuit board redesigns.
- Mechanical Scales:Spring-based analog systems persist in emerging markets with minimal margin pools.
- Kitchen Scales:Gram-level resolution targets nutritional professionals and commercial food service operations.
Digital scales absorb the bulk of installed capacity; smart scales are expanding most quickly.
End User:
Application context determines pricing power, with professional segments tolerating premium positioning for certified accuracy while household purchases remain discretionary and price-elastic.
- Nutritional Professionals:Registered dietitians and clinical nutritionists require NTEP-certified precision for patient meal planning and metabolic monitoring. These practitioners in Germany and Japan validate equipment purchases through reimbursement codes and professional liability requirements.
- Fitness Enthusiasts:Athletic consumers prioritize segmental body composition tracking and trend visualization over absolute accuracy. Garmin's GPS-linked ecosystem and Withings' cardiovascular health integrations capture this cohort through hardware-software bundling.
- Households:General wellness monitoring drives volume across mass retail channels.
- Health Clubs:Commercial durability and multi-user data management distinguish institutional procurement.
Households dominate unit shipments; nutritional professionals command the steepest price premiums.
Technology:
Connectivity infrastructure separates investment tiers, with RF engineering and security certification adding development cycles that traditional sensor platforms avoid entirely.
- Wi-Fi Enabled:Persistent cloud connectivity supports household-wide data access and firmware updates without smartphone proximity. These systems face FCC Part 15 emissions testing in the United States and CE RED compliance in Europe, extending certification timelines.
- Bluetooth Enabled:Lower power requirements suit battery-operated portable designs with smartphone-tethered workflows. Fitness app dependencies create stickier user relationships than standalone measurement devices.
- Sensor Technology:Multi-frequency bioelectrical impedance analysis enables segmental body composition estimation.
- Traditional:Unconnected strain gauge or mechanical architectures minimize regulatory exposure.
Bluetooth-enabled units capture the largest active installed base; Wi-Fi-enabled systems are climbing the fastest as household IoT density increases.
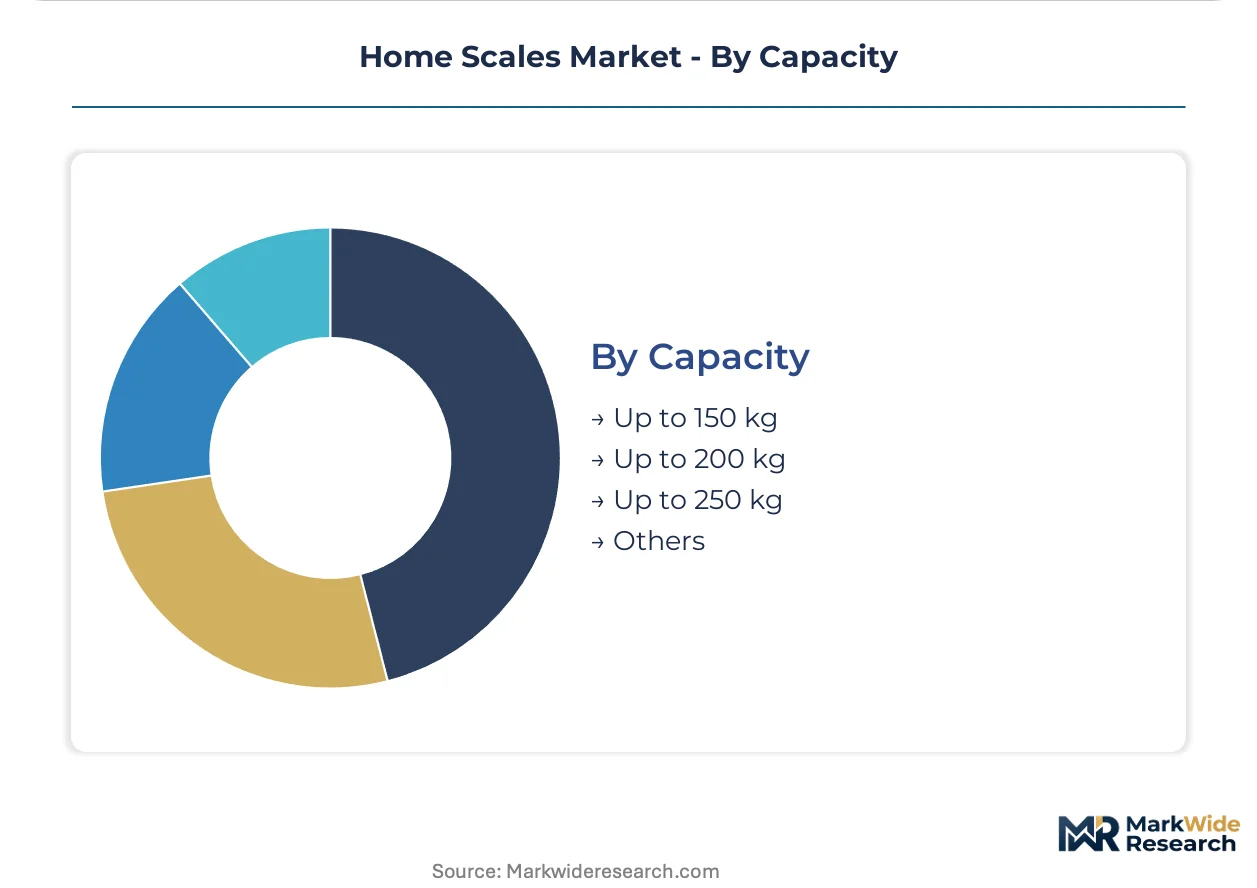
Capacity:
Load cell specifications and structural reinforcement requirements scale with rated capacity, with medical-grade 250 kg systems demanding specialized calibration protocols.
- Up to 250 kg:Bariatric medical applications and athletic training facilities require reinforced platforms with distributed load compensation. METI certification in Japan and FDA registration pathways in the United States impose additional validation burdens on manufacturers serving clinical segments.
- Up to 200 kg:Standard household coverage accommodates the 95th percentile of adult populations across OECD markets.
- Up to 150 kg:Compact designs dominate European and Asian residential bathrooms with space constraints.
- Others:Specialized industrial and veterinary applications fall outside standard consumer specifications.
Up to 200 kg variants anchor production volumes; up to 250 kg systems are gaining share fastest as medical applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strain gauge sensor fabrication concentrates in East Asian manufacturing clusters, with downstream assembly and calibration distributed across consumer markets. Platform integration mandates and Ecodesign compliance are redrawing competitive maps in Western Europe and North America.
Germany
Health-conscious households and dense pharmacy retail networks drive premium digital scale adoption. Ecodesign standby power regulations force circuit board redesigns ahead of enforcement deadlines. Stuttgart and Munich host precision sensor calibration facilities serving medical-grade equipment demand.
United States
Fitness platform ecosystems from Apple Health to MyFitnessPal lock users into hardware replacement cycles shorter than functional lifespans. FDA body composition claim constraints compress marketing differentiation space for bioelectrical impedance features. Boston and San Francisco anchor connected health device development clusters.
Japan
METI measurement accuracy certifications create non-tariff barriers protecting domestic manufacturers from uncertified imports. Aging demographics expand home health monitoring demand beyond traditional weight tracking. Osaka and Nagoya concentrate precision electronics assembly for both consumer and clinical segments.
China
Contract manufacturers decouple from Western branded vendors as logistics complexity and component costs reshape procurement strategies. GB standards for measurement instruments govern domestic market entry. Shenzhen and Dongguan dominate strain gauge production and Bluetooth module integration.
United Kingdom
Nutritional professional demand for NTEP-certified kitchen scales supports premium pricing unavailable in mass consumer channels. CE RED compliance extends certification timelines for Wi-Fi-enabled models. London and Manchester host registered dietitian networks validating equipment purchases through reimbursement codes.
Home Scales Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue platform-integrated subscription models. The vendor base spans medical precision specialists, consumer electronics conglomerates, and athletic ecosystem anchors. Three archetypes dominate: sensor calibration specialists, software-hardware integrators, and fitness platform subsidiaries. M&A activity concentrates on connectivity stack acquisitions; geographic expansion targets German and Japanese certification-heavy markets.
Within the precision calibration tier, Tanita exemplifies sustained technical differentiation through in-house sensor expertise. Among fitness ecosystem anchors, Withings and Garmin occupy positions defined by deep software-hardware integration and GPS-linked body composition tracking respectively. These three represent divergent strategic bets on medical-grade accuracy versus platform stickiness versus athletic user base lock-in.
| Leading Market Players |
|---|
| Tanita |
| Philips |
| Taylor USA |
| Soehnle |
| Withings |
| Omron Healthcare |
| Garmin |
| Salter |
| Fitbit |
| Others |
Supply & Pricing Matrix
Europe's Ecodesign standby power mandates gate qualified supply for premium-tier pricing access, forcing circuit board redesigns that eliminate non-compliant manufacturers from German and French retail channels. Component sourcing shifts toward certified supply chains that command positioning premiums unavailable to uncertified competitors.
Pricing Analysis
Warranty and calibration service bundling separates medical-grade precision tiers from unbundled consumer alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service depth. Cost compression in mechanical segments intensifies because Asian contract manufacturers compete on volume scale. Household buyers exhibit highest price sensitivity; nutritional professionals tolerate premiums for NTEP-certified accuracy.
Supply Chain Analysis
Single-source vulnerability sits with Chinese strain gauge sensor fabrication concentrated in Shenzhen and Dongguan manufacturing clusters. Raw material dependencies include precision aluminum load cells, Bluetooth RF modules, and REACH-compliant sensor housings. Tariff exposure on electronics assemblies threatens margin stability for Western branded vendors. Distribution runs through pharmacy retail networks in Germany and direct-to-consumer subscription channels in United States urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
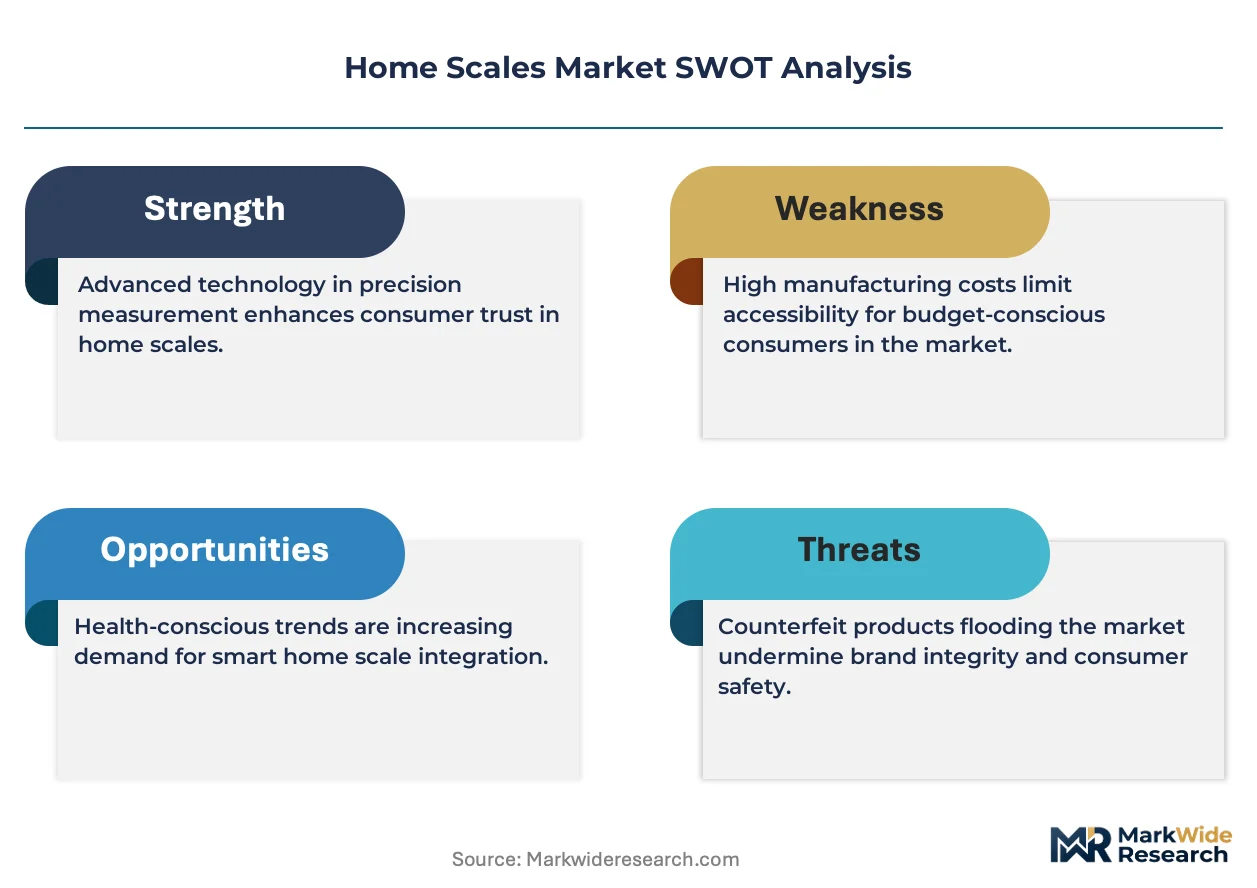
This market reads as a cost-of-compliance story where EU REACH substance restrictions create barrier-to-entry moats for manufacturers with certified supply chains and upgraded sensor housing materials.
For Market Incumbents: Anticipate medical device reclassification risk by securing FDA registration pathways and METI certification ahead of emerging biometric capability triggers. Defensive consolidation should prioritize backward integration into precision sensor calibration facilities in Stuttgart and Munich. Channel control through pharmacy retail networks in Germany insulates against direct-to-consumer subscription displacement. For New Entrants and Emerging Players: Enter via Wi-Fi-enabled kitchen scales targeting nutritional professionals in United Kingdom and Japan where NTEP and METI certifications command pricing premiums unavailable in mass consumer tiers. White-space opportunity concentrates in gram-level accuracy devices for commercial food service operations. Go-to-market leverage should emphasize reimbursement code validation through registered dietitian networks. For Investors and Strategic Acquirers: METI enforcement actions against uncertified imports are the leading indicator that certification-heavy markets are consolidating around compliant manufacturers. Long-term viability favors acquisition targets with in-house sensor calibration expertise and established regulatory pathways across FDA, REACH, and METI jurisdictions. Watch for connectivity stack acquisitions as fitness platform integration accelerates hardware-software bundling requirements.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification | Upgraded sensor housing materials unlock German pharmacy retail channel access. |
| Precision Calibration Facility Investment | In-house sensor expertise sustains Tanita's medical-grade positioning against contract manufacturers. |
| Platform Integration Partnership | MyFitnessPal and Apple Health synchronization creates stickier user replacement cycles. |
| Direct-to-Consumer Subscription Launch | Recurring analytics revenue offsets hardware margin compression in United States urban markets. |
| METI Certification Pathway | Measurement accuracy validation excludes uncertified competitors from Japanese home health monitoring demand. |
Research Methodology
Document review covered FDA 510(k) filings, EU Ecodesign implementing measures, and METI measurement accuracy standards, complemented by interviews with precision sensor calibration technicians, pharmacy retail category managers, and registered dietitian equipment procurement leads. Secondary validation drew from customs trade data, REACH substance restriction databases, and hospital GPO contract disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-level projections across smart, digital, mechanical, and kitchen scale architectures incorporate connectivity module cost curves and Ecodesign compliance investment requirements. Household, nutritional professional, fitness enthusiast, and health club end-use splits anchor demand-side modeling. CAGRs derived from historical replacement cycle analysis and platform integration adoption rates across Germany, United States, Japan, and China.
Forecast precision tightens around the base case; tail outcomes carry wider variance under medical device reclassification scenarios or accelerated Ecodesign enforcement timelines. Forecasts reflect assumptions about strain gauge sensor supply stability and fitness app ecosystem consolidation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
India Digital Showers Market
Household Items
Shoe Dryer Market
Household Items
Luxury Massage Chair Market
Household Items
Permanent Marker Market
Household Items
Electric Mop Market
Household Items
Turkey Cookware Market
Household Items
Japan Digital Showers Market
Household Items
Titanium Thermos Cup Market
Household Items
United Kingdom Air Purifier Market
Household Items
Countertop Market
Household Items
Infrared Sauna Heaters Market
Household Items
Smart Air Purifier Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
Range Hood Cleaning Service Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
Dishwasher Tablets Market