
 Toilet Deodorant Market | 2026-2036
Toilet Deodorant Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Deodorant Market Analytics
Commercial facility managers are rotating away from basic spray formats toward integrated odor-management systems that reduce labor costs. S. C. Johnson & Son leverages its institutional distribution network to sustain contracts with major hotel chains. Henkel anchors the European commercial segment with concentrated gel formulations. Kobayashi competes in East Asia through compact tablet designs optimized for high-density residential buildings.
Toilet deodorants are formulated products containing fragrance oils, surfactants, and masking agents designed to neutralize malodorous compounds in restroom environments, typically delivered through aerosol propellant, gel matrix slow-release, or automated timed-dispersion mechanisms. Spray formats remain the largest volume category though automatic dispenser systems capture expanding margin pools in commercial installations. Gel and tablet segments dominate residential replacement cycles where consumers prioritize shelf stability and discrete placement. Fragrance diversification toward ocean breeze and citrus profiles reflects hospitality sector preferences for fresh rather than floral scent signatures.
The U.S. EPA regulates volatile organic compound content in aerosol deodorants under Clean Air Act provisions, while the EU REACH framework restricts certain phthalate-based fragrance carriers, compelling reformulation across export-oriented manufacturers. Japan's Ministry of Economy, Trade and Industry oversees household product labeling standards that affect import eligibility for foreign brands. Stakeholders must monitor evolving chemical disclosure requirements as procurement specifications in commercial channels increasingly mandate ingredient transparency certification.
Market Dynamics
Commercial facility managers now prioritize integrated odor-management systems that reduce labor costs, forcing manufacturers to abandon standalone spray formats in favor of subscription-based dispenser networks with predictive refill algorithms.
Growth Catalysts
- EPA Safer Choice certification:Procurement specifications in U.S. hospitality chains now mandate ingredient transparency, redirecting contract awards toward reformulated low-VOC suppliers.
- China tier-one commercial real estate:Shanghai and Beijing institutional purchasers drive concentrated demand for automatic dispenser installations in premium office developments.
- Sensor-enabled refill systems:IoT-connected dispensers reduce maintenance visits by triggering alerts only when cartridges deplete, compressing operating costs for facility management firms.
Market Restraints
- Propellant cost volatility:Aerosol formats remain exposed to hydrocarbon feedstock fluctuations, squeezing margin on economy-tier spray products.
- EU REACH phthalate restrictions:Fragrance carrier reformulation adds six to nine months to product launch timelines for export-oriented manufacturers.
- DIY vinegar-baking soda substitutes:Residential consumers in cost-sensitive segments increasingly bypass branded deodorants for homemade alternatives.
Strategic Opportunities
- India tier-two urbanization:Hyderabad and Pune commercial construction creates first-mover advantage for automatic dispenser providers establishing service infrastructure.
- EU Green Deal procurement mandates:Public sector facility contracts now preference biodegradable gel matrices, opening institutional channels for compliant entrants.
- Subscription platform convergence:E-commerce direct-to-consumer models bypass traditional retail slotting fees, capturing replacement-cycle revenue in residential segments.
Industry Challenges
- Chemical formulation expertise scarcity:Rapidly shifting EPA and ECHA disclosure requirements outpace available toxicology assessment capacity at mid-tier manufacturers.
- Legacy dispenser retrofit complexity:Hotels and airports face wiring and mounting incompatibility when upgrading from mechanical to sensor-enabled systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Deodorant Market |
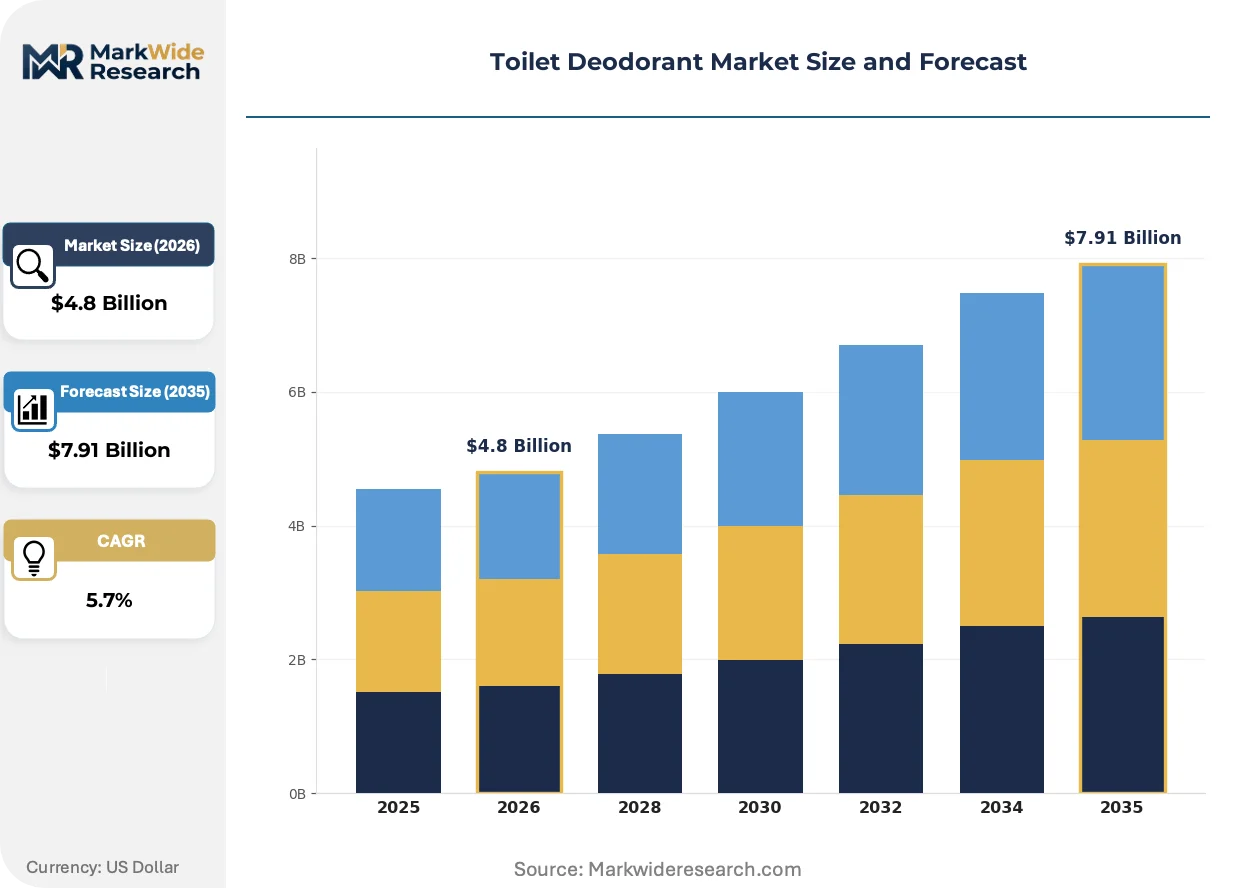
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Gel, Tablet, Automatic Dispenser Fragrance: Lavender, Citrus, Ocean Breeze, Pine End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops |
| Companies Covered | S. C. Johnson & Son, Reckitt Benckiser Group, Procter & Gamble, Henkel, Clorox, Good Maid, HAL Industry, Kao, Kobayashi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Deodorant Market Evolving Landscape
Formulation chemistry and delivery mechanisms are diverging sharply between premium commercial installations and mass residential channels, creating distinct innovation pathways with incompatible R&D investment profiles.
Electrochemical odor-neutralization technology is bifurcating the high-end commercial segment. These systems deploy catalytic oxidation rather than fragrance masking, eliminating consumable cartridge costs. Marriott and Hilton pilot programs in Texas and Florida properties demonstrate twelve-month payback periods against traditional gel systems. The technology is bifurcating supplier margins, compressing returns on conventional fragrance-delivery hardware while enabling premium pricing for integrated air-quality platforms.
EU REACH Annex XVII restrictions on phthalate-based carriers are forcing fragrance houses to accelerate bio-based solvent development. German and French formulators now submit full substance dossiers to ECHA eighteen months ahead of enforcement deadlines. Aerosol manufacturers serving export markets absorb the highest compliance burden, while gel and tablet formats bypass propellant regulations entirely.
Facility management outsourcing is consolidating purchasing authority into national procurement consortia. ISS and Sodexo now specify automatic dispenser performance metrics rather than product brands, unbundling hardware from consumable supply. This concentration is most visible in the United Kingdom, where NHS hospital trusts and university estates have standardized on three approved vendor platforms.
Toilet Deodorant Market Segmentation
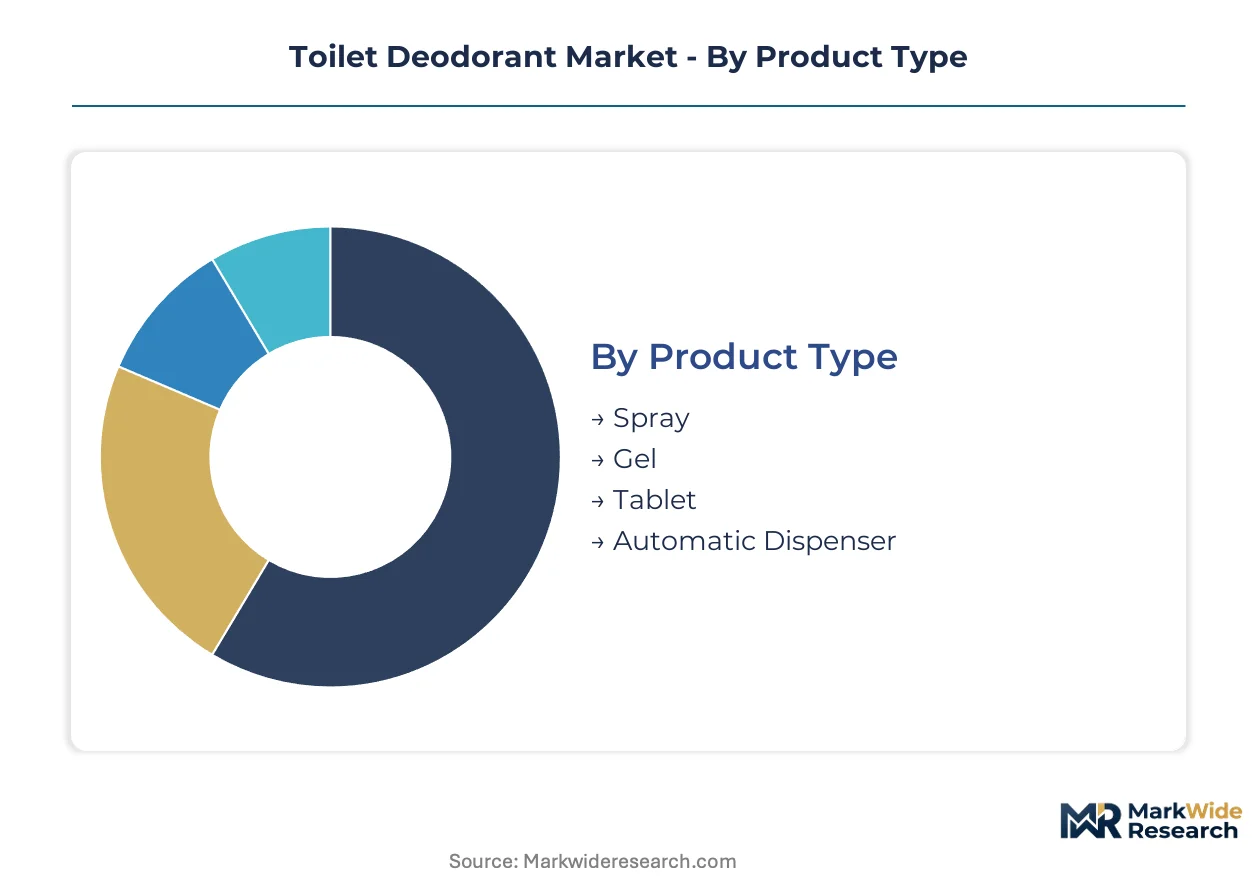
Product format selection determines regulatory exposure and margin structure across toilet deodorant categories. Fragrance profiles and distribution channels diverge sharply between institutional procurement contracts and residential replacement purchases.
Product Type:
Spray and gel formats dominate domestic manufacturing footprints, while automatic dispenser systems rely heavily on export-led component supply chains from East Asian electronics clusters.
- Spray:Aerosol propellant systems combine fragrance oils with hydrocarbon or compressed gas delivery mechanisms. Demand concentrates in U.S. mass retail and Latin American price-sensitive markets where EPA VOC regulations constrain formulation flexibility. Propellant cost volatility squeezes margin on economy-tier variants.
- Automatic Dispenser:IoT-enabled hardware with predictive refill algorithms reduces facility management labor costs. Procurement specifications from Marriott and Hilton in Texas and Florida properties prioritize sensor-enabled systems with twelve-month payback metrics against legacy gel installations.
- Gel:Slow-release matrix formulations bypass aerosol regulations entirely, anchoring European commercial adoption through concentrated refill cartridges.
- Tablet:Compact solid formats optimize for high-density residential buildings in East Asian urban markets where discrete placement and shelf stability drive replacement cycles.
Spray commands the established base. The steepest expansion runs through automatic dispenser systems.
Fragrance:
Scent selection stratifies across cost tiers, with premium hospitality procurement driving divergence from traditional floral profiles toward fresh signatures.
- Ocean Breeze:Synthetic marine accords dominate U.S. hospitality chain specifications. Marriott and Hilton procurement mandates favor fresh over floral signatures in guest bathroom installations.
- Citrus:Limonene-based formulations face EU REACH solvent restrictions, forcing German and French fragrance houses to accelerate bio-based carrier development eighteen months ahead of enforcement deadlines.
- Lavender:Traditional floral profile retains residential replacement demand in North American mass retail channels.
- Pine:Institutional janitorial supply contracts in educational and healthcare facilities specify forest-derived masking agents for perceived cleanliness association.
Lavender retains the installed base. Citrus climbs the fastest as hospitality procurement rotates toward fresh scent signatures.
End User:
Customer type determines volume scale and purchasing authority concentration, with outsourcing trends consolidating commercial buying power into national procurement consortia.
- Hospitality:Hotel chains now specify automatic dispenser performance metrics rather than product brands, unbundling hardware from consumable supply. ISS and Sodexo procurement consortia standardize on three approved vendor platforms in the United Kingdom.
- Office:Premium commercial real estate in Shanghai and Beijing drives institutional purchasing for integrated odor-management systems in new construction.
- Residential:Cost-sensitive consumers increasingly bypass branded deodorants for homemade vinegar-baking soda substitutes, compressing branded volume in economy tiers.
- Commercial:Broad facility management category encompassing retail, transportation, and public infrastructure with heterogeneous specification requirements.
Commercial captures the volume base. Hospitality gains share fastest through procurement consolidation and guest experience prioritization.
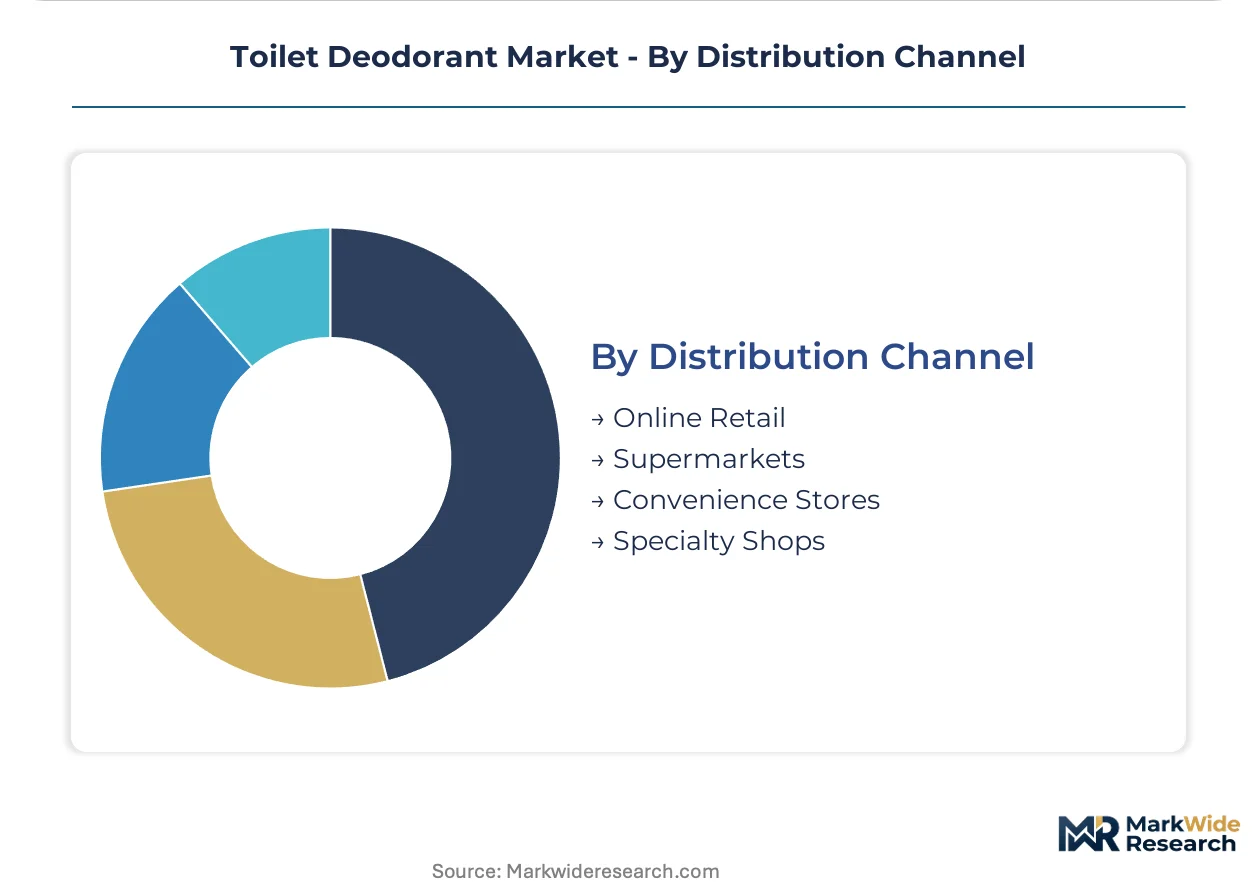
Distribution Channel:
Channel selection separates subscription-based recurring revenue models from traditional retail slotting fee structures.
- Online Retail:Direct-to-consumer platforms bypass retail slotting fees, capturing replacement-cycle revenue through subscription auto-replenishment algorithms.
- Supermarkets:Mass retail shelf space competition favors spray and gel formats with established household penetration metrics.
- Convenience Stores:Impulse purchase channel for travel-size and emergency replacement formats in urban convenience networks.
- Specialty Shops:Janitorial supply and hospitality procurement specialists service institutional contracts with specification compliance documentation.
Supermarkets anchor the volume base. Online retail expands most quickly through subscription platform convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European supply chain reliability for aerosol propellant feedstocks. Container throughput from Shanghai to Long Beach anchors trans-Pacific distribution of automatic dispenser hardware. The Dubai Logistics Corridor enables Middle East hospitality procurement consolidation.
United States
Marriott and Hilton procurement mandates in Texas and Florida properties prioritize sensor-enabled automatic dispensers with twelve-month payback metrics. EPA Safer Choice certification now redirects contract awards toward reformulated low-VOC suppliers in hospitality chains. The Port of Long Beach handles inbound electronics components for IoT-enabled dispenser manufacturing.
Germany
Henkel anchors European commercial adoption through concentrated gel formulations that bypass aerosol regulations entirely. ECHA REACH Annex XVII restrictions on phthalate-based carriers force fragrance houses to accelerate bio-based solvent development eighteen months ahead of enforcement. The Rhine-Ruhr industrial cluster concentrates formulation chemistry expertise for institutional supply contracts.
China
Shanghai and Beijing commercial real estate expansion drives institutional purchasing for integrated odor-management systems in premium office developments. MIIT household product labeling standards affect import eligibility for foreign brands entering tier-one cities. The Yangtze River Delta manufacturing base supplies compact tablet designs optimized for high-density residential buildings.
Japan
Kobayashi competes through compact tablet formats where discrete placement and shelf stability drive residential replacement cycles. METI oversees household product labeling standards that constrain formulation disclosure requirements for market entrants. Tokyo's dense urban housing stock concentrates demand for space-efficient deodorant delivery mechanisms.
United Kingdom
ISS and Sodexo procurement consortia standardize facility management purchasing on three approved vendor platforms across NHS hospital trusts and university estates. EU REACH framework compliance remains binding despite post-Brexit regulatory divergence. The Midlands logistics corridor distributes gel and spray formats to institutional janitorial supply networks.
Toilet Deodorant Market Competitive Landscape
Concentration sits with multinational consumer goods conglomerates that leverage institutional distribution networks and brand equity to sustain hospitality procurement contracts. The vendor base stratifies across three tiers: global FMCG houses with full-format portfolios, regional specialists dominating single geographies, and private-label manufacturers serving cost-sensitive retail channels. Competitive positioning hardens around EPA Safer Choice certification attainment and IoT-enabled dispenser hardware integration. Consolidation pressure intensifies as facility management outsourcing concentrates purchasing authority into national procurement consortia.
Among the named conglomerates, S. C. Johnson & Son, Henkel, and Kobayashi occupy distinct archetype positions. S. C. Johnson & Son exemplifies the institutional distribution model through sustained contracts with major hotel chains. Henkel represents the European commercial segment anchor with concentrated gel expertise. Kobayashi sits within the East Asian specialist tier optimized for compact residential formats.
| Leading Market Players |
|---|
| S. C. Johnson & Son |
| Reckitt Benckiser Group |
| Procter & Gamble |
| Henkel |
| Clorox |
| Good Maid |
| HAL Industry |
| Kao |
| Kobayashi |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for aerosol propellant feedstocks concentrate pricing power with Rotterdam and Houston chemical terminal operators, while automatic dispenser hardware draws from Shenzhen electronics clusters with divergent margin structures. This lead-time asymmetry separates fragrance formulation from IoT component sourcing, creating tiered procurement leverage across product formats.
Pricing Analysis
Volume-discount tiering structures separate hospitality procurement consortia from residential retail channels, with ISS and Sodexo extracting double-digit percentage concessions through multi-year consumable commitments. Pricing stratifies across premium sensor-enabled systems, standard gel cartridges, and economy spray formats, with EPA Safer Choice certification commanding measurable premiums in institutional segments. Cost compression in aerosol tiers intensifies because hydrocarbon feedstock volatility erodes manufacturer margins without corresponding price recovery mechanisms. Residential consumers exhibit highest price sensitivity, diverting to homemade substitutes, while hospitality chains prioritize total cost of ownership metrics over unit pricing.
Supply Chain Analysis
Strait of Malacca transit underwrites East Asian electronics component flows for automatic dispenser manufacturing, with Shenzhen and Guangzhou clusters dominating sensor and microcontroller assembly. Fragrance oil formulation draws from Grasse and New Jersey chemical corridors, while propellant supply rests on Rotterdam and Houston petrochemical infrastructure. Single-source vulnerability concentrates in lithium battery cells for IoT-enabled units, with Korean and Japanese suppliers anchoring cell production. Distribution runs through janitorial supply specialists for institutional channels and mass retail networks for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from predictive refill algorithms and cartridge subscription platforms expands faster than dispenser hardware sales, repositioning this market as a recurring-revenue opportunity rather than equipment transaction.
For Market Incumbents: Secure hospitality procurement consortia through exclusive sensor-enabled platform contracts that embed proprietary cartridge formats, locking out competing hardware vendors. Deepen backward integration into fragrance formulation chemistry to offset REACH compliance cost inflation and protect margin from raw material volatility. Electrochemical odor-neutralization pilots at Marriott and Hilton properties threaten traditional fragrance-delivery margins, demanding accelerated R&D investment in catalytic oxidation alternatives. For New Entrants and Emerging Players: Lead with biodegradable gel matrices targeting EU Green Deal procurement mandates in public sector facility contracts, where incumbent compliance lags create first-mover windows. Concentrate automatic dispenser service infrastructure in India tier-two cities before established vendors deploy field maintenance networks. Pursue direct-to-consumer subscription models bypassing retail slotting fees, capturing residential replacement-cycle revenue through auto-replenishment algorithms. For Investors and Strategic Acquirers: Long-term, this sits as a consumables-recurring play because cartridge replacement frequency generates predictable cash flows decoupled from new construction cycles. Target mid-tier manufacturers with EPA Safer Choice certification attainment and established institutional distribution relationships, as regulatory barriers compound acquisition value. Monitor electrochemical odor-neutralization pilot conversion rates at Texas and Florida hospitality properties as the inflection signal for technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Launch | Direct-to-consumer auto-replenishment captures recurring cartridge revenue outside retail slotting structures. |
| Electrochemical Technology Licensing | Catalytic oxidation pilots at Marriott properties demonstrate payback metrics against legacy gel installations. |
| REACH Compliance Certification | Full substance dossier submission to ECHA eighteen months ahead of phthalate restrictions secures EU market access. |
| India Tier-Two Service Buildout | Hyderabad and Pune commercial construction creates first-mover infrastructure advantage for automatic dispenser providers. |
| Backward Integration into Formulation | In-house fragrance chemistry development offsets carrier reformulation costs from EPA and ECHA disclosure requirements. |
Research Methodology
Operator-level perspectives from facility management directors, hospitality procurement leads, janitorial supply distributors, and fragrance house formulators anchored the qualitative base for this study. Primary fieldwork combined structured interviews with these stakeholders against secondary validation through EPA Safer Choice certified product registries, ECHA REACH substance dossiers, and hospitality chain sustainability reports. Customs data from Rotterdam and Long Beach terminals, alongside commercial real estate development permits from Shanghai and Beijing planning authorities, supplied trade flow and demand indicators. Bottom-up segment sizing triangulated against top-down macroeconomic consumption models.
Sensitivity analysis tested forecast outputs across propellant cost volatility scenarios, REACH enforcement timing variations, and hospitality construction cycle assumptions throughout the projection horizon. The analytical framework modeled product format, fragrance profile, end-user category, and distribution channel dimensions, with IoT adoption rates and regulatory compliance tiers as cross-cutting variables. CAGRs derived from historical volume trajectories adjusted for segment-specific penetration ceilings and replacement-cycle frequencies. Electrochemical technology diffusion curves and subscription platform conversion rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement and EU REACH Annex XVII implementation; material policy shifts would require re-modeling across aerosol and gel format demand projections. Practitioners should keep alternative scenarios live as electrochemical pilot outcomes and India urbanization trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bladeless Neck Fan Market
Household Items
Folded Tissues Market
Household Items
Bristle Brush Market
Household Items
Plastic Bathtub Market
Household Items
Global Humidifier Market
Household Items
Collapsible Water Bottle Market
Household Items
Consumerware Market
Household Items
Book Light Market
Household Items
Air Care Market
Household Items
Thermos Bottle Market
Household Items
Disposable Cutlery Market
Household Items
Washing Machine Cleaner Market
Household Items
Nebulizing Diffuser Market
Household Items
Water Purifier Bottle Market
Household Items
Automatic Dishwashing Products Market
Household Items
Portable Iron Market