
 Bone Supplements Market | 2026-2036
Bone Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Supplements Market Insights
FDA's updated dietary supplement labeling rules is restructuring cost-of-entry calculus for bone supplement manufacturers, forcing smaller brands to invest heavily in analytical testing and documentation. Herbalife International of America, Inc. leverages its direct-selling infrastructure to sustain margins amid rising compliance costs. GNC Holdings, LLC anchors its competitive stance through specialty retail channel control and in-house quality certification programs. Nature's Bounty differentiates via vertical integration into raw material sourcing, reducing third-party dependency.
Bone supplements encompass orally administered nutritional formulations containing calcium, vitamin D, magnesium, or collagen peptides, typically manufactured through spray-drying, granulation, or microencapsulation processes to enhance bioavailability and shelf stability; their primary commercial purpose is to support skeletal mineral density and reduce fracture risk in populations with inadequate dietary intake or age-related bone loss. Calcium formulations occupy the largest product type position due to decades of clinical validation and physician recommendation patterns. Gummy and liquid forms are gaining fastest within the form dimension, reflecting consumer preference shifts away from traditional pill fatigue, particularly among senior and pediatric end users where swallowing difficulties create compliance barriers.
FDA's Current Good Manufacturing Practice regulations, combined with FTC advertising substantiation requirements and USP verification standards, collectively elevate quality thresholds and create defensive moats for established manufacturers with dedicated regulatory affairs teams. The National Institutes of Health Office of Dietary Supplements further shapes demand through its consumer-facing fact sheets that influence physician counseling behavior. Stakeholders must monitor whether emerging state-level ingredient disclosure mandates fragment compliance requirements beyond federal baselines.
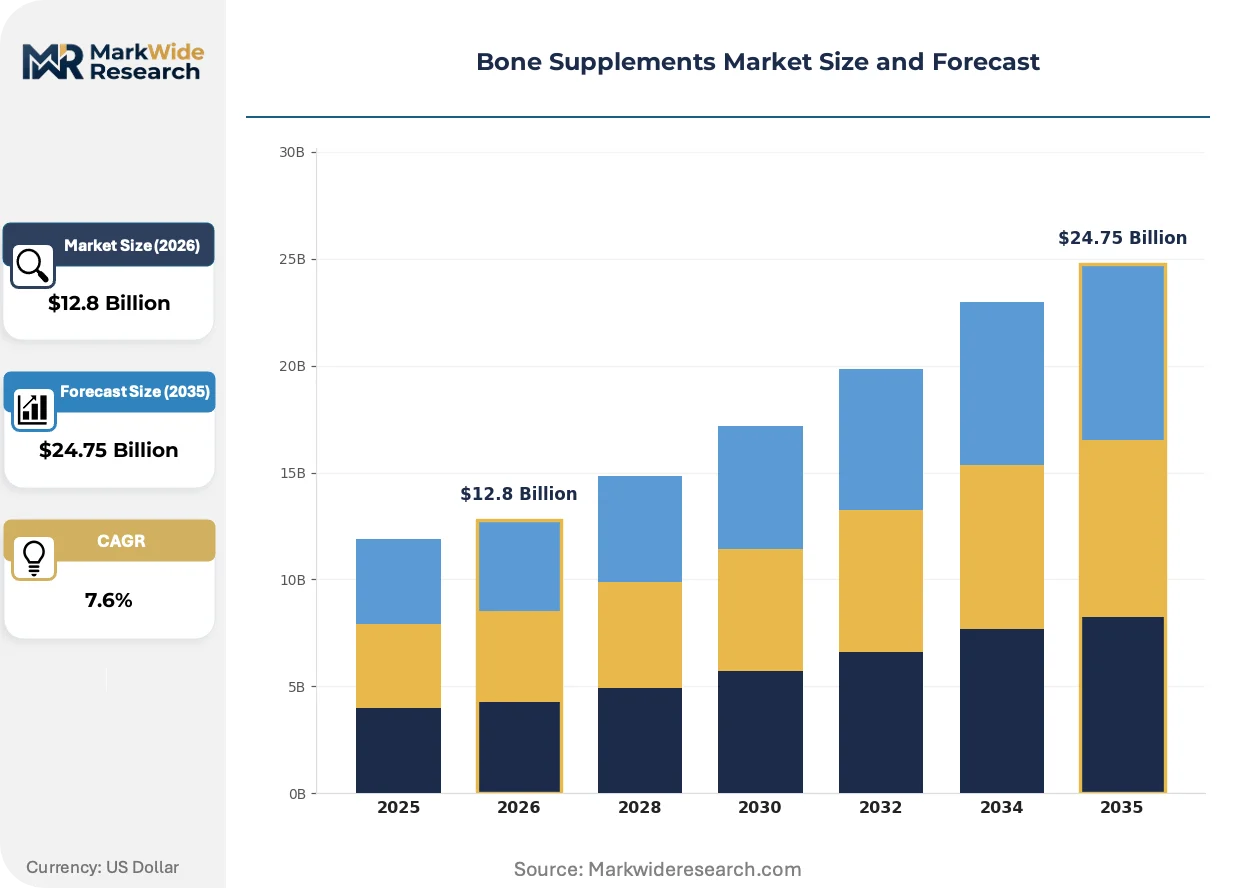
Market Dynamics
FDA's Current Good Manufacturing Practice enforcement is compressing the supplier base for bone supplement manufacturers, as smaller operators lack capital for analytical testing infrastructure and dedicated regulatory affairs teams.
Growth Catalysts
- Calcium-vitamin D combination formulations:Clinicians in the United States increasingly prescribe these combinations for postmenopausal osteoporosis management, driving pharmacy channel volume.
- Medicare Advantage preventive coverage expansion:Plan administrators in Florida, California, and Texas now reimburse bone density screening-linked supplement purchases, reducing out-of-pocket friction for seniors.
- Microencapsulation technology:This process enhances bioavailability of magnesium and collagen peptides, enabling manufacturers to differentiate through absorption claims validated by USP verification.
Market Restraints
- Algal calcium raw material concentration:Seventy percent of marine-derived calcium carbonate originates from Icelandic and Norwegian processing facilities, creating geographic supply vulnerability.
- FDA-FTC dual enforcement friction:Advertising substantiation requirements for structure-function claims demand clinical trial investment that excludes sub-$10 million revenue manufacturers.
- Food-first dietary guidance:NIH Office of Dietary Supplements consumer messaging emphasizes dairy and leafy green consumption over supplementation for adequate calcium intake.
Strategic Opportunities
- Pediatric gummy formulation white space:Children with lactose intolerance in suburban United States school districts represent an underserved segment with parental willingness to pay premium prices.
- Direct-to-clinic distribution bypass:Orthopedic practices in Arizona and Nevada are building in-house dispensaries, cutting retail pharmacy margin extraction.
- IRA preventive health incentive alignment:Medicare plan sponsors can structure supplemental benefit packages around bone health without statutory coverage restrictions.
Industry Challenges
- Analytical chemistry talent scarcity:USP verification programs require HPLC and ICP-MS competency that competes with pharmaceutical quality control salaries.
- Lot-to-lot consistency certification:NSF International and USP verification timelines extend 14-18 months, freezing inventory capital and delaying revenue recognition.
- Spray-drying equipment lead times:Stainless steel fluid bed dryers from specialized German and Italian suppliers now quote 26-week delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Supplements Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $24.75 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium, Vitamin D, Magnesium, Collagen Form: Tablets, Powder, Liquid, Gummies End User: Adults, Seniors, Children, Athletes Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Herbalife International of America, Inc., GNC Holdings, LLC, Nature's Bounty, Amway, Abbott Laboratories, Nestle Health Science, Bayer AG, Glanbia plc, Solgar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Supplements Market Trends and Innovations
Formulation science and distribution architecture are diverging from legacy pill-centric models, creating openings for bioavailability-enhanced delivery systems and clinically integrated purchase channels.
Collagen peptide hydrolysates are expanding into the senior nutrition segment as functional ingredients with dual claims for joint and bone matrix support. Geriatric dietitians in Medicare Advantage-contracted clinics now recommend these formulations alongside traditional mineral supplements. This convergence is compressing the historical separation between orthopedic and nutritional supplement prescribing behaviors.
FTC's 2023 Health Products Compliance Guidance is requiring randomized controlled trial evidence for bone density improvement claims, eliminating reliance on observational epidemiology. Mid-sized manufacturers are responding by funding investigator-initiated studies at academic medical centers. The gummy and liquid form categories face the steepest evidentiary burden given their targeting of compliance-challenged populations.
Subscription-based replenishment models are displacing retail pharmacy impulse purchases among diagnosed osteopenia patients. Digital health platforms integrated with DEXA scan providers in Minnesota and Wisconsin are capturing these buyers through automated refill algorithms. This channel shift is most visible in upper-income zip codes where concierge medicine practices bundle supplements into annual wellness contracts.
Bone Supplements Market Segmentation
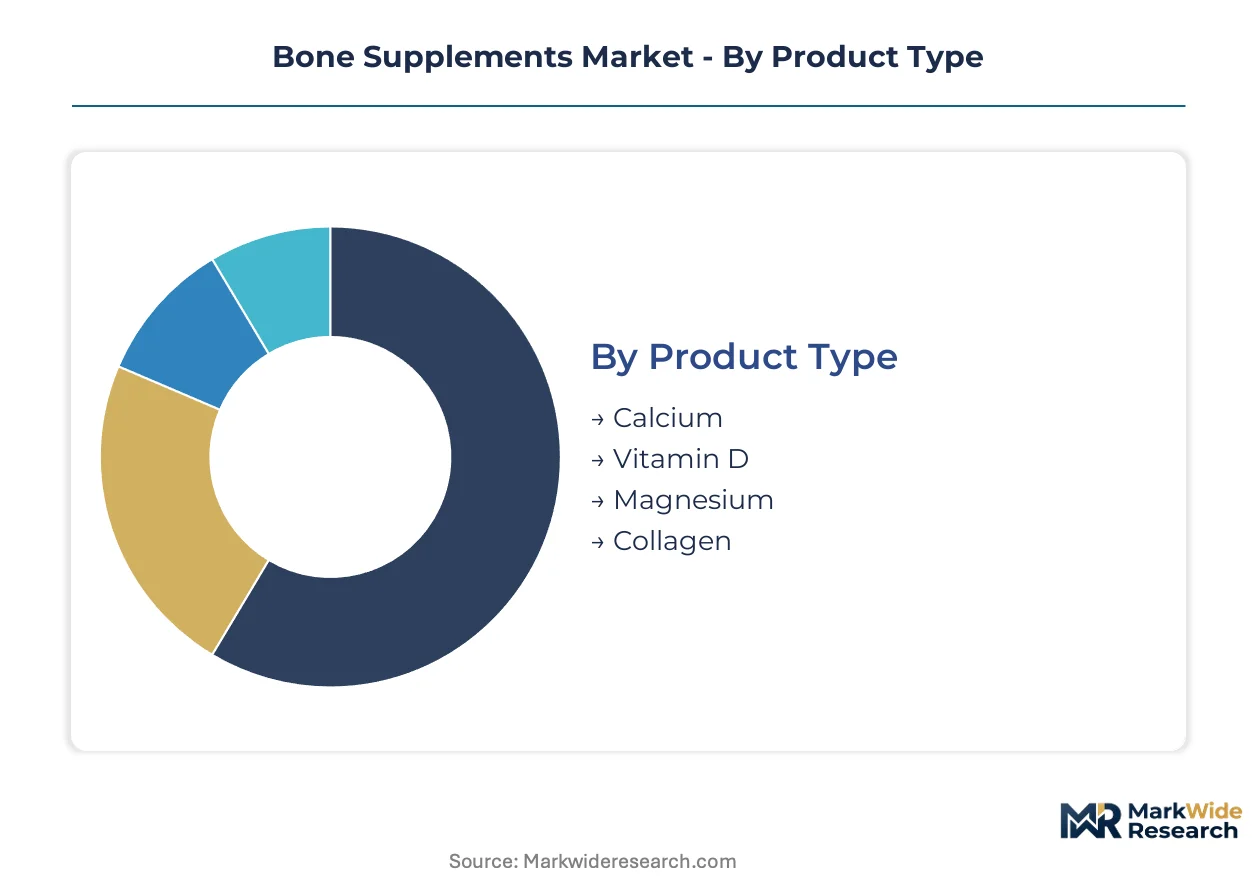
Bone supplement manufacturers configure production assets around bioavailability requirements and swallowing compliance barriers. Segment-level capital allocation determines which formulations absorb spray-drying and microencapsulation investments.
Product Type:
Calcium formulations demand the heaviest analytical chemistry infrastructure for USP verification and lot-to-lot consistency certification.
- Calcium:Carbonate and citrate salts dominate pharmacy channel prescribing patterns. Postmenopausal women in Medicare Advantage-contracted clinics drive volume through clinician recommendations tied to DEXA screening protocols.
- Vitamin D:Cholecalciferol and ergocalciferol variants require oil-based microencapsulation to prevent oxidation. Florida and Arizona seniors with limited sun exposure represent concentrated demand clusters within pharmacy benefit structures.
- Magnesium:Oxide and glycinate forms serve niche absorption-sensitive consumers. Athletes in performance-focused retail channels seek these for muscle-bone recovery synergy.
- Collagen:Peptide hydrolysates require enzymatic processing infrastructure. Geriatric dietitians in Minnesota and Wisconsin bundle these with mineral supplements for dual joint-bone matrix claims.
Calcium absorbs the bulk of installed capacity; collagen is expanding most quickly.
Form:
Manufacturing equipment lead times and stainless steel fluid bed dryer procurement differentiate capital requirements across delivery formats.
- Tablets:Direct compression and wet granulation lines represent sunk-cost legacy infrastructure. Pharmacy chains in suburban United States school districts rely on this form for cost-efficient pediatric and senior compliance programs.
- Gummies:Gelatin and pectin-based formulations require specialized molding and coating equipment. Children with lactose intolerance in Arizona and Nevada suburban districts command parental premium willingness-to-pay for palatable alternatives.
- Liquid:Emulsion stability testing extends quality control timelines. Swallowing-challenged seniors in Florida Medicare Advantage plans drive demand through concierge medicine bundling.
- Powder:Spray-dried and agglomerated variants serve bulk and sports nutrition channels. Athletes in direct-to-consumer subscription models favor unflavored collagen peptides for stackable dosing flexibility.
Tablets retain dominant share; gummies are climbing the fastest as pill fatigue reshapes senior and pediatric purchasing.
End User:
Customer acquisition economics vary sharply by age cohort compliance behavior and insurance coverage integration.
- Seniors:Medicare Advantage preventive benefit alignment reduces out-of-pocket friction. Florida, California, and Texas plan administrators now reimburse bone density screening-linked purchases.
- Adults:Diagnosed osteopenia patients in Minnesota and Wisconsin subscribe through DEXA-integrated digital health platforms. Automated refill algorithms capture this preventive-intervention window.
- Children:Lactose intolerance prevalence in suburban United States districts creates formulation gaps. Gummy and liquid palatability determines parental repurchase rates.
- Athletes:Performance-oriented magnesium and collagen stacking drives sports specialty channel volume. Direct-to-consumer brands compete on absorption claim differentiation verified by NSF International.
Seniors command the largest addressable base; children represent the steepest expansion trajectory for compliance-optimized formats.
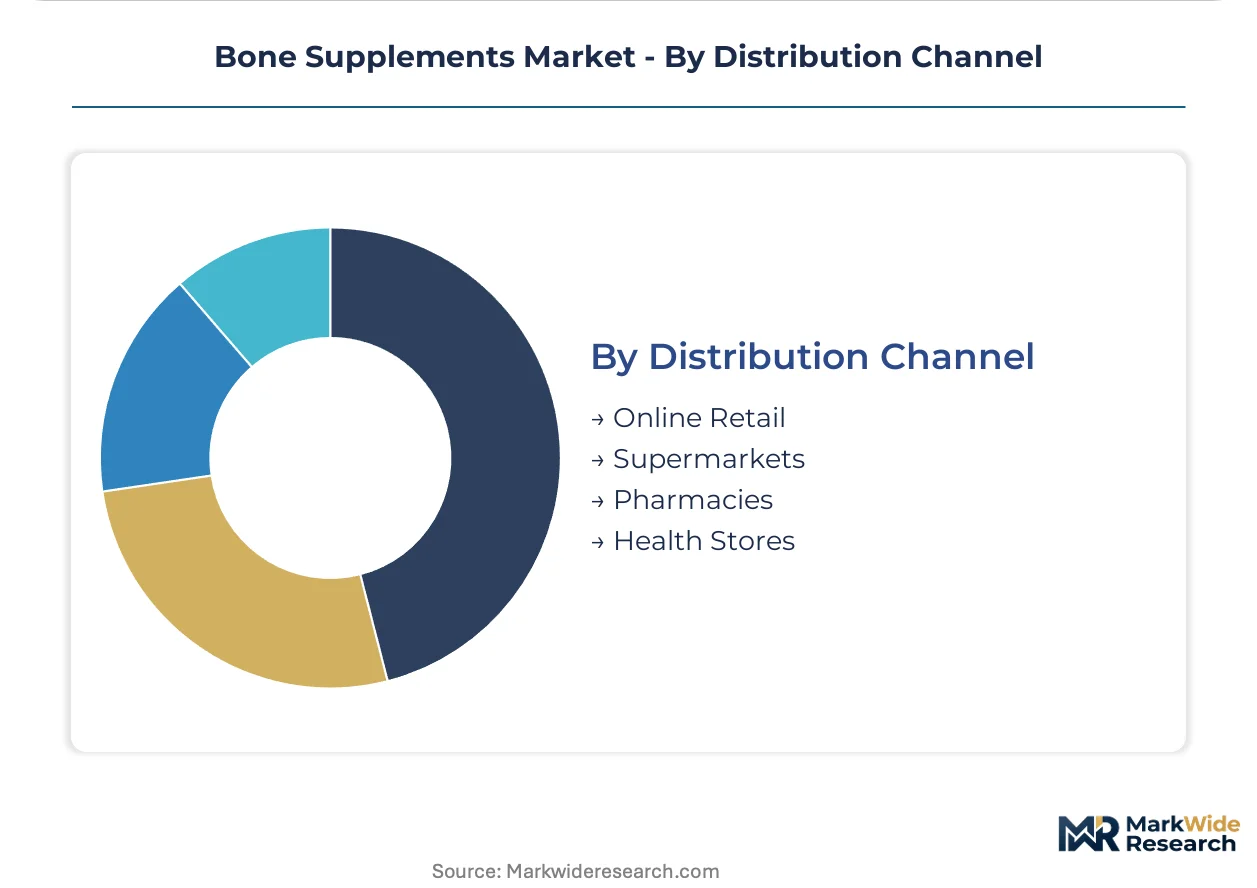
Distribution Channel:
Margin extraction patterns and inventory capital requirements structure channel selection for emerging versus established manufacturers.
- Pharmacies:Clinician recommendation pathways and insurance adjudication systems anchor calcium-vitamin D volume. Arizona and Nevada orthopedic practices are building in-house dispensaries to bypass retail margin layers.
- Online Retail:Subscription replenishment algorithms and DEXA data integration enable automated compliance. Upper-income zip codes in concierge medicine markets show highest conversion rates.
- Health Stores:Specialty retail certification programs and in-house quality testing defend shelf positioning. GNC Holdings anchors this channel through controlled distribution.
- Supermarkets:Mass-market calcium SKUs compete on price-per-serving metrics. Out-of-stock rates for gummy formats run higher due to seasonal demand volatility.
Pharmacies retain the deepest clinical integration; online retail is gaining share fastest through subscription mechanics and data-driven replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in developed economies where aging demographics intersect with preventive health insurance structures. Medicare Advantage plan administrators in Florida, California, and Texas now reimburse bone density screening-linked supplement purchases. Regulatory enforcement intensity varies sharply by jurisdiction, fragmenting compliance cost structures.
United States
Medicare Advantage preventive benefit expansion drives pharmacy channel volume for calcium-vitamin D combinations. FDA's Current Good Manufacturing Practice regulations compress the supplier base through analytical testing infrastructure requirements. Minnesota and Wisconsin host DEXA-integrated digital health platforms capturing diagnosed osteopenia patients through automated refill algorithms.
Germany
Aging demographics and physician counseling patterns sustain demand for bioavailability-enhanced magnesium formulations. EFSA health claim substantiation requirements elevate documentation burdens for structure-function claims. Bavaria and Baden-Württemberg concentrate spray-drying equipment suppliers serving contract manufacturing demand.
Japan
Postmenopausal osteoporosis management protocols emphasize collagen peptide co-administration with mineral supplements. PMDA and METI oversight of functional food labeling creates dual-track compliance for supplement-fortified beverages. Kanto region houses enzymatic processing infrastructure for peptide hydrolysate production.
China
Pediatric lactose intolerance prevalence in urban districts generates formulation demand for palatable delivery formats. NMPA dietary supplement registration requirements extend product approval timelines. Yangtze River Delta clusters microencapsulation technology providers serving domestic and export markets.
India
Rising geriatric populations in metropolitan areas expand addressable base for fracture-risk reduction products. FSSAI fortification standards and BIS quality certification create layered compliance obligations. Maharashtra and Gujarat host granulation and tablet compression capacity serving price-sensitive mass-market segments.
Bone Supplements Market Competitive Landscape
United States producers anchor one tier through direct-selling infrastructure and pharmacy channel integration; European specialists hold formulation science positioning through bioavailability patents and certification programs. The market structures around three tiers: multinational pharmaceutical conglomerates with dedicated nutraceutical divisions, mid-cap supplement pure-plays with vertical supply control, and contract manufacturers serving private-label demand. Consolidation pressures concentrate among mid-tier players lacking regulatory affairs scale. Dominant competitive moves include backward integration into raw material sourcing and specialty retail channel control.
Within the direct-selling archetype, Herbalife International of America, Inc. and Amway occupy positions leveraging person-to-person distribution to sustain margins amid compliance cost inflation. Among specialty retail anchored players, GNC Holdings, LLC exemplifies channel control strategies through in-house quality certification programs. Nature's Bounty represents backward integration into captive raw material supply, reducing third-party dependency for carbonate and citrate salt procurement.
| Leading Market Players |
|---|
| Herbalife International of America, Inc. |
| GNC Holdings, LLC |
| Nature's Bounty |
| Amway |
| Abbott Laboratories |
| Nestle Health Science |
| Bayer AG |
| Glanbia plc |
| Solgar Inc. |
| Others |
Pricing and Supply Chain Analysis
Microencapsulation technology adoption is simultaneously elevating production cost structures and concentrating manufacturing capability among capitalized producers capable of absorbing stainless steel fluid bed dryer procurement and extended quality control timelines. This process intensification creates pricing power asymmetries between USP-verified incumbents and sub-scale competitors facing 14-18 month certification freezes on inventory capital.
Pricing Analysis
Volume concentration in mass-market calcium carbonate tablets compresses per-unit margins, while premium absorption-claim gummies and liquids sustain markup tiers through palatability differentiation and concierge medicine bundling. Price differentiation hinges on USP verification status and bioavailability validation investment, with certified brands commanding shelf positioning premiums. Pricing pressure intensifies in supermarket channels where seasonal demand volatility strains working capital for gummy format producers. Pediatric end users in suburban school districts exhibit highest price sensitivity, whereas swallowing-challenged seniors in Medicare Advantage-integrated concierge practices show lowest elasticity.
Supply Chain Analysis
Domestic-content mandates in India's FSSAI fortification standards and China's NMPA registration pathways are reshaping raw material sourcing toward localized granulation and enzymatic processing infrastructure. Supply concentrates in Iceland and Norway for algal calcium carbonate, Germany and Italy for spray-drying equipment, and the Yangtze River Delta for microencapsulation technology providers. Raw material dependencies span marine-derived calcium carbonate, collagen peptide hydrolysates, and oil-based cholecalciferol carriers. Single-source vulnerability in Icelandic algal processing facilities exposes carbonate-dependent manufacturers to geographic disruption. Distribution runs through pharmacy chains with clinician recommendation pathways, though orthopedic in-house dispensaries in Arizona and Nevada are extracting direct-to-clinic volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance scale, with FDA Current Good Manufacturing Practice enforcement and FTC advertising substantiation requirements forcing sub-$10 million revenue manufacturers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into captive carbonate and citrate salt sourcing to insulate margin structures from Icelandic algal supply concentration, while expanding in-house quality certification programs to defend specialty retail shelf positioning against private-label encroachment. Invest dedicated regulatory affairs team scale to absorb 14-18 month USP verification timelines that freeze competitor inventory capital. For New Entrants and Emerging Players: IRA preventive health incentive alignment in Medicare Advantage plan structures opens a window for direct-to-clinic distribution bypass targeting orthopedic practices building in-house dispensaries in Arizona and Nevada. Pediatric gummy formulation white space in suburban United States school districts offers penetrable entry with parental premium willingness-to-pay for lactose intolerance alternatives. Pursue investigator-initiated study funding at academic medical centers to satisfy FTC randomized controlled trial requirements for absorption claims. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier pure-plays lacking regulatory affairs scale but holding vertical raw material control or DEXA-integrated digital health platform relationships. Long-term viability favors manufacturers with USP verification infrastructure and subscription-based replenishment algorithm capabilities. Monitor NSF International and USP verification program expansion timelines as inflection indicators for inventory capital efficiency differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| USP Verification Program Investment | Defensive moat creation through 14-18 month certification barriers that freeze competitor working capital. |
| Direct-to-Clinic Distribution Buildout | Margin extraction from orthopedic practices in Arizona and Nevada bypassing retail pharmacy layers. |
| Microencapsulation Technology Licensing | Bioavailability claim differentiation for magnesium and collagen peptide formulations in performance channels. |
| Pediatric Gummy Formulation Development | Palatability premium capture in suburban United States school districts with lactose intolerance prevalence. |
| Subscription Replenishment Algorithm Integration | Automated compliance capture of diagnosed osteopenia patients through DEXA-data-linked digital health platforms. |
Research Methodology
Multi-period observation of USP verification program expansion, Medicare Advantage preventive benefit reimbursement patterns, and spray-drying equipment procurement lead times anchored the trend analysis, supplemented by interviews with regulatory affairs directors at supplement manufacturers, pharmacy benefit administrators, orthopedic practice managers, and geriatric dietitians in Medicare-contracted clinics. Secondary validation drew from FDA Current Good Manufacturing Practice guidance documents, FTC Health Products Compliance Guidance, NIH Office of Dietary Supplements consumer messaging archives, and NSF International certification timelines. Bottom-up demand modeling across end-user segments triangulated against top-down value chain analysis.
Segment-weighting approaches distributed forecast contributions across calcium, vitamin D, magnesium, and collagen peptide product types; tablet, gummy, liquid, and powder delivery forms; senior, adult, pediatric, and athlete end users; and pharmacy, online retail, health store, and supermarket channels. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions across the analysis window. Industry-specific inputs included DEXA screening protocol penetration rates in Medicare Advantage plans and algal calcium raw material supply concentration metrics.
The model assumes a particular technology adoption path for microencapsulation and spray-drying process intensification; alternative pathways for enzymatic collagen peptide hydrolysate production would alter the outlook for bioavailability claim differentiation. Forecasts reflect assumptions around FDA-FTC dual enforcement intensity and Medicare preventive benefit expansion trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Micronutrient Powders (Mnps) Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Camu Camu Extract Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
India Personalized Nutrition Market