
 Marketing Automation Market | 2026-2036
Marketing Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Marketing Automation Market Intelligence
Subscription-based financing and usage-based leasing models are tilting competitive entry barriers downward, allowing mid-tier vendors to challenge incumbents without massive upfront capital. Adobe leverages its creative cloud ecosystem to anchor cross-sell momentum into marketing automation suites. Salesforce sustains dominance through its CRM-native architecture that embeds workflow automation inside existing customer data infrastructure. HubSpot differentiates through freemium-to-paid conversion mechanics that lower customer acquisition costs for small and mid-sized businesses.
Marketing automation comprises software platforms that orchestrate repetitive promotional tasks through rule-based triggers, behavioral scoring algorithms, and multi-channel campaign sequencing across email, social, and web touchpoints. These systems typically process first-party data through API-connected customer data platforms to deliver personalized messaging at scale for revenue operations teams. Email marketing retains the largest installed base among product type segments, though social media automation captures the fastest growth as short-form video channels expand advertiser tooling. Cloud-based deployment dominates new implementations, while hybrid configurations persist in regulated end user verticals such as healthcare where patient data residency requirements constrain pure SaaS adoption.
The EU AI Act and GDPR shape European platform architecture through mandatory algorithmic transparency disclosures and consent audit trails, while the US Federal Trade Commission scrutinizes deceptive automated messaging practices under Section 5 enforcement. India's Digital Personal Data Protection Act is now compelling multinational vendors to localize data processing infrastructure for education and retail clients operating in that jurisdiction. Stakeholders must monitor how fragmented privacy regimes fragment product roadmaps and inflate compliance engineering costs.
Market Dynamics
Enterprise B2B SaaS procurement teams are compressing vendor evaluation cycles from eighteen months to under six, forcing platform providers to demonstrate immediate workflow integration rather than long-term transformation roadmaps.
Growth Catalysts
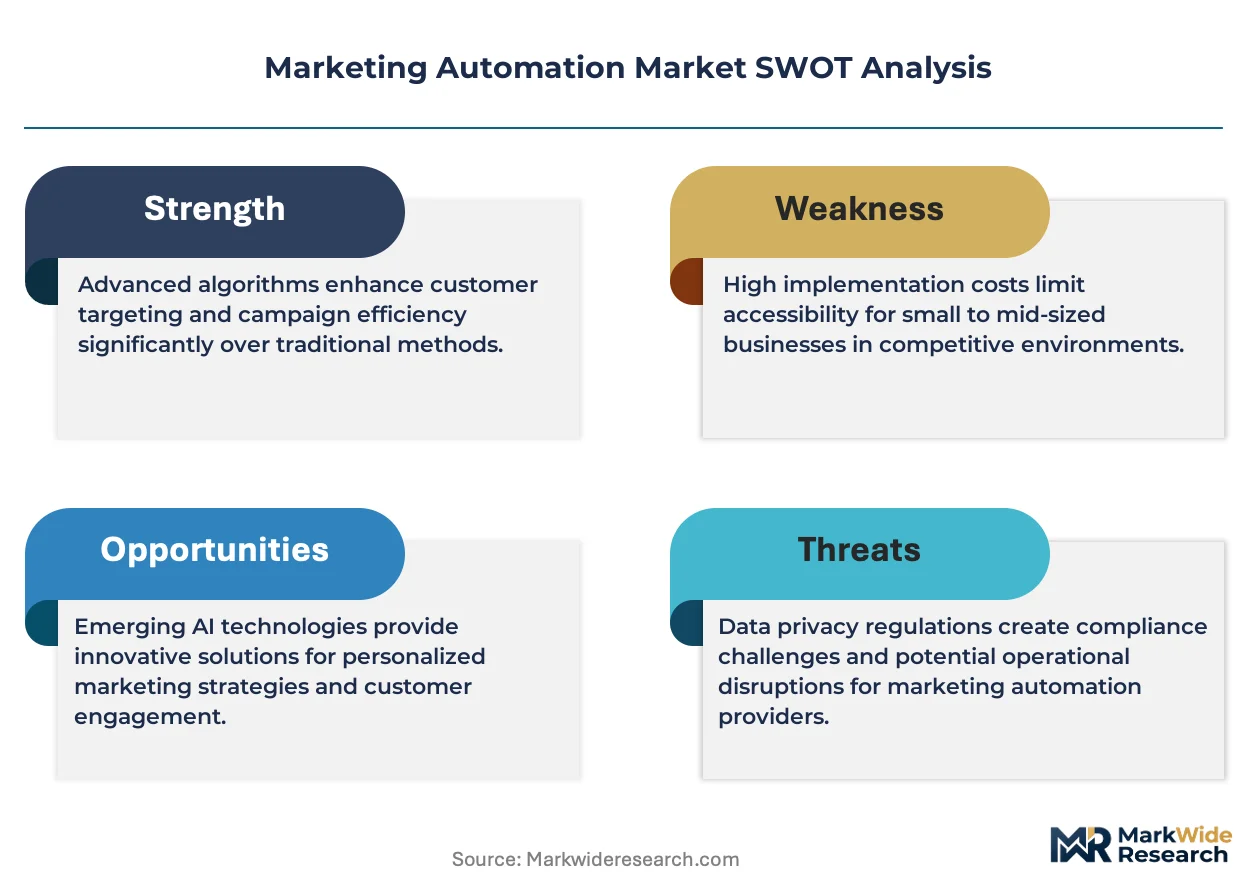
- EU AI Act compliance mandates:Algorithmic transparency requirements are accelerating replacement of black-box scoring engines with auditable decision trees in European deployments.
- Healthcare revenue cycle automation:US hospital systems facing CMS price transparency rules are automating patient financial communications to reduce bad debt exposure.
- First-party data infrastructure:Cookie deprecation is collapsing third-party audience targeting, driving investment in owned identity resolution and consent-layer orchestration.
Market Restraints
- Cloud egress cost volatility:Multi-tenant data platform fees from hyperscalers are consuming 15-22% of annual software budgets for mid-market automation buyers.
- API rate limiting:Social platform algorithm changes are throttling outbound message volumes, degrading campaign performance predictability.
- GDPR fine exposure:Cross-border data transfer uncertainty under Schrems II is extending legal review timelines for European implementations.
Strategic Opportunities
- India's Digital Personal Data Protection Act:Localization requirements are creating first-mover advantage for vendors establishing Mumbai and Hyderabad processing nodes.
- Generative content convergence:Large language model integration with dynamic template engines is collapsing creative production timelines from days to minutes.
- Embedded finance orchestration:Buy-now-pay-later and insurance attachment workflows are opening automation contracts within retail and automotive verticals.
Industry Challenges
- MLOps talent scarcity:Behavioral scoring model deployment and drift monitoring require specialized engineering profiles that command premium compensation in tight labor markets.
- Legacy CRM integration complexity:On-premise Siebel and SAP systems in financial services demand custom middleware development that extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marketing Automation Market |
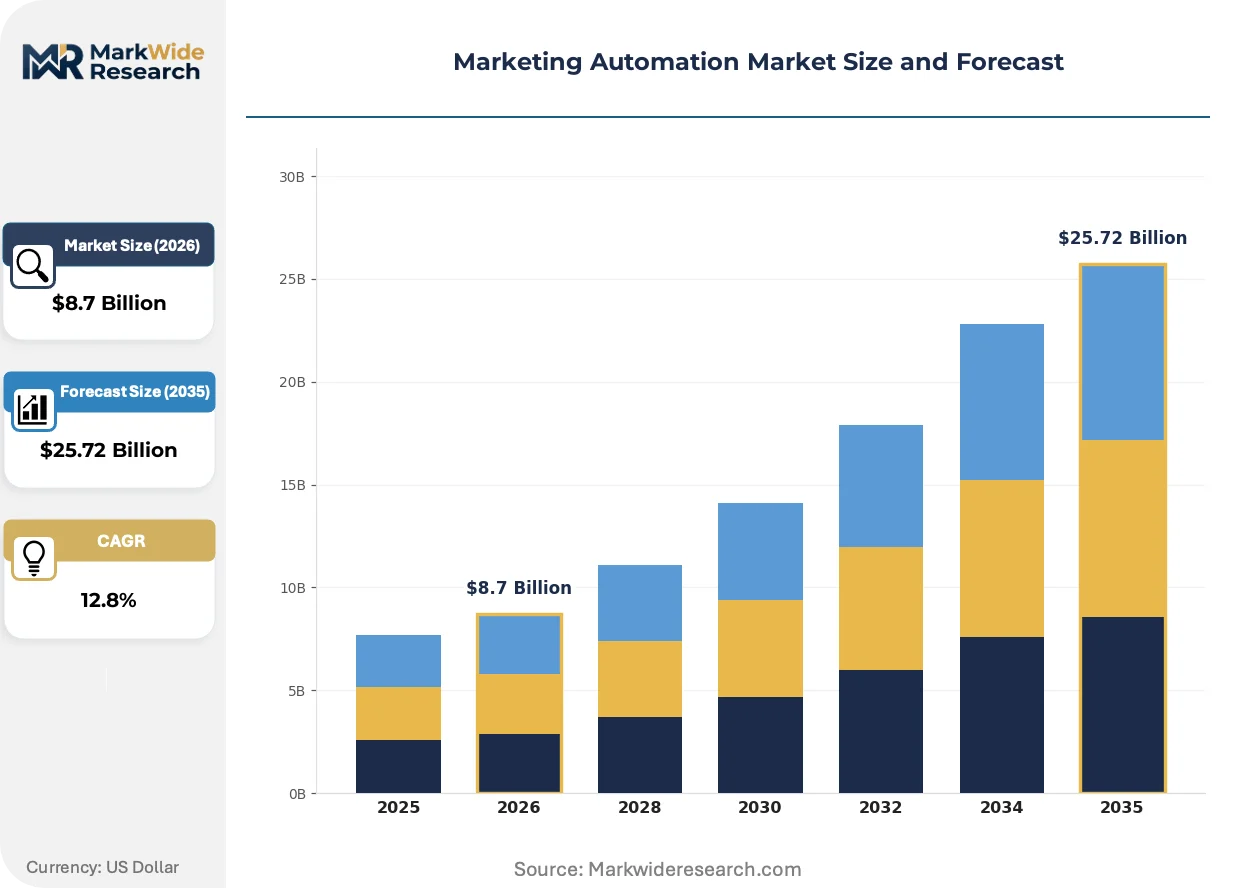
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $25.72 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Email Marketing, Social Media Automation, Lead Generation, Customer Relationship Management Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retail, E-commerce, Education, Healthcare Pricing Model: Subscription-Based, Pay-Per-Use, Freemium, Tiered Pricing |
| Companies Covered | HubSpot, Adobe, Oracle, Salesforce, Microsoft, ActiveCampaign, Klaviyo, SAP, Act-On Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marketing Automation Market Strategic Shifts & Innovations
Workflow orchestration is fragmenting into composable microservices, enabling buyers to assemble best-of-breed capabilities rather than accepting monolithic suite limitations.
Composable CDP architecture is collapsing the traditional boundary between data infrastructure and activation layers. Mid-market retailers in the United States are adopting headless customer data platforms that expose real-time segments directly to email and SMS execution engines. This modular approach is compressing total cost of ownership by eliminating redundant data storage and synchronization overhead.
GDPR Article 22 enforcement is reshaping automated decision-making disclosures across European deployments. Marketing automation vendors must now surface logic trees and provide human override mechanisms for credit and pricing algorithms. Healthcare and financial services segments are responding by embedding consent audit trails directly into campaign metadata rather than treating compliance as a post-hoc reporting layer.
Revenue operations teams are consolidating vendor relationships around platforms that unify sales engagement with marketing orchestration. Mid-market B2B technology buyers in North America are displacing point solutions for email, chat, and advertising in favor of integrated customer journey engines. This consolidation pattern is most visible among software companies with 200-2,000 employees where CMO-CRO alignment pressures favor single-vendor contracts.
Marketing Automation Market Segmentation
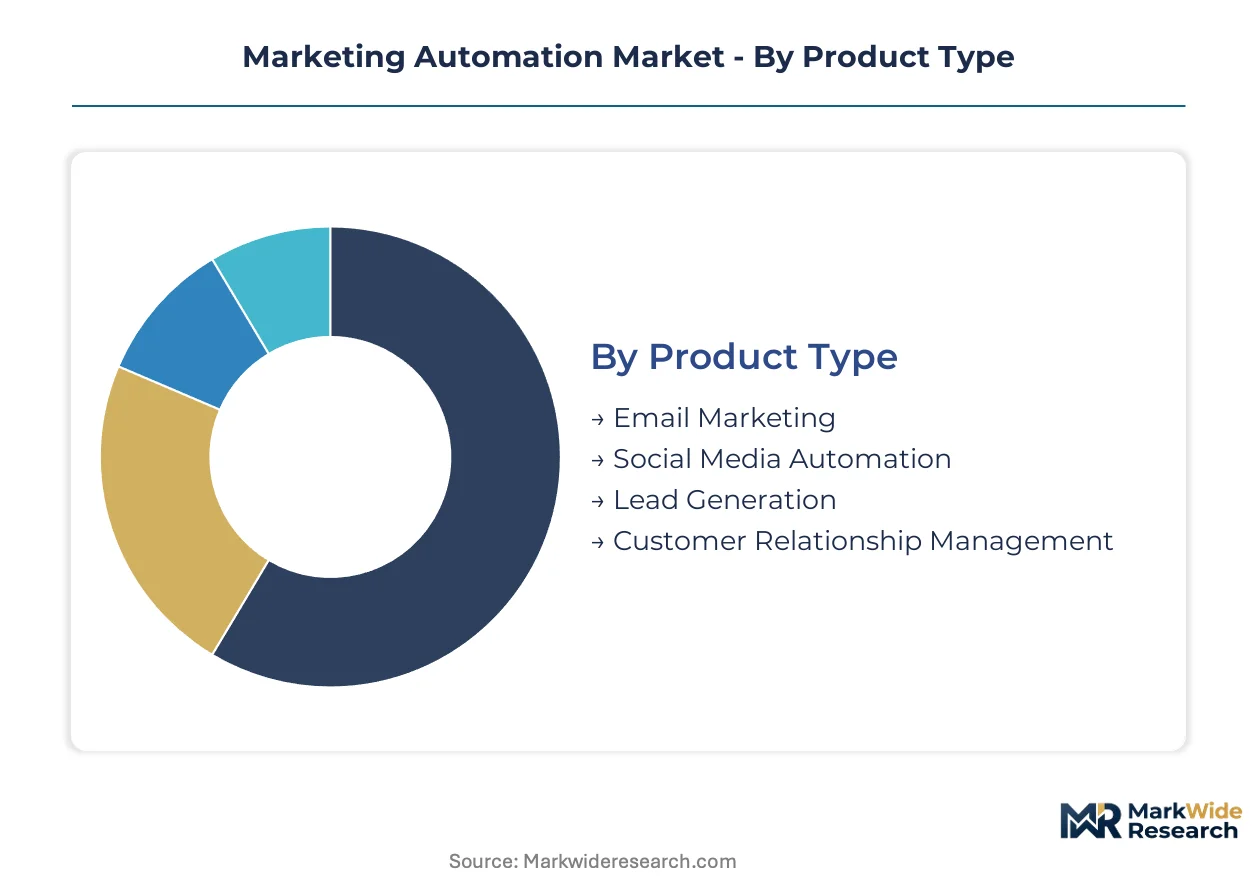
Marketing automation buyers select platforms based on workflow complexity, data residency requirements, and revenue team structure. Segment boundaries are blurring as vendors bundle email, social, and CRM capabilities into unified suites. Procurement teams evaluate total cost of ownership across deployment models and pricing structures rather than feature checklists alone.
Product Type:
Email marketing platforms turn over slowest due to entrenched integrations, while social media automation refreshes fastest as algorithm changes force quarterly vendor reassessments.
- Email Marketing:Rule-based sequencing engines process behavioral triggers through SMTP infrastructure and deliverability optimization layers. US mid-market retailers and healthcare systems anchor replacement demand as legacy ESP contracts expire and consent management requirements tighten. Email marketing anchors the volume base while social media automation gains share at the steepest rate.
- Social Media Automation:Multi-channel publishing tools connect to Meta, TikTok, and LinkedIn APIs for scheduled content deployment and engagement analytics. Short-form video expansion among North American DTC brands drives fastest refresh cycles as platform algorithm shifts degrade campaign predictability.
- Lead Generation:Landing page builders and form capture systems feed scoring algorithms that qualify prospects for sales handoff.
- Customer Relationship Management:Workflow automation modules embedded within contact databases synchronize marketing and sales activity streams.
Email marketing commands the largest installed base while social media automation climbs the fastest as video channel tooling matures.
Deployment:
Cost tier stratification separates hyperscaler-native SaaS from compliance-heavy hybrid configurations that carry 40-60% infrastructure premiums.
- Cloud-Based:Multi-tenant architectures on AWS, Azure, or Google Cloud eliminate capital expenditure and accelerate implementation timelines. North American mid-market retailers dominate new cloud deployments as cookie deprecation forces rapid first-party data infrastructure builds.
- Hybrid:Split architectures keep sensitive data on-premises while pushing execution workloads to cloud edge nodes. US healthcare systems facing HIPAA constraints and EU providers under GDPR Article 22 drive hybrid adoption where patient data residency conflicts with SaaS convenience.
- On-Premises:Self-hosted installations in private data centers persist where regulatory frameworks prohibit third-party data processing.
- SaaS:Vendor-managed software delivery abstracts infrastructure management through browser-based interfaces and API connectivity.
Cloud-based deployment captures the majority of new implementations while hybrid configurations expand most quickly among regulated verticals.
End User:
Application intensity varies sharply: retail and e-commerce run highest message volumes per seat, while healthcare and education prioritize consent audit density over throughput.
- Retail:Seasonal campaign surges and loyalty program orchestration demand high-throughput segmentation engines. United States mid-market retailers are displacing legacy email systems with integrated customer journey platforms that unify online and store-level purchase data.
- Healthcare:Patient financial communications and appointment scheduling workflows require HIPAA-compliant infrastructure with immutable audit trails. US hospital systems facing CMS price transparency rules automate revenue cycle communications to reduce bad debt exposure and improve collection rates.
- E-commerce:Cart abandonment sequences and personalized product recommendations drive conversion optimization through behavioral trigger networks.
- Education:Student recruitment and alumni engagement programs utilize enrollment funnel automation with FERPA-compliant data handling.
Retail generates the highest message volumes while healthcare posts the steepest expansion trajectory as revenue cycle automation mandates tighten.
Pricing Model:
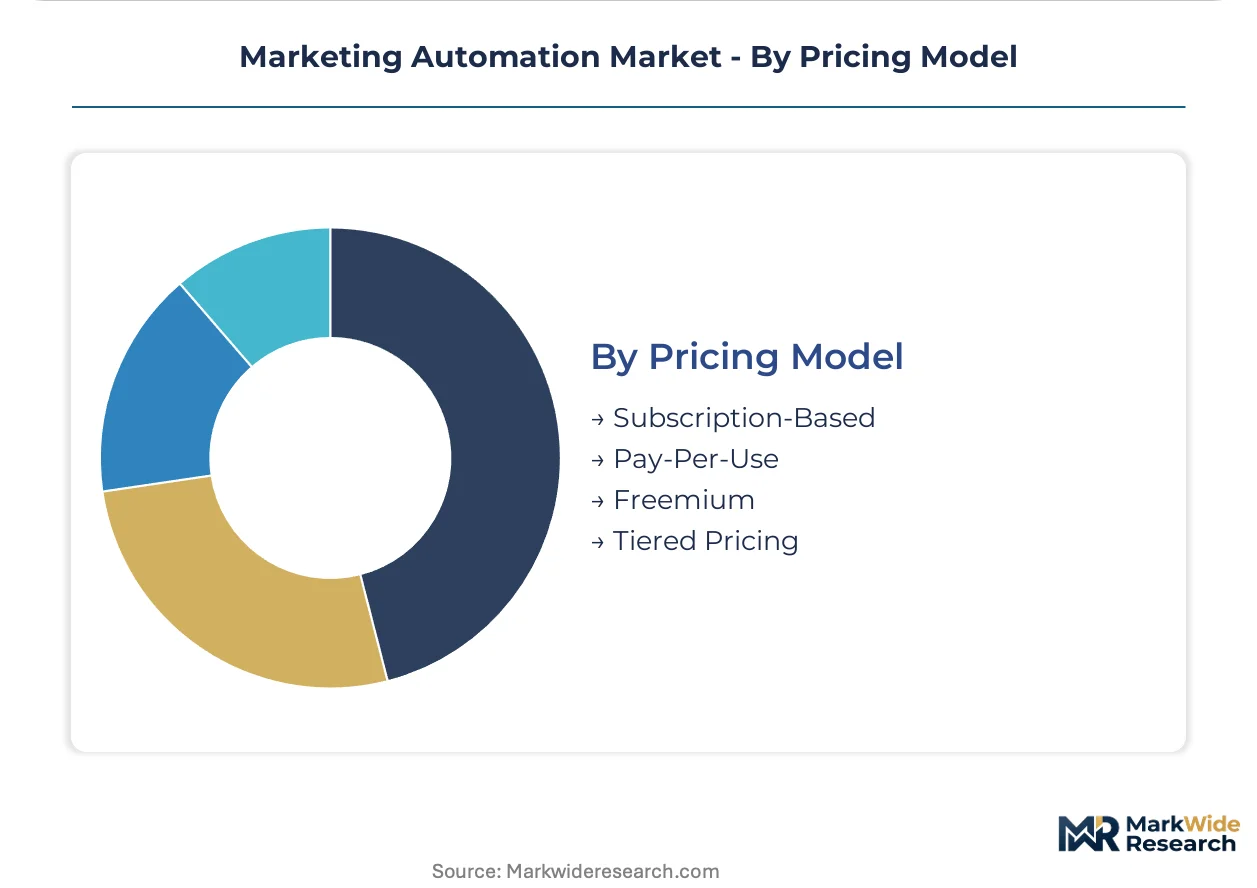
Customer type segmentation separates enterprise procurement teams seeking consumption predictability from growth-stage companies prioritizing cash flow flexibility.
- Subscription-Based:Fixed monthly or annual fees provide cost certainty for finance teams budgeting marketing technology spend. Enterprise B2B SaaS buyers compressing vendor evaluation cycles favor subscription models that eliminate usage forecasting complexity.
- Freemium:Zero-cost entry tiers with feature-gated upgrade paths lower customer acquisition costs for small and mid-sized businesses. HubSpot's conversion mechanics demonstrate how freemium structures capture early-stage companies before competitive displacement.
- Pay-Per-Use:Consumption-based billing aligns costs with actual message volumes or contact database growth.
- Tiered Pricing:Feature bundles segmented by user count, contact volume, or advanced capability access.
Subscription-based contracts anchor vendor revenue stability while freemium models expand most quickly among sub-200-employee companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where mid-market retailers absorb 40% infrastructure premiums, while EU compliance costs compress vendor margins across German and French deployments by comparable magnitudes.
United States
Mid-market retailers and healthcare systems drive replacement demand as legacy email systems expire and CMS price transparency rules mandate automated patient financial communications. FTC Section 5 enforcement scrutinizes deceptive automated messaging practices, forcing disclosure standardization. The Boston-Seattle corridor anchors SaaS vendor density where revenue operations teams consolidate around unified customer journey engines.
Germany
Industrial B2B manufacturers automate lead scoring and account-based marketing workflows to compress eighteen-month sales cycles. GDPR Article 22 and the EU AI Act mandate algorithmic transparency disclosures and human override mechanisms for pricing algorithms. The Rhine-Ruhr and Munich clusters host hybrid deployment specialists serving automotive and machinery verticals with on-premise data residency configurations.
United Kingdom
Financial services and professional services firms prioritize consent audit density over message throughput as FCA conduct rules tighten. The UK GDPR retention post-Brexit maintains Schrems II cross-border transfer constraints, extending legal review timelines for cloud implementations. London's fintech corridor drives embedded finance orchestration demand, linking marketing automation to buy-now-pay-later workflow triggers.
India
Education and retail clients compel multinational vendors to localize data processing infrastructure under the Digital Personal Data Protection Act. Mumbai and Hyderabad processing nodes create first-mover positioning for vendors establishing compliant delivery infrastructure. The Bangalore-Delhi corridor concentrates domestic SaaS adoption where sub-200-employee companies convert through freemium mechanics.
Japan
Enterprise manufacturers deploy behavioral scoring for distributor and dealer network orchestration across fragmented retail channels. METI guidelines on AI utilization encourage transparent decision-tree architectures over black-box models. The Tokyo-Osaka axis anchors marketing automation integration with existing SAP and Oracle ERP installations prevalent in keiretsu supply chains.
Marketing Automation Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in email deliverability, social API management, and identity resolution microservices. The vendor landscape stratifies into three tiers: hyperscaler-backed suites with CRM-native architecture, mid-market challengers leveraging subscription financing flexibility, and point-solution specialists in consent management or generative content. Consolidation pressure intensifies as enterprise procurement teams compress evaluation cycles from eighteen months to under six, favoring immediate workflow integration demonstrations over transformation roadmaps. Competitive moves center on M&A for CDP capabilities and strategic partnerships with hyperscalers to manage egress cost exposure.
Within the platform-integrator tier, Salesforce and Adobe exemplify divergent ecosystem strategies. Salesforce anchors its position through CRM-native workflow automation embedded within existing customer data infrastructure. Adobe leverages creative cloud cross-sell momentum to drive marketing automation suite adoption among brand-focused buyers. HubSpot occupies a distinct position in the freemium-conversion archetype, lowering customer acquisition costs for small and mid-sized businesses through tiered feature gating.
| Leading Market Players |
|---|
| HubSpot |
| Adobe |
| Oracle |
| Salesforce |
| Microsoft |
| ActiveCampaign |
| Klaviyo |
| SAP |
| Act-On Software |
| Others |
Cost & Logistics Intelligence
The Singapore-Frankfurt data corridor anchors cloud infrastructure cost dynamics for marketing automation vendors, concentrating supply-side leverage among hyperscalers while forcing downstream price differentiation between compliance-heavy European deployments and volume-driven North American implementations.
Pricing Analysis
The customization-premium spread separates standard SaaS-tiered subscriptions from configured-to-order hybrid deployments carrying 40-60% infrastructure premiums. Pricing stratifies across premium, standard, and economy tiers based on consent audit density and API throughput volumes. Cost compression in mid-market cloud tiers is intensifying because hyperscaler egress fees consume 15-22% of annual software budgets. Enterprise B2B SaaS buyers show lowest price sensitivity due to compressed evaluation cycles, while sub-200-employee companies convert through freemium mechanics with highest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for hardware-dependent edge nodes supporting hybrid deployments. Infrastructure provision concentrates in the United States, Ireland, and Singapore where hyperscaler regions anchor multi-tenant architectures. Raw material dependencies span silicon wafers for server components, rare earth elements for storage systems, and copper for data center interconnects. Distribution runs through direct vendor sales teams for enterprise contracts and self-service portals for mid-market conversions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marketing automation sits in early-cycle expansion as first-party data infrastructure replacement accelerates across cookie-deprived retail and healthcare verticals.
For Market Incumbents: Harden algorithmic transparency architectures against EU AI Act enforcement actions displacing black-box scoring engines. Embed consent audit trails directly into campaign metadata rather than treating GDPR compliance as post-hoc reporting. Acquire CDP capabilities to defend against point-solution consolidation pressure from revenue operations teams. For New Entrants and Emerging Players: Build out Mumbai and Hyderabad processing nodes to capture first-mover positioning under India's Digital Personal Data Protection Act localization mandates. Target education and retail segments in the Bangalore-Delhi corridor where freemium conversion mechanics show highest penetration. Lead with generative content convergence to collapse creative production timelines against incumbent workflow limitations. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy CRM integrators burdened by on-premise Siebel and SAP middleware complexity in financial services. Long-term viability hinges on MLOps talent acquisition and behavioral scoring model deployment capabilities. Watch for FTC Section 5 enforcement intensity as signal for disclosure standardization investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CDP Capability Acquisition | Unifies data infrastructure with activation layers for mid-market retailers replacing legacy ESP systems. |
| Generative Content Integration | Collapses creative production timelines through large language model deployment in dynamic template engines. |
| Hybrid Deployment Expansion | Captures HIPAA-constrained healthcare systems and GDPR Article 22-regulated European providers. |
| Localization Node Establishment | Creates compliant delivery infrastructure for India's Digital Personal Data Protection Act enforcement. |
| Revenue Operations Consolidation | Aligns CMO-CRO pressures toward single-vendor contracts in 200-2,000 employee B2B technology buyers. |
Research Approach
The analysis maps email marketing platforms, social media automation tools, lead generation systems, and CRM-embedded workflows, each validated through revenue operations leaders, CMOs at mid-market B2B SaaS companies, healthcare IT procurement officers, and retail digital transformation directors. Primary interview findings triangulate against SEC filings from publicly traded vendors, hyperscaler capex disclosures, CMS price transparency rule documentation, and EU AI Act regulatory texts. Bottom-up contact database scaling models reconcile with top-down enterprise software spending forecasts.
Assumptions held fixed include current GDPR Article 22 enforcement patterns, cookie deprecation timelines, and hyperscaler pricing structures; variables tested include EU AI Act implementation intensity and India localization requirement phasing. Segmentation dimensions span deployment model, organization size, vertical application, and regional regulatory cluster. CAGRs derive from installed base replacement velocity and net new adoption curves across first-party data infrastructure builds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by generative AI-native entrants or hyperscaler direct-to-customer expansions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Smart Card Reader Market
Digital Solutions
Harbor Management Software Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Smart Signage Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Digital Twin Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
North America Smart Card Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Global Digital Art Software Market