
 North America Lip Care Products Market | 2026-2036
North America Lip Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lip Care Products Market Intelligence
Pharmacy and specialty retail shelf space is rewriting how lip care brands build consumer loyalty in North America. Burt's Bees Products Company leverages its natural ingredient heritage to dominate the mass premium tier. eos Products differentiates through distinctive packaging and direct-to-consumer engagement. Chapstick sustains broad drugstore distribution that anchors its everyday accessibility across the United States and Canada.
Lip care products encompass topical formulations—typically comprising waxes, oils, emollients, and active agents such as petrolatum, shea butter, or chemical sunscreen filters—manufactured through melt-and-pour or hot-fill processes to deliver hydration, protection, and aesthetic enhancement. Balms and treatments occupy the largest volume share due to year-round functional demand, while natural and organic ingredient types command the fastest expansion as clean-label preferences intensify. Glosses retain strong seasonal elasticity tied to fashion cycles, and medicinal segments face tighter FDA scrutiny that elevates compliance costs.
FDA sunscreen monograph enforcement and EPA chemical review protocols shape permissible active ingredients and labeling requirements across the United States. Health Canada and PMRA standards govern north-of-border product registration and SPF claim substantiation. Stakeholders must monitor pending regulatory determinations on mineral versus chemical UV filters to align R&D pipelines with compliance trajectories.
Market Dynamics
FDA sunscreen monograph uncertainty is compressing formulation timelines and forcing brands to pre-position mineral SPF alternatives ahead of final rule determinations. This regulatory overhang is accelerating R&D expenditure and reshaping supplier relationships across the United States and Canada.
Growth Catalysts
- Clean-label ingredient mandates:California's Proposition 65 enforcement and Health Canada's hotlist updates are pulling brands toward botanical waxes and natural emollients. Reformulation pipelines now prioritize shea butter and plant-derived alternatives to petrolatum.
- SPF integration into daily lip routines:Dermatologist recommendations and consumer skin-cancer awareness are embedding UV protection into standard lip care purchase criteria. Tinted SPF formats capture incremental shelf space in pharmacy and specialty retail.
- Direct-to-consumer channel expansion:Subscription models and TikTok-native brand building are lowering customer acquisition costs for indie entrants. Toronto's indie brand ecosystem and Los Angeles influencer marketing clusters concentrate this momentum.
Market Restraints
- Beeswax supply volatility:Colony collapse disorder and climate stress on North American apiaries are tightening natural wax availability. Price premiums for certified organic beeswax constrain margin structures for heritage natural-positioned brands.
- FDA active ingredient bottleneck:Pending determinations on zinc oxide and titanium dioxide nano-particle safety are freezing new SPF lip product launches. Brands face inventory risk on chemical filter formulations that may lose GRASE status.
- Private-label substitution pressure:Mass retailers are expanding store-brand lip care assortments with near-identical ingredient decks. Price compression at the drugstore tier erodes branded volume in everyday functional segments.
Strategic Opportunities
- Men's grooming segment underpenetration:Male consumers in the United States and Canada exhibit low current lip care attachment rates. Unscented, matte-finish formats with performance positioning represent white space against feminized incumbent assortments.
- Blue light and pollution defense claims:Antioxidant-infused lip treatments targeting urban environmental stressors are gaining traction in Toronto and New York metropolitan markets. This functional extension commands premium pricing with limited formulation cost increment.
- Refillable and zero-waste packaging:California's extended producer responsibility legislation and Canadian single-use plastic restrictions are creating regulatory tailwinds for solid lip balm formats and aluminum case systems.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in natural emulsion stability and mineral SPF dispersion is concentrated among a small cohort of contract manufacturers. Brands face extended development timelines and higher NPD costs.
- Cross-border labeling complexity:Divergent FDA and Health Canada SPF claim substantiation requirements force dual packaging SKUs or lowest-common-denominator claims. This friction elevates supply chain overhead for unified North America portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lip Care Products Market |
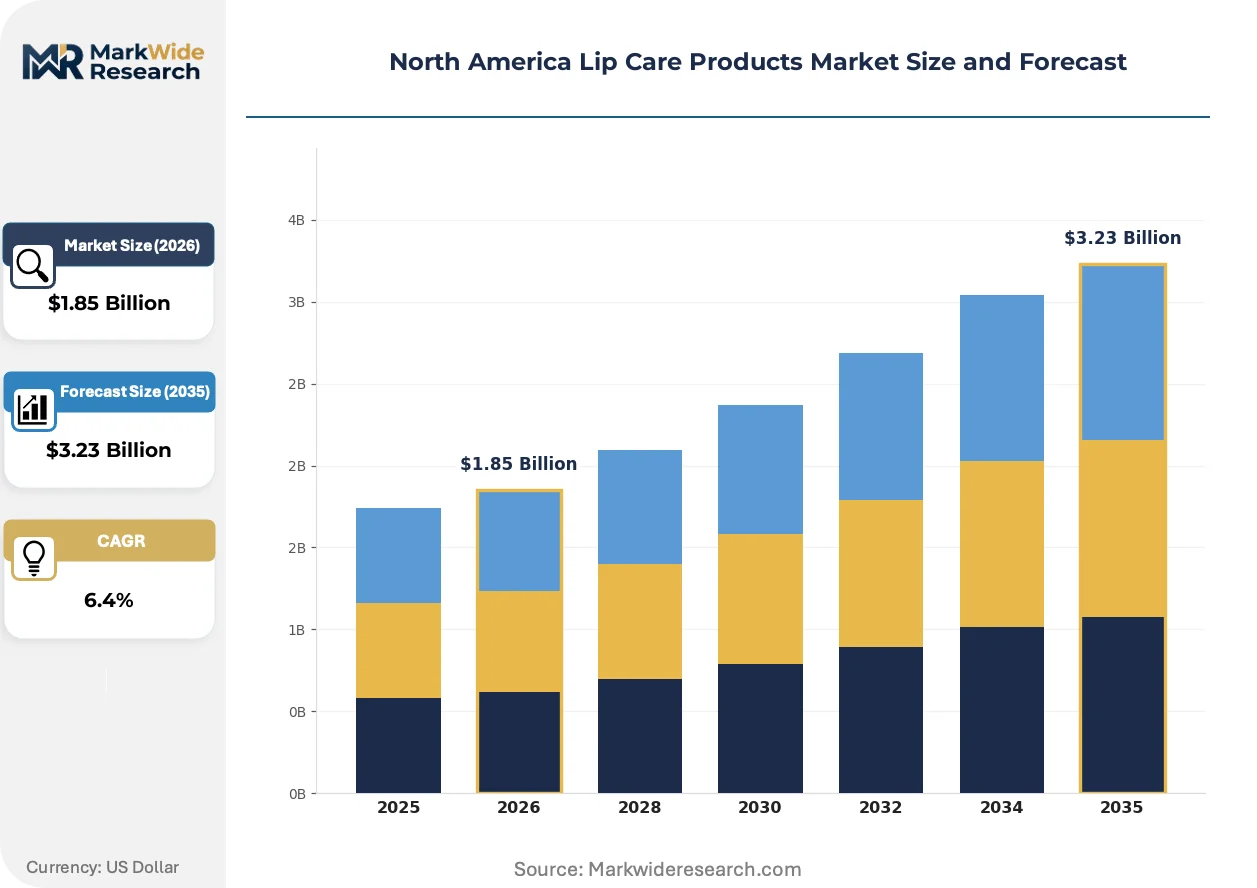
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balms, Glosses, Treatments, Scrubs Ingredient Type: Natural, Organic, Synthetic, Medicinal Customer Type: Women, Men, Children, Professionals Distribution Channel: Online, Retail, Pharmacies, Salons |
| Companies Covered | Blistex Inc, L'Oréal, Chapstick, Unilever, Revlon, Burt’s Bees Products Company, eos Products, Beiersdorf, Carmex, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lip Care Products Market Strategic Shifts & Innovations
Biotechnology-derived ingredients and packaging material science are converging to redefine product performance credentials and environmental positioning. These shifts are compressing traditional competitive advantages rooted in heritage formulations.
Biotech-engineered squalane and fermented oils are rendering obsolete conventional plant-derived emollients dependent on agricultural yield volatility. Indie brands in California's clean beauty corridor are adopting these inputs fastest, securing supply contracts with precision fermentation suppliers. The technology is compressing cost structures for premium natural-positioned products while eliminating batch-to-batch inconsistency.
FDA's pending sunscreen monograph update is forcing pre-emptive mineral filter migration across SPF-infused lip portfolios. Brands are accelerating zinc oxide dispersion R&D to maintain aesthetic acceptability against chemical filter benchmarks. This regulatory pressure most affects mass-market SPF lip balms, where reformulation costs strain price-competitive positioning.
Young adult buyers are unbundling lip care from seasonal purchase patterns, treating hydration and protection as year-round skincare essentials. Pharmacy and specialty retail are capturing this behavioral shift through expanded everyday shelf placement, displacing seasonal promotional dependence. This pattern concentrates in United States coastal metropolitan markets and Toronto's urban core.
North America Lip Care Products Market Segmentation
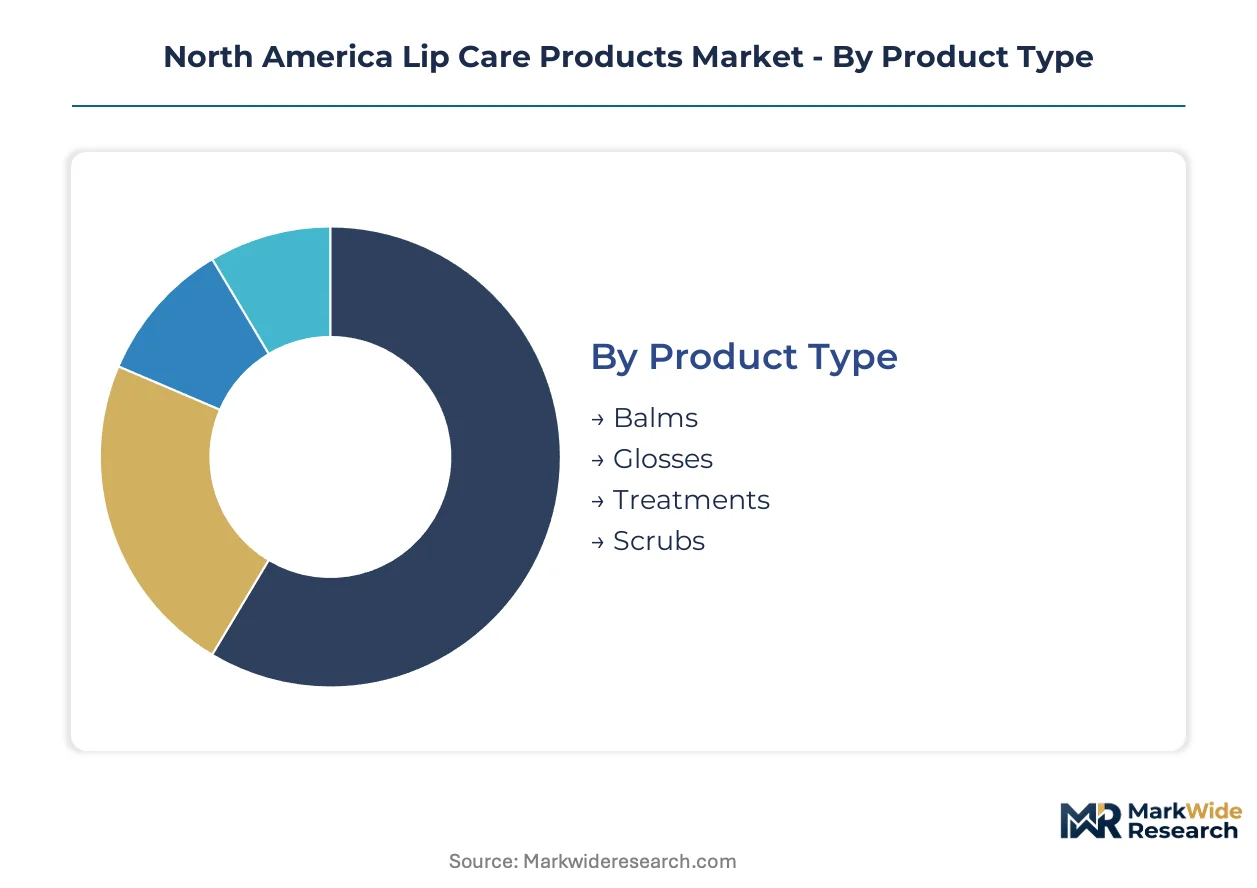
Lip care product segmentation in North America reflects divergent consumer priorities across functional utility, ingredient transparency, and purchase occasion. Category boundaries are blurring as SPF integration and clean-label positioning reshape traditional format definitions.
Product Type:
Mature formats dominate unit volumes while emerging hybrids capture premium pricing and shelf space expansion.
- Balms:Wax-based formulations incorporating petrolatum, shea butter, or plant-derived emollients deliver baseline hydration and protection. Year-round functional demand in United States pharmacy and mass retail channels sustains volume leadership despite margin compression from private-label alternatives.
- Treatments:Concentrated active formulations target specific conditions including severe dryness, sun damage, and anti-aging. Dermatologist recommendations and clinical positioning command premium pricing in California's clean beauty corridor and Toronto specialty retail.
- Glosses:Aesthetic-focused formulations with variable pigment density and shine levels retain strong seasonal elasticity tied to fashion cycles.
- Scrubs:Exfoliating formats with sugar, salt, or biodegradable bead bases occupy niche positioning within premium indie brand assortments.
Balms retain volume leadership; treatments hold the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates heritage synthetic formulations from rapidly scaling natural and certified organic alternatives.
- Natural:Botanical waxes, plant oils, and mineral-derived actives satisfy California Proposition 65 compliance and Health Canada hotlist requirements. Brands accelerate reformulation pipelines to secure clean-label positioning ahead of regulatory tightening.
- Organic:Certified inputs meeting USDA or Canada Organic Regime standards command price premiums of 40-60% above conventional natural alternatives. Supply constraints on certified organic beeswax and shea butter concentrate sourcing risk among limited supplier bases.
- Synthetic:Petrolatum-based and chemically synthesized formulations maintain cost competitiveness in mass drugstore tiers despite clean-label headwinds.
- Medicinal:Active pharmaceutical ingredients including menthol, camphor, and medicated SPF filters face elevated FDA scrutiny and GRASE status uncertainty.
Natural ingredients are climbing the fastest; synthetic maintains share in price-sensitive channels.
Customer Type:
Application context and purchase motivation vary sharply across demographic segments with divergent loyalty patterns.
- Women:Core purchasers across all format and price tiers, driving 70%+ of category volume through habitual daily use and seasonal replenishment cycles.
- Men:Underpenetrated segment with low current attachment rates; unscented matte formats and performance positioning represent expansion white space in United States and Canadian urban markets.
- Children:Safety-critical segment demanding hypoallergenic, flavor-free, and mineral-SPF-only formulations with stringent labeling requirements.
- Professionals:Workplace-appropriate tinted SPF and long-wear formats concentrate demand in metropolitan professional corridors including New York, Chicago, and Vancouver.
Women anchor absolute volume; men represent the most underdeveloped expansion opportunity.
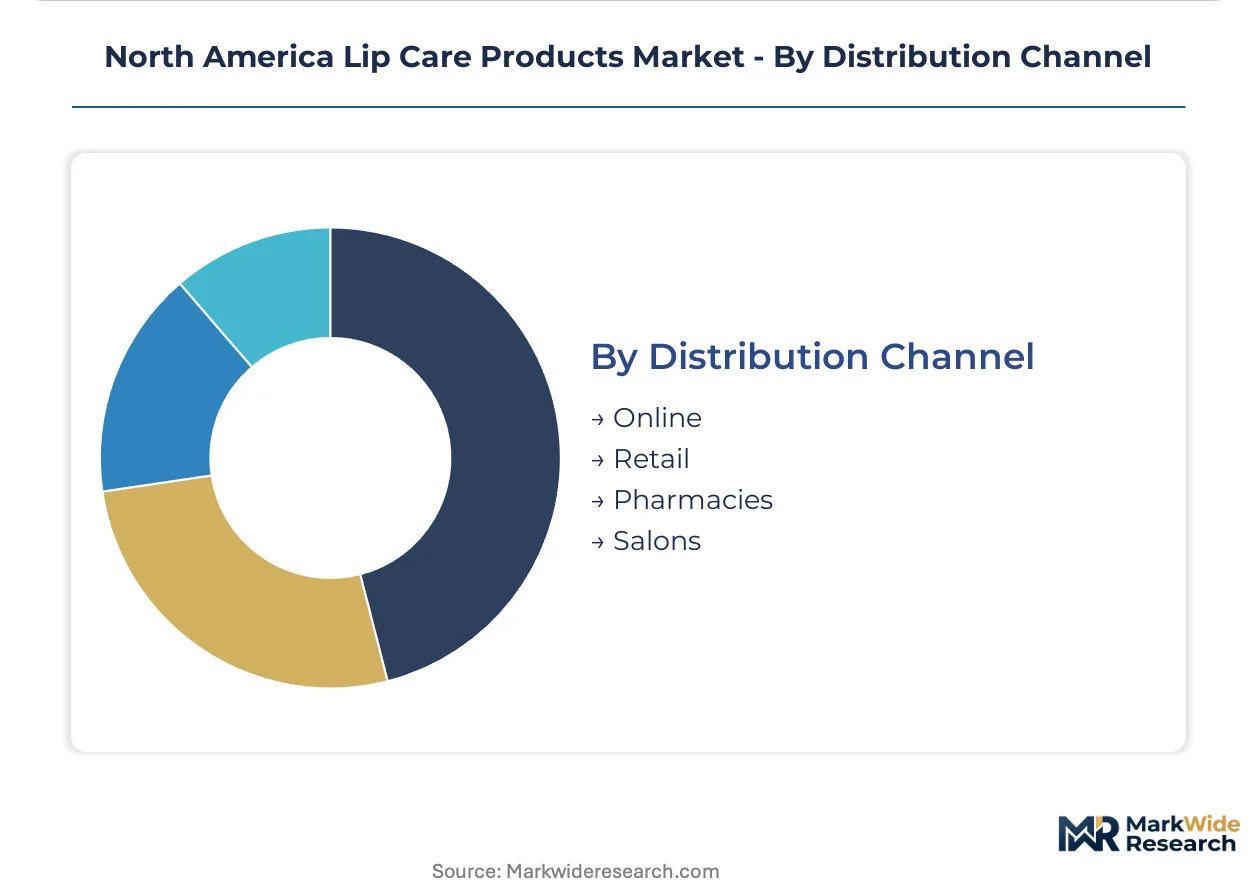
Distribution Channel:
Channel strategy determines margin structure and consumer relationship depth across impulse, planned, and subscription purchase occasions.
- Retail:Mass merchants and specialty beauty stores capture planned purchase missions with broad SKU visibility and promotional dependency.
- Online:Direct-to-consumer and marketplace platforms enable subscription models and TikTok-native brand building with superior customer acquisition economics for indie entrants.
- Pharmacies:Professional recommendation channel concentrating SPF-infused and medicated formats; CVS, Walgreens, and Shoppers Drug Mart anchor United States and Canadian distribution.
- Salons:Service-integrated retail capturing premium treatment and professional-grade format trials with high conversion to replenishment.
Pharmacies sustain the highest purchase frequency; online channels are gaining share fastest among young adult cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in California's clean beauty corridor while mass-market volume anchors in Midwest pharmacy chains. This asymmetry shapes divergent go-to-market strategies across the continent. Regulatory fragmentation between FDA and Health Canada standards compounds operational complexity for unified North American portfolios.
United States
California's Proposition 65 enforcement and dermatologist-driven SPF adoption pull formulation standards upward. FDA sunscreen monograph uncertainty compresses launch timelines for chemical filter products. Los Angeles influencer marketing clusters and New York metropolitan professional corridors concentrate demand for tinted SPF and blue-light defense formats.
Canada
Health Canada's hotlist updates and PMRA chemical review protocols govern permissible active ingredients. Toronto's indie brand ecosystem anchors direct-to-consumer innovation with subscription model experimentation. Shoppers Drug Mart pharmacy distribution sustains highest purchase frequency for medicated and mineral-SPF segments.
Mexico
COFEPRIS regulatory alignment with FDA standards facilitates cross-border product registration for US manufacturers. Mexico City metro area concentrates premium import demand among young adult consumers. Northern border states channel maquiladora-adjacent manufacturing capacity for cost-competitive natural wax formulations.
North America Lip Care Products Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with formulation and packaging technology. The market structures around three tiers: mass-market heritage brands with pharmacy anchorage, premium natural-positioned specialists with clean-label credentials, and indie entrants with direct-to-consumer channel control. Strategic archetypes include vertically integrated botanical suppliers, contract manufacturing-dependent brand builders, and platform-owned portfolio players. Competitive moves concentrate on mineral SPF reformulation pipelines and refillable packaging system development ahead of regulatory deadlines.
Within the heritage natural-positioned tier, Burt's Bees Products Company and eos Products exemplify divergent differentiation strategies—one leveraging ingredient heritage, the other distinctive format innovation. Among mass-market drugstore anchors, Chapstick occupies foundational shelf space across CVS and Walgreens networks. L'Oréal represents platform-scale portfolio breadth with cross-category resource deployment capability.
| Leading Market Players |
|---|
| Blistex Inc |
| L'Oréal |
| Chapstick |
| Unilever |
| Revlon |
| Burt's Bees Products Company |
| eos Products |
| Beiersdorf |
| Carmex |
| Others |
Cost & Logistics Intelligence
Beeswax supply volatility from colony collapse disorder and climate stress on North American apiaries compresses margin structures for heritage natural-positioned brands while simultaneously widening spreads between certified organic and conventional natural tiers. This input bottleneck forces brands to either absorb cost premiums or reformulate toward plant-derived alternatives, reshaping supplier relationships across California's clean beauty corridor and Toronto's indie brand ecosystem.
Pricing Analysis
Configured-to-order pricing for custom SPF-infused and tinted formats commands substantial premiums over standard petrolatum-based balms. Three-tier pricing structure across premium, standard, and economy levels separates certified organic formulations with USDA or Canada Organic Regime credentials from conventional natural alternatives and synthetic mass-market offerings. Price differentiation hinges on certification grade and customization level, with dermatologist-recommended treatment formats least sensitive and private-label drugstore substitutes most vulnerable to cost compression. Pricing pressure stems from mass retailer store-brand expansion with near-identical ingredient decks.
Supply Chain Analysis
Extended payment terms from contract manufacturers to precision fermentation suppliers are becoming standard as biotech-engineered squalane and fermented oils displace agricultural-dependent inputs. Geographic supply concentration centers on the United States for botanical wax processing, Canada for mineral SPF formulation expertise, and Mexico for cost-competitive natural wax manufacturing near northern border maquiladora zones. Raw material dependencies include certified organic beeswax, shea butter from West African cooperatives, and zinc oxide for mineral SPF dispersion. Single-source vulnerability concentrates in specialized formulation chemist talent pools. Distribution runs through pharmacy chains including CVS, Walgreens, and Shoppers Drug Mart for highest-frequency replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mass retailers expanding private-label substitution and direct-to-consumer platforms capturing young adult cohorts, fragmenting traditional brand loyalty and compressing pricing power at the drugstore tier.
For Market Incumbents: Insulate market position by accelerating mineral SPF reformulation pipelines ahead of FDA sunscreen monograph final determinations and securing captive supply contracts with certified organic beeswax apiaries to defend margin structures against input volatility. Channel control through pharmacy shelf-space agreements remains essential as private-label pressure intensifies.
For New Entrants and Emerging Players: Pursue white-space expansion in unscented matte-finish formats targeting underpenetrated male consumers across United States and Canadian urban markets, and leverage subscription models with TikTok-native brand building to lower customer acquisition costs. Toronto's indie brand ecosystem offers the most penetrable geography for direct-to-consumer experimentation.
For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors precision-fermentation-enabled ingredient platforms and refillable packaging system developers over heritage petrolatum-dependent formulations. Long-term viability across the next decade hinges on clean-label credential defensibility and mineral SPF aesthetic performance. Acquisition targets with biotech squalane supply contracts and aluminum case manufacturing capabilities signal premium positioning durability. Watch FDA GRASE determinations on zinc oxide nano-particle safety as the critical inflection indicator for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Mineral SPF Reformulation Pipeline | FDA sunscreen monograph compliance secures shelf space ahead of chemical filter restrictions. |
| Precision Fermentation Supply Contract | Biotech-engineered squalane eliminates agricultural yield volatility for California clean beauty brands. |
| Refillable Aluminum Case System | California extended producer responsibility legislation creates regulatory tailwind for zero-waste formats. |
| Direct-to-Consumer Subscription Launch | TikTok-native brand building lowers acquisition costs among Toronto and Los Angeles young adult clusters. |
| Men's Grooming Format Extension | Unscented matte positioning captures white space against feminized incumbent pharmacy assortments. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with brand managers, category buyers at CVS and Walgreens, formulation chemists at contract manufacturers, and regulatory affairs specialists; and secondary validation through FDA sunscreen monograph filings, Health Canada PMRA registration databases, Nielsen retail audit data, and customs records tracking beeswax and shea butter import flows. Bottom-up triangulation against top-down market sizing anchored volume and value estimates.
Forecast inputs span product type segmentation across balms, treatments, glosses and scrubs; ingredient type tiers from synthetic through natural to certified organic; and distribution channel dynamics including pharmacy, retail, online and salon. CAGRs were derived from segment-level growth trajectory modeling incorporating SPF integration rates, clean-label preference shifts, and direct-to-consumer channel penetration curves. Regulatory timeline uncertainty around FDA active ingredient determinations and California Proposition 65 enforcement intensity shaped scenario-weighted projections across the analysis window.
Sensitivities concentrate around FDA GRASE status revisions for chemical UV filters, colony collapse disorder severity affecting North American apiary output, and mass retailer private-label expansion velocity. Forecasts reflect documented assumptions regarding regulatory implementation timelines and consumer clean-label adoption curves. Macroeconomic contraction, accelerated regulatory restriction, or breakthrough biotech emollient cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Bio-Based Cosmetics Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
Body Glitters Market
Beauty & Personal Care
Pore Strips Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
South Korea Beauty and Personal Care Products Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
Deodorant Products Market
Beauty & Personal Care
DIY Haircut Kits Market