
 Global Cosmetics Market | 2026-2036
Global Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetics Market Analysis
Capital-intensity divergence between biotech-capable formulators and legacy brand houses is redrawing competitive boundaries in cosmetics. L'Oréal S.A. leverages advanced skin biology research to anchor its premium dermatology portfolio. The Estée Lauder Companies Inc. sustains exclusivity through controlled distribution in travel retail and department store concessions. Shiseido Company Limited differentiates via Japanese fermentation biotechnology and regional R&D hubs.
Cosmetics comprise topical preparations formulated with emollients, active ingredients, preservatives, and delivery systems designed to cleanse, protect, or enhance human appearance, manufactured through processes ranging from cold blending to high-shear emulsification at controlled temperatures. Skincare commands the largest margin pool as consumers prioritize ingredient transparency and clinical efficacy claims. Haircare competes on salon-professional credibility and scalp-health positioning, while fragrance depends on concentration tiering and limited-edition releases to sustain pricing power. Online Retail is displacing traditional department store traffic, though Specialty Stores retain authority in color-matching and personalized consultation.
Regulators including the FDA, the EU's ECHA under REACH, and China's NMPA impose divergent safety thresholds on preservatives, colorants, and nanomaterials, forcing multinationals to maintain region-specific formulation portfolios. The EU's MDR and forthcoming microplastic restrictions will eliminate certain exfoliants and glitter applications, redirecting R&D budgets toward biodegradable alternatives. Stakeholders must monitor regulatory fragmentation between major markets while building flexible manufacturing networks capable of rapid formula adaptation.
Market Dynamics
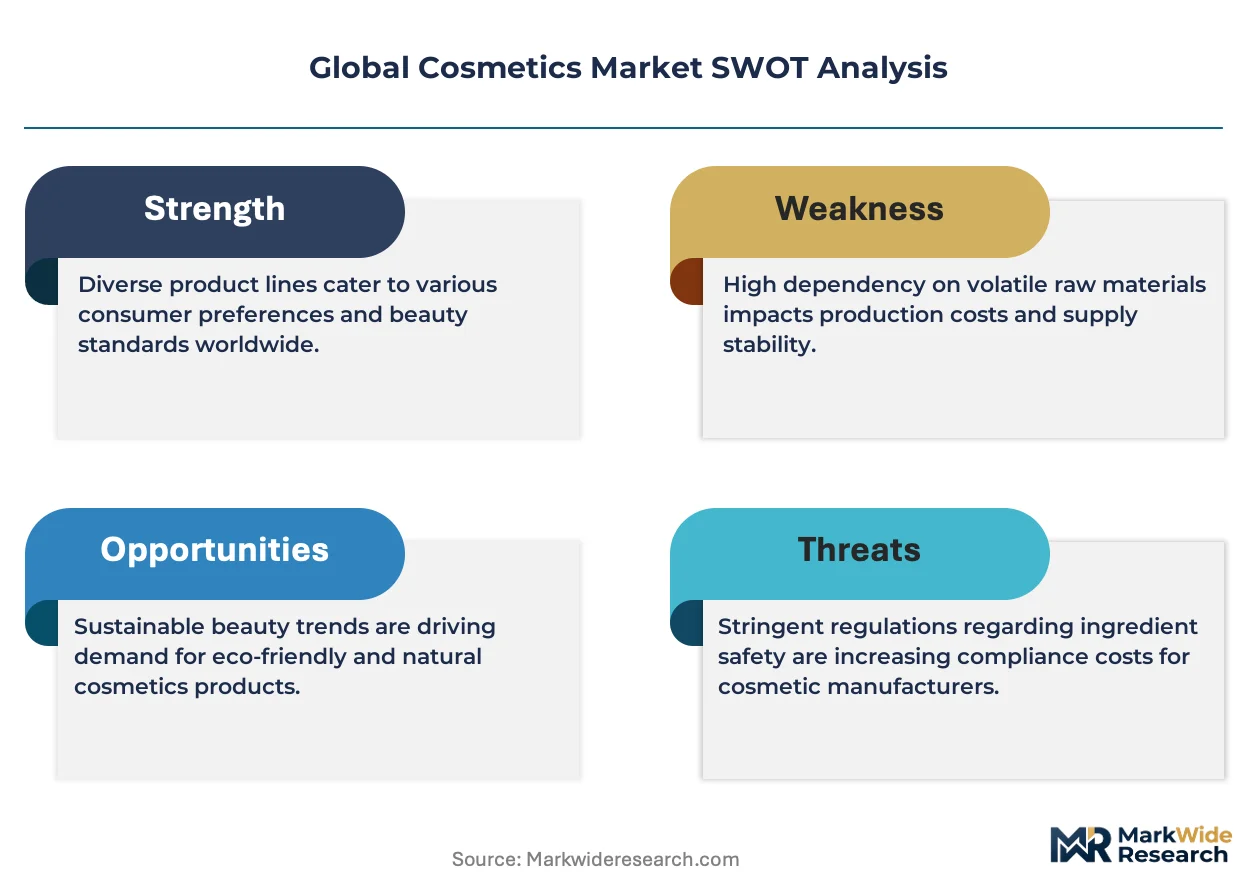
Biotechnology-enabled formulation capabilities are splitting the competitive landscape between capital-heavy precision labs and traditional brand houses dependent on marketing scale.
Growth Catalysts
- Live-commerce penetration:China's Douyin and Taobao Live platforms convert entertainment into immediate purchase intent, compressing the path from product discovery to checkout for younger demographics.
- REACH microplastic restrictions:The EU's tightening exfoliant and glitter bans redirect R&D investment toward biodegradable alternatives, opening first-mover advantages for compliant formulators.
- Scalp microbiome science:Advances in sequencing technology enable personalized haircare diagnostics, creating premium positioning opportunities in the professional salon channel.
Market Restraints
- Petrochemical derivative volatility:Surfactant and emollient feedstock costs fluctuate with crude oil and palm oil futures, squeezing margin predictability for mass-market producers.
- Chinese domestic brand consolidation:State-supported champions like Florasis and Perfect Diary capture shelf space and talent pools, raising customer acquisition costs for foreign entrants.
- Preservative safety thresholds:Divergent FDA, ECHA, and NMPA approval timelines force parallel formulation tracks, inflating SKU complexity and inventory carrying costs.
Strategic Opportunities
- India's tier-two urbanization:Rising disposable incomes in cities like Jaipur and Indore outpace organized retail coverage, creating whitespace for direct-to-community distribution models.
- Men's scalp health positioning:Underdeveloped professional haircare protocols for male pattern conditions offer margin expansion beyond commoditized shaving categories.
- SAMR clean beauty incentives:China's State Administration for Market Rewards prioritizes domestic green chemistry patents, channeling subsidies toward localized biotech R&D facilities.
Industry Challenges
- Fermentation scale-up expertise:Japanese and Korean biotech talent commands premium compensation, constraining rapid replication of Shiseido-style bio-ferment capabilities elsewhere.
- Legacy ERP integration:Real-time batch tracking for REACH compliance requires retrofitting decades-old manufacturing execution systems without disrupting continuous production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetics Market |
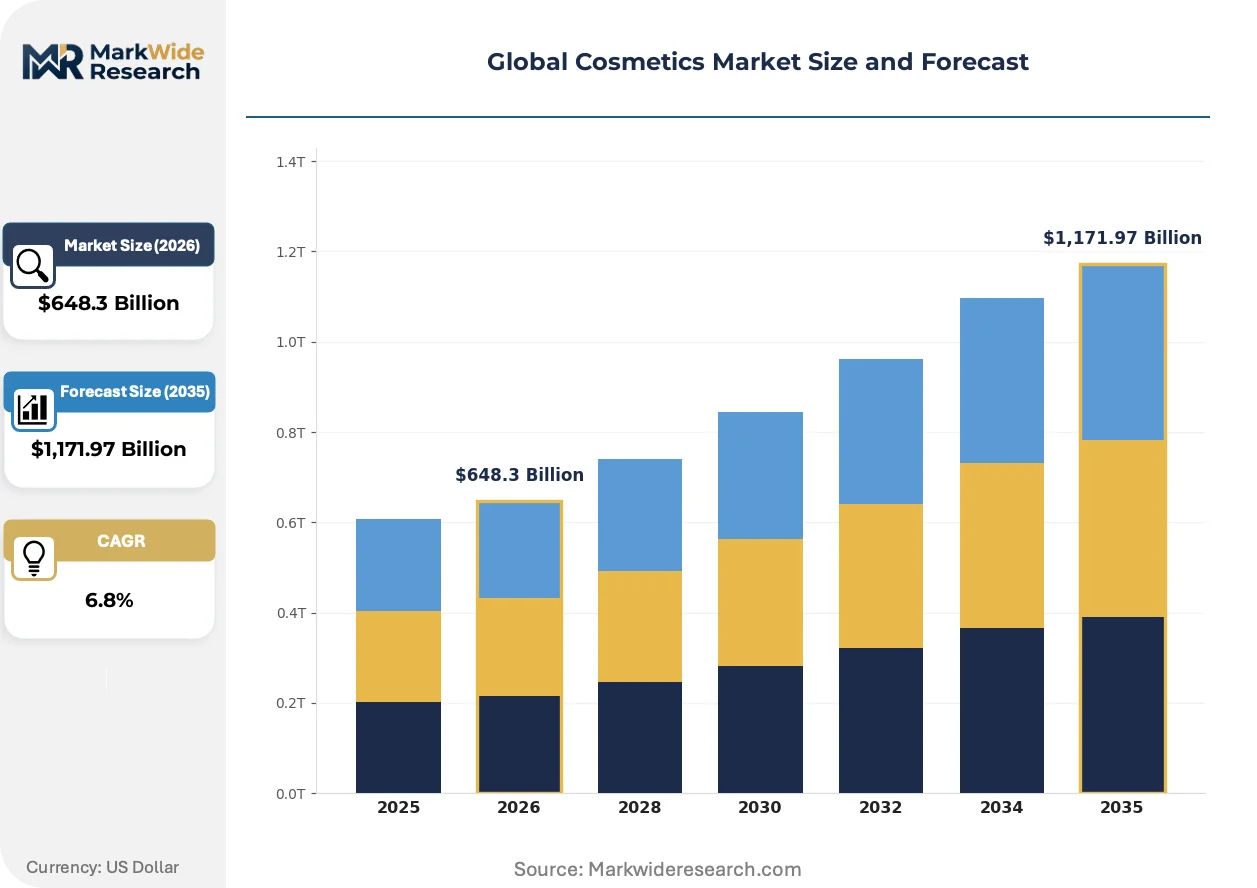
| Market Size in 2026 | $648.3 Billion |
| Market Size in 2035 | $1,171.97 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare Distribution Channel: Online Retail, Department Stores, Specialty Stores, Drugstores Customer Type: Women, Men, Unisex, Teenagers Packaging Type: Tubs, Bottles, Jars, Sachets |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Unilever PLC, The Procter & Gamble Company, Shiseido Company Limited, Beiersdorf AG, Coty Inc., Johnson & Johnson, Oriflame Cosmetics AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetics Market Emerging Trajectories
Formulation science, retail infrastructure, and consumer data systems are converging to collapse traditional boundaries between clinical dermatology and discretionary beauty.
Biomimetic peptide synthesis is fragmenting the anti-aging active ingredient supply chain. Korean contract manufacturers now produce custom signal peptides at kilogram scale, enabling mid-tier brands to compete with heritage houses on clinical claim credibility. The technology is fragmenting concentration of premium efficacy narratives across price tiers.
REACH Annex XVII expansions will prohibit additional microplastic categories from 2027. Formulators must eliminate certain film-forming agents and glitter substrates, redirecting investment toward cellulose-based alternatives and mineral replacements. Color cosmetics and rinse-off products face the steepest compliance curves.
Subscription-based personalization is displacing one-off retail transactions. Proprietary skin diagnostic hardware—deployed in Sephora Shanghai and Douglas Berlin—generates recurring revenue through algorithm-matched serum refills. This model concentrates lifetime value capture in China's first-tier cities and Germany's metropolitan corridors.
Global Cosmetics Market Segmentation
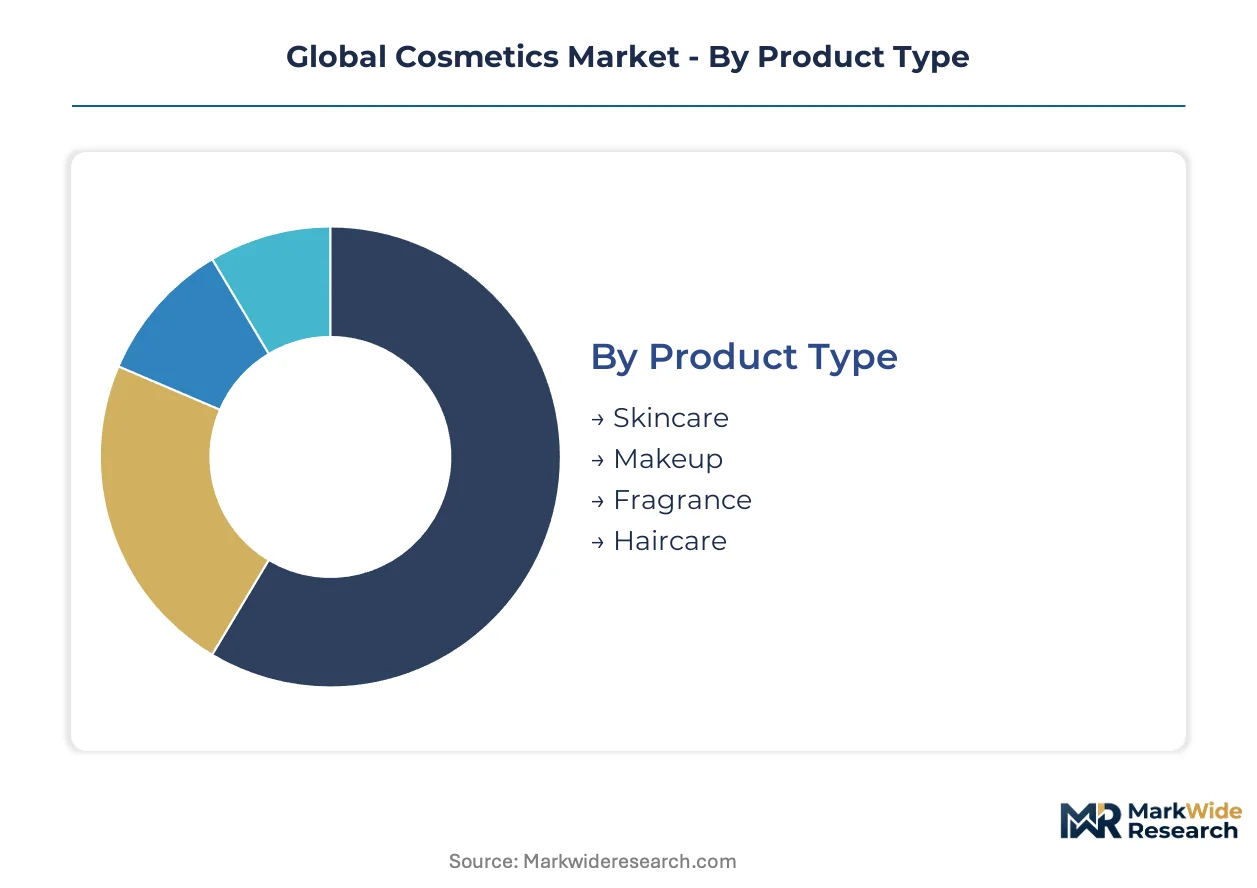
Segmentation in cosmetics determines where formulation R&D budgets flow and which distribution partnerships command premium terms. Margin capture diverges sharply between clinical-positioned skincare and volume-driven color cosmetics, while channel selection dictates inventory velocity and customer lifetime value profiles.
Product Type:
Skincare concentrates the industry's highest margin pools through ingredient transparency premiums and repeat purchase frequency.
- Skincare:Formulations incorporate emollients, humectants, and active peptides delivered via lipid nanoparticles or encapsulation systems. Demand clusters in China's first-tier cities where Douyin live-commerce converts ingredient education into immediate transactions, though EU REACH microplastic restrictions are forcing reformulation of rinse-off exfoliants.
- Makeup:Color cosmetics rely on pigment dispersion technology, film-forming polymers, and texture modifiers for wear longevity. Professional salon channels in Germany and France sustain premium pricing through color-matching consultation services, while mass-market compression in North America pushes private-label substitution.
- Fragrance:Concentration tiering from parfum to eau de toilette segments price accessibility, with limited-edition releases sustaining exclusivity.
- Haircare:Scalp microbiome positioning and salon-professional credibility drive differentiation beyond commoditized cleansing functions.
Skincare holds installed capacity. Haircare is rotating up the share rankings.
Distribution Channel:
Channel selection determines working capital intensity and customer data capture depth, with digital platforms compressing discovery-to-purchase cycles.
- Online Retail:Algorithmic personalization and subscription refills generate recurring revenue streams. Taobao Live and Douyin in China convert entertainment content into immediate purchase intent, while Amazon's recommendation engines dominate replenishment purchasing in the United States.
- Department Stores:Controlled distribution through concession models preserves brand exclusivity, particularly for fragrance and premium skincare. Travel retail corridors in Dubai and Seoul sustain margin premiums through duty-free pricing architectures.
- Specialty Stores:Sephora and Douglas deploy diagnostic hardware for skin analysis and color-matching, concentrating authority in personalized consultation.
- Drugstores:Mass-market accessibility depends on shelf-space negotiations and promotional frequency, with CVS and Walgreens driving volume through loyalty program integration.
Online Retail is expanding most quickly. Department Stores are defending share through exclusivity contracts.
Customer Type:
Demographic targeting shapes formulation complexity and marketing spend allocation, with male grooming representing the steepest trajectory shift.
- Women:Historical core demand spans full product categories with highest per-capita spending and subscription retention rates.
- Men:Social norm shifts in South Korea and China normalize skincare routines beyond shaving, with scalp health diagnostics opening professional salon penetration.
- Unisex:Fragrance and minimalist skincare lines reduce SKU complexity for brands pursuing streamlined inventory.
- Teenagers:TikTok-driven discovery prioritizes affordability and viral packaging over clinical efficacy claims.
Women retain volume concentration. Men are climbing the fastest in share rankings.
Packaging Type:
Primary packaging determines preservation integrity, dosing precision, and sustainability compliance costs across the value chain.
- Tubs:Wide-mouth containers suit balms and masks requiring finger application, though air exposure accelerates oxidation of sensitive actives.
- Bottles:Pump and dropper dispensers dominate serum and fluid categories, with airless designs commanding premium positioning for oxidation-prone formulations.
- Jars:Thick-walled glass or acrylic constructions signal luxury positioning for moisturizers and eye creams.
- Sachets:Single-use formats enable trial sampling and travel portability, with biodegradable films responding to EU microplastic restrictions.
Bottles hold installed capacity. Sachets are gaining share fastest through sampling economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Western Europe and Northeast Asia, while volume manufacturing gravitates toward China and Southeast Asia. Divergent regulatory timelines between the EU's REACH framework and China's NMPA approval pathways force parallel formulation tracks. Live-commerce penetration and scalp-health diagnostics are redrawing demand geography across major consumer markets.
China
Douyin and Taobao Live platforms convert entertainment content into immediate purchase intent, compressing discovery-to-checkout cycles for younger consumers. SAMR clean beauty incentives channel subsidies toward localized biotech R&D facilities in Shanghai and Hangzhou. Domestic champions like Florasis capture premium spending through live-commerce channels, raising customer acquisition costs for foreign entrants in first-tier cities.
United States
Algorithmic personalization and subscription refills dominate replenishment purchasing through Amazon's recommendation engines. FDA preservative safety thresholds diverge from EU ECHA standards, forcing distinct formulation portfolios for mass-market producers. The Pacific Northwest and Northeast Corridor concentrate indie brand incubation, with direct-to-consumer models displacing traditional department store traffic.
Germany
Professional salon channels sustain premium pricing through color-matching consultation services in Douglas and Sephora flagship locations. REACH Annex XVII microplastic restrictions eliminate certain exfoliants and glitter applications, redirecting R&D investment toward cellulose-based alternatives. The Rhine-Ruhr metropolitan region anchors formulation science clusters serving EU-wide compliance requirements.
South Korea
Social norm shifts normalize male skincare routines beyond shaving, with scalp health diagnostics opening professional salon penetration. MFDS regulatory pathways enable rapid clinical claim approval for biomimetic peptide formulations. Seoul Capital Area contract manufacturers now produce custom signal peptides at kilogram scale, fragmenting premium efficacy narratives across price tiers.
India
Rising disposable incomes in Jaipur and Indore outpace organized retail coverage, creating whitespace for direct-to-community distribution models. BIS standards for cosmetics safety diverge from FDA and ECHA thresholds, complicating import compliance for multinational portfolios. Maharashtra and Karnataka concentrate domestic manufacturing capacity for mass-market haircare and skincare categories.
Global Cosmetics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the cosmetics value chain. Precision biotechnology laboratories command premium positioning through fermentation-derived actives and clinical efficacy claims. Mass-market brand houses compete on marketing scale and shelf-space negotiations in drugstore and hypermarket channels. Strategic moves concentrate on M&A for biotech capabilities and controlled distribution partnerships in travel retail corridors.
Within the heritage conglomerate tier, L'Oréal S.A. and The Estée Lauder Companies Inc. exemplify divergent approaches to premium positioning—one anchoring dermatology credibility through skin biology research, the other sustaining exclusivity through concession-controlled department store distribution. Shiseido Company Limited occupies a distinct position linking Japanese fermentation biotechnology with regional R&D hub deployment. Unilever PLC and The Procter & Gamble Company represent scale-driven archetypes competing on portfolio breadth and emerging market penetration.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Unilever PLC |
| The Procter & Gamble Company |
| Shiseido Company Limited |
| Beiersdorf AG |
| Coty Inc. |
| Johnson & Johnson |
| Oriflame Cosmetics AG |
| Others |
Supply Flow & Price Mechanics
EU REACH Annex XVII microplastic restrictions gate both supplier qualification and price differentiation simultaneously, forcing formulators to absorb cellulose-based alternative costs or pass them through premium positioning. Certification-compliant biotech actives command spreads against commodity petrochemical derivatives, compressing margins for mass-market producers unable to access fermentation scale-up expertise.
Pricing Analysis
The customization-premium spread separates configured-to-order peptide formulations from standard emollient bases, with biomimetic actives carrying ingredient transparency premiums against bulk surfactant tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence between EU ECHA-compliant and non-compliant portfolios. Cost compression in mass-market haircare intensifies because palm oil and crude-linked feedstock volatility squeezes predictable margin structures. Professional salon channels exhibit lowest price sensitivity due to scalp-health diagnostic bundling, while drugstore replenishment purchasing shows highest elasticity.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan ports fluctuate with container availability on Asia-Europe trade lanes, elevating working capital requirements for just-in-time active ingredient deliveries. Biotech formulation capacity concentrates in South Korea, Japan, and Germany, drawing from Chinese fermentation feedstock and French specialty chemical intermediates. Single-source vulnerability sits with Japanese bio-ferment expertise, where talent scarcity constrains rapid capability replication. Distribution runs through live-commerce platforms in China, Amazon fulfillment networks in the United States, and controlled concession models in European department stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation scale-up expertise functions as the binding constraint in this market, with biotech-capable formulators capturing margin pools unavailable to marketing-dependent brand houses. The capability gap between precision laboratories and legacy manufacturers continues widening.
For Market Incumbents: Shield premium positioning through controlled distribution partnerships in travel retail corridors and department store concessions, preventing private-label substitution in color cosmetics. Accelerate backward integration into fermentation-derived active supply through regional R&D hub deployment, countering Korean contract manufacturer fragmentation of clinical efficacy narratives.
For New Entrants and Emerging Players: China's SAMR clean beauty certification fast-track channels subsidies toward localized biotech facilities, opening whitespace for green chemistry patent holders against established multinationals. Target India's tier-two cities like Jaipur and Indore through direct-to-community distribution models, exploiting organized retail coverage gaps with scalp-health diagnostic services.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biomimetic peptide synthesis capabilities, favoring precision laboratories over brand-marketing scale players across the analysis window. Acquisition targets should display in-house fermentation expertise and REACH-compliant formulation portfolios. The signal to watch is EU microplastic restriction enforcement timelines accelerating cellulose-based alternative adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotech R&D Facility Localization | SAMR subsidies in Shanghai and Hangzhou accelerate green chemistry patent development timelines. |
| Live-Commerce Channel Expansion | Douyin and Taobao Live platforms convert entertainment content into immediate purchase intent in China. |
| REACH Compliance Reformulation | Cellulose-based alternatives replace prohibited microplastic exfoliants ahead of Annex XVII deadlines. |
| Scalp Microbiome Diagnostic Deployment | Professional salon penetration captures male grooming demand beyond commoditized shaving categories. |
| Backward Integration into Fermentation | In-house bio-ferment capabilities reduce dependency on Korean and Japanese contract manufacturers. |
Methodological Framework
A spread of perspectives from brand managers, category buyers at retailers, supply planners, and channel sales heads converged on the working assumptions underlying demand projections. Primary interviews with formulation R&D directors and regulatory affairs leads at multinational houses were cross-checked against secondary validation from ECHA REACH filings, NMPA cosmetic registrations, customs trade data, and Nielsen retail audit records. Bottom-up SKU-level modeling and top-down category spend analysis were triangulated to anchor volume and value estimates.
Segmentation dimensions modeled include product type, distribution channel, customer demographic, and packaging format across the projection horizon. CAGRs were derived from trend extrapolation of live-commerce penetration rates, male grooming adoption curves, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated biomimetic peptide production scale-up timelines and EU microplastic restriction implementation schedules.
Decision-makers should treat outputs as directional under assumptions of continued live-commerce growth and stable REACH enforcement intensity; material deviation would warrant model refresh. Forecasts reflect base-case regulatory timelines and consumer behavior continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Asia-Pacific Bath and Shower Products Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Argentina Beauty and Personal Care Products Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Hair Removal Creams for Private Parts Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Advanced Night Repair Serum Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market
Beauty & Personal Care
Hair Gel Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market