
 US Sexual Wellness Market | 2026-2036
US Sexual Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
US Sexual Wellness Market Intelligence
California is tilting toward specialized manufacturing clusters for body-safe silicone formulations and intimate device assembly. Doc Johnson leverages decades of domestic production expertise to sustain its position in premium toy manufacturing. Church & Dwight anchors mass-market condom and lubricant distribution through pharmacy and supermarket channels. LELO differentiates through design-forward positioning and controlled retail partnerships.
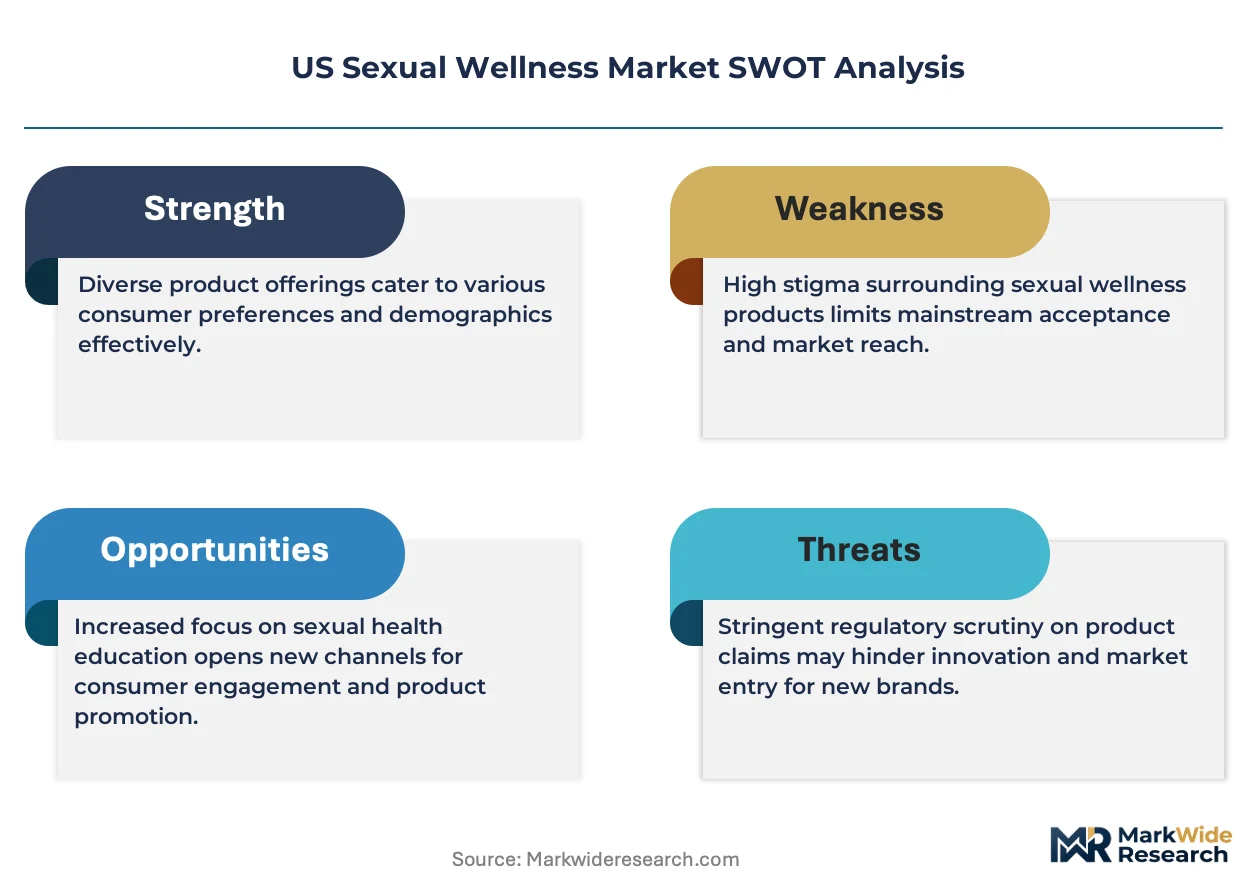
Sexual wellness encompasses products engineered for intimate health, pleasure, and reproductive safety, typically utilizing medical-grade silicone, natural rubber latex, or water-based polymer formulations manufactured under ISO 10993 biocompatibility protocols. Condoms and lubricants constitute mature, high-volume categories with established procurement patterns through pharmacy and supermarket channels. Sex toys represent the fastest-growing product type, driven by direct-to-consumer online distribution and shifting social normalization. The end user base spans adults, couples, LGBTQ+ consumers, and seniors, with premium and mid-range price segments capturing disproportionate margin pools as brand loyalty intensifies.
FDA medical device classification rules govern vibrators and related apparatus, while OSHA workplace safety standards apply to manufacturing facilities handling latex and chemical lubricant bases. FTC advertising guidelines restrict unsubstantiated health claims for performance enhancers. State-level regulations in California under Proposition 65 mandate chemical disclosure labeling that affects formulation choices nationwide. Stakeholders must monitor evolving FDA guidance on software-enabled intimate devices and anticipate how state privacy laws could reshape consumer data practices in online sexual wellness retail.
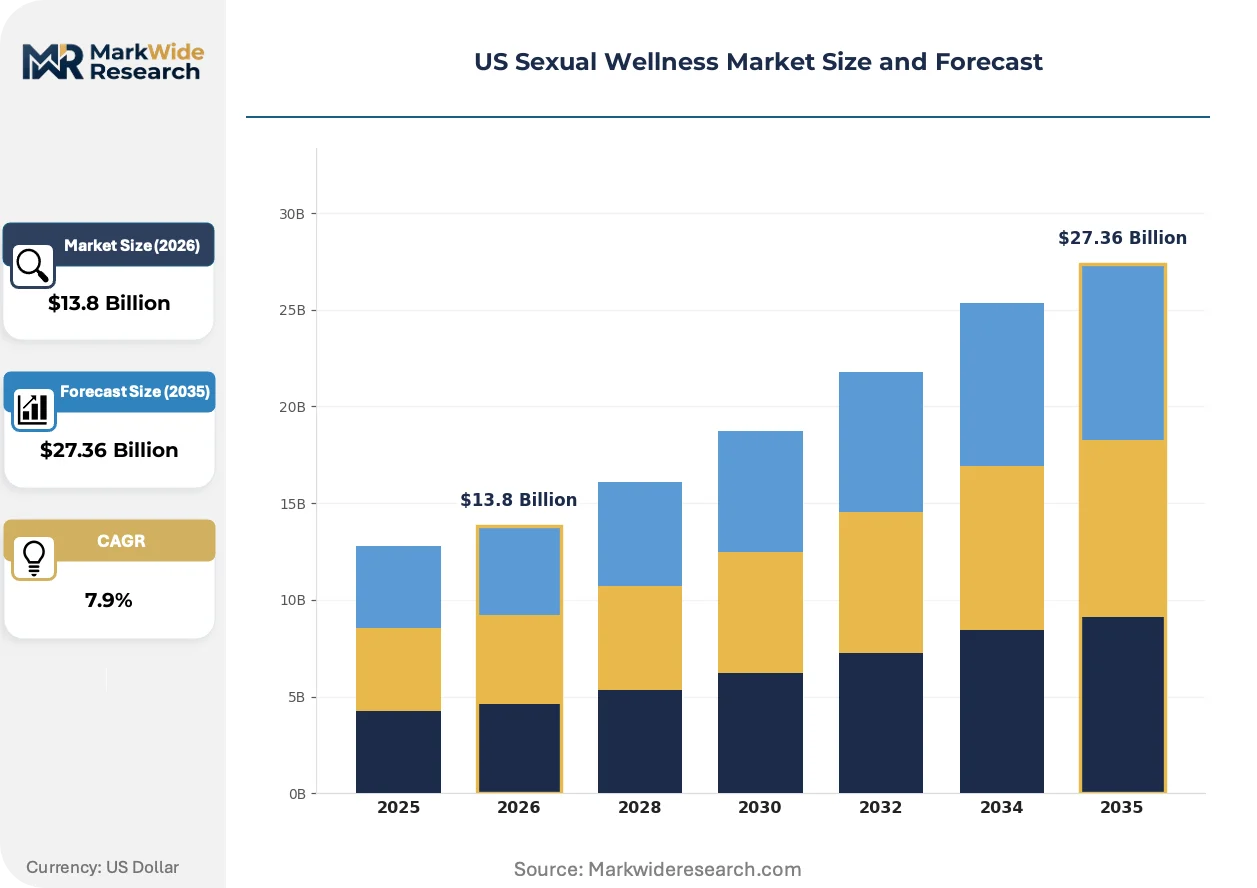
Market Dynamics
Direct-to-consumer e-commerce platforms are compressing traditional retail margins while FDA medical device reclassifications force manufacturers to recalibrate compliance architectures. California's Proposition 65 chemical disclosure mandates ripple through national formulation decisions.
Growth Catalysts
- Telehealth integration:Remote intimate health consultations normalize product recommendations from licensed clinicians, expanding prescription-adjacent channels for therapeutic devices.
- ISO 10993 biocompatibility protocols:Standardized material safety testing reduces buyer hesitation and accelerates insurance reimbursement pathways for medical-grade intimate wellness products.
- Texas and Florida demand clusters:Population density in Sun Belt metros supports dedicated distribution centers, cutting last-mile delivery times for discreet packaging services.
Market Restraints
- Medical-grade silicone price volatility:Petrochemical feedstock fluctuations compress gross margins for domestic manufacturers reliant on specialty polymer suppliers.
- FDA 510(k) clearance timelines:Software-enabled intimate devices face unpredictable review periods, freezing product launch schedules and capital deployment.
- Condom substitution by LARC methods:Long-acting reversible contraceptives prescribed through Planned Parenthood and hospital systems erode steady-state latex demand.
Strategic Opportunities
- Menopause-focused therapeutic segments:FDA-cleared vibratory devices for vulvovaginal atrophy address an underserved demographic with reimbursable clinical indications.
- Subscription-based replenishment models:Lubricant and condom auto-delivery locks in recurring revenue while reducing customer acquisition costs.
- OSHA Voluntary Protection Programs:Manufacturing facilities achieving VPP Star certification differentiate for B2B procurement from hospital system purchasing cooperatives.
Industry Challenges
- Biomedical engineering talent scarcity:Firmware developers with ISO 13485 experience command premium compensation, constraining connected device roadmaps.
- Prop 65 litigation exposure:California plaintiff firms target chemical disclosure gaps, forcing defensive labeling investments that propagate nationwide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sexual Wellness Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $27.36 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condoms, Lubricants, Sex Toys, Performance Enhancers End User: Adults, Couples, LGBTQ+, Seniors Distribution Channel: Online, Pharmacies, Specialty Stores, Supermarkets Price Segment: Premium, Mid-Range, Economy, Discount |
| Companies Covered | Doc Johnson, Okamoto Industries, Church & Dwight, LELO, Karex Berhad, LifeStyles, Diamond Products, Dame Products, Reckitt Benckiser Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sexual Wellness Market Strategic Shifts & Innovations
Software-enabled intimate devices are forcing hardware manufacturers to build firmware competencies while material scientists pursue bio-based alternatives to petroleum-derived formulations.
App-controlled vibration patterns and biometric feedback loops are migrating from novelty features to standard expectations among premium buyers. Millennial and Gen Z consumers treat connected functionality as baseline, compressing price premiums for basic mechanical devices. This capability threshold is migrating from high-end LELO and We-Vibe SKUs into mid-tier private-label offerings sold through Amazon and Target.
FDA draft guidance on software-as-medical-device classifications is tightening quality management system requirements for firmware updates. Manufacturers must now document cybersecurity controls and over-the-air patch protocols before 510(k) clearance. Connected intimate wellness brands are responding by segregating US-bound product lines from EU MDR and Health Canada pathways to contain compliance scope.
Subscription bundling of lubricants, condoms, and toy cleaners is displacing single-transaction pharmacy purchases among urban millennials. Urban Outfitters and Sephora curate sexual wellness assortments alongside skincare, normalizing cross-category browsing. This channel convergence is most visible in Brooklyn, Austin, and Portland metro areas where wellness retail density supports experiential merchandising.
US Sexual Wellness Market Segmentation
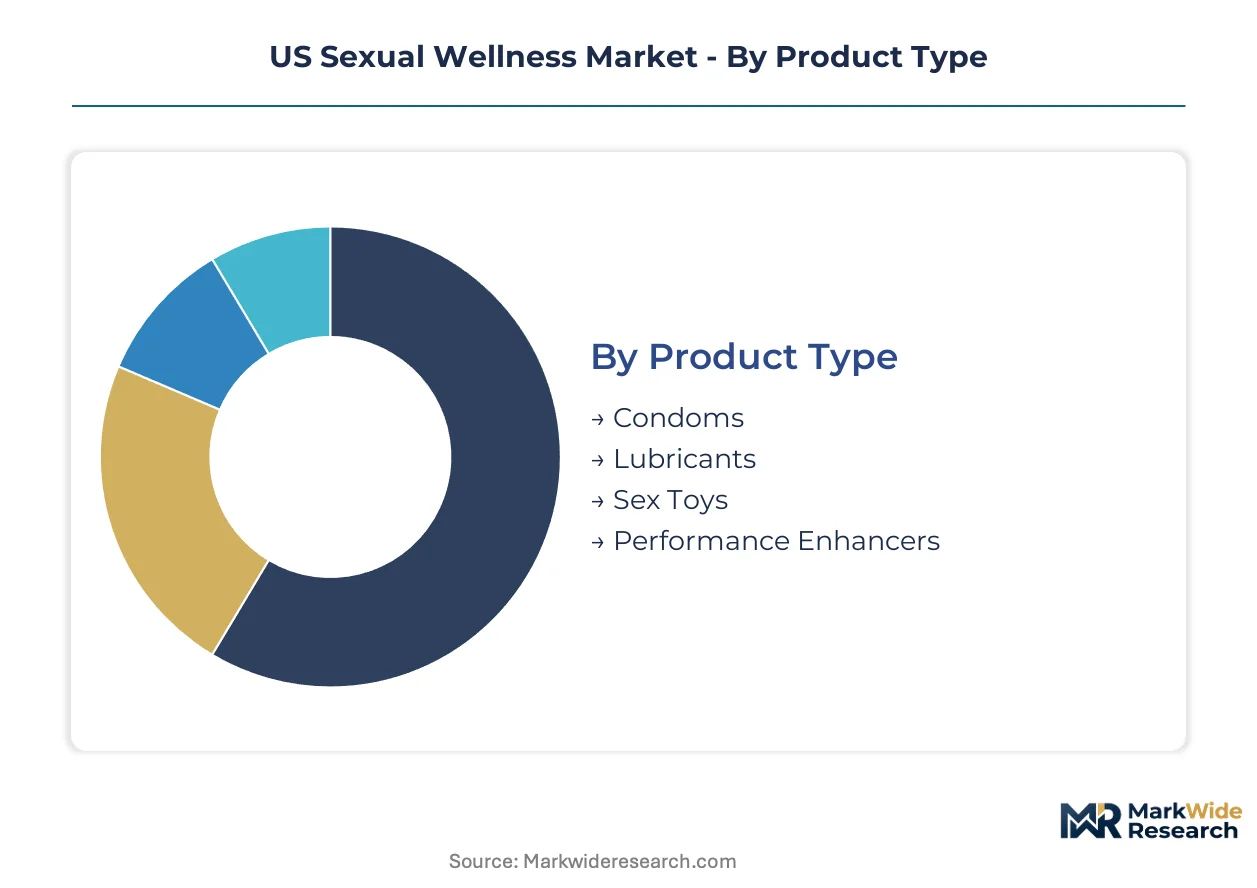
Segmentation in US sexual wellness reveals how FDA device classifications, discreet purchasing preferences, and demographic-specific needs fragment demand across incompatible channel strategies. Manufacturers must calibrate formulation standards, packaging protocols, and marketing compliance separately for each slice.
Product Type:
Product categories span from regulated medical devices to unregulated wellness consumables, each demanding distinct material certifications and channel access.
- Sex Toys:Medical-grade silicone and ABS plastic constructions undergo ISO 10993 biocompatibility testing. Demand concentrates in California and New York metro areas where direct-to-consumer brands maintain fulfillment infrastructure, though FDA 510(k) clearance timelines for app-enabled devices compress margin realization.
- Lubricants:Water-based, silicone-based, and hybrid polymer formulations compete on osmolality and pH compatibility metrics. Pharmacy and supermarket procurement in Texas and Florida drives volume, with Prop 65 disclosure requirements forcing nationwide reformulation of glycerin and paraben-containing variants.
- Condoms:Natural rubber latex and polyisoprene sheaths manufactured under FDA 510(k) quality system regulations. Planned Parenthood and hospital system purchasing cooperatives anchor institutional demand.
- Performance Enhancers:Topical desensitizers and herbal supplements face FTC advertising scrutiny for unsubstantiated erectile claims. Online subscription bundling with toys and lubricants dominates distribution.
Established volume favors condoms; emerging adoption favors sex toys.
End User:
Demographic targeting requires navigating divergent privacy expectations, clinical validation demands, and cultural normalization thresholds.
- Adults:Individual purchasers aged 25-45 drive replenishment cycles for lubricants and condoms through pharmacy auto-refill programs.
- Couples:Joint purchasing decisions elevate design-forward aesthetics and shared control features as selection criteria, with Brooklyn and Austin retail clusters supporting experiential trial.
- LGBTQ+:Specialized retailers and community-focused e-commerce platforms curate gender-affirming products and inclusive educational content, commanding loyalty premiums.
- Seniors:Medicare-eligible consumers seeking FDA-cleared vibratory devices for vulvovaginal atrophy represent the steepest expansion trajectory, with telehealth integration unlocking prescription-adjacent reimbursement pathways.
Volume concentration sits with adults; margin expansion sits with seniors.
Distribution Channel:
Channel selection determines compliance burden, customer acquisition economics, and brand positioning latitude.
- Online:Direct-to-consumer platforms and Amazon Marketplace capture the steepest expansion trajectory through discreet packaging and algorithmic personalization, though state privacy laws reshape data practices.
- Pharmacies:CVS, Walgreens, and Rite Aid chains anchor condom and lubricant replenishment with pharmacist endorsement credibility, limiting SKU breadth for devices.
- Specialty Stores:Babeland, Good Vibrations, and curated Sephora assortments enable tactile evaluation and staff consultation, concentrating in coastal urban clusters.
- Supermarkets:Mass-market condom placement in Target and Walmart generates impulse volume at compressed margins, with planogram constraints excluding most toy categories.
Margin structure favors specialty stores; volume scale favors supermarkets.
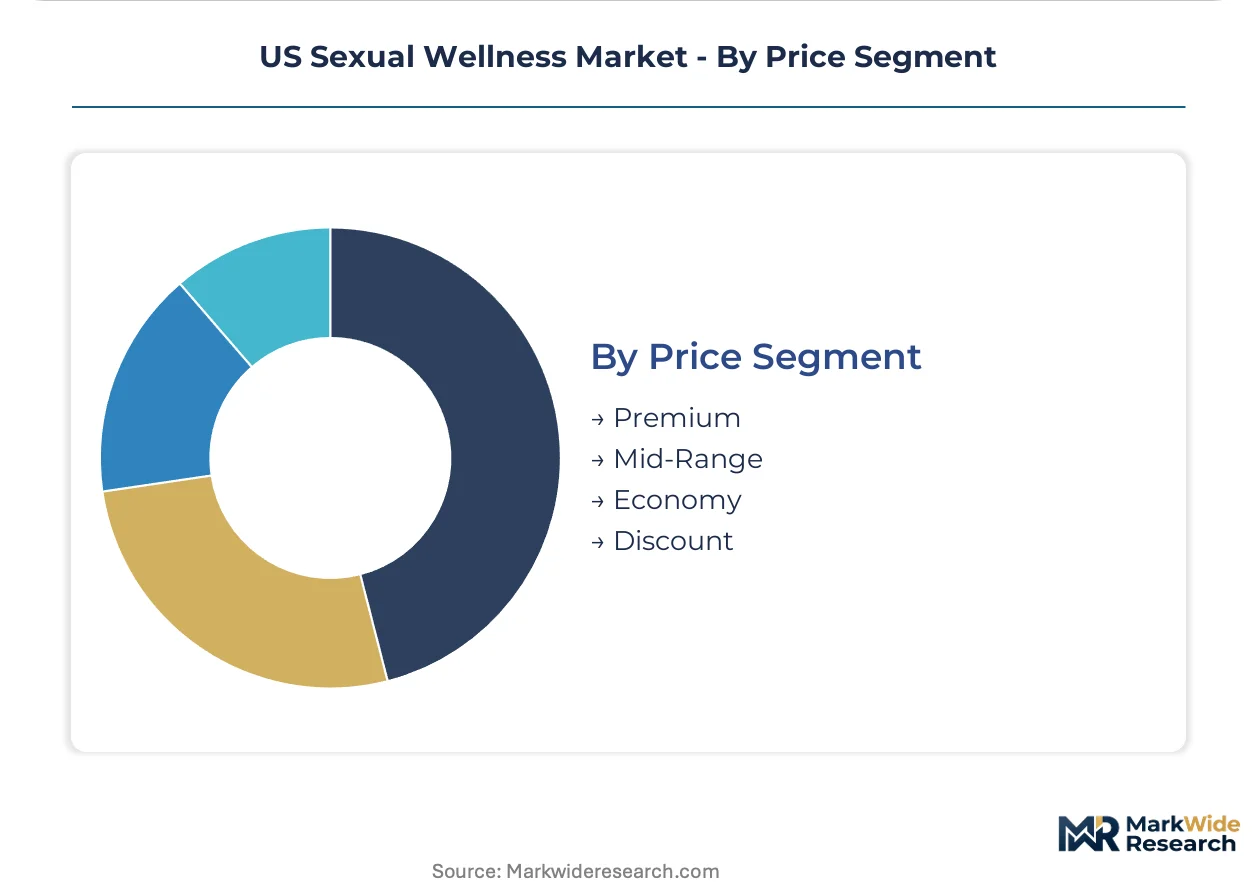
Price Segment:
Pricing tiers correlate with material certification grade, firmware sophistication, and retail channel markup requirements.
- Premium:Medical-grade silicone, app connectivity, and extended warranties justify 3-5x economy pricing, with LELO and We-Vibe anchoring positioning through controlled retail partnerships.
- Mid-Range:Private-label offerings from Amazon and Target absorb connectivity features from premium tiers at 40-60% price discounts, capturing mainstream adoption.
- Economy:Basic mechanical devices and standard lubricant formulations serve price-sensitive demand through supermarket and drugstore channels.
- Discount:Unbranded imports and closeout inventory circulate through gray-market e-commerce, bypassing FDA registration and material testing protocols.
Revenue concentration favors mid-range; brand equity accrues to premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing clusters for silicone formulations and intimate device assembly concentrate in coastal states with established wellness retail infrastructure. FDA oversight and California's Proposition 65 disclosure mandates ripple through national formulation decisions regardless of production location.
California
Los Angeles and San Fernando Valley host specialized manufacturing facilities for medical-grade silicone formulations and device assembly. FDA 510(k) quality system regulations govern local production of app-enabled intimate devices, extending clearance timelines for firmware-upgradable products. Oakland and San Francisco retail clusters support experiential merchandising through curated wellness boutiques.
New York
Brooklyn and Manhattan anchor the densest concentration of direct-to-consumer brand headquarters and fulfillment infrastructure. State privacy laws reshape consumer data practices for online sexual wellness retailers operating from New York metro data centers. Buffalo and Rochester distribution nodes serve discreet packaging services for Northeast corridor demand.
Texas
Dallas-Fort Worth and Houston metro areas support dedicated distribution centers cutting last-mile delivery times for e-commerce fulfillment. OSHA workplace safety standards apply to manufacturing facilities handling latex and chemical lubricant bases in the Gulf Coast petrochemical corridor. Austin retail clusters normalize sexual wellness merchandising alongside skincare and lifestyle categories.
Florida
Miami and Tampa Bay population density supports pharmacy and supermarket procurement volume for condom and lubricant replenishment. FTC advertising guidelines restrict unsubstantiated health claims for performance enhancers distributed through Florida-based online subscription services. Orlando logistics hubs serve discreet direct-to-consumer shipping throughout the Southeast.
Illinois
Chicago anchors Midwest distribution networks for mass-market condom placement through pharmacy and supermarket chains. ISO 10993 biocompatibility protocols guide material testing for silicone formulations processed through regional polymer suppliers. Planned Parenthood purchasing cooperatives in Illinois anchor institutional demand for latex products.
US Sexual Wellness Market Key Industry Players
Heritage domestic manufacturers and design-forward premium specialists split the market into incompatible capability tiers. Consolidation pressures concentrate around FDA medical device reclassifications and direct-to-consumer channel economics. Two strategic archetypes dominate: vertically integrated fabricators with decades of domestic production expertise, and digitally native brands built on controlled retail partnerships and firmware-enabled differentiation. Competitive moves center on compliance architecture recalibration and subscription-based replenishment model deployment.
Among heritage domestic fabricators, Doc Johnson exemplifies vertically integrated manufacturing archetypes with established silicone formulation and device assembly capabilities. Church & Dwight anchors mass-market distribution through pharmacy and supermarket channel dominance. LELO occupies a position within the design-forward premium tier, representing controlled retail partnership strategies that segregate product lines by regulatory pathway.
| Leading Market Players |
|---|
| Doc Johnson |
| Okamoto Industries |
| Church & Dwight |
| LELO |
| Karex Berhad |
| LifeStyles |
| Diamond Products |
| Dame Products |
| Reckitt Benckiser Group |
| Others |
Cost & Logistics Intelligence
Undercapacity in California medical-grade silicone compounding facilities is driving dual supplier behavior: premium tier manufacturers are securing long-term offtake agreements while mid-market brands absorb spot market volatility through formula adjustments. This utilization squeeze feeds directly into pricing posture, with FDA-cleared device makers passing through material premiums while economy tier competitors compress margins to maintain shelf positioning.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across intimate wellness devices, separating reimbursable medical-grade vibrators from discretionary consumer electronics. Three-tier pricing stratification across premium, standard, and economy levels correlates with ISO 10993 certification depth and firmware sophistication. Cost compression in the economy tier is intensifying because Amazon private-label absorption of connectivity features erodes mechanical-only value propositions. Pharmacy channel buyers exhibit highest price sensitivity, while specialty boutique purchasers prioritize material provenance over unit economics.
Supply Chain Analysis
Petrochemical feedstock volatility between Gulf Coast refiners and Asian silicone polymer producers dominates supply chain risk exposure for domestic manufacturers. Production gravity centers on California compounding facilities, Guangdong injection molding clusters, and Malaysian latex processing plants. Raw material dependencies span medical-grade silicone elastomers, ABS engineering resins, and natural rubber latex sheaths. Single-source vulnerability concentrates in FDA-registered polymer suppliers with validated biocompatibility dossiers. Distribution runs through direct-to-consumer fulfillment nodes in Brooklyn and Dallas-Fort Worth, with discreet packaging protocols adding last-mile cost premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US sexual wellness market sits in early-cycle expansion as telehealth integration normalizes clinician-endorsed intimate health products, accelerating prescription-adjacent penetration among Medicare-eligible demographics previously underserved by discretionary retail channels.
For Market Incumbents: Harden compliance architecture against FDA software-as-medical-device reclassifications by segregating firmware update protocols before 510(k) submission. Anchor silicone formulation capacity in California manufacturing clusters to preempt Proposition 65 litigation exposure. Vertical integration into medical-grade polymer compounding defends margin position against petrochemical feedstock volatility threatening Gulf Coast suppliers. For New Entrants and Emerging Players: Build out menopause-focused therapeutic segments where FDA-cleared vibratory devices for vulvovaginal atrophy face minimal incumbent competition and unlock reimbursable clinical indications. Target senior demographics through telehealth partnerships as the most penetrable end-user segment with prescription-adjacent channel access. Deploy subscription-based lubricant replenishment models to capture recurring revenue before customer acquisition costs escalate. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA 510(k) clearance moats compound over firmware-enabled product generations, consolidating value among compliant manufacturers. Acquisition target archetypes include vertically integrated fabricators with ISO 13485 quality systems and established silicone formulation expertise. Monitor FDA draft guidance finalization on cybersecurity controls as the inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks prescription-adjacent reimbursement for therapeutic intimate devices through Medicare pathways. |
| Telehealth Platform Integration | Enables licensed clinician endorsement that normalizes product recommendations for underserved senior demographics. |
| Subscription Replenishment Model | Captures recurring lubricant and condom revenue while reducing customer acquisition costs in competitive online channels. |
| California Manufacturing Footprint | Secures Proposition 65 compliance advantage that propagates nationwide through defensive labeling investments. |
| Biocompatibility Certification Investment | Accelerates insurance reimbursement pathways for medical-grade intimate wellness products under ISO 10993 protocols. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with sexual wellness manufacturing executives, FDA regulatory affairs specialists, and hospital GPO contracts managers; and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and Nielsen retail audit data. Bottom-up demand modeling triangulated against top-down market sizing across product type, end-user demographic, and distribution channel dimensions.
Forecast inputs considered adoption curve trajectories for software-enabled devices, telehealth integration penetration rates, and Proposition 65 compliance cost propagation across the projection horizon. Segmentation modeling spanned product category, user demographic, price tier, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for FDA clearance timeline uncertainty and material cost volatility assumptions.
Stress conditions across FDA reclassification timing, silicone polymer price bands, and state privacy law enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding telehealth adoption velocity and reimbursement pathway expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
At Home Hair Dye Market