
 Global and North America Organic and Natural Feminine Care Market | 2026-2036
Global and North America Organic and Natural Feminine Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global and North America Organic and Natural Feminine Care Market Foresight
Organic cotton is expanding its share of top-sheet and absorbent-core formulations across pads and liners, displacing conventional bleached rayon in mid-tier and premium lines. Procter & Gamble Co. leverages its retail shelf-space dominance to maintain conventional-to-natural hybrid portfolios in mass-market channels. Seventh Generation anchors its positioning through USDA BioPreferred and Safer Choice certifications that command shelf placement in Whole Foods and Target locations. Rael differentiates via Korean-manufactured organic cotton supply chains with OCS 100 traceability.
Organic and natural feminine care comprises menstrual and daily hygiene products manufactured without synthetic pesticides, chlorine bleach, petrochemical-derived fragrances, or artificial absorbents, typically utilizing certified organic cotton, plant-based cellulose, or medical-grade silicone as primary materials. These goods serve consumers seeking reduced dermal exposure to endocrine-disrupting compounds and lower environmental persistence through compostable or biodegradable disposal pathways. Organic sanitary pads occupy the largest revenue pool due to higher per-unit pricing and established consumer familiarity, while biodegradable menstrual cups represent the fastest-expanding segment as one-product multi-cycle economics attract cost-conscious and sustainability-motivated buyers. Distribution through online retailers is capturing share from pharmacies as subscription models and direct-to-consumer education content reduce purchase friction for first-time natural product adopters.
FDA biocompatibility evaluations and EPA Safer Choice standards govern material safety claims for products sold in the United States, while REACH restrictions on residual formaldehyde and phthalates shape formulation decisions for European market access. ECHA's ongoing microplastic restriction proposals threaten conventional synthetic absorbent polymers, accelerating converter investment in cellulose-based alternatives. Stakeholders must monitor how impending state-level ingredient disclosure laws in California and New York will fragment labeling requirements beyond federal baselines.
Market Dynamics
REACH restrictions on residual formaldehyde and phthalates are compressing formulation timelines for European market access, forcing converters to accelerate cellulose-based absorbent polymer substitution before ECHA microplastic bans take effect.
Growth Catalysts
- US FDA biocompatibility evaluations:Material safety testing mandates are elevating certified organic cotton as the default compliant input for intimate care goods sold through mass retail channels.
- Subscription commerce infrastructure:Direct-to-consumer platforms with educational content layers are reducing trial friction for first-time natural product adopters in Germany and Canada.
- Working women demographic concentration:Professional cohorts across North America are prioritizing dermal exposure reduction, driving certified organic cotton purchases through premium distribution channels.
Market Restraints
- Organic cotton input cost volatility:Climate-induced yield fluctuations in Turkey and India are compressing converter margins and limiting price accessibility for mass-market tiers.
- Korean supply chain concentration:OCS 100-certified organic cotton manufacturing clusters in South Korea create single-source vulnerability for traceability-dependent brands.
- Cellulose absorbency technical ceiling:Plant-based core materials currently underperform synthetic superabsorbent polymers on overnight capacity metrics, restricting premium positioning.
Strategic Opportunities
- California and New York state disclosure laws:Impending ingredient transparency mandates will fragment labeling requirements beyond federal baselines, creating first-mover advantage for pre-compliant portfolios.
- Biodegradable menstrual cup segment:One-product multi-cycle economics attract cost-conscious and sustainability-motivated buyers underserved by incumbent pad-centric assortments.
- EPA Safer Choice certification pathway:Federal eco-label recognition unlocks institutional procurement channels including university and corporate campus vending networks.
Industry Challenges
- USDA BioPreferred certification timeline:Multi-year audit cycles for biobased content verification delay product launches and tie up working capital in inventory hold.
- Compostability standard fragmentation:Incompatible industrial versus home composting certifications across municipalities create consumer confusion and return-rate elevation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global and North America Organic and Natural Feminine Care Market |
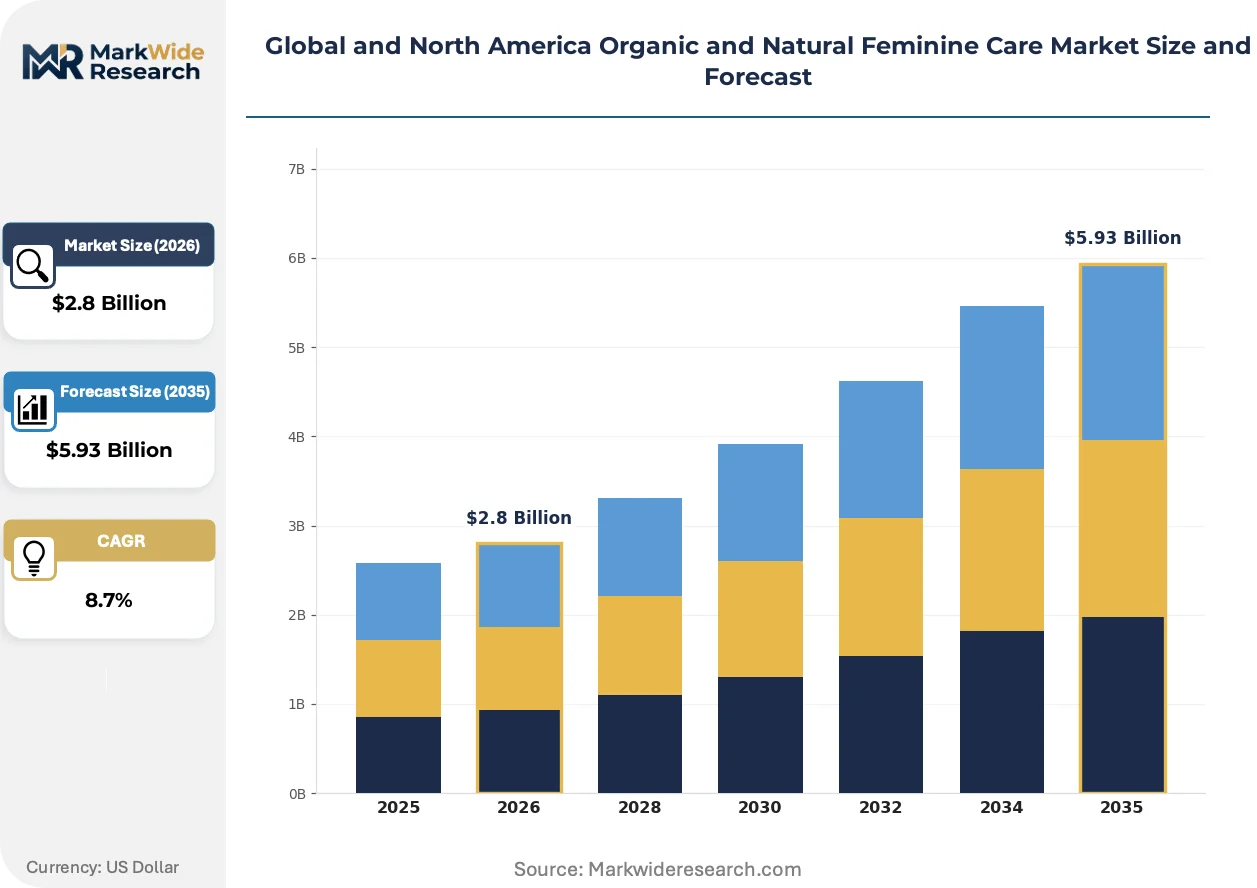
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Sanitary Pads, Natural Tampons, Herbal Panty Liners, Biodegradable Menstrual Cups, Compostable Wipes Customer Type: Teenagers, Young Adults, Working Women, Expectant Mothers, Seniors Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Supermarkets, Direct Sales Application: Daily Hygiene, Menstrual Protection, Postpartum Care, Sensitive Skin Care, Odor Control |
| Companies Covered | Unilever PLC, Seventh Generation, The Honest Company, Inc., Rael, Cora, The Honey Pot Company, LLC, Natracare, Organyc, Procter & Gamble Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global and North America Organic and Natural Feminine Care Market Shifts & Advancements
Material traceability systems and biobased certification protocols are compressing competitive differentiation timelines, rewarding converters who embed supply chain visibility into product storytelling before regulatory mandates harden.
Plant-based cellulose cores are integrating into overnight pad formulations as the primary absorbent layer, replacing petroleum-derived superabsorbent polymers. German and Canadian distributors are accelerating SKU expansion for these lines. This integration is enabling mid-tier brands to capture premium price positioning without full organic cotton cost structures.
ECHA microplastic restriction proposals are accelerating converter investment in cellulose-based alternatives ahead of formal implementation. Formulation teams are requalifying absorbent cores under REACH pre-registration protocols. Menstrual cup manufacturers with medical-grade silicone supply chains face reduced compliance burden compared to conventional pad producers.
Certification-driven preference shifts are elevating USDA BioPreferred and OCS 100 labels above legacy brand equity in purchase decisions. Whole Foods and Target shelf placement algorithms now weight certified biobased content scores in category management reviews. This behavior is most visible in United States coastal metropolitan markets where ingredient literacy rates exceed national averages.
Global and North America Organic and Natural Feminine Care Market Segmentation
Consumer upgrade cycles in feminine care are shortening as certification literacy spreads, forcing brands to align product architectures with distinct usage occasions and procurement preferences. Segmentation clarity enables converters to match material investments—organic cotton, plant cellulose, or medical silicone—to the specific performance and transparency demands of each buyer cohort.
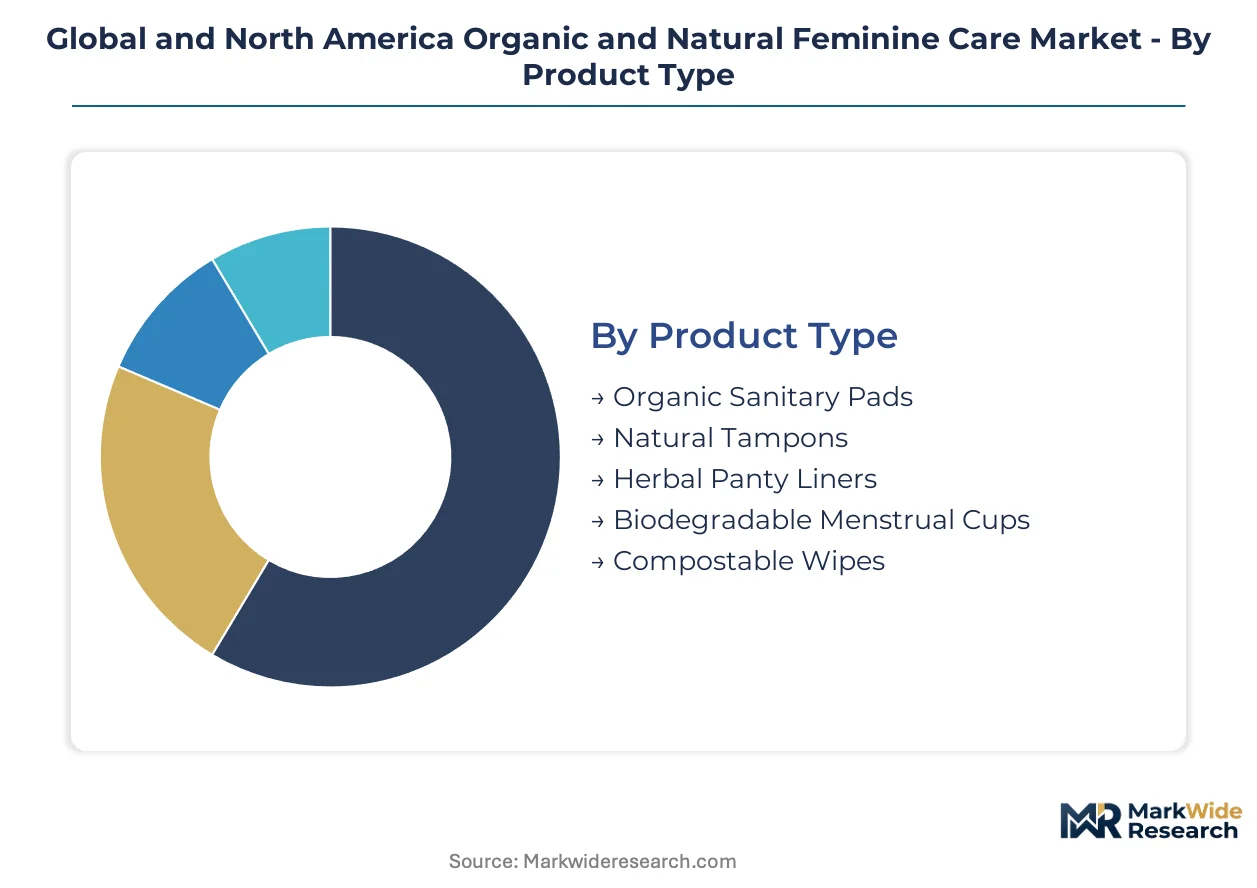
Product Type:
Replacement frequency and per-unit economics dictate how consumers trade between disposable and reusable formats across their menstrual lifecycle.
- Organic Sanitary Pads:Multi-layer constructions with certified organic cotton top sheets and plant-based absorbent cores dominate shelf space in United States mass retail. German and Canadian distributors prioritize these SKUs for working women seeking dermal exposure reduction without behavioral change.
- Natural Tampons:Compact cylindrical formats using organic cotton fiber and cardboard applicators attract athletic and swim-active users in coastal United States metros. FDA biocompatibility testing requirements elevate certified inputs as the compliance default for pharmacy channel placement.
- Herbal Panty Liners:Thin daily-use products with botanical-infused organic cotton covers address odor-conscious teenagers and young adults through specialty store channels.
- Biodegradable Menstrual Cups:Medical-grade silicone cups with multi-year lifespans are gaining share fastest among cost-conscious sustainability adopters in Germany and Canada.
- Compostable Wipes:Plant-fiber cleansing cloths with pH-balanced formulations serve postpartum and sensitive skin segments through subscription commerce platforms.
Organic sanitary pads sit at the top of the volume ranking, with biodegradable menstrual cups climbing the fastest.
Customer Type:
Purchase authority and price sensitivity diverge sharply across life stages, with professional cohorts driving premium certification demand.
- Working Women:Time-constrained professionals across United States urban centers prioritize subscription-delivered certified organic assortments that eliminate in-store decision friction. This cohort accepts per-unit premiums for USDA BioPreferred and OCS 100 traceability.
- Young Adults:University-aged buyers in Germany and Canada exhibit high ingredient literacy and trial willingness for reusable formats, accelerating menstrual cup adoption through peer recommendation networks.
- Teenagers:First-time product users influenced by parental purchasing patterns show elevated sensitivity to skin irritation claims and fragrance-free positioning.
- Expectant Mothers:Postpartum-focused buyers seek super-absorbent organic pads and compostable wipes through hospital discharge kits and specialty maternity retailers.
- Seniors:Light incontinence and daily hygiene needs drive panty liner volume through pharmacy loyalty programs with predictable replenishment cycles.
Working women generate the highest revenue per capita, while young adults are expanding most quickly as a buyer pool.
Distribution Channel:
Channel selection determines which certification signals reach consumers at the point of purchase decision.
- Online Retailers:Direct-to-consumer platforms with educational content layers reduce trial friction for first-time natural product adopters in Germany and Canada. Subscription models lock in recurring revenue and capture preference data for SKU optimization.
- Specialty Stores:Whole Foods and Target shelf placement algorithms weight certified biobased content scores, elevating USDA BioPreferred and Safer Choice labels above legacy brand equity.
- Pharmacies:CVS and Walgreens chains retain conventional-to-natural hybrid portfolios where FDA biocompatibility claims support insurance-adjacent health positioning.
- Supermarkets:Mass-market grocers in United States heartland states carry limited organic cotton assortments at price points competing with conventional rayon products.
- Direct Sales:Brand-owned pop-ups and campus vending networks leverage EPA Safer Choice certification for institutional procurement contracts.
Online retailers command the steepest expansion trajectory, though specialty stores maintain the highest average transaction values.
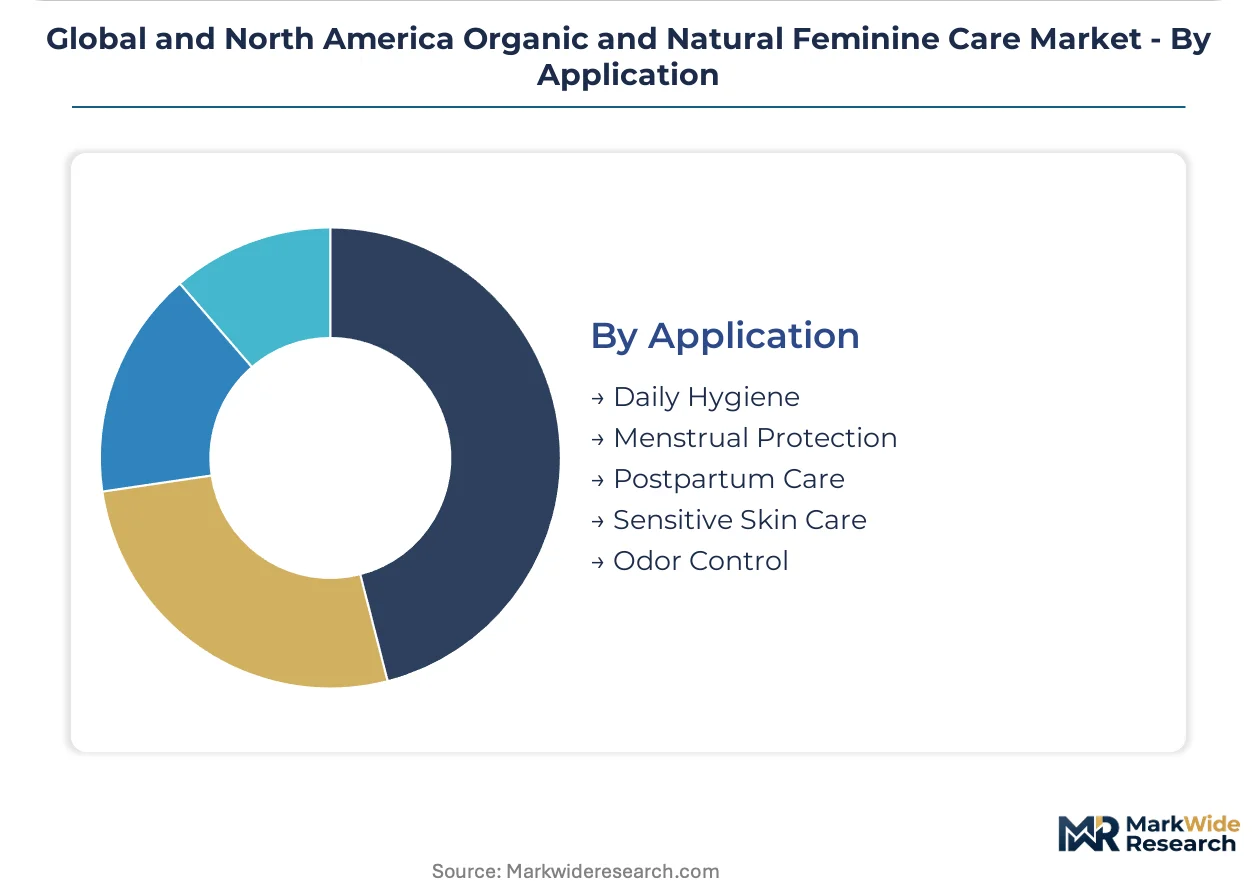
Application:
Usage occasion intensity shapes absorbent performance requirements and disposal convenience priorities.
- Menstrual Protection:Heavy-flow and overnight demands stress-test plant-based absorbent cores against synthetic superabsorbent polymer benchmarks, limiting premium positioning for cellulose-only formulations.
- Daily Hygiene:Non-menstrual panty liner use concentrates in working women seeking freshness maintenance without dermal irritation from petrochemical fragrances.
- Postpartum Care:Hospital discharge and home recovery periods drive super-absorbent organic pad volume with clinical-grade absorbency requirements.
- Sensitive Skin Care:Dermatologist-recommended organic cotton products serve eczema and allergy-prone users through pharmacy and specialty channels.
- Odor Control:Botanical-infused liners and pH-balanced wipes address social anxiety around freshness without masking fragrances.
Menstrual protection anchors absolute volume, with postpartum care gaining share fastest among hospital-system contract suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States retail clusters in coastal metropolitan corridors command premium shelf placement for certified organic feminine care assortments. FDA biocompatibility evaluations and EPA Safer Choice standards govern material safety claims nationwide. REACH restrictions on residual formaldehyde and phthalates compress formulation timelines for European market access, forcing cross-border supply chain adjustments.
United States
Working women in coastal metropolitan markets drive certified organic cotton purchases through subscription commerce platforms. California and New York state disclosure laws fragment labeling requirements beyond federal FDA baselines. Whole Foods and Target shelf placement algorithms in urban corridors weight USDA BioPreferred scores above legacy brand equity.
Germany
Young adult buyers in university towns exhibit high ingredient literacy and accelerate menstrual cup adoption through peer networks. ECHA microplastic restriction proposals accelerate converter investment in cellulose-based absorbent alternatives ahead of formal REACH implementation. Distributors in Berlin and Hamburg prioritize SKU expansion for plant-based cellulose core formulations.
Canada
Professional cohorts in Toronto and Vancouver prioritize dermal exposure reduction through premium distribution channels. Health Canada regulations align with FDA biocompatibility standards while maintaining distinct labeling requirements for natural health product claims. Subscription models capture preference data for SKU optimization in metropolitan British Columbia and Ontario markets.
South Korea
OCS 100-certified organic cotton manufacturing clusters supply traceability-dependent brands serving North American and European export demand. MFDS regulations govern medical-grade silicone menstrual cup production for institutional procurement channels. Seoul-based converters face single-source vulnerability pressures as brands seek supply chain diversification.
India
Organic cotton cultivation in Maharashtra and Gujarat supplies raw material inputs subject to climate-induced yield volatility. BIS standards for feminine hygiene products create compliance benchmarks for domestic market access. Processing facilities in Tamil Nadu and Karnataka serve as emerging alternatives to Korean manufacturing concentration.
Global and North America Organic and Natural Feminine Care Market Competitive Landscape
Global majors compete with regional champions across certification and traceability dimensions in the organic and natural feminine care sector. Mass-market incumbents leverage retail shelf-space dominance to maintain conventional-to-natural hybrid portfolios, while specialist challengers anchor positioning through USDA BioPreferred and OCS 100 certifications. Three strategic archetypes dominate: legacy FMCG conglomerates with hybrid portfolios, pure-play natural specialists with supply chain transparency, and direct-to-consumer disruptors with subscription infrastructure. Competitive moves concentrate on certification pre-compliance ahead of state-level disclosure mandates and supply chain diversification away from Korean manufacturing clusters.
Among mass-market incumbents, Procter & Gamble Co. exemplifies the hybrid portfolio archetype, occupying shelf space across conventional and natural-tier assortments. Seventh Generation anchors the certified specialist tier through USDA BioPreferred and Safer Choice credentials that command placement in premium retail channels. Rael occupies a position within the traceability-focused segment, representing supply chain transparency strategies dependent on OCS 100-certified manufacturing.
| Leading Market Players |
|---|
| Unilever PLC |
| Seventh Generation |
| The Honest Company, Inc. |
| Rael |
| Cora |
| The Honey Pot Company, LLC |
| Natracare |
| Organyc |
| Procter & Gamble Co. |
| Others |
Supply & Pricing Matrix
Organic cotton fiber costs originating from Maharashtra and Gujarat cultivation zones transmit directly through converter margins into three-tier pricing structure across premium, standard, and economy levels for finished pads and liners. Climate-induced yield volatility in these Indian states compresses mass-market tier accessibility while Korean OCS 100-certified manufacturing clusters command premium positioning through traceability premiums.
Pricing Analysis
Input-cost pass-through from Turkish and Indian organic cotton harvests drives tier stratification across certification grades. USDA BioPreferred and OCS 100 labels command shelf placement premiums at Whole Foods and Target, while conventional rayon-blend products compete on unit economics in heartland supermarkets. Pricing pressure stems from climate volatility compressing converter margins, with working women in coastal metros showing least price sensitivity and mass-market conventional buyers most responsive to per-unit differentials.
Supply Chain Analysis
Organic cotton supply rests on cultivation clusters in India and Turkey, with OCS 100-certified processing concentrating in South Korean manufacturing hubs. Medical-grade silicone for menstrual cups draws from specialized polymer suppliers, while plant-based cellulose cores feed from Nordic and Canadian pulp operations. Single-source vulnerability in Korean traceability-dependent production creates structural risk, with distribution running through subscription platforms and specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA biocompatibility mandates in the United States and REACH pre-registration timelines in Europe creates cost and compliance differentials for converters with dual-market exposure.
For Market Incumbents: Hedge against Korean supply chain concentration by cultivating alternative OCS 100-certified processing relationships in India and Vietnam. Accelerate cellulose-based absorbent core R&D to preempt ECHA microplastic restrictions while defending shelf space through hybrid portfolio maintenance at CVS and Walgreens. For New Entrants and Emerging Players: Subscription commerce platforms represent the most penetrable channel for first-time natural product adopters in Germany and Canada. Target young adult buyers in university towns with peer-networked menstrual cup education, leveraging cost-per-cycle economics against incumbent pad-centric assortments. For Investors and Strategic Acquirers: Consolidation pressure builds where certification pre-compliance investments outstrip working capital availability for mid-tier converters. Long-term viability favors traceability-integrated specialists with captive organic cotton supply relationships. Watch California and New York state disclosure law implementation timelines as inflection indicators for first-mover certification advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Compliance Investment | USDA BioPreferred and OCS 100 credentials unlock Whole Foods and Target shelf placement algorithms. |
| Supply Chain Diversification | Alternative processing in India and Vietnam reduces Korean manufacturing cluster dependency. |
| Direct-to-Consumer Platform Launch | Subscription models with educational content layers capture preference data in Germany and Canada. |
| Cellulose Core Formulation Development | Plant-based absorbent alternatives preempt ECHA microplastic restriction implementation. |
| Sustainability Repositioning | EPA Safer Choice certification unlocks university and corporate campus vending procurement. |
Research Methodology
Bottom-up consumer cohort modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with brand managers at natural care specialists, category buyers at Target and Whole Foods, supply planners at organic cotton converters, and regulatory affairs leads at FDA-registered facilities combined with secondary validation from USDA BioPreferred registry data, EPA Safer Choice certified product lists, ECHA pre-registration filings, and customs trade records for organic cotton fiber imports.
Historical trendline analysis across organic cotton input costs, certification adoption rates, and channel shift patterns informed projection modeling. Segmentation dimensions include product format, customer life stage, distribution channel type, and application intensity. CAGRs derive from fitted growth curves applied to certified product volume trajectories, with working women demographic expansion and subscription commerce penetration serving as key forecast inputs.
Revisions become necessary when ECHA microplastic restrictions formalize, California or New York disclosure laws accelerate, or climate events disrupt Indian and Turkish organic cotton harvests. Forecasts reflect assumptions about regulatory timelines and consumer certification literacy diffusion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Women Intimate Care Products Market
Beauty & Personal Care
Beauty Oils Market
Beauty & Personal Care
Makeup Brushes Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Canada Dermocosmetics Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
UV Nail Gel Lamp Market