
 MRP Software Market | 2026-2036
MRP Software Market Size, Share, and Industry Trends Forecast 2026-2036
MRP Software Market Insights
Subscription-based feature layers is restructuring how MRP vendors monetize core planning logic. Oracle NetSuite leverages its cloud-native architecture to anchor mid-market manufacturers seeking integrated ERP-MRP convergence. Plex specializes in food and beverage compliance workflows, sustaining differentiation through FDA-aligned lot traceability. Katana competes on rapid deployment timelines, occupying the SMB segment with visual production scheduling interfaces.
Material Requirements Planning software automates the calculation of materials, capacity, and scheduling needed to manufacture finished goods, typically operating through bill-of-materials explosion algorithms and time-phased inventory netting against master production schedules. Cloud-based deployments are capturing the fastest expansion as manufacturers retire on-premise servers, while hybrid architectures persist in defense and pharmaceutical settings where air-gapped quality control modules remain mandatory. Inventory Management functionality commands the deepest incumbent investment, though Production Planning modules are generating disproportionate new-logo interest as reshoring initiatives multiply bill-of-materials complexity.
FDA 21 CFR Part 11 and EU GMP Annex 11 shape validation requirements for MRP systems deployed in life sciences manufacturing, forcing vendors to maintain audit trails and electronic signature capabilities. ISO 27001 and SOC 2 Type II certifications have become table stakes for cloud-based providers serving automotive OEM supply chains. Stakeholders must weigh the trade-off between multi-tenant SaaS economics and single-tenant isolation as cyber-insurance underwriters sharpen scrutiny of manufacturing software attack surfaces.
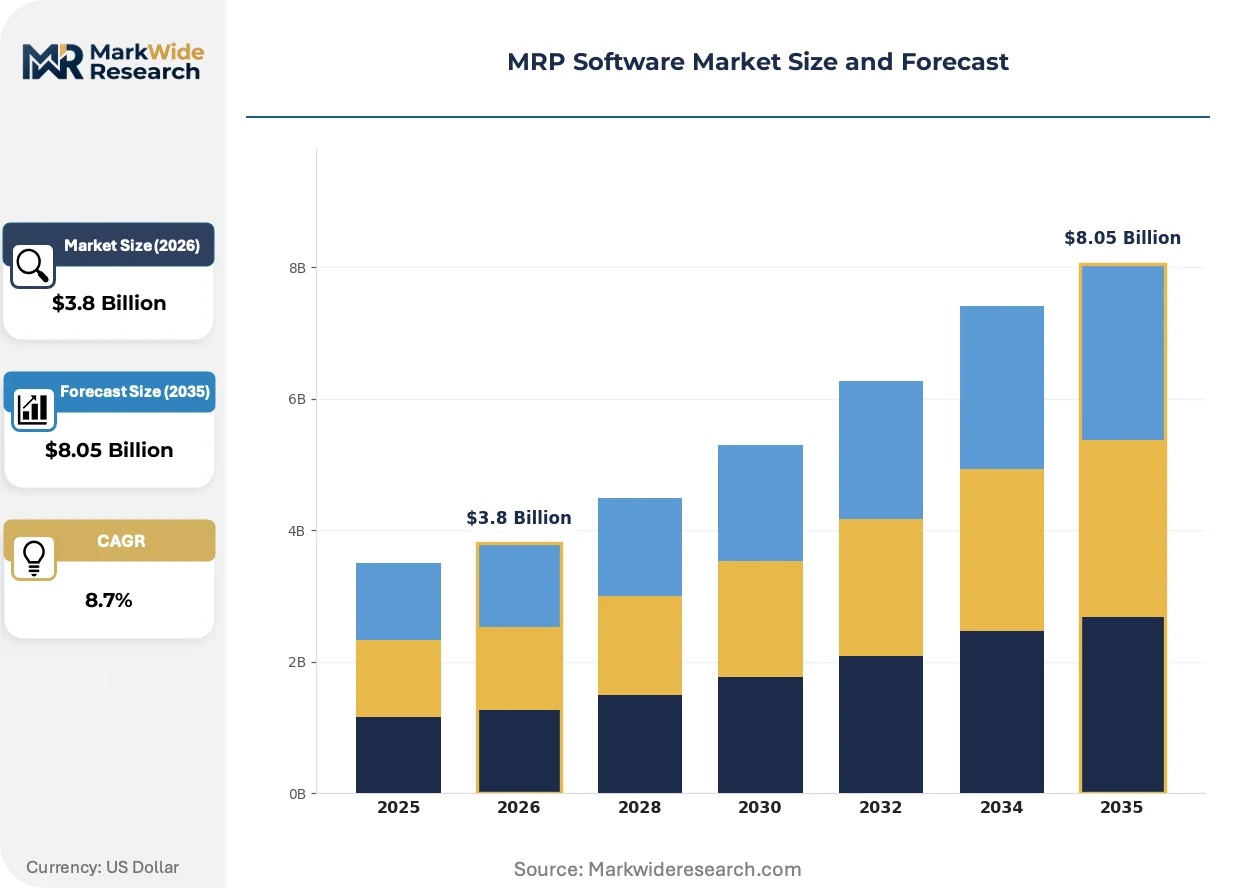
Market Dynamics
Cloud-native MRP architectures are compressing deployment timelines from quarters to weeks, forcing incumbent vendors to restructure delivery models around microservices and API-first integration.
Growth Catalysts
- EU AI Act compliance mandates:Life sciences manufacturers in Germany and France are accelerating validated MRP procurement to meet algorithmic transparency requirements for production planning systems.
- Reshoring-driven BOM complexity:Automotive suppliers in the United States are adopting advanced MRP modules to manage multi-tier supplier networks replacing single-source offshore dependencies.
- FDA 21 CFR Part 11 validation:Pharmaceutical contract manufacturers require electronic signature and audit trail capabilities, expanding addressable market for compliant cloud MRP platforms.
Market Restraints
- Air-gapped infrastructure persistence:Defense and classified manufacturing in the United States mandates isolated quality control modules, blocking pure SaaS adoption.
- Specialized integration labor scarcity:Legacy ERP-MRP bridge development requires scarce SAP-fluent consultants, inflating total cost of ownership.
- Hybrid architecture complexity:Manufacturers maintaining on-premise batch records alongside cloud planning layers face data synchronization failures.
Strategic Opportunities
- Mid-market SMB penetration:Manufacturers with under 500 employees in India and Brazil remain underserved by enterprise-focused MRP suites.
- Digital twin convergence:Integration of MRP with real-time shop floor simulation creates closed-loop planning for high-mix electronics assembly.
- EU Green Deal carbon tracking:Scope 3 emissions reporting requirements position MRP vendors to embed supply chain carbon accounting modules.
Industry Challenges
- Legacy system migration friction:AS/400 and mainframe-dependent manufacturers face data model incompatibility with modern relational MRP databases.
- Validation documentation burden:FDA-aligned computerized systems validation requires 12-18 month implementation timelines for life sciences deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRP Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-premise, Cloud-based, Hybrid, Open-source End User: Manufacturers, Distributors, Retailers, Service Providers Deployment Model: Single-tenant, Multi-tenant, SaaS, Managed Functionality: Inventory Management, Production Planning, Sales Forecasting, Quality Control |
| Companies Covered | Fishbowl, Plex, Oracle NetSuite, Sage X3, Wherefour, Odoo, Katana, Craftybase, MRPeasy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRP Software Market Trends and Innovations
Artificial intelligence is penetrating core planning algorithms, transforming deterministic MRP logic into probabilistic demand sensing that reduces safety stock buffers.
Machine learning-based demand forecasting is overtaking traditional statistical methods in consumer electronics manufacturing. Tier-1 contract manufacturers in Taiwan and South Korea deploy neural networks that ingest point-of-sale data directly. This compression of forecast-to-plan cycles is overtaking monthly S&OP rhythms with continuous replanning capabilities.
EU GMP Annex 11 updates are tightening electronic record integrity requirements for MRP systems in sterile pharmaceutical production. The revised guidance demands immutable audit trails for all planning parameter changes. German and Irish drug substance manufacturers are responding by procuring single-tenant isolated instances rather than multi-tenant SaaS.
Subscription pricing is displacing perpetual license models across mid-market manufacturing. CFOs in industrial equipment and medical device sectors now favor operational expenditure treatment for planning software. This preference shift is most visible in the United States, where private equity-backed manufacturers prioritize EBITDA preservation over capital deployment.
MRP Software Market Segmentation
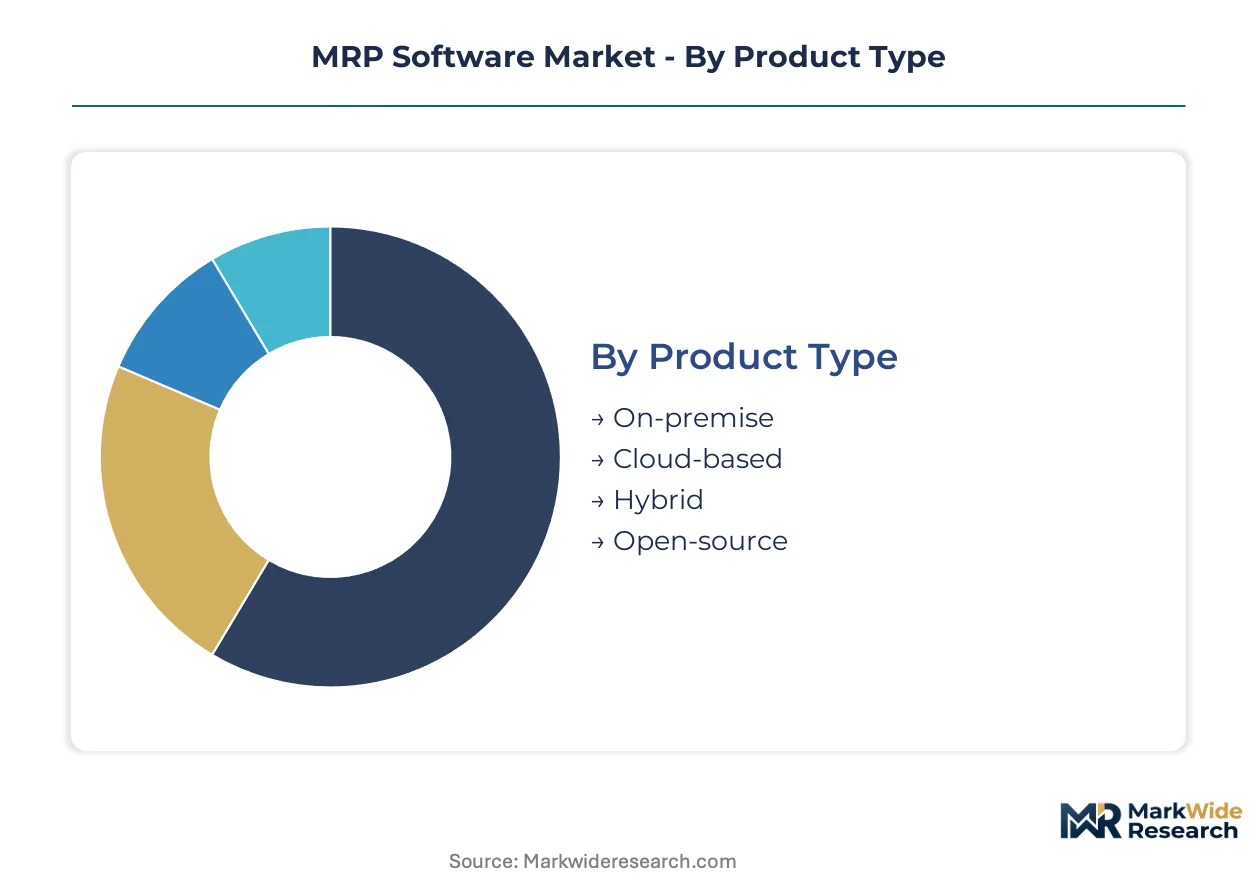
MRP software segmentation reveals divergent capital requirements across deployment modes and user sophistication. Procurement patterns cluster around compliance intensity and IT infrastructure maturity rather than company size alone.
Product Type:
Capital intensity peaks with on-premise installations requiring server hardware, perpetual licensing, and dedicated IT staffing.
- On-premise:Full-stack infrastructure deployed within manufacturer data centers demands substantial upfront hardware investment and ongoing facility costs. Defense contractors in the United States and pharmaceutical manufacturers in Germany maintain these installations to satisfy air-gapped security mandates and FDA 21 CFR Part 11 validation protocols.
- Cloud-based:Subscription economics shift expenditure to operational budgets while eliminating physical infrastructure. Mid-market automotive suppliers in the United States and electronics contract manufacturers in Taiwan are migrating to these deployments to compress implementation timelines and enable remote access for distributed engineering teams.
- Hybrid:Split architectures isolate quality control modules on-premise while running planning logic in cloud environments. Life sciences manufacturers in Ireland and France adopt this model to balance EU GMP Annex 11 compliance with SaaS flexibility.
- Open-source:Community-developed platforms attract cost-constrained manufacturers with internal development capabilities. Industrial equipment producers in India and Brazil leverage these tools to avoid vendor lock-in and customize algorithms for local supply chain conditions.
Most installed capacity flows through on-premise systems. Expansion is steepest in cloud-based deployments.
End User:
Application complexity varies sharply between discrete manufacturing and downstream distribution channels.
- Manufacturers:Bill-of-materials explosion algorithms and capacity planning modules address multi-tier supplier coordination. Discrete manufacturers in automotive and electronics verticals generate the deepest functionality requirements as reshoring initiatives multiply component sourcing complexity.
- Distributors:Inventory positioning and demand aggregation tools dominate procurement criteria. Third-party logistics providers in Germany and the United States deploy these systems to optimize cross-dock operations and vendor-managed inventory programs.
- Retailers:Seasonal demand volatility drives forecast-to-shelf synchronization needs. Consumer electronics retailers in South Korea and Taiwan integrate MRP with point-of-sale data streams to trigger automated replenishment.
- Service Providers:Spare parts planning and reverse logistics capabilities differentiate offerings. Aerospace maintenance contractors in the United States track component life cycles to optimize repair shop scheduling and minimize aircraft downtime.
Manufacturers account for the dominant share of installed seats. Service providers are gaining share fastest as aftermarket revenue models expand.
Deployment Model:
Isolation requirements and data sovereignty concerns fragment procurement across tenancy architectures.
- Single-tenant:Dedicated instances provide complete environmental control for audit and security purposes. Sterile pharmaceutical manufacturers in Germany and Ireland procure these deployments to satisfy EU GMP Annex 11 electronic record integrity requirements.
- Multi-tenant:Shared infrastructure delivers SaaS economics through resource pooling. Mid-market industrial equipment manufacturers in the United States favor this model for EBITDA preservation and rapid scaling.
- SaaS:Browser-accessible platforms eliminate client-side maintenance burdens. Electronics contract manufacturers in Taiwan and South Korea adopt these solutions to enable continuous replanning cycles without on-site IT intervention.
- Managed:Vendor-operated private clouds bridge control and convenience. Automotive OEM supply chains in Germany and the United States deploy these hybrid arrangements to satisfy cyber-insurance underwriter scrutiny while retaining single-tenant isolation.
Multi-tenant SaaS captures the majority of new-logo activity. Single-tenant expansion is strongest in life sciences verticals.
Functionality:
Module investment priority reflects operational pain points rather than software maturity.
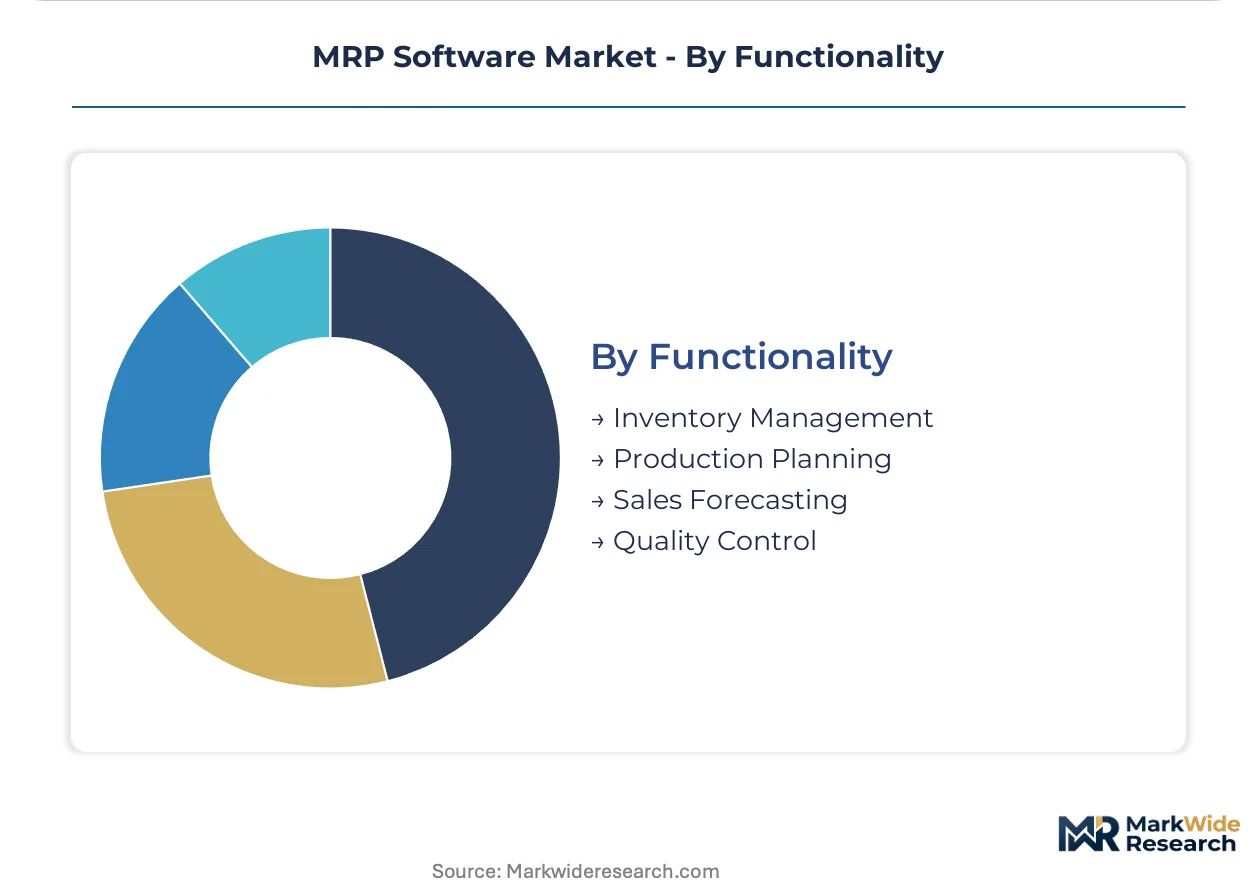
- Inventory Management:Time-phased netting algorithms and safety stock optimization form the historical core of MRP systems. This module commands the deepest incumbent investment across all manufacturing verticals and represents the most mature competitive battleground.
- Production Planning:Capacity leveling and sequencing tools address high-mix assembly complexity. Electronics manufacturers in Taiwan and South Korea are expanding adoption of these modules as neural network-based demand forecasting compresses forecast-to-plan cycles.
- Sales Forecasting:Statistical and machine learning approaches to demand sensing reduce buffer inventory. Consumer goods manufacturers in the United States deploy these capabilities to align production with point-of-sale volatility.
- Quality Control:Lot traceability and non-conformance tracking satisfy regulatory mandates. Food and beverage processors in the United States and pharmaceutical manufacturers in Germany require FDA-aligned electronic signatures and immutable audit trails.
Inventory Management retains the largest installed base. Production Planning is climbing the fastest as reshoring multiplies bill-of-materials complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands deeper compliance-driven procurement than the United States, while China's factory digitization subsidies outpace both in deployment velocity. Regulatory divergence across these three markets fragments vendor standardization efforts.
United States
Reshoring initiatives in automotive and electronics multiply bill-of-materials complexity for domestic suppliers. FDA 21 CFR Part 11 validation requirements shape pharmaceutical contract manufacturer procurement, mandating electronic signatures and immutable audit trails. The Midwest industrial corridor spanning Michigan and Ohio anchors discrete manufacturing MRP adoption as Tier-1 suppliers replace offshore dependencies.
Germany
EU AI Act algorithmic transparency mandates accelerate validated MRP procurement among life sciences manufacturers. EU GMP Annex 11 electronic record integrity requirements tighten further under 2024 guidance updates, pushing sterile drug producers toward single-tenant isolated deployments. The Rhine-Ruhr and Bavarian manufacturing clusters concentrate demand as chemical and automotive OEMs modernize planning infrastructure.
China
Made in China 2025 smart factory subsidies drive cloud-native MRP adoption among electronics contract manufacturers. NMPA computerized systems validation guidelines align with international GMP standards for domestic pharmaceutical producers. The Yangtze River Delta and Pearl River Delta manufacturing belts lead deployment as neural network-based demand forecasting compresses forecast-to-plan cycles.
India
PLI scheme incentives for electronics and automotive manufacturing expand addressable market for mid-market MRP suites. BIS standards for manufacturing software quality create baseline procurement criteria for domestic producers. The Maharashtra and Gujarat industrial corridors attract vendor attention as manufacturers with under 500 employees remain underserved by enterprise-focused platforms.
South Korea
Electronics contract manufacturers deploy machine learning-based demand forecasting to synchronize production with point-of-sale volatility. MFDS GMP requirements for pharmaceutical production software shape validation protocols for domestic drug makers. The Seoul Capital Area and Busan-Ulsan manufacturing clusters anchor adoption as Tier-1 producers enable continuous replanning capabilities.
MRP Software Market Competitive Landscape
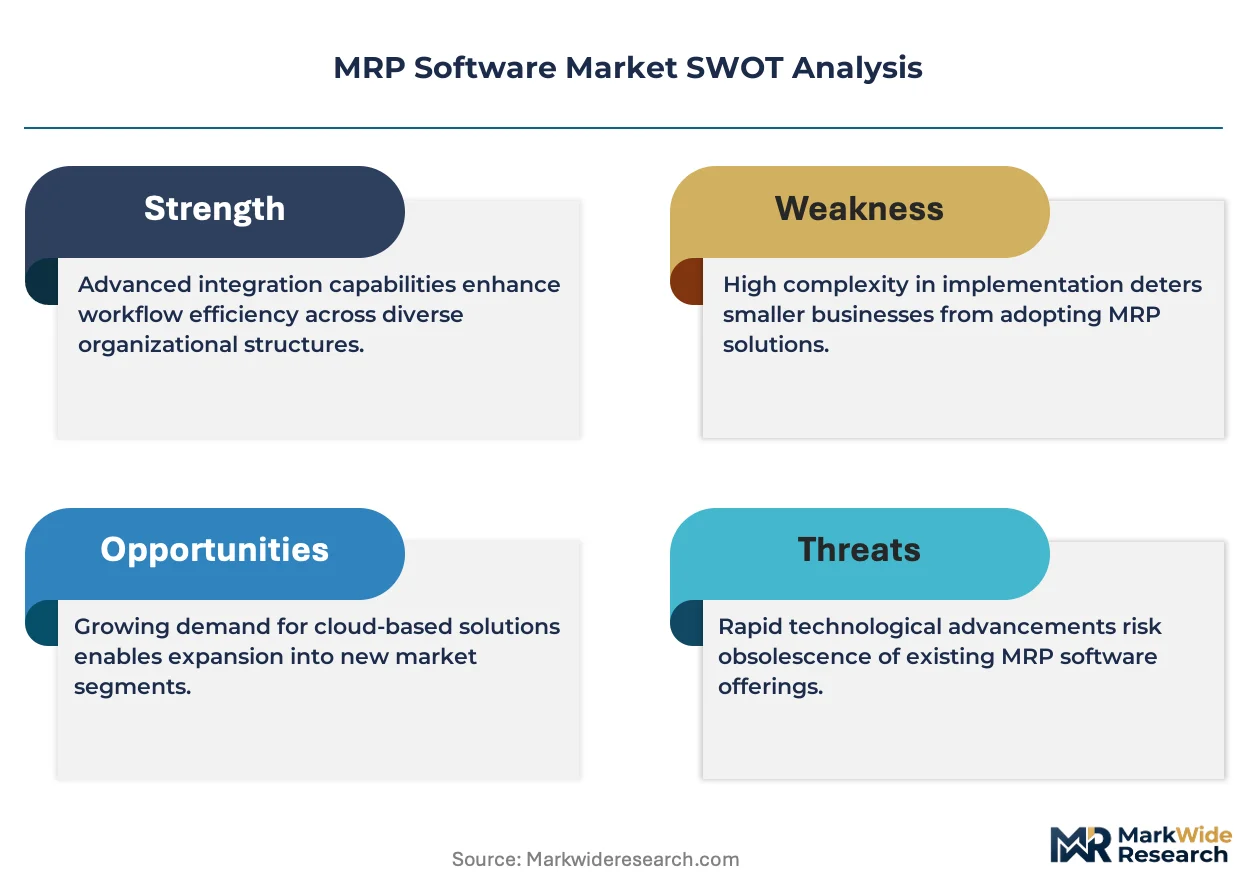
Branded specialists and contract manufacturers split share differently across segments, with cloud-native architectures compressing deployment timelines from quarters to weeks. The vendor base organizes around three tiers: enterprise ERP-integrated suites, vertical-specialist platforms, and rapid-deployment SMB tools. Consolidation pressure concentrates among mid-market players as private equity-backed manufacturers prioritize EBITDA preservation. M&A activity targets API-first microservices capabilities, while geographic expansion focuses on underserved Indian and Brazilian manufacturers.
Within the cloud-native tier, Oracle NetSuite and Katana occupy distinct positions. Oracle NetSuite anchors mid-market manufacturers seeking integrated ERP-MRP convergence through its subscription-based architecture. Katana exemplifies rapid-deployment specialization, competing on visual production scheduling interfaces for SMB segments. Plex represents vertical differentiation, sustaining positioning through FDA-aligned compliance workflows in food and beverage manufacturing.
| Leading Market Players |
|---|
| Fishbowl |
| Plex |
| Oracle NetSuite |
| Sage X3 |
| Wherefour |
| Odoo |
| Katana |
| Craftybase |
| MRPeasy |
| Others |
Pricing and Supply Chain Analysis
Mid-market discrete manufacturers in automotive and electronics verticals anchor procurement volume, concentrating negotiating power around subscription-based SaaS tiers rather than perpetual licensing structures. This buyer archetype's preference for operational expenditure treatment compresses price floors for on-premise alternatives while elevating cloud-native premiums.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for cloud-native MRP modules as contract manufacturers achieve scale economies. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 21 CFR Part 11 validation tier and ISO 27001 certification status. Pricing pressure stems from open-source alternatives gaining traction among cost-constrained Indian and Brazilian producers. SMB manufacturers with under 500 employees exhibit highest price sensitivity, while sterile pharmaceutical producers in Germany and Ireland accept premium single-tenant isolation.
Supply Chain Analysis
FDA and EU GMP Annex 11 certification gating restricts vendor qualification to providers maintaining immutable audit trails and electronic signature capabilities. Software development concentrates in the United States, Germany, and India, with cloud infrastructure resting on hyperscaler data centers in Ireland, Singapore, and Virginia. Supply chain risk centers on single-source vulnerability for SAP-fluent integration consultants bridging legacy ERP-MRP architectures. Distribution runs through direct vendor sales teams for enterprise accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MRP software market represents a late-cycle quality story as FDA and EU AI Act compliance mandates shift procurement toward validated, audit-ready platforms over rapid-deployment alternatives. Demand is concentrating in specifications that embed regulatory documentation rather than pure planning speed.
For Market Incumbents: To counter open-source erosion in cost-sensitive emerging markets, deepen API-first microservices architecture to compress implementation timelines below six weeks. Prioritize backward integration into compliance documentation services, capturing the 12-18 month validation burden as recurring revenue rather than implementation cost. For New Entrants and Emerging Players: Launch via vertical-specialist channel partnerships targeting food and beverage processors in the United States seeking FDA-aligned lot traceability without Plex's enterprise price point. The most penetrable white space sits with Indian and Brazilian manufacturers under 500 employees, where BIS standards create procurement criteria but enterprise suites remain unaffordable. For Investors and Strategic Acquirers: Private equity-backed manufacturing software consolidators are the most active acquirer in this space, seeking API-first microservices capabilities to bolt onto existing ERP portfolios. Target acquisition archetype: vertical-specialist platforms with FDA validation documentation libraries. The signal to watch is EU AI Act enforcement action against non-compliant planning algorithms, which would trigger replacement demand among German and French life sciences manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first microservices architectures enable sub-quarter ERP-MRP convergence for mid-market automotive suppliers. |
| Acquisition of Specialist Firm | Vertical compliance expertise in FDA 21 CFR Part 11 documentation accelerates life sciences market penetration. |
| Geographic Expansion | PLI scheme incentives in India and Brazil expand addressable market for rapid-deployment SMB tools. |
| Strategic Partnership | Hyperscaler alliances in Ireland and Singapore satisfy data sovereignty requirements for EU GMP Annex 11 compliance. |
| Product Launch | Carbon accounting module embedding responds to EU Green Deal Scope 3 emissions reporting mandates. |
Research Methodology
Direct dialogue with MRP vendor product managers, IT procurement officers at Tier 1 automotive suppliers, pharmaceutical validation specialists, and cloud infrastructure architects grounded qualitative assessment. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EU AI Act regulatory texts, SEC filings of publicly traded manufacturing software providers, and hyperscaler capex disclosures. Bottom-up and top-down triangulation cross-checked vendor-reported deployment metrics against end-user procurement patterns.
Bottom-up modeling aggregated segment-level adoption curves across deployment mode, organization size, and vertical compliance intensity. Top-down constraints incorporated macro manufacturing output projections and factory digitization program budgets. CAGRs were derived from fitted adoption curves rather than linear extrapolation, with neural network-based demand forecasting penetration and reshoring-driven bill-of-materials complexity serving as key demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or prolonged SAP consultant scarcity. Model outputs reflect assumptions about cloud migration velocity and regulatory harmonization timelines. A model refresh is warranted upon material change in FDA computerized systems validation guidance or NMPA alignment with international GMP standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Cloud Communication Platform Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Artwork Management Software Market
Software & Services
Automotive Digital Retailing Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Global Trade Promotion Management Software Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Global Quoting Software Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Global Audit Software Market
Software & Services
Harbor and Marina Management Software Market
Software & Services
Global Automation Software Market
Software & Services
Anti-Plagiarism for the Education Sector Market