
 Child Safety Seat Market | 2026-2036
Child Safety Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Child Safety Seat Market Intelligence
A capital-intensity divergence between premium manufacturers and mass-market producers is rotating competitive dynamics across the child safety seat landscape. Britax leverages in-house crash-test facilities and European engineering heritage to command premium positioning. Graco sustains broad retail penetration through Walmart and Target shelf dominance in North America. Evenflo competes aggressively on value-tier pricing while maintaining FMVSS certification compliance.
A child safety seat is a purpose-built restraint system engineered from energy-absorbing foams, steel-reinforced frames, and flame-retardant textiles, designed to protect occupants from collision forces through controlled deceleration and distributed load management. Convertible seats occupy the largest revenue pool by spanning multiple usage stages from rear-facing infancy to forward-facing toddler configurations. ISOFIX-certified products are capturing disproportionate growth as latch-based installation reduces misuse rates versus seatbelt routing. Booster seats face margin compression in mature Western markets where birth rates stagnate.
NHTSA enforces FMVSS 213 standards that mandate dynamic sled testing and labeling protocols, while ECE R44 regulations across European Economic Area countries prescribe differing age and weight classification schemes that fragment product development requirements. The EU's General Safety Regulation is tightening side-impact test criteria, forcing redesign cycles for manufacturers serving dual certification markets. Stakeholders must monitor divergence between NHTSA's proposed updates and ECE R129 phase-in timelines to avoid stranded inventory in transatlantic distribution channels.
Market Dynamics
ISOFIX anchoring systems are compressing installation-error rates while fragmenting certification requirements across NHTSA and ECE jurisdictions, forcing manufacturers to maintain parallel testing protocols for transatlantic distribution.
Growth Catalysts
- ECE R129 Phase-In:The EU's i-Size regulation mandates rear-facing seating until fifteen months, extending product replacement cycles and driving premium convertible seat demand across Germany, France, and Italy.
- Side-Impact Test Mandates:NHTSA's proposed updates to FMVSS 213 are compelling manufacturers to integrate energy-absorbing foam architectures that exceed baseline federal requirements.
- Urban Birth Rate Concentration:Megacity clusters in Texas, California, and New York generate disproportionate unit volume through dense pediatric populations and stringent state-level enforcement.
Market Restraints
- Steel and Polymer Input Volatility:Flame-retardant textile feedstocks and high-density polyethylene resins face petrochemical price swings that compress margin predictability for mass-market producers.
- Dual-Certification Inventory Risk:Divergent NHTSA and ECE labeling protocols strand finished goods when regulatory timelines misalign, particularly affecting distribution through Rotterdam and Charleston ports.
- Extended Product Lifecycles:Convertible seat durability spanning four to six years depresses replacement frequency compared with infant-only systems.
Strategic Opportunities
- Subscription-Based Rotation Services:Direct-to-consumer platforms offering staged seat transitions as children age are capturing urban parents seeking convenience over retail purchase.
- Telematics Integration:Sensor-equipped seats transmitting occupancy and installation data to fleet operators are penetrating ride-share and corporate shuttle segments.
- India BIS Certification Gap:Absence of mandatory national standards creates first-mover advantage for ISOFIX-certified imports targeting metropolitan Delhi and Mumbai households.
Industry Challenges
- Crash-Test Engineer Scarcity:Specialized biomechanical expertise for dynamic sled testing concentrates among legacy suppliers, constraining new entrant R&D velocity.
- Dual-Jurisdiction Compliance Timelines:Simultaneous NHTSA and ECE homologation cycles extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Child Safety Seat Market |
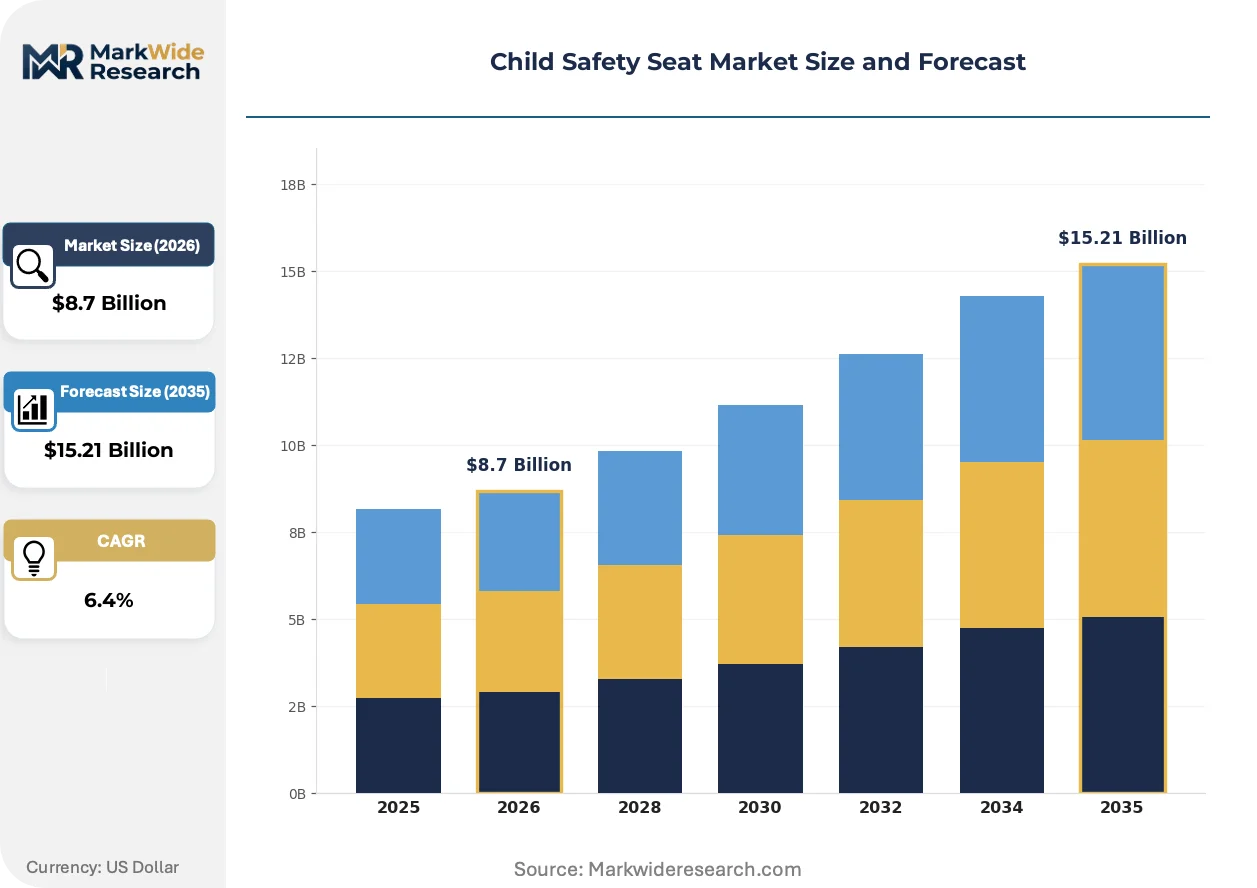
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infant Seat, Convertible Seat, Booster Seat, All-in-One Seat Deployment Type: On-premise, Online Retail, In-store, Direct Sales Usage Stage: Newborn, Toddler, Preschooler, School Age Certification: FMVSS, ECE R44, ISOFIX, Others |
| Companies Covered | Britax, Chicco, Graco, Evenflo, Maxi-Cosi, Cybex, Clek, Cosco, Diono, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Child Safety Seat Market Strategic Shifts & Innovations
Smart sensing architectures and modular load-management systems are redefining how restraint systems communicate with vehicle platforms and caregivers.
Sensor-integrated occupancy detection is displacing passive mechanical indicators in premium segments. Forward-facing toddler configurations now incorporate capacitive sensing pads that verify harness tension and chest-clip engagement. BMW and Mercedes-Benz factory-installed bases are standardizing these interfaces, compressing aftermarket attachment-system margins.
ECE R129's side-impact pole-test protocol is forcing structural redesigns across European supply chains. Manufacturers serving dual-certification markets must validate wing structures against both ECE intrusion metrics and NHTSA sled-deceleration profiles. Convertible seat lines targeting Germany and the Netherlands face the steepest engineering-cost escalations.
Urban millennial parents are consolidating purchase decisions through subscription bundling with stroller and carrier ecosystems. Direct-to-consumer brands bypassing Target and Walmart shelf fees are capturing coastal metropolitan demand. Brooklyn, Seattle, and Austin zip codes show the highest concentration of online-first safety seat transactions.
Child Safety Seat Market Segmentation
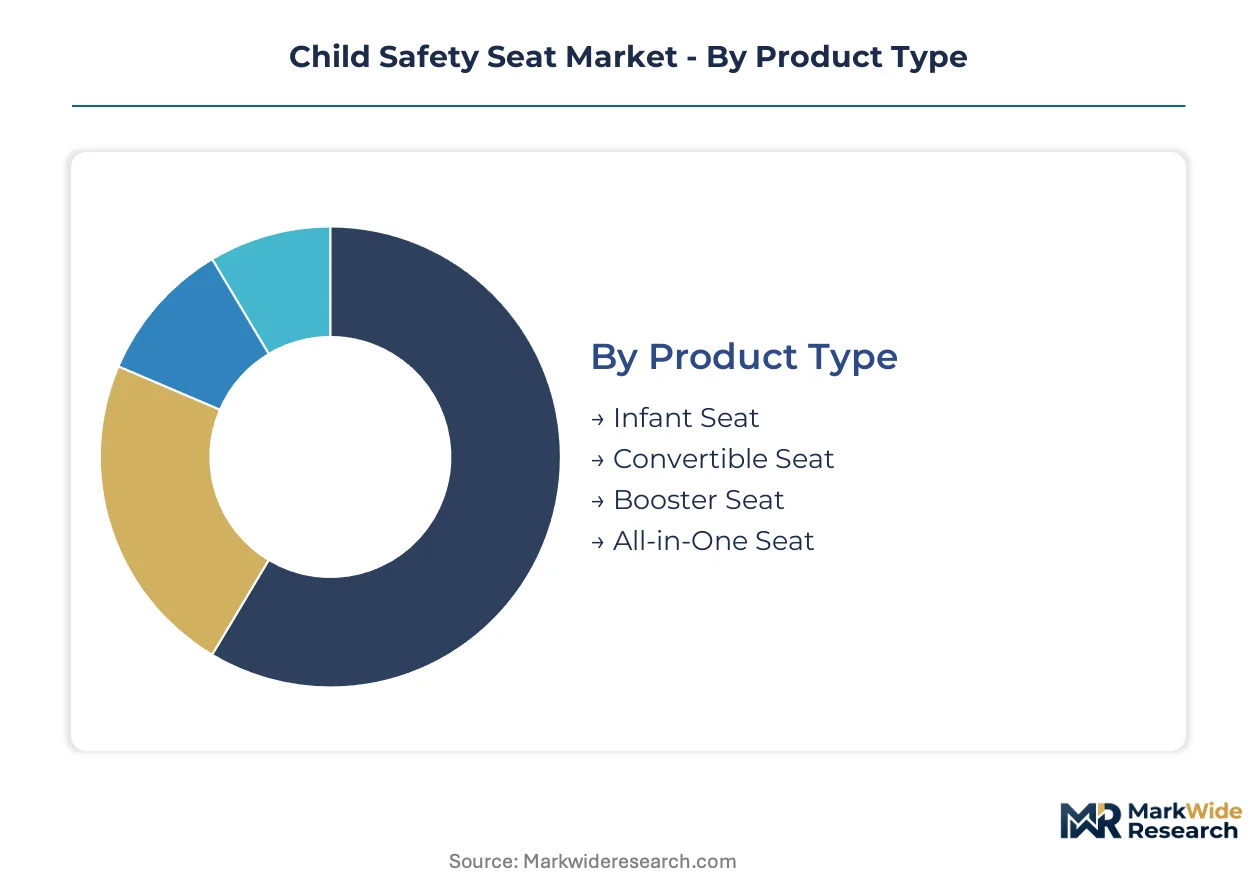
Product configuration and channel strategy diverge sharply across child safety seat categories. Certification requirements and usage-stage transitions create distinct margin profiles that reshape how manufacturers allocate R&D and distribution resources.
Product Type:
Convertible seats and infant-only systems flow through divergent retail channels, with premium configurations concentrating in specialty boutiques while mass-market SKUs dominate big-box shelf space.
- Convertible Seat:Dual-mode architecture spans rear-facing infancy through forward-facing toddler stages using steel-reinforced frames and energy-absorbing foam cores. Demand clusters in Texas, California, and New York metropolitan areas where state laws mandate extended rear-facing use and parents prioritize single-purchase longevity over staged replacements.
- Infant Seat:Rear-facing-only designs with detachable carrier bases dominate hospital discharge bundles and baby registry purchases. Volume concentrates through Target and Walmart in suburban zip codes with high birth rates, though direct-to-consumer brands are capturing coastal urban demand via subscription rotation services.
- Booster Seat:Backless and high-back configurations for school-age children face margin compression in mature Western markets.
- All-in-One Seat:Extended-lifecycle designs spanning newborn through booster stages appeal to value-conscious households seeking single-purchase solutions.
Convertible seats dominate installed base. All-in-One configurations are where expansion concentrates.
Deployment Type:
Channel economics vary by customer acquisition cost and inventory velocity, with digital-native brands exploiting lower overhead to undercut traditional retail markups.
- Online Retail:Direct-to-consumer platforms and Amazon marketplace listings capture urban millennial parents seeking ISOFIX-certified inventory with video installation tutorials. Brooklyn, Seattle, and Austin zip codes show the highest transaction density, bypassing shelf fees that inflate brick-and-mortor pricing.
- In-store:Physical retail through Buy Buy Baby, Target, and Walmart remains critical for tactile evaluation of harness systems and fabric quality. Rural and suburban parents rely on in-person fitting assistance, particularly for first-time purchases where installation uncertainty runs highest.
- On-premise:Fleet and institutional procurement for daycare centers, hospitals, and ride-share operators.
- Direct Sales:Manufacturer-owned channels and subscription rotation services.
In-store captures the highest absolute unit volume. Online retail is climbing the fastest.
Usage Stage:
Replacement frequency and price elasticity shift dramatically as children age, with newborn-stage purchases showing the lowest price sensitivity and school-age segments exhibiting commoditization pressure.
- Newborn:Rear-facing-only restraint systems for infants up to twelve months represent the premium pricing tier, with parents prioritizing NHTSA crash-test ratings and hospital discharge compatibility over cost. First-time parent anxiety drives attachment to established brands with visible safety marketing.
- Toddler:Forward-facing transition seats for ages one through three face the steepest competitive intensity as convertible configurations extend usable lifespan and compress replacement cycles.
- Preschooler:Harness-to-booster combination seats for ages three through five.
- School Age:Belt-positioning boosters for children four feet nine inches and taller.
Newborn commands premium pricing power. Toddler is where margin pressure intensifies most acutely.
Certification:
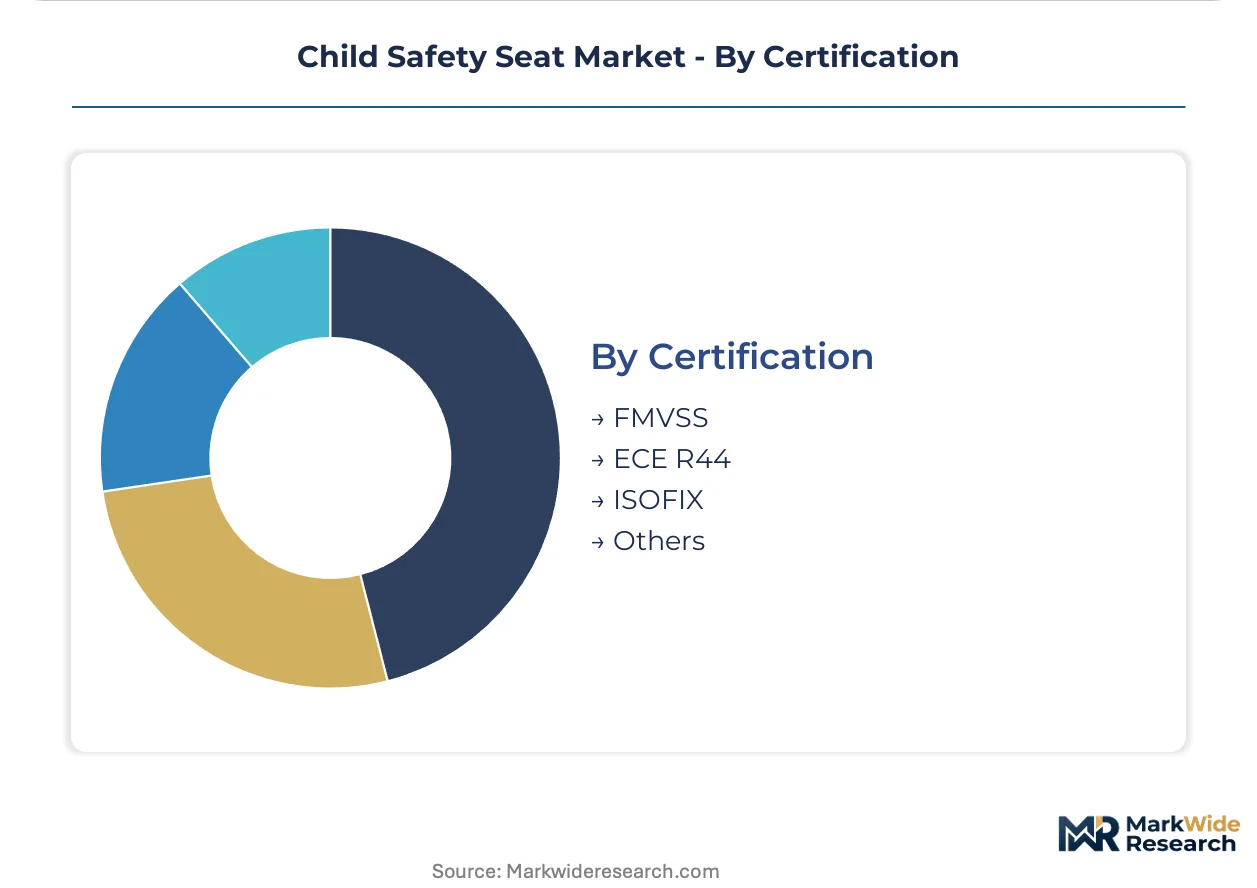
Regulatory divergence between NHTSA and ECE jurisdictions fragments product development, with dual-certified SKUs carrying fourteen-month longer launch timelines and elevated testing overhead.
- ISOFIX:Latch-based anchoring systems reduce installation-error rates versus seatbelt routing and command disproportionate growth in premium segments. ECE R129 mandates in the EU and voluntary adoption in US coastal states are accelerating ISOFIX penetration through factory-installed vehicle bases from BMW and Mercedes-Benz.
- FMVSS:NHTSA's Federal Motor Vehicle Safety Standard 213 governs dynamic sled testing and labeling for US distribution, with proposed side-impact updates forcing foam architecture redesigns across domestic supply chains.
- ECE R44:European weight and age classification schemes differ from NHTSA protocols, stranding inventory when regulatory timelines misalign at Rotterdam and Charleston ports.
- Others:Emerging national standards including India's voluntary BIS certification and China's GB standards.
FMVSS governs the largest addressable market by geography. ISOFIX is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Parents in Germany and the Netherlands absorb premium pricing for extended rear-facing configurations, while Indian metropolitan buyers prioritize ISOFIX-certified imports at accessible price points. State-level enforcement intensity in the United States creates additional demand segmentation between coastal and interior markets.
United States
Texas, California, and New York metropolitan clusters generate disproportionate unit volume through dense pediatric populations and graduated state-level seat transition laws. NHTSA's FMVSS 213 governs dynamic sled testing and labeling protocols, with proposed side-impact updates forcing foam architecture redesigns. Brooklyn, Seattle, and Austin zip codes show the highest concentration of online-first safety seat transactions as direct-to-consumer brands bypass traditional retail markups.
Germany
ECE R129 i-Size mandates extend rear-facing requirements to fifteen months, driving premium convertible seat demand across German households. The EU's General Safety Regulation tightens side-impact test criteria, forcing redesign cycles for manufacturers serving dual certification markets. Stuttgart and Munich industrial corridors concentrate engineering talent for advanced load-management systems and ISOFIX base development.
China
GB standards and voluntary certification schemes fragment quality tiers as metropolitan Shanghai and Beijing parents gravitate toward imported ISOFIX-certified products. The country's national automotive safety regulator maintains distinct testing protocols from NHTSA and ECE systems. Yangtze River Delta manufacturing clusters supply domestic brands while premium imports penetrate coastal tier-one cities through cross-border e-commerce channels.
India
Absence of mandatory BIS certification for child restraint systems creates first-mover advantage for ISOFIX-certified imports targeting Delhi and Mumbai households. The Bureau of Indian Standards maintains voluntary guidelines that lag ECE R129 stringency. Maharashtra and Karnataka urban centers show emerging demand concentration as vehicle ownership expands among nuclear families with dual-income earners.
France
ANSM and national consumer safety agencies enforce ECE R44 and R129 protocols with particular attention to side-impact pole-test validation. Paris and Lyon metropolitan areas concentrate retail distribution for premium European brands with extended rear-facing configurations. French regulatory timelines occasionally misalign with ECE phase-in schedules, creating inventory management complexity for transnational suppliers.
Child Safety Seat Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the child safety seat landscape. Premium manufacturers maintain in-house crash-test facilities and European engineering heritage, while mass-market producers sustain broad retail penetration through big-box shelf dominance. Three archetypes define competitive positioning: vertically integrated specialists with captive testing infrastructure, contract manufacturers serving private-label retailers, and direct-to-consumer digital natives exploiting subscription bundling. Consolidation pressure operates through M&A activity targeting certification expertise and geographic expansion into underpenetrated Asian markets.
Among legacy European engineering houses, Britax and Maxi-Cosi exemplify premium-tier positioning through heritage certification depth and in-house dynamic sled capabilities. Graco occupies a position within the mass-market archetype, leveraging North American retail shelf dominance and value-tier pricing power. Clek represents the specialist segment, concentrating engineering resources on narrow product configurations rather than portfolio breadth. These three anchors illustrate how competitive advantage fragments across certification intensity, channel control, and manufacturing scale rather than concentrating in unified market leaders.
| Leading Market Players |
|---|
| Britax |
| Chicco |
| Graco |
| Evenflo |
| Maxi-Cosi |
| Cybex |
| Clek |
| Cosco |
| Diono |
| Others |
Cost & Logistics Intelligence
Capacity utilization at dedicated child safety seat manufacturing facilities in China, Mexico, and Poland shapes both supply concentration and price floors across product tiers. High-mix, low-volume convertible seat production favors integrated manufacturers with captive testing infrastructure, while mass-market infant systems compete on polymer input costs and retail shelf fees.
Pricing Analysis
After-sales revenue from replacement covers, harness systems, and ISOFIX base accessories drives lifetime value per customer relationship. Three-tier pricing structure across premium, standard, and economy levels separates Britax and Maxi-Cosi engineering-intensive offerings from Graco's retail-optimized SKUs and Cosco's value-tier positioning. Price differentiation rests on ECE R129 i-Size certification depth and in-house crash-test facility ownership. Cost compression in the booster seat category intensifies because birth rate stagnation in Western markets erodes replacement frequency. Fleet procurement officers at ride-share operators show lowest price sensitivity, while suburban parents purchasing first infant systems through Target and Walmart demonstrate highest elasticity.
Supply Chain Analysis
Inventory lead times for flame-retardant textile feedstocks and high-density polyethylene resins extend to fourteen weeks when petrochemical capacity tightens. Manufacturing concentrates in China, Mexico, and Poland, with Yangtze River Delta clusters supplying steel-reinforced frame components and Guanajuato facilities serving North American retail replenishment. Raw material dependencies draw from Saudi petrochemical complexes for polymer resins, Belgian textile mills for flame-retardant fabrics, and German engineering houses for ISOFIX latch mechanisms. Single-source vulnerability concentrates in specialized energy-absorbing foam formulations from two European chemical suppliers. Distribution runs through Rotterdam and Charleston port hubs into big-box retail distribution centers, with direct-to-consumer brands bypassing this layer through Shenzhen and Austin fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based rotation services and telematics-enabled fleet contracts are expanding faster than hardware unit sales, reframing child safety seat economics around recurring revenue attachment. Manufacturers capturing this service layer extract superior lifetime value from urban millennial households and corporate mobility managers.
For Market Incumbents: Secure certification expertise in dual-jurisdiction homologation to defend against direct-to-consumer entrants exploiting NHTSA-ECE timeline gaps. Lock in exclusive ISOFIX base supply agreements with BMW and Mercedes-Benz factory-install programs. Channel control through Buy Buy Baby and Target shelf dominance remains critical, though subscription rotation services threaten retail margin capture. For New Entrants and Emerging Players: Installation support services represent the most exploitable service-layer gap, as incumbent technical assistance concentrates at retail rather than digital touchpoints. Target metropolitan Indian households in Delhi and Mumbai where BIS certification absence permits ISOFIX-certified import penetration. Pursue telematics integration partnerships with ride-share fleet operators seeking occupancy verification and liability reduction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive crash-test infrastructure over contract manufacturers exposed to retail pricing volatility. Long-term viability across the analysis window hinges on regulatory divergence between NHTSA and ECE jurisdictions sustaining dual-certification complexity. Acquisition candidates should demonstrate established ECE R129 i-Size validation pipelines and European engineering heritage. The signal to watch is NHTSA's proposed FMVSS 213 side-impact update timeline, which would force redesign investments and consolidate advantage among pre-positioned suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ISOFIX Base Standardization | Factory-installed vehicle anchor systems from BMW and Mercedes-Benz compress aftermarket attachment margins and lock in premium positioning. |
| Subscription Rotation Service Launch | Direct-to-consumer platforms bypass Target and Walmart shelf fees while capturing Brooklyn, Seattle, and Austin urban demand concentration. |
| ECE R129 i-Size Certification Investment | Extended rear-facing mandates across Germany, France, and Italy drive premium convertible seat replacement cycles and engineering cost barriers. |
| Telematics Integration Partnership | Sensor-equipped occupancy detection penetrates ride-share and corporate shuttle segments with recurring data-service revenue. |
| India Market Entry via BIS Gap | Absence of mandatory national standards creates first-mover advantage for ISOFIX-certified imports targeting Delhi and Mumbai nuclear families. |
Research Approach
Desk research of NHTSA FMVSS 213 regulatory filings, ECE R44 and R129 homologation databases, and customs trade data preceded structured interviews with child safety seat product managers, automotive OEM procurement officers, and pediatric trauma center safety coordinators. Primary fieldwork encompassed crash-test facility engineers at legacy European suppliers and big-box retail category buyers. Secondary validation drew from hospital discharge bundle documentation, state-level child passenger safety law compendiums, and vehicle registration databases. Bottom-up unit volume estimates triangulated against top-down spending projections from household consumption surveys.
Variance decomposition across product type, certification tier, distribution channel, and metropolitan demographic cluster anchored the analytical framework. Segmentation dimensions modeled include convertible versus infant-only versus booster configurations, ISOFIX versus seatbelt anchoring systems, online versus in-store channel economics, and Texas-California-New York versus German versus Indian metropolitan demand patterns. CAGRs were derived from regression-based trajectory fitting against regulatory phase-in schedules and birth rate projections. Industry-specific forecast inputs incorporated ECE R129 i-Size mandate compliance timelines and NHTSA proposed rulemaking commentary.
Underlying assumptions cover stable petrochemical feedstock availability, gradual ISOFIX vehicle fleet penetration, and sustained state-level enforcement intensity in US coastal markets, with deviation risk concentrated in NHTSA-ECE regulatory timeline misalignment and steel or polymer input price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Road Safety Market
Personal Safety
Global Fall Protection Market
Personal Safety
Life Jacket Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Global Self Defense Products Market
Personal Safety
Concealable Vest Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Smart Home Safety Market
Personal Safety
Rearward Facing Type Child Safety Seats Market
Personal Safety
Pepper Sprays Market
Personal Safety
Smart Personal Safety and Security Device Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Pedestrian Protection Airbag Market
Personal Safety
Personal Safety Alarms Market