
 Global Perfluorocarbons Market | 2026-2036
Global Perfluorocarbons Market Size, Share, and Industry Trends Forecast 2026-2036
Global Perfluorocarbons Market Foresight
Asset-light leasing models for fluorochemical processing equipment is reconfiguring capital barriers for mid-tier entrants seeking plasma etching gas supply contracts. Solvay S.A. leverages its integrated fluorine chemistry platform to sustain long-term supply agreements with semiconductor fabs. Daikin Industries, Ltd. anchors its position through captive production of fluoropolymer precursors in Japan. AGC Inc. competes via specialized purification systems that meet sub-ppt contamination thresholds for EUV lithography processes.
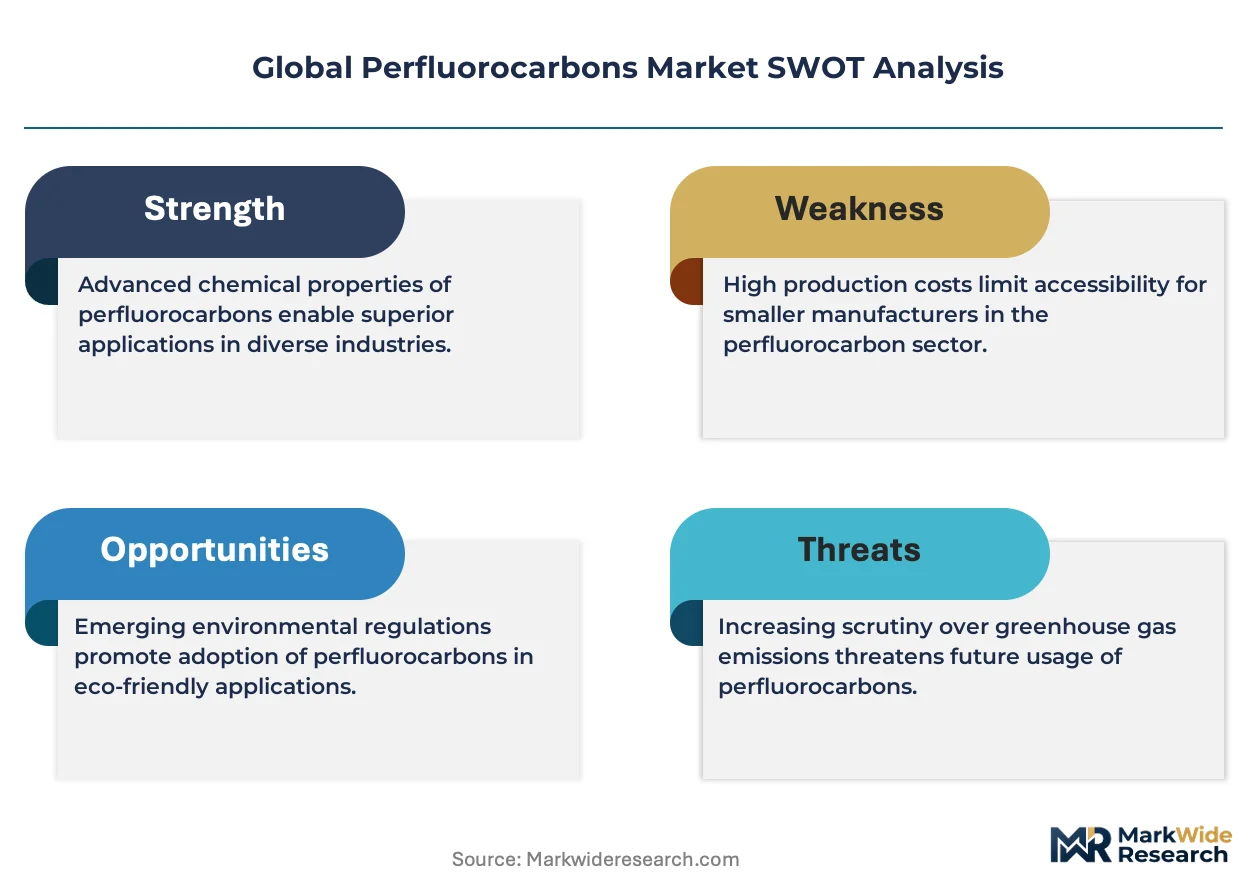
Perfluorocarbons are fully fluorinated aliphatic compounds containing only carbon and fluorine atoms, synthesized through electrochemical fluorination or cobalt trifluoride fluorination of hydrocarbon feedstocks, valued for their chemical inertness, dielectric stability, and extremely low toxicity in precision industrial environments. Plasma etching applications dominate value capture due to irreplaceable roles in reactive ion etching for sub-7nm semiconductor architectures. Medical applications, particularly perfluorodecalin in liquid ventilation and ophthalmic surgery, represent the fastest-growing segment as regulatory pathways for oxygen therapeutics mature. Refrigeration applications face structural compression from F-Gas phasedown schedules in Europe and corresponding state-level mandates in California and Washington.
The EPA enforces production quotas and use restrictions under the AIM Act, while the European Commission implements F-Gas Regulation phasedown targets that directly limit perfluorocarbon volumes in refrigeration and insulating foam sectors. China's Ministry of Ecology and Environment classifies certain perfluorocarbons as controlled ozone-depleting substances, requiring import licenses and consumption permits that shape regional supply availability. Stakeholders must monitor divergence between EPA allowance trading prices and EU quota auction mechanisms, as this spread will determine where incremental production capacity receives financing approval.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are driving structural demand for perfluorocarbon-based etching gases as advanced node production scales toward sub-3nm architectures, while EPA and EU F-Gas phasedown mandates simultaneously compress refrigerant applications and redirect capital toward gas recovery systems.
Growth Catalysts
- Advanced Node Semiconductor Production:Foundries in Hsinchu and Pyeongtaek are expanding plasma etching capacity for 2nm and 1.4nm process nodes, creating irreplaceable demand for high-purity perfluorocarbon feedstocks in reactive ion etching chambers.
- AIM Act Quota Trading:The EPA's allowance trading mechanism for hydrofluorocarbon phasedowns is indirectly elevating perfluorocarbon valuations in semiconductor applications exempt from production caps.
- Liquid Ventilation Therapeutics:Regulatory pathways for oxygen therapeutics are maturing in Japan and the European Union, accelerating perfluorodecalin adoption in ophthalmic surgery and liquid ventilation protocols.
Market Restraints
- Fluorite Feedstock Concentration:Acid-grade fluorite mining concentrates in China and Mexico, exposing electrochemical fluorination supply chains to export licensing volatility and geopolitical friction.
- F-Gas Phasedown Compression:The EU F-Gas Regulation's stepped reduction quotas directly limit perfluorocarbon volumes in refrigeration and insulating foam sectors, eliminating historical demand anchors.
- Alternative Etching Chemistry:Fluorine-free plasma chemistries using nitrogen trifluoride and remote plasma sources are penetrating mature node semiconductor manufacturing, threatening perfluorocarbon incumbency at trailing-edge fabs.
Strategic Opportunities
- India Semiconductor Mission:The country's PLI scheme for semiconductor fabrication is attracting gas supply infrastructure investment around Gujarat and Karnataka, creating first-mover positioning for etching gas distributors.
- EU Critical Raw Materials Act:Strategic stockpiling mandates for fluorochemical precursors are generating offtake agreements for European purification and blending facilities serving domestic fab projects.
- EUV Resist Underlayer Applications:Perfluoropolyether formulations are migrating into antireflective coatings for extreme ultraviolet lithography, opening adjacent chemical demand streams beyond etching gases.
Industry Challenges
- Sub-ppt Purification Expertise:Semiconductor fabs now require contamination thresholds below parts-per-trillion for metal impurities, constraining qualified supplier pools to facilities with molecular distillation and cryogenic separation capabilities.
- Cylinder Fleet Asset Intensity:High-purity gas distribution requires dedicated stainless-steel cylinder networks with electropolished surfaces, forcing capital deployment into container logistics before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Perfluorocarbons Market |
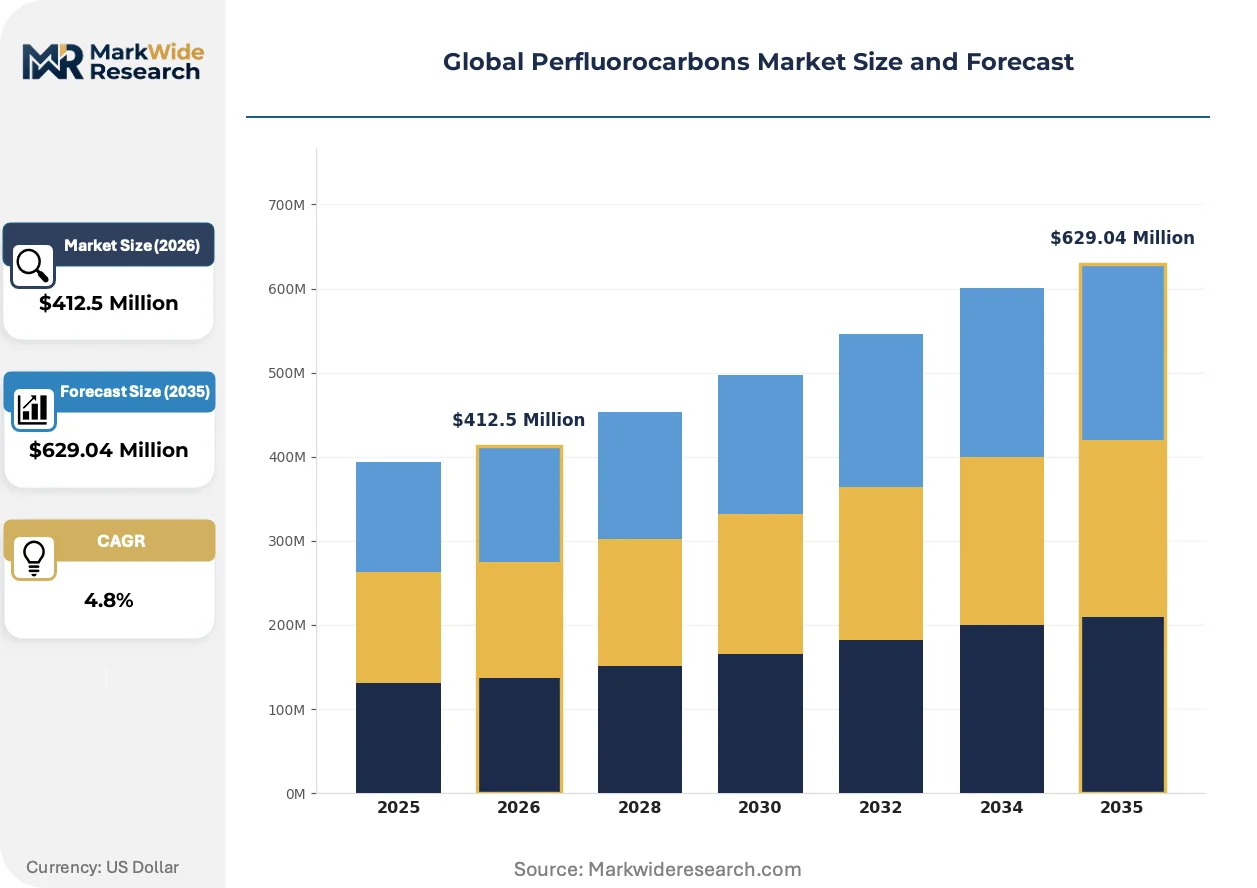
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Perfluoropropane, Perfluorobutane, Perfluorohexane, Perfluorodecalin Application: Refrigeration, Plasma Etching, Medical Applications, Electronics Manufacturing End User: Aerospace, Automotive, Electronics, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Sales, Agents |
| Companies Covered | 3M Company, Solvay S.A., The Chemours Company, Daikin Industries, Ltd., AGC Inc., Arkema Group, Fujian Yongjing Technology Co., Ltd., F2 Chemicals Ltd, Changshu 3F Zhonghao New Chemical Materials Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Perfluorocarbons Market Shifts & Advancements
Perfluorocarbon applications are bifurcating between precision semiconductor manufacturing demanding ever-higher purity grades and medical oxygen therapeutics requiring novel formulation stability, while regulatory phasedowns in climate-sensitive sectors force portfolio rebalancing.
Plasma etching chemistry is migrating from traditional perfluorocarbon blends toward gas-recovery-integrated closed-loop systems. Taiwan Semiconductor Manufacturing and Samsung Foundry are deploying point-of-use abatement and recycling infrastructure at new fabrication facilities. This technology shift is compressing virgin gas consumption intensity per wafer while sustaining absolute volume growth through node complexity multiplication.
The EU F-Gas Regulation's 2024-2030 steppedown schedule is forcing refrigerant manufacturers toward lower-GWP hydrofluoroolefin and natural refrigerant alternatives. Industrial gas distributors are redirecting perfluorocarbon inventory toward semiconductor and medical channels exempt from quota restrictions. German and French chemical processors are investing in fluorine recovery pyrolysis units to maintain European production rights under the regulation's reclamation credit mechanisms.
Long-term supply contracting is displacing spot market purchasing among advanced semiconductor foundries. Buyers in South Korea and Taiwan are negotiating ten-year offtake agreements with fixed purity escalation clauses and dedicated cylinder fleet provisions. This procurement consolidation is visible most acutely in Hsinchu Science Park, where foundries are vertically integrating into gas distribution through joint ventures with Japanese chemical houses.
Global Perfluorocarbons Market Segmentation
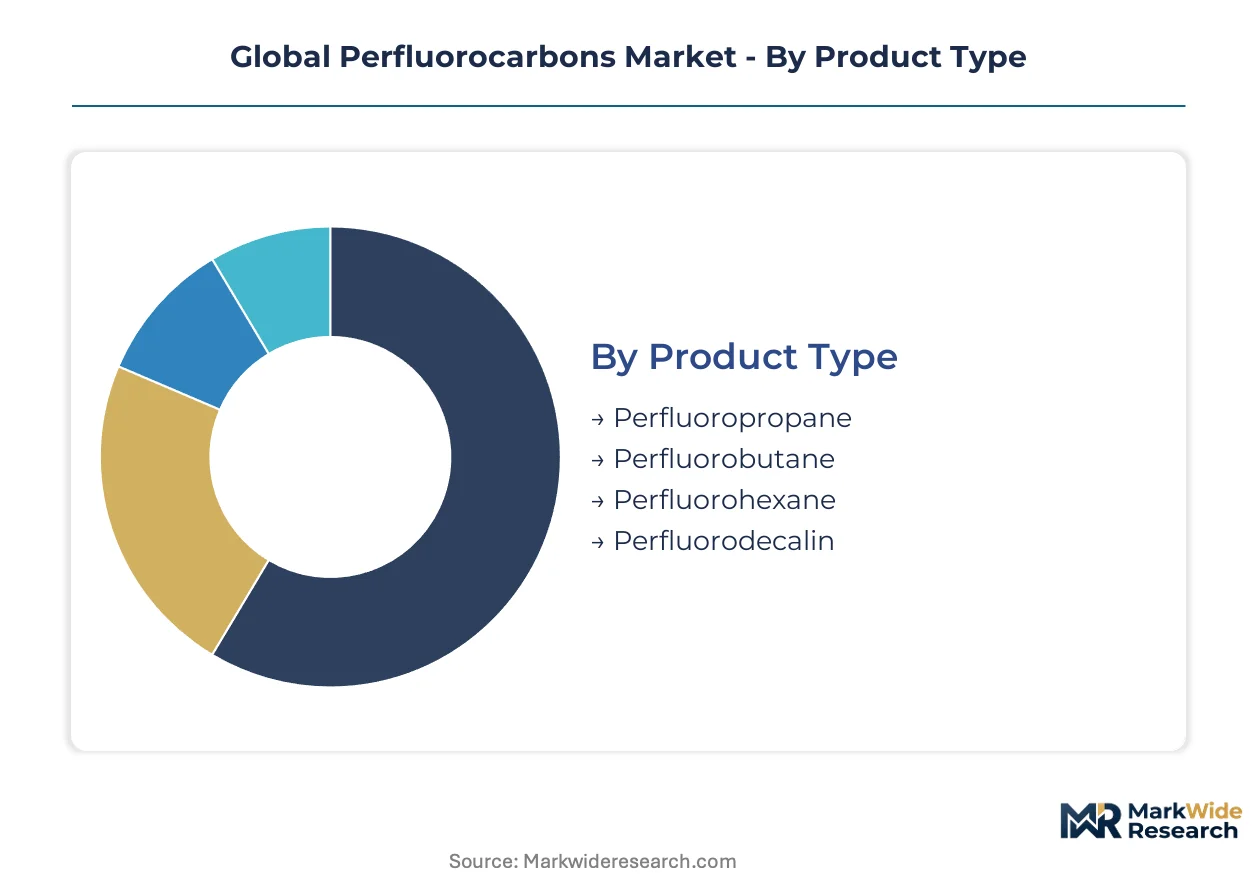
Perfluorocarbon supply chains require differentiated service intensity across product grades, with semiconductor-grade specifications demanding dedicated cylinder fleets and on-site technical support while industrial grades operate through conventional logistics. Segmentation reveals how purity thresholds, regulatory exposure, and end-use criticality reshape procurement patterns and margin structures across the value chain.
Product Type:
After-sales service intensity escalates dramatically with molecular weight and purity grade, as heavier perfluorocarbons for medical oxygen therapeutics require stability monitoring and cold-chain custody documentation absent from industrial refrigerant applications.
- Perfluoropropane:A three-carbon fully fluorinated alkane with exceptional dielectric strength and thermal stability. Semiconductor foundries in Taiwan specify this compound for dielectric gap-fill processes in 3nm node production, where batch consistency directly impacts wafer yield. Demand concentrates in Hsinchu Science Park as TSMC expands advanced packaging capacity.
- Perfluorobutane:Four-carbon perfluorocarbon valued for liquid ventilation applications and ophthalmic surgery due to high oxygen solubility and rapid clearance from pulmonary tissue. Regulatory pathways for oxygen therapeutics in Japan and the European Union are accelerating perfluorodecalin adoption, though perfluorobutane retains niche positioning in diagnostic microbubble formulations.
- Perfluorohexane:Six-carbon chain compound serving industrial heat transfer and specialized solvent applications where chemical inertness outweighs cost considerations. Electronics manufacturers in South Korea deploy this grade for precision cleaning of photomask substrates.
- Perfluorodecalin:Bicyclic perfluorocarbon with the highest oxygen-carrying capacity among commercial grades, commanding premium pricing in liquid ventilation and ocular surgery protocols. Pharmaceutical distributors in Germany and France are building cold-chain infrastructure to support hospital adoption.
Perfluoropropane holds the largest share; momentum sits with perfluorodecalin as oxygen therapeutic approvals mature.
Application:
Cost tier differentiation separates commodity refrigerant volumes from semiconductor-grade premiums exceeding tenfold multiples, with purification infrastructure investments creating moats between application strata.
- Refrigeration:Historical anchor application now compressing under EU F-Gas Regulation phasedown quotas and corresponding state mandates in California and Washington. Industrial gas distributors are redirecting inventory toward exempt semiconductor and medical channels.
- Plasma Etching:Reactive ion etching for sub-7nm semiconductor architectures generates irreplaceable demand for sub-ppt purity grades. Samsung Foundry and TSMC are deploying point-of-use abatement systems at Pyeongtaek and Hsinchu facilities to comply with EPA emissions guidelines while sustaining throughput.
- Medical Applications:Liquid ventilation and ophthalmic surgery protocols are expanding most quickly as Japan's PMDA and the EMA advance regulatory frameworks for oxygen therapeutics. Perfluorodecalin formulations require stability certification and batch tracking absent from industrial applications.
- Electronics Manufacturing:Precision cleaning and heat transfer fluids for semiconductor fabrication equipment, where contamination thresholds now require molecular distillation capabilities limiting qualified suppliers.
Plasma etching commands premium pricing power; medical applications are climbing the fastest as therapeutic pathways mature.
End User:
Customer type fragmentation concentrates procurement authority differently, with semiconductor fabs negotiating decade-long offtake agreements while pharmaceutical distributors operate on quarterly tender cycles.
- Aerospace:Fire suppression and heat transfer applications in avionics cooling systems, where Boeing and Airbus specifications require dedicated qualification batches and traceability documentation.
- Automotive:Limited penetration confined to electric vehicle battery thermal management prototypes, with OEMs in Germany evaluating perfluorocarbon coolants against hydrofluoroolefin alternatives under EU fleet emissions rules.
- Electronics:Dominant demand concentration spanning semiconductor foundries, display panel manufacturers, and printed circuit board fabricators. South Korea's memory chip producers anchor regional volume through captive gas supply joint ventures.
- Pharmaceuticals:Emerging therapeutic segment requiring GMP-compliant manufacturing and cold-chain distribution infrastructure distinct from industrial gas logistics.
Electronics manufacturing holds the largest share; pharmaceuticals represents the steepest expansion trajectory as clinical approvals accumulate.
Distribution Channel:
Supply concentration in electrochemical fluorination capacity shapes channel economics, with direct relationships mandatory for semiconductor-grade volumes while distributors handle industrial refrigerant quotas.
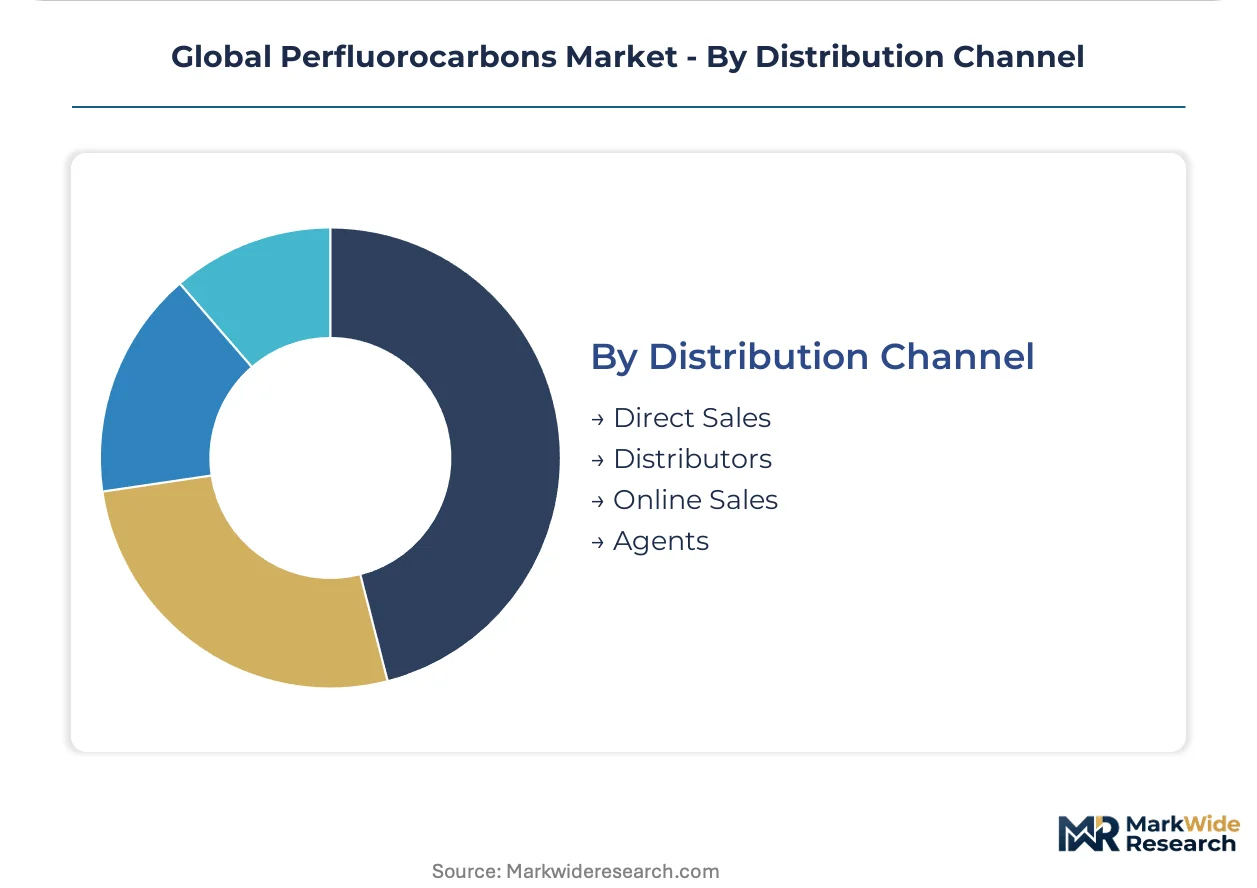
- Direct Sales:Long-term supply agreements with fixed purity escalation clauses dominate advanced node semiconductor procurement, requiring dedicated stainless-steel cylinder fleets with electropolished surfaces.
- Distributors:Regional industrial gas specialists manage refrigerant and industrial-grade volumes subject to F-Gas quota allocation and reclamation credit verification in Europe.
- Online Sales:Limited to research-grade quantities and reference standards, with purity certification and batch documentation delivered through digital chain-of-custody platforms.
- Agents:Intermediary relationships in markets with import licensing requirements, particularly China where MEE classifies certain perfluorocarbons as controlled substances.
Direct sales holds the largest share; distributors are gaining share fastest as mid-tier foundries seek flexible procurement terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production quotas under the EPA's AIM Act and the EU F-Gas Regulation are redirecting perfluorocarbon volumes toward semiconductor corridors in East Asia, while import licensing requirements in China constrain supply availability for industrial applications.
United States
EPA allowance trading mechanisms for hydrofluorocarbon phasedowns are elevating perfluorocarbon valuations in exempt semiconductor applications. State-level mandates in California and Washington mirror EU F-Gas restrictions, compressing refrigerant demand. Foundry construction in Arizona and Texas is attracting gas supply infrastructure investment for advanced node production.
Taiwan
TSMC's expansion of 2nm and 1.4nm process capacity at Hsinchu Science Park is generating irreplaceable demand for sub-ppt purity perfluoropropane. The island's EPA enforces emissions guidelines requiring point-of-use abatement systems at new fabrication facilities. Long-term offtake agreements with Japanese chemical houses are consolidating procurement authority among top-tier foundries.
South Korea
Samsung Foundry and SK Hynix are scaling plasma etching capacity for memory chip architectures at Pyeongtaek complexes. The MFDS regulates medical-grade perfluorocarbon imports for oxygen therapeutic applications. Captive gas supply joint ventures between memory producers and domestic distributors are reshaping channel economics.
Germany
EU Critical Raw Materials Act stockpiling mandates are generating offtake agreements for European purification facilities. The ECHA implements F-Gas Regulation steppedown quotas that limit industrial refrigerant volumes. Chemical processors in North Rhine-Westphalia are investing in fluorine recovery pyrolysis units to maintain production rights under reclamation credit mechanisms.
China
MEE classification of certain perfluorocarbons as controlled ozone-depleting substances requires import licenses and consumption permits. Acid-grade fluorite mining concentration in Inner Mongolia and Hunan exposes electrochemical fluorination supply chains to export licensing volatility. Semiconductor self-sufficiency initiatives under MIIT guidance are accelerating domestic gas purification capacity construction in Jiangsu and Shanghai.
Global Perfluorocarbons Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement relationships with advanced node foundries. The market structure concentrates around integrated fluorine chemistry platforms and specialized purification facilities. Three archetypes dominate: captive precursor producers, independent gas distributors with cylinder fleet assets, and pharmaceutical-grade formulators with GMP compliance. Capacity expansion and long-term supply contracting represent the dominant competitive moves as buyers seek supply security.
Among integrated chemistry platforms, Solvay S.A. and Daikin Industries, Ltd. occupy positions sustained by backward integration into fluoropolymer precursors. AGC Inc. exemplifies the purification-specialist archetype, serving contamination thresholds for EUV lithography processes. Chinese fabricators including Changshu 3F Zhonghao New Chemical Materials Co., Ltd. represent regional scale players competing on electrochemical fluorination capacity.
| Leading Market Players |
|---|
| 3M Company |
| Solvay S.A. |
| The Chemours Company |
| Daikin Industries, Ltd. |
| AGC Inc. |
| Arkema Group |
| Fujian Yongjing Technology Co., Ltd. |
| F2 Chemicals Ltd |
| Changshu 3F Zhonghao New Chemical Materials Co., Ltd. |
| Others |
Supply & Pricing Matrix
Inner Mongolia's acid-grade fluorite mining concentration shapes downstream pricing power for electrochemical fluorination feedstocks, with export licensing volatility from China's MEE translating directly into cost premiums for semiconductor-grade perfluorocarbon producers in Taiwan and South Korea.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between semiconductor-grade premiums and industrial refrigerant baselines, with sub-ppt purity thresholds commanding tenfold multiples over standard grades. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service intensity, with medical oxygen therapeutic formulations requiring cold-chain custody documentation. Cost compression in industrial refrigerant tiers is intensifying because EU F-Gas phasedown quotas eliminate historical demand anchors. Pharmaceutical distributors exhibit the highest price sensitivity due to reimbursement pathway uncertainty, while advanced node foundries prioritize supply security over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese chemical houses to Taiwanese foundries are restructuring working capital requirements for cylinder fleet operators. Geographic supply concentration centers on China for acid-grade fluorite, Japan for electrochemical fluorination capacity, and South Korea for captive gas supply joint ventures. Raw material dependencies draw from fluorite ore, cobalt trifluoride catalysts, and hydrocarbon feedstocks. Single-source vulnerability in Chinese fluorite export licensing exposes downstream processors to permit volatility. Distribution runs through direct long-term offtake agreements for semiconductor grades and regional industrial gas distributors for industrial quotas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perfluorocarbon supply chains are approaching a platform-economics inflection as EUV lithography process nodes demand interoperable purification standards across TSMC, Samsung Foundry, and Intel manufacturing ecosystems.
For Market Incumbents: Entrench procurement relationships through dedicated cylinder fleet provisioning and on-site technical support teams at Hsinchu and Pyeongtaek complexes. Backward integration into fluoropolymer precursor production defends margin position against Chinese electrochemical fluorination scale players. Prioritize molecular distillation capacity additions to maintain qualification for sub-ppt contamination thresholds as node architectures advance. For New Entrants and Emerging Players: India's Gujarat and Karnataka semiconductor corridors present the most penetrable geography for etching gas distributors seeking first-mover positioning under the country's PLI scheme. Medical oxygen therapeutic applications in Germany and France offer white-space expansion as EMA regulatory pathways mature for perfluorodecalin formulations. Pursue asset-light leasing models for fluorochemical processing equipment to reduce capital barriers for mid-tier foundry supply contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fluorine chemistry platforms lacking semiconductor-grade purification capabilities. Long-term viability hinges on exposure to advanced node production scaling rather than refrigerant applications facing structural compression. Monitor divergence between EPA allowance trading prices and EU quota auction mechanisms as the inflection signal for where incremental production capacity receives financing approval.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Solvay and Daikin sustain supply security through captive fluoropolymer precursor production in Belgium and Japan. |
| Long-term Supply Agreement | Ten-year offtake contracts with fixed purity escalation clauses consolidate procurement authority among Hsinchu foundries. |
| Capacity Expansion | AGC's molecular distillation investments in Japan address sub-ppt contamination thresholds for EUV lithography processes. |
| Joint Venture | Samsung Foundry's captive gas supply partnerships with domestic distributors reshape Pyeongtaek channel economics. |
| Green Manufacturing Transition | German chemical processors deploy fluorine recovery pyrolysis units to maintain production rights under EU reclamation credit mechanisms. |
Research Methodology
Operator-level perspectives from semiconductor fab gas procurement managers, electrochemical fluorination plant engineers, pharmaceutical regulatory affairs specialists, and industrial gas distribution channel heads anchored the qualitative base. Primary fieldwork combined with secondary validation from customs and trade data, SEC filings of listed fluorochemical producers, EPA AIM Act allowance trading records, and EU F-Gas Regulation quota auction results. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning purity grade tier, end-use application, regional production hub, and regulatory exposure cluster. CAGRs derived from node complexity multiplication effects in semiconductor manufacturing and therapeutic approval velocity in medical applications. Forecast inputs incorporated fluorite export licensing volatility from China's MEE and EU Critical Raw Materials Act stockpiling mandate implementation.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese electrochemical fluorination scale players or accelerated EUV node transitions would shift outcomes. Macroeconomic contraction in semiconductor capital expenditure, regulatory acceleration of F-Gas phasedown schedules, or breakthroughs in fluorine-free plasma chemistries would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Military Propellants Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Petrochemicals Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Aliphatic Hydrocarbon Market
Petrochemicals
Basic Petrochemical Market
Petrochemicals
Propylene Market