
 Global Peanut Meal Market | 2026-2036
Global Peanut Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peanut Meal Market Foresight
Commodity trading routes for peanut meal are fragmenting as regional crushers bypass traditional export hubs. Wilmar International leverages its integrated oilseed processing network across Southeast Asia to secure origination volumes. Cargill competes through ocean freight optimization and destination-market blending capabilities. Chia Tai Group anchors its position with backward integration into poultry operations that consume captive meal output.
Peanut meal comprises the residual solid matter after oil extraction from groundnut kernels, typically containing 40-50% crude protein and variable fiber content depending on whether mechanical pressing or solvent extraction is employed. The material serves primarily as a protein-rich feed ingredient for monogastric and ruminant livestock rations. Solvent-extracted variants command premium placement in aquafeed formulations where lower oil residues improve pellet stability. Livestock feed applications still occupy the largest volume share, though aquafeed represents the fastest-growing demand pool as marine ingredient substitution accelerates. Bulk packaging dominates terminal market logistics, while jumbo bags gain share among mid-scale feed compounders seeking handling efficiency.
REACH compliance governs contaminant thresholds for peanut meal entering European feed channels, while FDA feed safety rules shape product specifications for US-bound shipments. China's GB standards for feed原料 set maximum aflatoxin limits that directly determine export lot acceptance at ports. Stakeholders must track evolving mycotoxin testing protocols and deforestation traceability mandates across destination jurisdictions to preserve market access.
Market Dynamics
Feed-grade protein markets are restructuring around deforestation traceability mandates, with EU Green Deal compliance costs now determining which origin lots clear European ports and which divert to alternative destinations.
Growth Catalysts
- Aquafeed formulation standards:Marine ingredient substitution protocols in Southeast Asian shrimp farming are elevating solvent-extracted peanut meal into premium ration slots previously occupied by fishmeal.
- India's dairy sector expansion:Cooperative milk procurement networks in Gujarat and Maharashtra are scaling compound feed offtake, pulling additional crush volumes through domestic oilseed processors.
- REACH contaminant thresholds:ECHA-mandated aflatoxin testing protocols are filtering out informal suppliers, concentrating import volumes among certified exporters with laboratory documentation.
Market Restraints
- Groundnut input cost volatility:Edible oil price swings in Indian spot markets transmit directly to meal production economics, compressing crusher margins without corresponding feed price adjustments.
- Argentina-originated supply concentration:Mechanical pressing infrastructure in Córdoba and Santa Fe provinces dominates exportable surplus, creating single-origin vulnerability for Atlantic-facing buyers.
- Soybean meal substitution elasticity:Protein equivalence calculations in poultry ration software default to soy pricing, limiting peanut meal inclusion rates when oilseed spreads narrow.
Strategic Opportunities
- Vietnam aquafeed underpenetration:Coastal shrimp farming provinces from Bà Rịa-Vũng Tàu to Kiên Giang lack established solvent-extracted meal supply chains, opening origination partnerships with local feed mills.
- EU Deforestation Regulation traceability premiums:Geolocation documentation and farm-level audit trails command price premiums in Dutch and German feed channels as compliance deadlines approach.
- Blockchain-IoT convergence:Immutable lot records linked to moisture and temperature sensors are collapsing documentation costs for export certification, enabling mid-scale crushers to access premium European buyers.
Industry Challenges
- Mycotoxin laboratory capacity:Certified testing infrastructure for aflatoxin B1 and total aflatoxin quantification remains concentrated in port cities, delaying rural crush facility qualification for export markets.
- Solvent extraction capex requirements:Hexane-based processing lines demand seven-figure capital commitments with extended commissioning timelines, excluding smaller processors from aquafeed-grade output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peanut Meal Market |
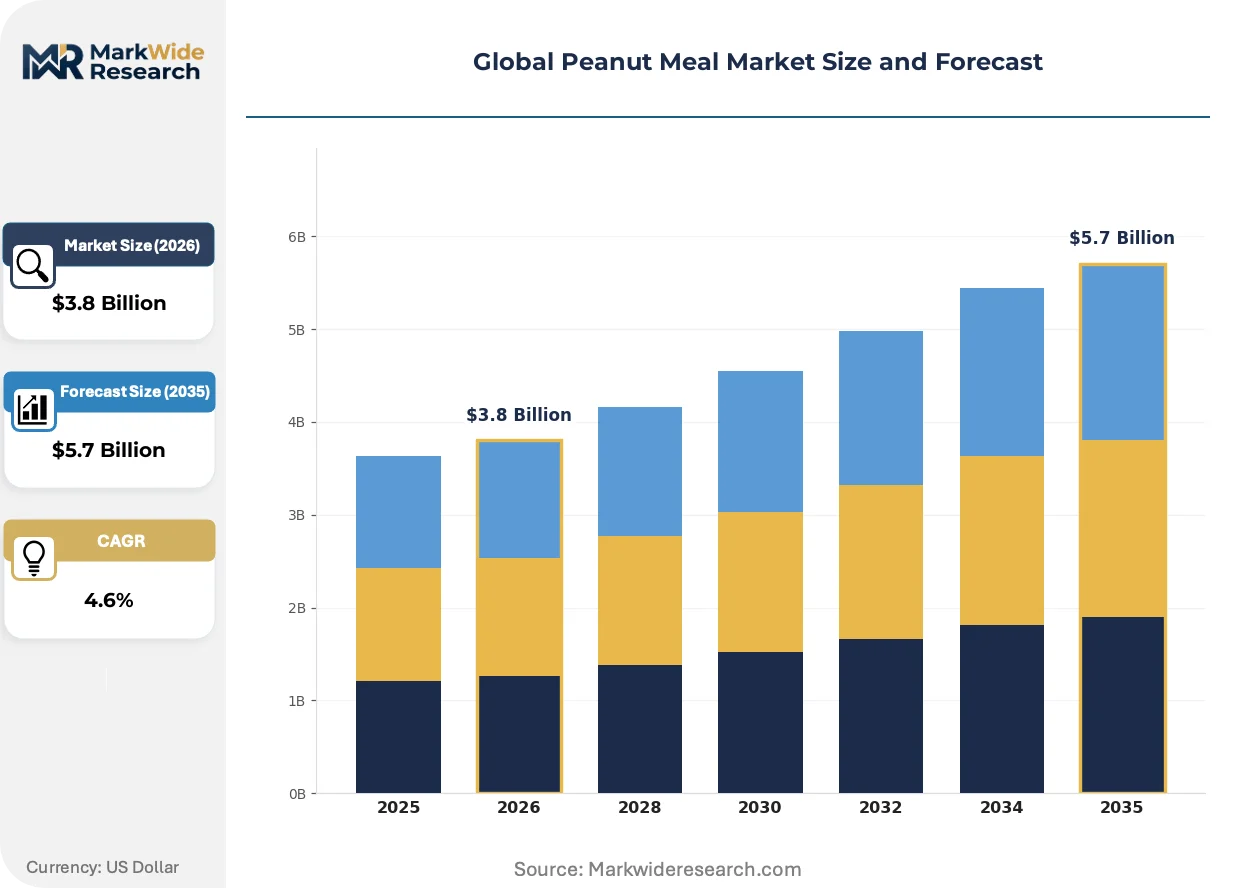
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cake, Solvent Extracted Oil, Press Cake, Defatted Meal Application: Livestock Feed, Aquafeed, Organic Fertilizers, Pet Food, Biogas Production End User: Feed Manufacturers, Agricultural Cooperatives, Bioproduct Companies, Pet Food Companies Packaging Type: Bagged, Bulk, Jumbo Bags, Sack Packaging |
| Companies Covered | Chia Tai Group, Longda, Luhua, Wilmar International, Jiusan Group, Yihaikerry, Cargill, Xiwang Foodstuffs, Cofco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peanut Meal Market Shifts & Advancements
Processing technology and procurement protocols are converging to compress quality variation and documentation friction, reshaping how origin lots qualify for destination-market placement.
Near-infrared spectroscopy calibration for protein and fiber quantification is collapsing laboratory turnaround times at crusher loading points. Vietnamese and Thai feed compounders now demand real-time certificates of analysis before vessel booking, compressing the window for lot rejection and re-blending. This compression is forcing origin suppliers to install inline sensors or lose contract eligibility.
EU Green Deal deforestation-free supply chain rules are mandating geolocation coordinates for every farm contributing to export lots. EFSA-aligned feed safety audits now trace peanut cultivation plots through satellite verification and farm registry cross-checks. Dutch and German importers are responding by consolidating procurement among vertically documented suppliers with existing compliance infrastructure.
Direct crusher-to-compounder contracting is displacing spot market purchases at Southeast Asian ports. Large Vietnamese shrimp feed manufacturers now sign twelve-month offtake agreements with Indian solvent extraction facilities, locking protein specifications and delivery schedules. This shift concentrates volume flows through documented channels and marginalizes traders lacking backward integration into crush assets.
Global Peanut Meal Market Segmentation
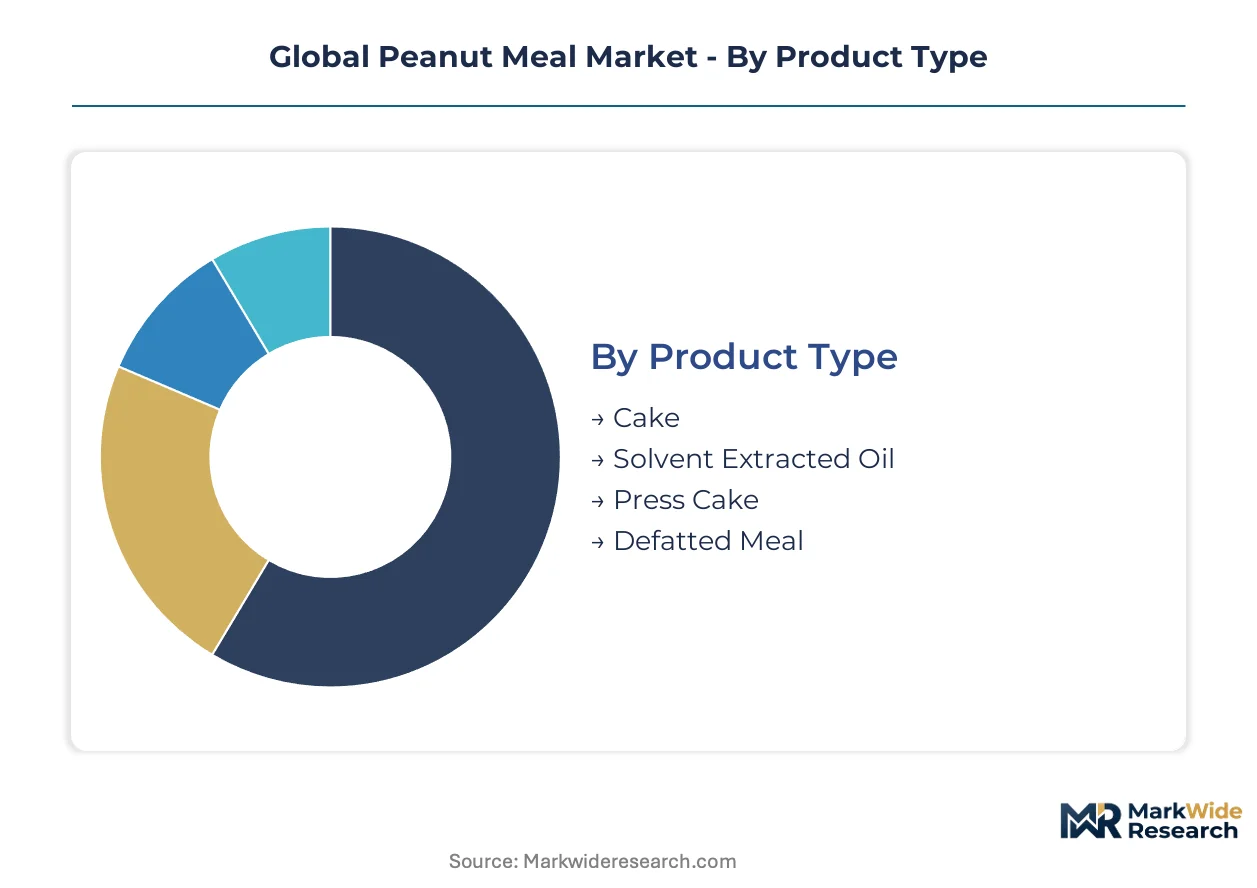
Peanut meal segmentation reflects divergent processing economics and destination-market quality thresholds. Distinct product grades command price spreads that separate commodity feed applications from premium aquafeed formulations. Packaging and end-user channel choices further stratify procurement patterns across integrated processors and independent compounders.
Product Type:
Use-case spectrum spans mechanical pressing for livestock rations through solvent extraction for high-protein aquafeed specifications.
- Solvent Extracted Oil:Hexane-processed meal achieves 45-50% crude protein with residual oil below 1.5%, meeting aquafeed pellet stability requirements in Vietnamese shrimp farming provinces. ECHA REACH contaminant documentation requirements filter supplier eligibility toward certified crushers with laboratory infrastructure.
- Cake:Mechanical pressing leaves 8-12% residual oil content, producing softer pellets suited for ruminant feed rations in Indian dairy cooperatives. Gujarat and Maharashtra crushing facilities dominate origination volumes for this grade.
- Press Cake:Intermediate oil retention at 5-8% serves poultry layer formulations where energy density requirements moderate protein concentration needs.
- Defatted Meal:Maximum protein concentration above 50% targets specialty pet food manufacturers in Germany and the Netherlands seeking ingredient label differentiation.
The dominant share belongs to Cake, while Solvent Extracted Oil is closing the gap fastest.
Application:
Volume concentration tracks protein substitution economics across livestock species and marine farming systems.
- Livestock Feed:Dairy sector expansion in India pulls the largest absolute tonnage through cooperative procurement networks in Gujarat. Poultry ration inclusion rates fluctuate with soybean meal price spreads, compressing peanut meal uptake when oilseed parity narrows.
- Aquafeed:Marine ingredient substitution protocols in Southeast Asian shrimp farming elevate solvent-extracted grades into premium ration slots. Bà Rịa-Vũng Tàu to Kiên Giang provinces lack established supply chains, opening origination partnerships.
- Organic Fertilizers:Nitrogen-rich residuals from oil extraction serve specialty crop producers in California and Spain seeking organic certification compliance.
- Pet Food:Hypoallergenic positioning drives inclusion in premium dog and cat formulations, particularly among European manufacturers targeting grain-free product lines.
- Biogas Production:Residual organic matter contributes to anaerobic digestion feedstock in German agricultural biogas facilities.
Livestock Feed maintains volume leadership, though Aquafeed demonstrates the steepest expansion trajectory.
End User:
Procurement scale and quality documentation requirements separate integrated compounders from distributed agricultural buyers.
- Feed Manufacturers:Large Vietnamese shrimp feed producers now execute twelve-month offtake agreements with Indian solvent extraction facilities, locking protein specifications and delivery schedules. Direct crusher-to-compounder contracting marginalizes traders lacking backward integration into crush assets.
- Agricultural Cooperatives:Distributed dairy and poultry operations in India aggregate demand through state-level federations, purchasing bulk deliveries for internal feed milling.
- Bioproduct Companies:Industrial protein extraction and biochemical conversion operations seek consistent quality lots for non-feed applications.
- Pet Food Companies:European and North American manufacturers demand batch-level mycotoxin documentation exceeding standard feed-grade thresholds.
Feed Manufacturers command the dominant procurement volume, while Pet Food Companies are expanding specification requirements most aggressively.
Packaging Type:
Handling efficiency and contamination risk determine format selection across terminal markets and inland distribution.
- Bulk:Vessel-loading economics dominate ocean freight routes from Argentina's Córdoba and Santa Fe provinces to European and Southeast Asian ports. REACH and EU Green Deal documentation travels with bulk lot manifests.
- Jumbo Bags:Mid-scale feed compounders in Thailand and Vietnam seek handling efficiency without full bulk infrastructure investment. Real-time certificates of analysis now precede vessel booking, compressing rejection windows.
- Bagged:Smallholder dairy cooperatives in India require 50kg units for manual handling at village collection points.
- Sack Packaging:Traditional woven polypropylene serves residual spot market transactions at secondary ports.
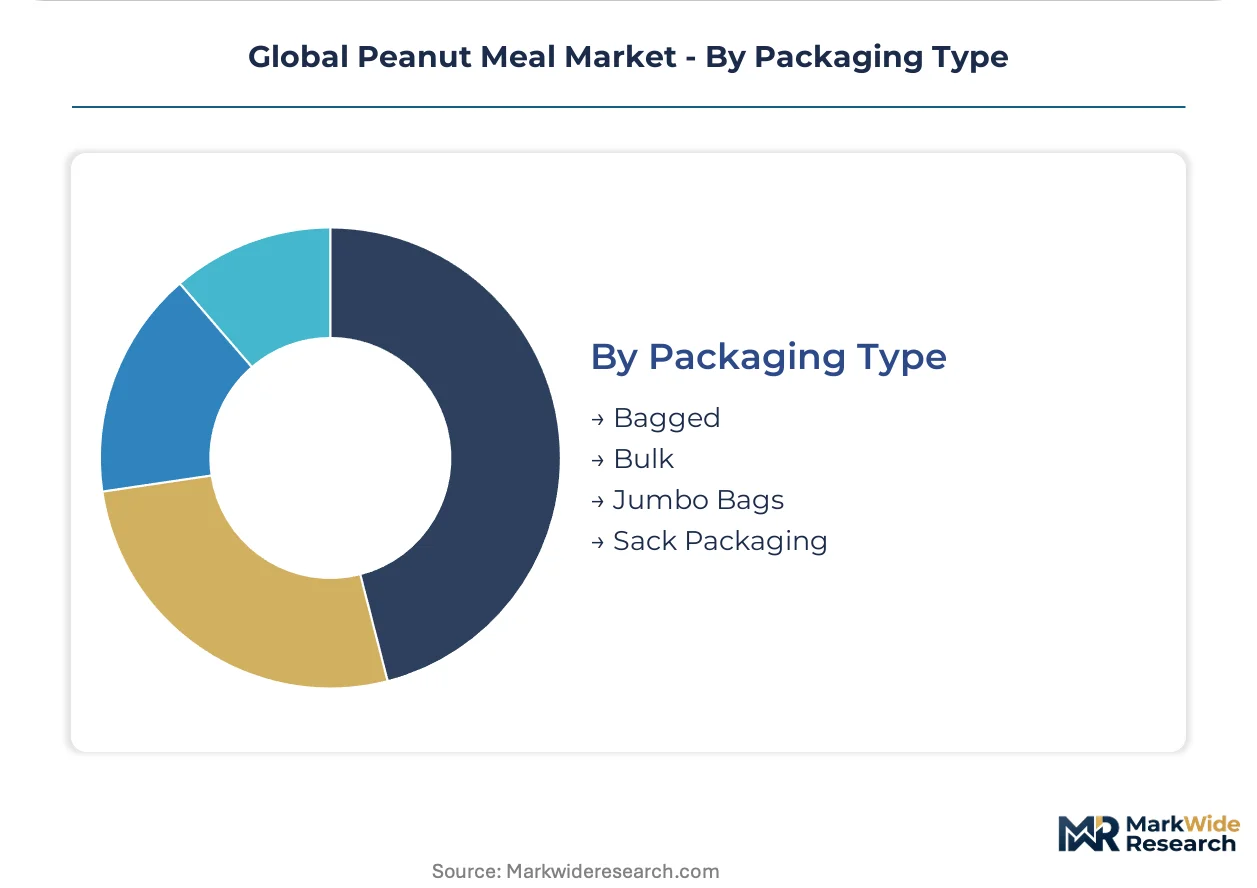
Bulk retains the largest volume share, while Jumbo Bags are gaining adoption fastest among mid-scale compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal deforestation-free supply chain rules are redirecting peanut meal trade flows toward compliant origination points. India's dairy sector expansion and Vietnam's aquafeed industrialization are concentrating demand growth in Asia. Argentina's mechanical pressing infrastructure remains the primary Atlantic-facing supply source.
India
Gujarat and Maharashtra dairy cooperatives are scaling compound feed procurement through state-level federations. FSSAI feed safety standards and DGFT export documentation requirements filter supplier eligibility toward certified crushers. Solvent extraction facilities in Rajkot and Ahmedabad are locking twelve-month offtake agreements with Vietnamese shrimp feed manufacturers.
Vietnam
Coastal shrimp farming provinces from Bà Rịa-Vũng Tàu to Kiên Giang lack established solvent-extracted meal supply chains, creating origination partnerships with Indian processors. The country's national feed safety regulator mandates real-time certificates of analysis before vessel booking, compressing rejection windows. Direct crusher-to-compounder contracting is marginalizing spot market traders at Ho Chi Minh City port terminals.
Argentina
Mechanical pressing infrastructure in Córdoba and Santa Fe provinces dominates exportable surplus for Atlantic-facing buyers. The country's national agricultural export authority enforces aflatoxin documentation protocols that determine lot acceptance at European ports. Bulk vessel loading economics from Rosario grain terminals shape ocean freight routes to the Netherlands and Germany.
Germany
Dutch and German feed channels are consolidating procurement among vertically documented suppliers with EU Deforestation Regulation compliance infrastructure. ECHA REACH contaminant thresholds and EFSA-aligned feed safety audits trace cultivation plots through satellite verification. Pet food manufacturers in Hamburg and Bremen demand batch-level mycotoxin documentation exceeding standard feed-grade thresholds.
Thailand
Mid-scale feed compounders seek handling efficiency through jumbo bag procurement without full bulk infrastructure investment. The country's national feed quality regulator aligns with GB standards for aflatoxin limits that determine import lot acceptance. Bangkok-based shrimp feed producers are expanding solvent-extracted meal inclusion rates in marine ingredient substitution protocols.
Global Peanut Meal Market Competitive Landscape
On the supply side, the industry is consolidating around integrated oilseed processors with backward integration into crushing assets and destination-market blending capabilities. Three archetypes dominate: Southeast Asian agribusiness conglomerates with aquafeed channel access, Chinese state-linked crushers with domestic origination scale, and multinational traders with ocean freight optimization and compliance documentation infrastructure. Competitive moves center on origination partnerships with Vietnamese feed mills and blockchain-IoT traceability investments for EU market access.
Among Southeast Asian agribusiness conglomerates, Wilmar International anchors the integrated processing network archetype with origination leverage across multiple jurisdictions. Cargill occupies the multinational trader position with ocean freight and destination-market blending capabilities. Chia Tai Group exemplifies backward integration into poultry operations that consume captive meal output, representing the downstream demand anchoring strategy.
| Leading Market Players |
|---|
| Chia Tai Group |
| Longda |
| Luhua |
| Wilmar International |
| Jiusan Group |
| Yihaikerry |
| Cargill |
| Xiwang Foodstuffs |
| Cofco |
| Others |
Supply & Pricing Matrix
Undercapacity in Indian solvent extraction facilities concentrates pricing power among certified crushers with ECHA REACH documentation infrastructure, compressing margins for mechanical pressing operators while elevating premium realizations for aquafeed-grade output. This utilization asymmetry forces buyers into twelve-month offtake commitments to secure volume, locking in protein specifications and delivery schedules that spot market traders cannot match.
Pricing Analysis
Volume-discount tiering separates solvent-extracted premium grades from mechanical cake and press cake intermediates, with aquafeed specifications commanding spreads based on residual oil thresholds and contaminant documentation depth. Price differentiation rests on certification grade—ECHA REACH compliance versus informal testing—and geographic delivery cost differentials between Indian origination and Vietnamese destination ports. Cost compression in mechanical pressing tiers is intensifying because soybean meal substitution elasticity narrows inclusion rates when oilseed spreads contract. Mid-scale Vietnamese compounders exhibit highest price sensitivity, while Dutch and German feed channels with EU Deforestation Regulation mandates show lowest sensitivity to base price movements.
Supply Chain Analysis
Upstream groundnut feedstock availability draws from Indian Gujarat and Maharashtra crushing belts, Argentine Córdoba and Santa Fe provinces, and select West African origination points. Raw material dependencies center on hexane solvent supply for extraction lines, laboratory certification infrastructure for mycotoxin testing, and geolocation documentation systems for EU compliance. Single-source vulnerability concentrates in Argentine mechanical pressing infrastructure, where Atlantic-facing buyers lack alternative origination for bulk vessel economics. Distribution runs through direct crusher-to-compounder contracting that marginalizes spot market traders at Ho Chi Minh City and Bangkok port terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against soybean meal protein equivalence calculations that default inclusion rates in poultry ration software, threatening volume retention when oilseed spreads narrow.
For Market Incumbents: Insulate contract volumes by embedding blockchain-IoT traceability infrastructure that collapses documentation costs for EU Deforestation Regulation compliance, locking premium channel access against uncertified competitors. Deepen backward integration into crushing assets across Indian Rajkot and Ahmedabad clusters to secure origination leverage as solvent extraction capacity tightens. Priority lever: twelve-month offtake agreements with Vietnamese shrimp feed manufacturers to preempt spot market displacement.
For New Entrants and Emerging Players: Pursue Vietnam's coastal shrimp farming provinces from Bà Rịa-Vũng Tàu to Kiên Giang, where solvent-extracted meal supply chains remain underdeveloped and local feed mills seek origination partnerships. Target mid-scale Thai compounders seeking jumbo bag handling efficiency without bulk infrastructure investment. Go-to-market angle: real-time certificate of analysis capabilities that compress rejection windows and match incumbent documentation speed.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Indian solvent extraction facilities with locked Vietnamese aquafeed offtake and existing ECHA REACH certification infrastructure. Long-term viability over the projection horizon favors acquisition targets with geolocation documentation systems and farm-level audit trails already operational. Signal to watch: consolidation velocity among Córdoba and Santa Fe mechanical pressing operators as Argentine supply concentration creates vulnerability-driven M&A pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-IoT Traceability Investment | Immutable lot records linked to sensors collapse EU compliance documentation costs for mid-scale crushers. |
| Backward Integration into Crushing Assets | Rajkot and Ahmedabad facility ownership secures origination leverage against spot market traders. |
| Long-term Supply Agreement | Twelve-month offtake contracts with Vietnamese shrimp feed manufacturers lock protein specifications and delivery schedules. |
| Certification Infrastructure Buildout | ECHA REACH laboratory capacity expansion filters out informal suppliers and concentrates import volumes. |
| Geographic Expansion | Kiên Giang and Bà Rịa-Vũng Tàu origination partnerships capture underpenetrated aquafeed demand. |
Research Methodology
Initial hypotheses were tested against primary input from oilseed crushing facility managers, Vietnamese shrimp feed procurement directors, Indian dairy cooperative feed planners, European compounder regulatory affairs leads, and Argentine export terminal operators and refined through secondary validation against customs trade data, FSSAI feed safety filings, ECHA REACH registration databases, and Vietnamese national feed quality regulator import records. Bottom-up volume estimates from crusher capacity utilization and top-down demand calibration from livestock and aquafeed consumption patterns were triangulated to reconcile segment-level outputs.
Demand-supply-balance modeling across product type, application, end user, and packaging format dimensions generated volume and value trajectories over the projection horizon. CAGRs were derived from segment-specific growth coefficients applied to base-year estimates, with aquafeed substitution protocols and dairy sector expansion rates serving as primary demand-side inputs and solvent extraction capacity additions and groundnut input cost volatility as supply-side constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-linked crushers with domestic origination scale would shift outcomes through accelerated capacity deployment. Cross-checking against FAO oilseed meal trade statistics and national feed industry association consumption surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Peanuts Market
Nuts and Seeds
Macadamia Butter Market
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Rubus Idaeus (Raspberry) Seeds Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Asia-Pacific Grape Seed Extract Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Australia Fox Nuts Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
North America Moringa Products Market