
 Rubus Idaeus (Raspberry) Seeds Market | 2026-2036
Rubus Idaeus (Raspberry) Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Rubus Idaeus (Raspberry) Seeds Market Analytics
Poland's Mazovia region is rewriting supply dynamics for Rubus Idaeus seed derivatives as Polish growers expand cold-press extraction capacity for cosmetic-grade oils. Aldivia SA leverages backward integration into berry sourcing to secure raw material consistency across seasonal harvests. Nutrativa Global anchors North American distribution through direct relationships with natural cosmetics manufacturers. TC USA Inc. competes on organic certification breadth, maintaining USDA Organic and EU Organic compliance simultaneously.
Rubus Idaeus seeds comprise the dried, cleaned embryos of raspberry fruit, typically containing 15-22% oil by weight with a fatty acid profile dominated by linoleic acid, alpha-linolenic acid, and oleic acid, extracted through cold-pressing or supercritical CO2 methods for cosmetic, nutraceutical, and agricultural propagation applications. Organic seeds command premium positioning in cosmetic formulations where clean-label claims determine brand access to European and North American retail channels. Commercial farming applications for hybrid seeds show structural expansion as berry growers seek disease-resistant stock with standardized germination rates. Online retail distribution channels capture margin pools through subscription-based seed replenishment models targeting home gardeners and small-scale landscapers.
USDA Organic standards govern seed certification for US market access, while EU REACH and EFSA frameworks regulate cosmetic-grade oil purity and novel food applications across European jurisdictions. FDA oversight of cosmetic ingredient safety influences formulation decisions by US-based end-users importing processed seed oils. Stakeholders must monitor evolving organic equivalence agreements between regulatory blocs, as divergence in certification requirements threatens cross-border supply chain continuity for multinational seed oil processors.
Market Dynamics
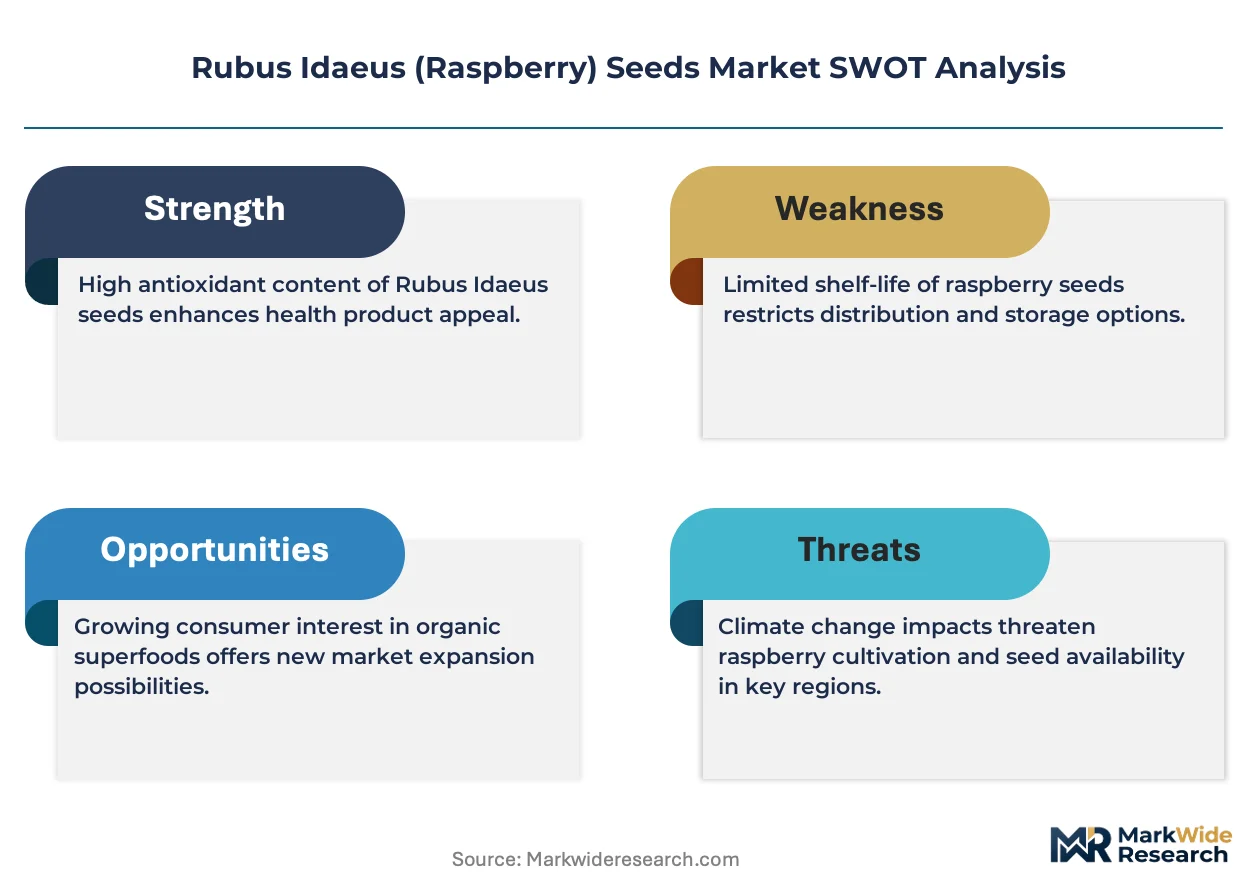
EU REACH compliance on seed oil purity is compressing extraction standards across the raspberry seed value chain, forcing processors to upgrade cold-press infrastructure or exit cosmetic-grade supply tiers entirely. This regulatory pressure concentrates margin capture among operators with backward-integrated berry sourcing and certified organic handling capacity.
Growth Catalysts
- Cold-press extraction technology:Cosmetic formulators in Poland's Mazovia region deploy advanced mechanical pressing to preserve linoleic acid profiles above 52%, qualifying oils for premium skincare formulations. Equipment upgrades reduce thermal degradation losses by half versus conventional solvent methods.
- EU Organic certification:Clean-label positioning requirements across German and French retail channels pull organic raspberry seeds into formulation pipelines for natural cosmetics. EFSA novel food approvals expand oil applications into functional food matrices.
- Hybrid seed propagation demand:Commercial berry growers in Pacific Northwest cultivation zones source disease-resistant Rubus Idaeus stock with standardized germination rates above 85%, replacing open-pollinated varieties prone to root rot.
Market Restraints
- Input cost volatility:Fresh raspberry pulp prices fluctuate with weather-induced harvest variations in Poland and Serbia, squeezing seed byproduct economics for oil processors dependent on fruit industry waste streams.
- Supply concentration risk:Cosmetic-grade seed oil refining clusters in three Polish extraction facilities, creating single-source vulnerability for EU formulators requiring REACH-compliant documentation chains.
- Substitution threat:Cranberry seed oil offers comparable linoleic acid content at 15-20% lower input costs, pressuring raspberry positioning in mid-tier natural skincare formulations.
Strategic Opportunities
- Underpenetrated propagation markets:Brazilian and Chilean berry growers lack access to certified disease-resistant Rubus Idaeus genetics, creating export channels for EU-based seed breeders with phytosanitary clearance capacity.
- Subscription retail channels:Direct-to-consumer seed replenishment models target home gardeners in US Pacific Coast states, bypassing wholesale horticultural distributors with automated seasonal delivery.
- Supercritical CO2 convergence:Combination of carbon dioxide extraction with inline terpene recovery systems enables pharmaceutical-grade oil purity for dermal therapeutic applications beyond cosmetic use.
Industry Challenges
- Certification timeline compression:USDA Organic and EU Organic dual compliance requires 18-24 month field history documentation, delaying market entry for new cultivation entrants.
- Extraction capex intensity:Supercritical CO2 systems demand capital deployment above cold-press alternatives, filtering processor participation toward balance-sheet-strong operators.
- Phytosanitary standard fragmentation:Divergent national seed treatment regulations between EU member states complicate cross-border propagation material shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubus Idaeus (Raspberry) Seeds Market |
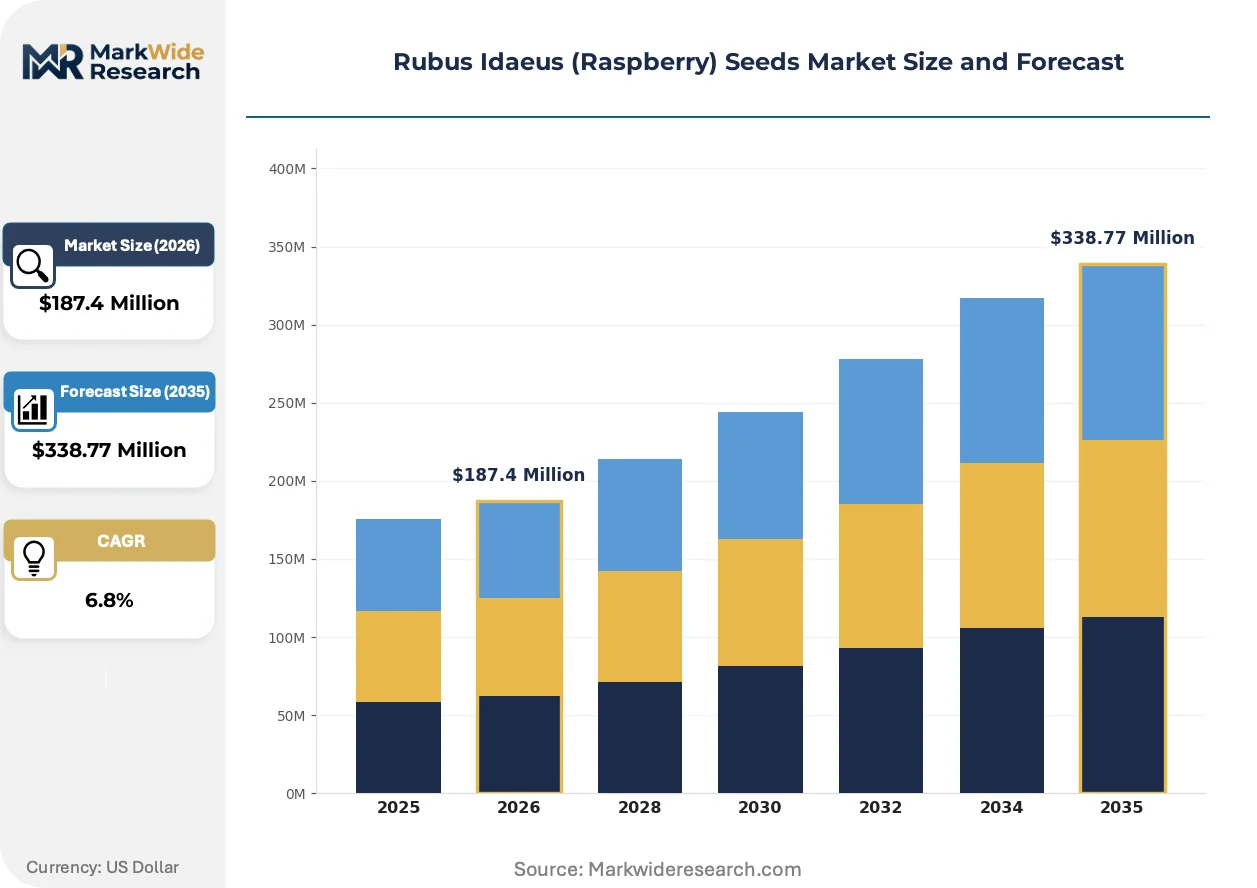
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Seeds, Conventional Seeds, Hybrid Seeds, Heirloom Seeds End Use: Gardening, Commercial Farming, Research, Landscaping Distribution Channel: Online Retail, Garden Centers, Agricultural Supply Stores, Direct Sales Packaging Type: Bulk Bags, Retail Packs, Seed Tapes, Small Sachets |
| Companies Covered | Aldivia SA, Organic Pure Oil, TC USA Inc., Nutrativa Global, Natural Sourcing, O&3 - The Oil Family, Camden-Grey Essential Oils, Leven Rose, Aromantic Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubus Idaeus (Raspberry) Seeds Market Evolving Landscape
Processing technology and regulatory frameworks are compressing traditional extraction economics while opening premium tier access for operators with certified organic infrastructure and advanced mechanical separation capabilities.
Supercritical CO2 extraction is hybridizing with inline antioxidant recovery systems to produce pharmaceutical-grade raspberry seed oil with extended shelf stability. German cosmetic manufacturers adopt these integrated platforms to meet ECHA purity thresholds for dermal therapeutic claims. The technology is hybridizing mid-tier processors out of REACH-compliant supply chains entirely.
REACH Annex XVII restrictions on solvent residues in cosmetic applications tighten maximum allowable hexane traces to 5 ppm, forcing solvent-based extractors toward mechanical alternatives. Polish processors retrofit cold-press lines to maintain EU market access. Cosmetic formulators in France and Benelux markets now require batch-specific residue documentation.
Certification-driven procurement now dominates brand access decisions for natural cosmetics retailers in Germany and Scandinavia. Buyers specify dual USDA-EU Organic compliance as table stakes, displacing single-certification suppliers from shelf placement. This pattern concentrates most visibly in Nordic pharmacy chains where clean-label positioning commands 40% shelf space allocation.
Rubus Idaeus (Raspberry) Seeds Market Segmentation
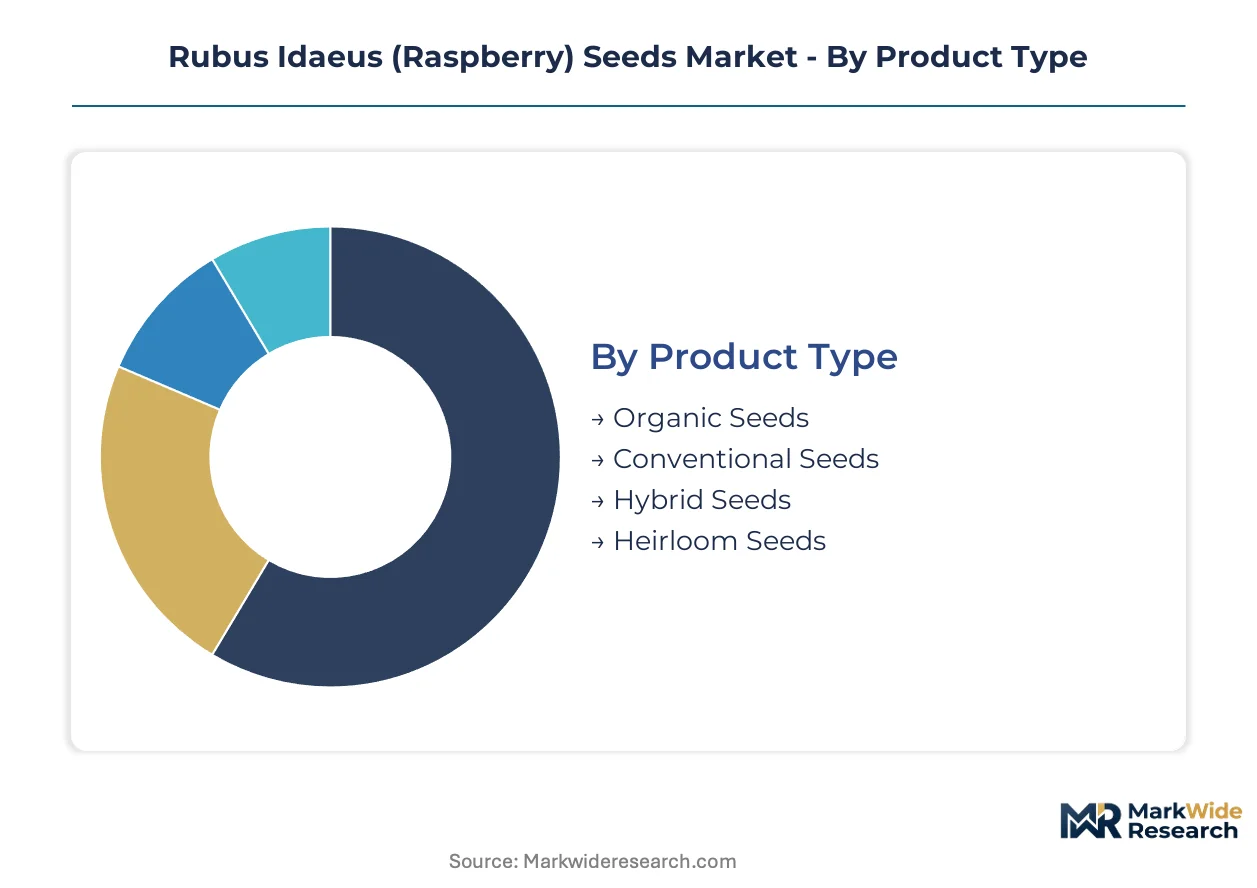
Raspberry seed procurement patterns diverge sharply across use cases, with cosmetic oil extractors demanding certified organic traceability while propagation buyers prioritize germination consistency over certification tier. Segmentation reveals how extraction technology, distribution reach, and packaging format each create distinct margin pools and competitive moats.
Product Type:
After-sales service intensity peaks with hybrid seed lines, where breeders provide technical support for germination protocols and disease management through multiple growing seasons.
- Organic Seeds:Cold-pressed oil extraction requires seeds certified under USDA Organic or EU Organic frameworks, with linoleic acid preservation driving premium positioning in French and German cosmetic formulations. Polish Mazovia processors dominate supply, backward-integrated into berry sourcing to secure batch consistency.
- Hybrid Seeds:Disease-resistant stock with standardized germination rates above 85% commands technical support contracts from Pacific Northwest commercial berry operations. Root rot resistance traits displace open-pollinated varieties in high-density cultivation zones.
- Conventional Seeds:Uncertified propagation material serves price-sensitive landscaping contractors in Eastern European markets with less stringent retail labeling requirements.
- Heirloom Seeds:Heritage varieties attract home gardeners through subscription retail channels emphasizing genetic diversity and flavor profiles over yield optimization.
By volume, conventional seeds lead. By growth pace, organic certification tiers are expanding most quickly.
End Use:
Application-specific requirements reshape procurement specifications, with research buyers demanding phytosanitary documentation that commercial farming clients rarely require.
- Commercial Farming:Large-scale berry operations in Serbia and Poland source hybrid seeds with documented field performance across multiple harvest cycles, prioritizing disease resistance over oil extraction potential.
- Gardening:Home cultivation drives demand for retail-packaged heirloom and organic varieties through online subscription models targeting Pacific Coast US demographics with automated seasonal replenishment.
- Landscaping:Municipal and commercial landscape architects specify conventional seed lines for erosion control and ornamental hedgerow applications where fruit quality is irrelevant.
- Research:Agricultural universities and seed banks require detailed genetic provenance documentation and phytosanitary clearance for breeding program access, creating procurement delays of 6-12 months.
Commercial farming generates the highest absolute volume. Gardening applications show the steepest expansion trajectory through direct-to-consumer channels.
Distribution Channel:
Channel selection determines margin capture, with direct sales bypassing wholesale markups while online retail enables subscription-based recurring revenue models.
- Online Retail:Subscription platforms target home gardeners with automated seasonal delivery, capturing recurring revenue streams and bypassing traditional horticultural distributor networks.
- Direct Sales:Large commercial farming operations negotiate volume contracts directly with Polish and Serbian seed breeders, securing price advantages through multi-year commitments.
- Garden Centers:Brick-and-mortar retail in Germany and Scandinavia emphasizes certified organic packaging to meet clean-label positioning requirements of Nordic pharmacy chains.
- Agricultural Supply Stores:Conventional seed lines for commercial landscaping move through established farm supply cooperatives with credit terms and bulk delivery logistics.
Direct sales dominate commercial farming procurement. Online retail is gaining share fastest among home gardening segments.
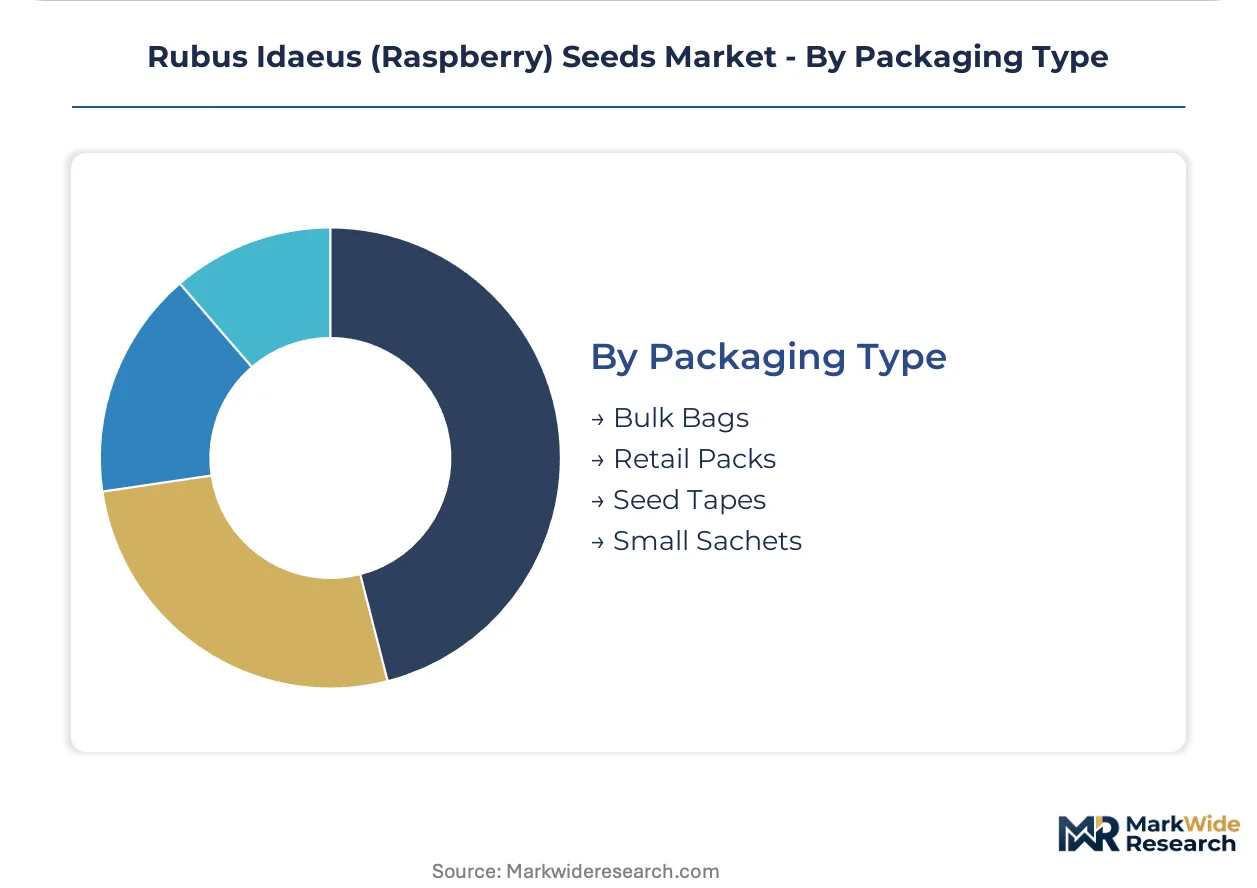
Packaging Type:
Packaging format aligns with buyer scale and handling infrastructure, from automated planting equipment compatibility to small-scale hand-sowing convenience.
- Bulk Bags:Commercial berry operations in Poland's Mazovia region receive tonnage shipments with moisture-controlled storage specifications for mechanical planting equipment compatibility.
- Retail Packs:Branded consumer packaging for garden center and online channels carries dual USDA-EU Organic certification badges required for German and French retail placement.
- Seed Tapes:Pre-spaced embedding in biodegradable strips targets home gardeners seeking precise row planting without thinning labor.
- Small Sachets:Single-variety trial packs serve research institutions and specialty crop breeders evaluating germination performance before volume commitment.
Bulk bags lead in volume throughput. Retail packs show the strongest growth momentum through e-commerce expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Mazovia region anchors seed oil extraction capacity for cosmetic-grade supply chains, while backward-integrated berry sourcing clusters concentrate margin capture among operators with certified organic handling infrastructure. Regulatory divergence between USDA Organic and EU REACH frameworks fragments procurement patterns across Atlantic trade routes.
Poland
Polish processors in the Mazovia region deploy cold-press extraction technology to preserve linoleic acid profiles above 52% for premium skincare formulations. EU REACH Annex XVII restrictions on solvent residues tighten maximum allowable hexane traces to 5 ppm, forcing mechanical retrofitting of extraction lines. Warsaw-based extraction facilities now dominate continental European supply for REACH-compliant documentation chains.
United States
USDA Organic certification governs seed access for natural cosmetics manufacturers targeting Pacific Coast home gardening demographics through subscription retail channels. FDA oversight of cosmetic ingredient safety influences formulation decisions by domestic end-users importing processed seed oils. Oregon and Washington cultivation zones source disease-resistant hybrid stock with standardized germination rates above 85%.
Serbia
Serbian berry growers supply seed byproduct streams to oil processors dependent on fresh raspberry pulp economics subject to weather-induced harvest variations. The country's national agricultural regulator enforces phytosanitary documentation for cross-border propagation material shipments into EU member states. Belgrade-region processors compete on conventional seed lines for price-sensitive Eastern European landscaping contractors.
Germany
German cosmetic manufacturers adopt supercritical CO2 extraction platforms integrated with inline antioxidant recovery systems to meet ECHA purity thresholds for dermal therapeutic claims. EFSA novel food approvals expand oil applications into functional food matrices. Bavarian and Baden-Württemberg formulators now require batch-specific residue documentation from Polish suppliers.
France
French retail channels in pharmacy and natural cosmetics segments specify dual USDA-EU Organic compliance as table stakes for shelf placement. ANSM and CNIL frameworks govern cosmetic ingredient traceability and data handling in supply chain documentation. Paris-region formulators concentrate procurement among three certified extraction facilities with backward-integrated berry sourcing.
Rubus Idaeus (Raspberry) Seeds Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction technology and certified organic handling. The market structures around three tiers: multinational oil processors with backward-integrated berry sourcing, mid-scale extraction specialists serving regional cosmetic formulators, and subscription-based direct-to-consumer seed distributors. Dominant competitive moves include capacity expansion in cold-press infrastructure and strategic partnerships bridging USDA-EU Organic dual certification requirements.
Within the backward-integrated tier, Aldivia SA exemplifies operators securing raw material consistency across seasonal harvests through captive berry sourcing. TC USA Inc. and Nutrativa Global occupy positions on the certification-breadth vector, with the former maintaining simultaneous USDA Organic and EU Organic compliance while the latter anchors North American distribution through direct relationships with natural cosmetics manufacturers. These three entities represent distinct archetypes: European extraction-integrated sourcing, transatlantic dual-certification compliance, and continent-specific distribution anchoring.
| Leading Market Players |
|---|
| Aldivia SA |
| Organic Pure Oil |
| TC USA Inc. |
| Nutrativa Global |
| Natural Sourcing |
| O&3 - The Oil Family |
| Camden-Grey Essential Oils |
| Leven Rose |
| Aromantic Ltd |
| Others |
Value Network & Pricing Analysis
Road freight corridors linking Poland's Mazovia region to German cosmetic formulators transmit cost volatility from fuel surcharges directly into seed oil price differentials, amplifying margin pressure for processors lacking backward-integrated berry sourcing while rewarding operators with captive cultivation networks.
Pricing Analysis
EU REACH Annex XVII dictates the pricing tier structure across cosmetic-grade raspberry seed oil supply chains. Three-tier pricing stratifies across certified organic cold-pressed, conventional mechanical, and solvent-extracted economy levels. Certification grade and extraction technology intensity drive price differentiation, with dual USDA-EU Organic compliance commanding substantial premia over single-certification alternatives. Cost compression in mid-tier conventional oils is intensifying because Polish processors retrofit cold-press lines to maintain market access. Commercial berry growers sourcing hybrid propagation stock demonstrate highest price sensitivity, while German pharmaceutical-grade formulators show least sensitivity due to therapeutic claim requirements.
Supply Chain Analysis
Phytosanitary documentation requirements for cross-border propagation material shipments function as de facto export controls limiting genetic flow from Serbian breeding programs into EU member states. Geographic supply concentration centers on Poland, Serbia, and Germany, with extraction capacity clustering disproportionately in Mazovia processing facilities. Raw material dependencies rest on fresh raspberry pulp byproduct streams, cold-press mechanical components, and supercritical CO2 system infrastructure. Single-source vulnerability pervades the three Polish extraction facilities dominating REACH-compliant documentation chains. Distribution runs through direct volume contracts for commercial farming, subscription platforms for home gardening, and horticultural cooperatives for landscaping applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Raspberry seed markets track cyclical recovery patterns tied to fresh berry harvest volumes, with weather-induced pulp supply fluctuations creating predictable input cost waves that disciplined operators exploit through captive sourcing.
For Market Incumbents: Pre-empt cranberry seed oil substitution threats by locking multi-year organic certification contracts with Mazovia berry cooperatives before harvest volatility spikes input costs. Expand cold-press capacity in backward-integrated Polish facilities to capture REACH-driven mechanical extraction demand. Prioritize dual USDA-EU Organic compliance investments to defend shelf placement in Nordic pharmacy chains where clean-label positioning commands premium allocation.
For New Entrants and Emerging Players: Brazilian and Chilean berry propagation markets offer white-space entry with minimal incumbent competition for disease-resistant hybrid genetics. Target subscription-based direct-to-consumer channels in US Pacific Coast states where automated seasonal replenishment models bypass entrenched horticultural distributor networks. Pursue phytosanitary clearance partnerships with EU-based breeders to establish regulatory credibility before volume scaling.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural conglomerates with underoptimized raspberry seed oil divisions lacking extraction technology integration. Long-term viability hinges on certification infrastructure and backward-integrated sourcing rather than commodity trading margins. Monitor EFSA novel food approval velocity as inflection indicator for functional food matrix expansion beyond cosmetic applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Berry Sourcing | Aldivia SA's captive cultivation model secures raw material consistency across seasonal harvest variations. |
| Cold-Press Capacity Expansion | Polish processors retrofit mechanical lines to meet EU REACH Annex XVII solvent residue thresholds. |
| Dual Certification Compliance Investment | TC USA Inc. maintains simultaneous USDA Organic and EU Organic access for transatlantic distribution. |
| Subscription Platform Development | Direct-to-consumer channels bypass wholesale markups with automated seasonal replenishment for home gardeners. |
| Supercritical CO2 Technology Adoption | German manufacturers integrate inline antioxidant recovery to meet ECHA purity thresholds for therapeutic claims. |
Research Methodology
Cross-validation between primary interviews with berry cultivation managers, cosmetic formulation chemists, seed oil extraction technicians, and horticultural distribution specialists anchors the qualitative findings against secondary validation from customs trade databases, EU REACH registration dossiers, EFSA novel food application records, and SEC filings of publicly traded agricultural processors. Bottom-up volume estimates from individual extraction facility capacities reconcile with top-down demand projections from cosmetic manufacturer procurement patterns.
Calibration against historical price spreads between organic and conventional seed tiers, extraction technology adoption curves, and certification timeline documentation refines the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use application, distribution channel format, and regional regulatory cluster. CAGRs derive from weighted average growth rates across these segments, with specific inputs from cold-press equipment deployment schedules and hybrid seed germination rate improvements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by supercritical CO2 technology providers or accelerated EFSA novel food approvals would shift outcomes. Material shifts in EU organic equivalence agreements or REACH solvent residue thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Dry Roasted Almonds Snack Market
Nuts and Seeds
United States Cashew Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Bambara Beans Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Europe Hazelnut Market