
 Betel Nuts Market | 2026-2036
Betel Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Betel Nuts Market Insights
REACH compliance is restructuring the cost-of-entry calculus for European-bound betel nut exporters, forcing upstream investment in residue testing and supply chain traceability. Hunan Wuzizui Industrial Group leverages captive farming networks in Hainan to sustain raw material security. PT. Ruby Privatindo anchors Indonesian export volumes through long-standing South Asian and Middle Eastern relationships. Hunan Binzhilang Industrial Group differentiates via pharmaceutical-grade processing infrastructure that meets stricter quality thresholds.
Betel nuts are the dried seeds of Areca catechu, typically containing 8-12% moisture and 8-15% polyphenol content after curing, used primarily for chewing preparations, traditional medicine extracts, and condiment manufacturing. Whole betel nuts occupy the largest volume share but carry thinner margins due to commodity-like trading dynamics. Betel nut powder competes fastest among food manufacturers seeking standardized dosing for packaged paan masala and gutkha formulations. Betel nut capsules within herbal medicine channels command premium pricing where CDSCO or equivalent national regulators enforce active compound verification.
India's FSSAI, Taiwan's FDA, and Indonesia's BPOM collectively shape market access through divergent aflatoxin limits, labeling mandates, and import licensing regimes that fragment compliance costs across origin countries. The EU's REACH framework and evolving EFSA hazard classifications threaten to exclude non-compliant suppliers from high-value European channels entirely. Stakeholders must monitor regulatory divergence between Asian consuming markets and Western import jurisdictions when allocating capital between traditional whole-nut trading and higher-margin processed formats.
Market Dynamics
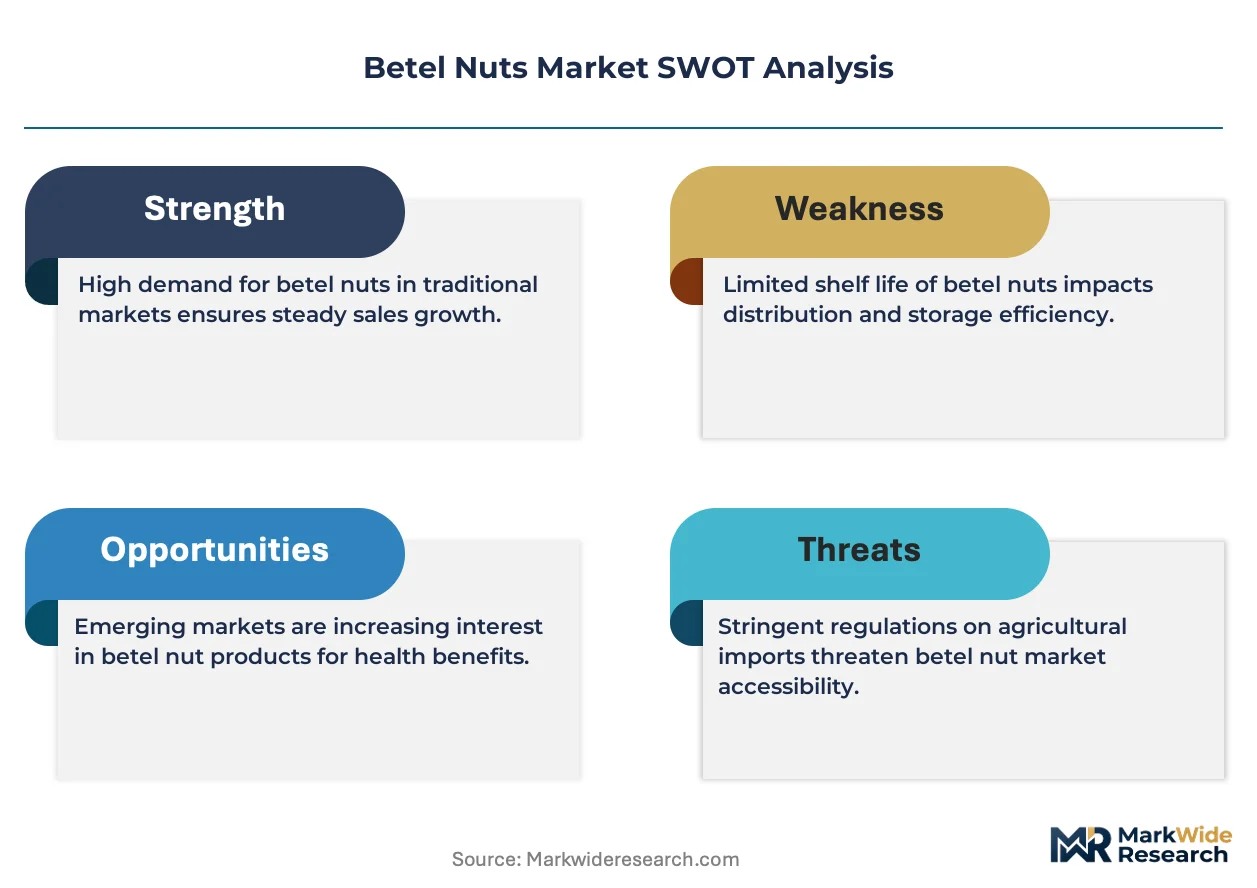
Taiwan's FDA aflatoxin tightening and India's FSSAI residue mandates are forcing processors to rebuild supply chains around certified testing infrastructure rather than traditional spot-market sourcing.
Growth Catalysts
- Chewing-preparation standardization:Packaged paan masala manufacturers in Maharashtra and Karnataka demand uniform polyphenol content, pulling investment into mechanized curing and moisture-controlled storage systems.
- REACH traceability mandates:European-bound exporters must document farm-level pesticide application, accelerating adoption of blockchain-linked batch tracking among Hainan and Indonesian suppliers.
- Herbal medicine channel expansion:CDSCO-style active-compound verification requirements in South Asian pharmaceutical markets create premium pricing tiers for capsule-grade processed formats.
Market Restraints
- Input cost volatility:Areca catechu harvest fluctuations in Taiwan's Pingtung County and India's coastal Karnataka concentrate raw material pricing power among contract farmers.
- Regulatory friction:Divergent aflatoxin limits between Taiwan's FDA, Indonesia's BPOM, and India's FSSAI fragment compliance costs and block economies of scale in multi-destination processing.
- Substitution threat:Synthetic nicotine pouches and tobacco-free oral products in urban Indian and Taiwanese retail channels erode chewing-preparation volume among younger demographics.
Strategic Opportunities
- Underpenetrated Middle Eastern markets:South Asian diaspora communities in Saudi Arabia and the UAE sustain demand for whole-nut and processed formats with limited local competition from certified suppliers.
- Regulatory tailwind:India's PLI scheme for food processing infrastructure subsidizes cold-chain and testing equipment that enables FSSAI-compliant export-grade production.
- Technology convergence:Near-infrared spectroscopy paired with mobile-based farm-data capture is electrifying quality verification speed at village-level collection points in Myanmar's Bago Region.
Industry Challenges
- Certification timeline compression:BPOM and FSSAI parallel-track approval requirements for novel extract formats stretch R&D-to-market cycles beyond traditional whole-nut trading payback periods.
- Skill scarcity in residue analytics:Taiwan's FDA-grade aflatoxin and pesticide testing protocols demand chromatography-trained technicians unavailable in Myanmar's emerging processing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Betel Nuts Market |
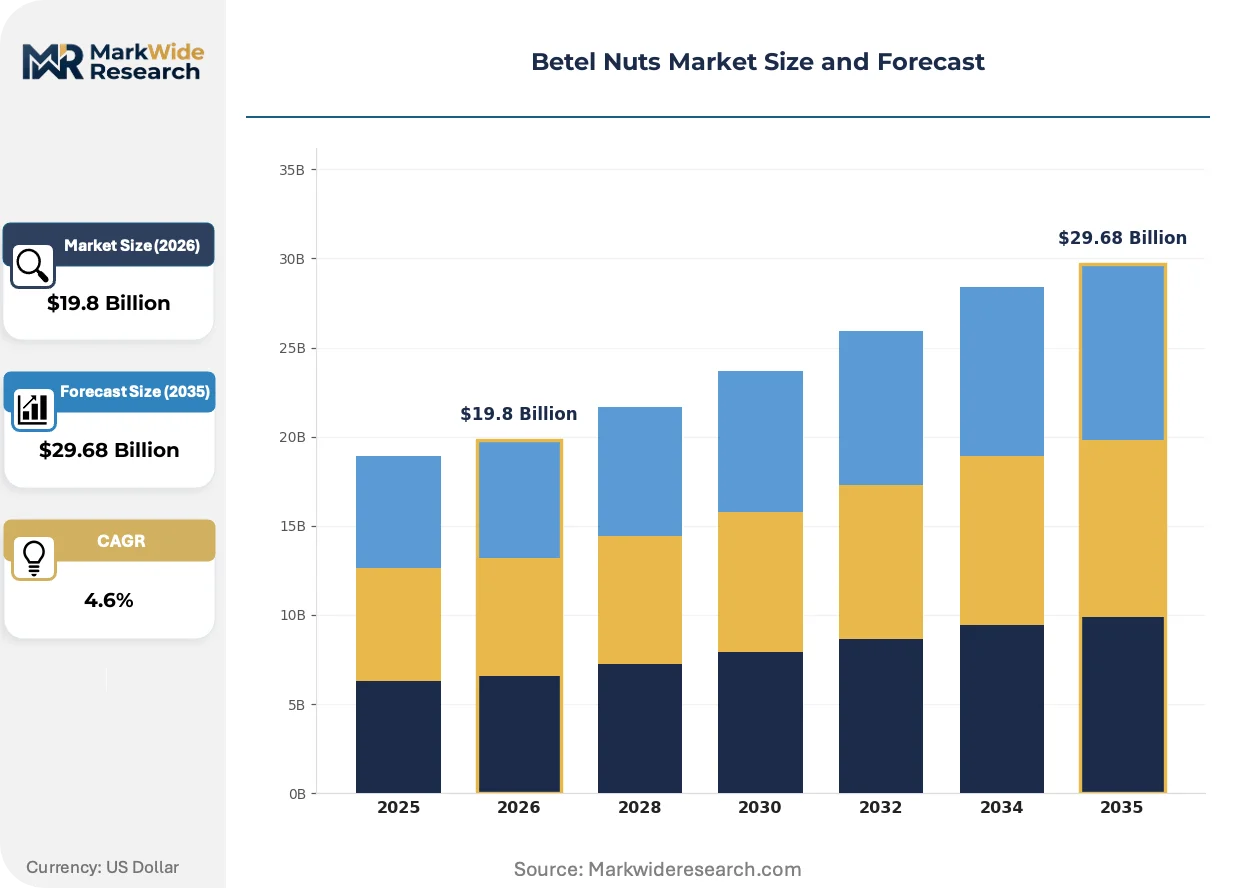
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Betel Nuts, Betel Nut Powder, Betel Nut Capsules, Betel Leaves End User: Retail Consumers, Food Manufacturers, Herbal Medicine, Chewing Tobacco Users Sales Channel: Online Retail, Specialty Stores, Supermarkets, Traditional Markets Regulatory Aspect: Export Regulations, Import Tariffs, Health Guidelines, Quality Standards |
| Companies Covered | Hunan Wuzizui Industrial Group, Hunan Binzhilang Industrial Group, KOUWEIWANG, PT. Ruby Privatindo, Xiangtan Xiangzuoji Food, Hunan Pangge Xinhong Industry, Changsha Cocoa Betel Nut House, Sri Vinayaka, Hainan Yali Agricultural Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Betel Nuts Market Trends and Innovations
Processing technology and regulatory verification systems are converging to separate export-capable suppliers from traditional traders. Three forces dominate this transition.
Near-infrared spectroscopy for real-time polyphenol and moisture assessment is electrifying quality-control throughput at Indian and Taiwanese processing facilities. Large paan masala manufacturers in Mumbai and Chennai deploy inline scanning to reject substandard batches before curing completion. This compression of testing latency is enabling just-in-time procurement contracts that bypass traditional auction-market intermediaries.
REACH documentation requirements and evolving EFSA hazard classifications are restructuring European market access. Exporters must now maintain farm-level pesticide logs and residue certificates across multi-year lookback periods. Smallholder-dependent supply chains in Indonesia's Sumatra and India's Kerala face exclusion pressure as compliance costs concentrate volume among integrated processors with captive laboratory capacity.
Urban retail channels in Taipei, Mumbai, and Yangon are fragmenting away from open-market nut sales toward pre-packaged, branded chewing preparations with ingredient disclosure. Younger consumers in these cities prioritize convenience and perceived safety over traditional bulk purchasing. This rotation compresses margins for commodity traders while expanding shelf-space access for FSSAI- and FDA-certified processors with packaged-format capabilities.
Betel Nuts Market Segmentation
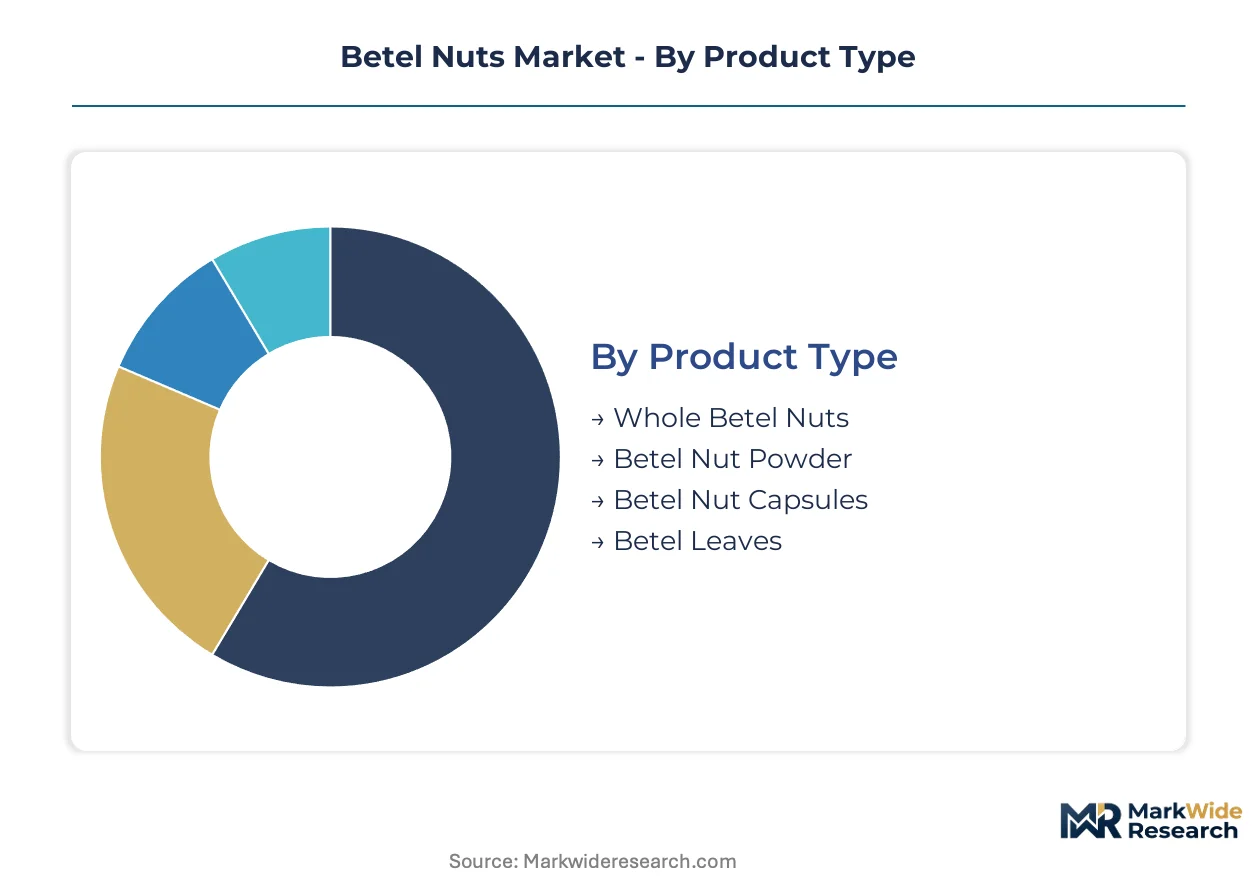
Processing infrastructure and regulatory compliance capabilities determine competitive position across betel nut product formats. Segmentation reveals where capital investment concentrates and which channels reward certification premiums.
Product Type:
Supply concentration in Hainan and Sumatra shapes raw material flows toward processors with captive curing infrastructure and residue testing capacity.
- Whole Betel Nuts:Dried Areca catechu seeds with 8-12% moisture content trade as commodity feedstock for downstream processors. Maharashtra and Karnataka paan masala manufacturers in India pull volume through auction markets, though FSSAI aflatoxin mandates are pushing procurement toward certified suppliers with laboratory documentation.
- Betel Nut Powder:Mechanically ground material with standardized polyphenol content serves packaged gutkha and paan masala producers seeking dosing precision. Food manufacturers in Mumbai and Chennai demand batch consistency that inline near-infrared spectroscopy now enables, compressing rejection rates at receiving docks.
- Betel Nut Capsules:Pharmaceutical-grade extracts for herbal medicine channels require CDSCO or equivalent national regulator verification of active compounds.
- Betel Leaves:Fresh wrapping material for traditional chewing preparations moves through distinct cold-chain logistics separate from dried nut distribution.
Whole betel nuts absorb the bulk of installed capacity; betel nut powder is expanding most quickly as mechanized curing investments accelerate.
End User:
Customer sophistication divides the market between price-sensitive traditional users and compliance-demanding institutional buyers.
- Retail Consumers:Individual purchasers in India, Taiwan, and Myanmar drive volume through traditional market channels. Younger demographics in Taipei and Yangon urban centers are shifting toward pre-packaged branded formats with ingredient disclosure, eroding open-market nut sales.
- Food Manufacturers:Packaged paan masala and gutkha producers in Maharashtra and Karnataka constitute the largest institutional demand pool. These manufacturers specify polyphenol ranges and moisture thresholds that mechanized curing systems must hit to secure supply contracts.
- Herbal Medicine:Extract producers serving South Asian pharmaceutical markets face CDSCO active-compound verification requirements.
- Chewing Tobacco Users:Traditional consumers of combined areca-tobacco preparations represent a contracting segment as synthetic nicotine pouches penetrate Indian and Taiwanese urban retail.
Food manufacturers command the steepest volume growth; herbal medicine channels sustain the highest margin premiums.
Sales Channel:
Distribution infrastructure investment separates certified processors from traditional traders in last-mile access.
- Online Retail:E-commerce platforms enable direct-to-consumer branded chewing preparations with FSSAI or FDA labeling compliance. Urban Indian and Taiwanese consumers prioritize convenience and perceived safety over bulk purchasing through this channel.
- Specialty Stores:Dedicated paan and gutkha retailers in Mumbai, Chennai, and Karachi maintain relationships with specific processor brands.
- Supermarkets:Modern retail chains in Taipei and Indian metro cities stock pre-packaged formats with full ingredient disclosure.
- Traditional Markets:Open-air auction systems in Karnataka and Hainan still handle the majority of whole-nut volume.
Traditional markets retain the largest transaction volume; online retail is climbing the fastest as urban consumer preferences fragment.
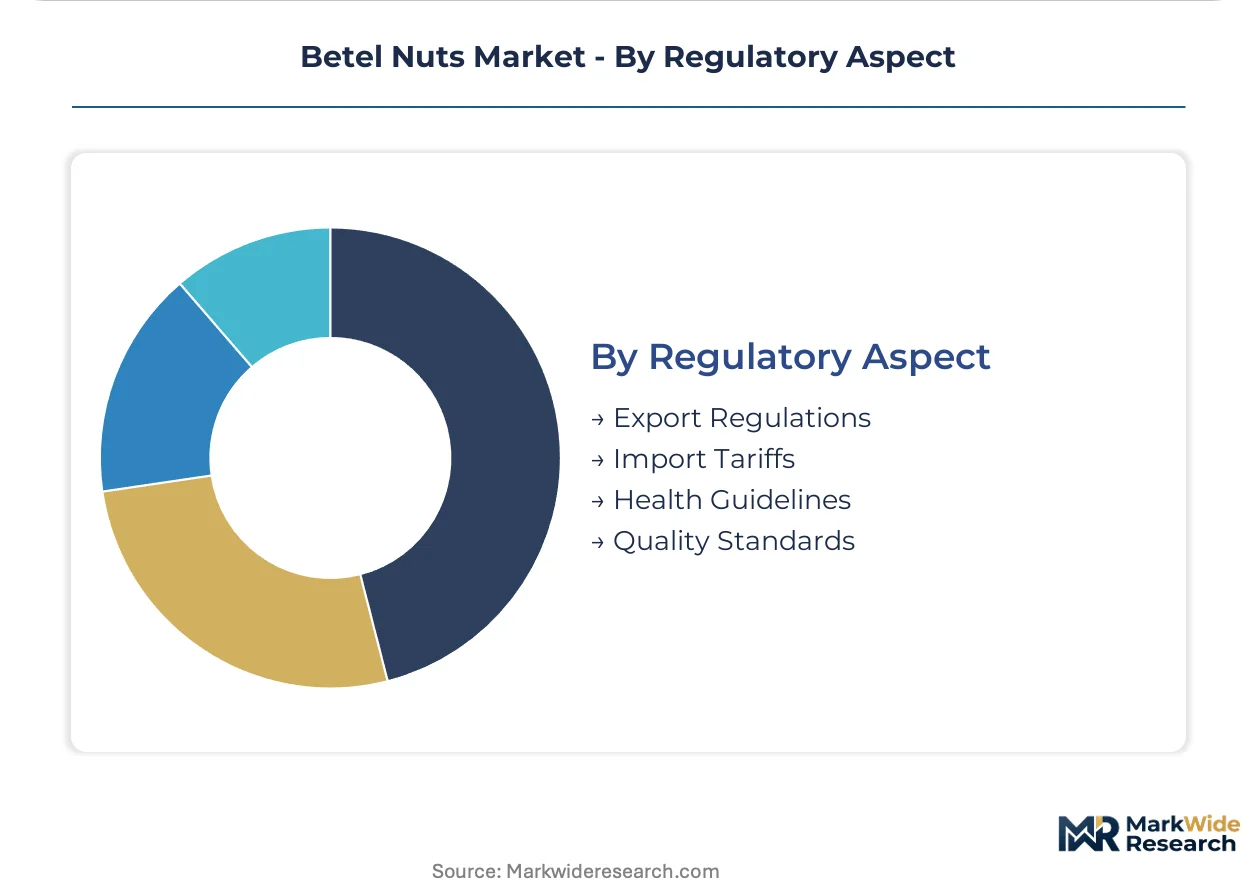
Regulatory Aspect:
Compliance cost fragmentation across destination markets determines which processors can sustain multi-territory operations.
- Export Regulations:REACH documentation requirements for European-bound shipments mandate farm-level pesticide logs across multi-year lookback periods. Indonesian and Hainan suppliers with blockchain-linked batch tracking are securing access that smallholder-dependent chains cannot match.
- Import Tariffs:Duty structures between South Asian and Middle Eastern markets influence routing decisions for Indonesian and Indian exporters.
- Health Guidelines:Taiwan's FDA aflatoxin tightening and India's FSSAI residue mandates are forcing parallel investment in chromatography infrastructure.
- Quality Standards:Divergent specifications between BPOM, FSSAI, and FDA fragment testing protocols and block economies of scale.
Health guidelines absorb the bulk of processor compliance spending; export regulations are expanding most quickly as European channels open to documented supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India, Taiwan, and Myanmar absorb the majority of chewing-preparation consumption, while Indonesia and China supply raw material flows through distinct processing clusters. Regulatory divergence between Asian consuming markets and Western import jurisdictions fragments compliance investment across origin countries.
India
Retail consumers in Maharashtra and Karnataka drive institutional procurement from paan masala manufacturers. FSSAI residue mandates and aflatoxin tightening force processors to abandon spot-market sourcing for certified laboratory documentation. Mumbai and Chennai mechanized curing facilities now deploy near-infrared spectroscopy to meet food manufacturer polyphenol specifications.
Taiwan
Traditional chewing preparation remains culturally entrenched among older demographics while younger consumers fragment toward pre-packaged formats. FDA aflatoxin limits and labeling mandates compress margins for uncertified traders. Pingtung County harvest fluctuations concentrate raw material pricing power among contract farmers with multi-year processor relationships.
Indonesia
Sumatra and Hainan-oriented supply chains face REACH documentation pressure for European-bound shipments. BPOM quality standards fragment testing protocols from FSSAI and FDA requirements, blocking economies of scale in multi-destination processing. PT. Ruby Privatindo anchors export volumes through long-standing South Asian and Middle Eastern relationships.
Myanmar
Bago Region village-level collection points adopt mobile-based farm-data capture paired with spectroscopy verification. Central bank trade financing constraints limit processor working capital for chromatography infrastructure investment. Yangon urban retail channels fragment away from open-market sales toward branded chewing preparations with ingredient disclosure.
China
Hunan province processors leverage Hainan captive farming networks for raw material security. NMPA-style pharmaceutical-grade standards for extract formats create premium pricing tiers separate from commodity whole-nut trading. Changsha and Xiangtan industrial clusters concentrate mechanized curing capacity serving domestic packaged paan masala demand.
Betel Nuts Market Competitive Landscape
Hainan and Hunan province producers anchor one tier; Indonesian specialists hold export-oriented relationships with South Asian and Middle Eastern buyers. The vendor base separates between integrated processors with captive laboratory capacity and smallholder-dependent traders facing REACH exclusion pressure. Three archetypes dominate: mechanized curing operators, pharmaceutical-grade extract specialists, and traditional whole-nut commodity traders. Competitive moves concentrate on backward integration into farming networks and blockchain-linked batch tracking for European documentation compliance.
Within the integrated processor tier, Hunan Wuzizui Industrial Group and Hunan Binzhilang Industrial Group exemplify Chinese operators with Hainan supply network control. PT. Ruby Privatindo occupies a position representing Indonesian export specialists serving diaspora demand in Saudi Arabia and the UAE. Xiangtan Xiangzuoji Food sits within the mechanized curing archetype serving domestic food manufacturer procurement.
| Leading Market Players |
|---|
| Hunan Wuzizui Industrial Group |
| Hunan Binzhilang Industrial Group |
| KOUWEIWANG |
| PT. Ruby Privatindo |
| Xiangtan Xiangzuoji Food |
| Hunan Pangge Xinhong Industry |
| Changsha Cocoa Betel Nut House |
| Sri Vinayaka |
| Hainan Yali Agricultural Development |
| Others |
Pricing and Supply Chain Analysis
Chromatography-trained technician scarcity in Myanmar's Bago Region widens labor-cost differentials between certified processors and traditional traders, stretching pricing-tier spreads from commodity whole-nut auction grades to pharmaceutical-grade extract premiums.
Pricing Analysis
Volume concentrates in whole betel nut commodity trading while margins accrue to processed formats. Three-tier pricing structure across pharmaceutical-grade, food-manufacturer-certified, and traditional auction grades separates CDSCO-verified capsule producers from FSSAI-compliant powder suppliers and uncertified whole-nut traders. Price differentiation hinges on residue testing documentation and polyphenol standardization. Margins are tightening for uncertified traders as Taiwan's FDA and India's FSSAI mandates force laboratory investment. Retail consumers in traditional markets exhibit highest price sensitivity; herbal medicine channels show least.
Supply Chain Analysis
Single-source vulnerability sits with Hainan and Sumatra as dominant raw material origins for global betel nut flows. Supply draws from Areca catechu farming networks in China's Hainan province, Indonesia's Sumatra, and India's coastal Karnataka. Key inputs span cured seeds, moisture-controlled storage infrastructure, and chromatography testing equipment. Regulatory restriction risk intensifies as REACH documentation requirements and divergent aflatoxin limits between Taiwan's FDA, Indonesia's BPOM, and India's FSSAI fragment compliance pathways. Distribution runs through auction markets in Karnataka and Hainan for whole nuts, while certified processors bypass intermediaries via direct contracts with paan masala manufacturers in Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The betel nut market occupies a technology-transition phase where near-infrared spectroscopy and blockchain-linked batch tracking displace traditional visual grading and paper-based provenance records.
For Market Incumbents: Acquire chromatography laboratory capacity and certified testing infrastructure to defend against synthetic nicotine pouch substitution eroding chewing-preparation volumes among younger demographics in Taipei and Mumbai. Pursue backward integration into Hainan or Sumatra farming networks to secure raw material security and REACH-compliant pesticide documentation for European-bound shipments. For New Entrants and Emerging Players: Begin with underpenetrated Middle Eastern markets where South Asian diaspora communities in Saudi Arabia and the UAE sustain demand with limited certified supplier competition. Target pharmaceutical-grade extract formats for CDSCO-regulated herbal medicine channels where active-compound verification commands premium pricing. Deploy mobile-based farm-data capture paired with spectroscopy verification as a go-to-market differentiator. For Investors and Strategic Acquirers: Re-rating potential sits with integrated processors possessing captive laboratory capacity given India's PLI scheme subsidizing cold-chain and testing equipment investment. Long-term viability favors operators with multi-territory compliance capabilities spanning FSSAI, FDA, and BPOM requirements. Watch for synthetic nicotine pouch penetration rates in Indian and Taiwanese urban retail as an inflection indicator for traditional chewing-preparation demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Certification Investment | Chromatography infrastructure enables FSSAI and FDA compliance for export-grade production. |
| Backward Integration into Farming | Captive Hainan supply networks secure raw material security and REACH pesticide documentation. |
| Blockchain Batch Tracking Deployment | Farm-level data capture satisfies European documentation requirements for residue traceability. |
| Mechanized Curing Capacity Expansion | Near-infrared spectroscopy integration meets food manufacturer polyphenol specifications. |
| Pharmaceutical-Grade Extract Development | CDSCO active-compound verification unlocks premium pricing in South Asian herbal medicine channels. |
Research Methodology
Document review covered customs and trade flow databases, regulatory filings with Taiwan's FDA and India's FSSAI, and industry association reports, complemented by interviews with processing facility managers, paan masala manufacturer procurement leads, agricultural cooperative representatives, and chromatography equipment suppliers. Secondary validation drew from BPOM quality standards documentation, REACH guidance publications, and customs records. Bottom-up volume estimates from country-level consumption patterns were triangulated against top-down supply-side capacity assessments across Hainan, Sumatra, and Karnataka processing clusters.
Segment-level projections across product type, end user, sales channel, and regulatory compliance tier were generated through the analysis window. The modeling framework incorporated mechanized curing adoption rates, residue testing infrastructure deployment timelines, and synthetic nicotine substitution elasticities in urban Indian and Taiwanese retail channels. CAGRs were derived from regression analysis of historical volume trends against regulatory mandate implementation schedules and technology adoption curves.
Underlying measurement precision varies by segment; pharmaceutical-grade capsule formats carry tighter precision than traditional whole-nut auction volumes due to consolidated producer reporting. Forecasts reflect assumptions around regulatory enforcement intensity, technology adoption rates, and substitution dynamics that could shift materially with unexpected policy changes or breakthrough product formulations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nuts and Nutmeals Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Tree Nuts Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
China Almond Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Dry Roasted Almonds Snack Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
Pistachios Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Cashew Roasting Machine Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Carob Extract Market