
 Peanuts Market | 2026-2036
Peanuts Market Size, Share, and Industry Trends Forecast 2026-2036
Peanuts Market Analysis
Single-serve pouch packaging is shifting how retail consumers access peanuts, unbundling bulk formats into portion-controlled options that fit convenience-oriented lifestyles. Olam International leverages its integrated origination network across African and South American growing regions to sustain supply consistency for food manufacturers. Hampton Farms anchors its position through direct farm-to-retail roasting operations in the southeastern United States. J.M. Smucker Company differentiates through branded peanut butter portfolios that command shelf space in supermarkets.
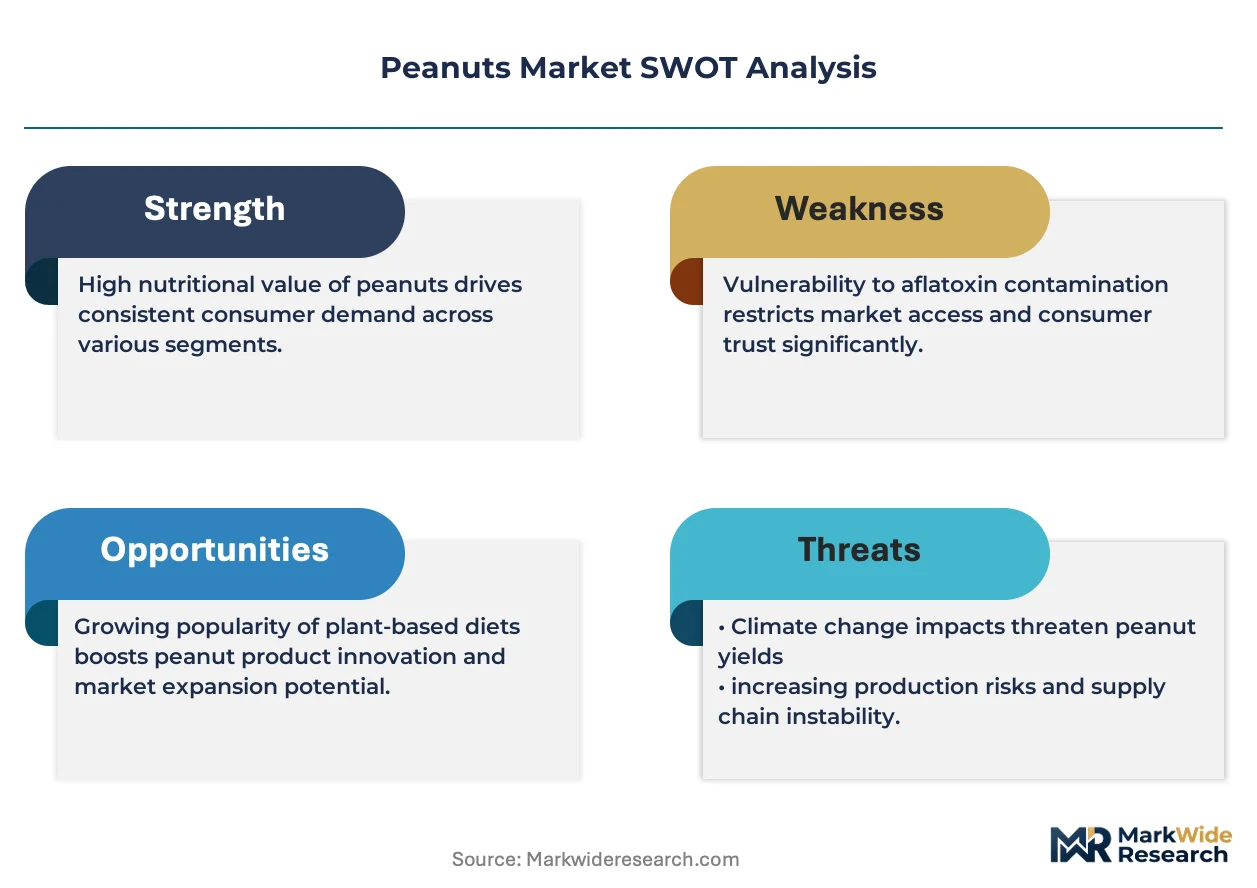
Peanuts are leguminous oilseeds containing approximately 48-50% oil and 25-28% protein by weight, with commercial grades defined by runner, Virginia, Spanish, and Valencia botanical varieties that determine shell size, kernel shape, and preferred processing application. Raw peanuts and peanut butter together occupy the dominant value positions in product type segmentation, with peanut butter capturing recurring household purchase frequency and raw peanuts supplying industrial oil crushing and snack roasting channels. Pouch packaging is expanding fastest among format options, reflecting on-the-go consumption patterns in online retail and convenience-oriented sales channels.
FDA enforces aflatoxin action limits under the Food Safety Modernization Act, while USDA grading standards classify peanut lots by kernel size, damage percentage, and foreign material content that directly determine export eligibility and processor pricing tiers. India's FSSAI has tightened maximum residue limits for pesticide contaminants in imported peanut consignments, affecting sourcing decisions for Indian oil millers and snack manufacturers. Stakeholders must monitor how evolving mycotoxin regulations across multiple jurisdictions reshape acceptable supply origins and testing cost structures.
Market Dynamics
Plant-based protein demand is restructuring peanut procurement patterns, forcing snack manufacturers to secure dedicated supply contracts ahead of crushing season while oil millers compete for the same kernel grades.
Growth Catalysts
- FSMA aflatoxin protocols:FDA's tightened testing mandates under the Food Safety Modernization Act are filtering out smaller non-compliant suppliers, concentrating volume among certified handlers who can absorb laboratory verification costs.
- Runner variety dominance:Mechanical harvesting compatibility and uniform kernel sizing make runner peanuts the preferred input for automated peanut butter production lines serving retail and foodservice channels.
- India's dual consumption pattern:Rural households sustain direct food use while urban processing clusters expand oil extraction capacity, creating parallel demand streams that stabilize import requirements.
Market Restraints
- Input cost volatility:Fertilizer nitrogen prices fluctuate with natural gas benchmarks, compressing margins for Georgia and Alabama growers who lack forward-contracting discipline.
- Supply concentration risk:West African origination clusters in Senegal and Mali face intermittent port congestion and political risk that disrupts just-in-time delivery schedules for European crushers.
- Substitution pressure:Sunflower seed oil and rapeseed oil compete for frying and blending applications where peanut oil premium pricing cannot be justified.
Strategic Opportunities
- Single-serve pouch expansion:Convenience retailers in Brazil and Mexico are allocating incremental shelf space to portion-controlled nut packs, bypassing traditional bulk-bin distribution.
- FSSAI residue limit alignment:Indian oil millers who pre-certify shipments against Food Safety and Standards Authority pesticide thresholds gain preferential access to premium-priced crushing contracts.
- Blockchain provenance tracking:Integration of distributed ledger verification with mobile-based farm data collection is enabling origin-transparent supply chains that command retail loyalty.
Industry Challenges
- Skilled agronomist shortage:Integrated pest management expertise for aflatoxin prevention remains concentrated among aging extension agents in Georgia and Texas production belts.
- Legacy roasting equipment retrofit costs:Smaller processors face capital constraints upgrading to continuous-flow systems capable of meeting real-time moisture and color specification monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peanuts Market |
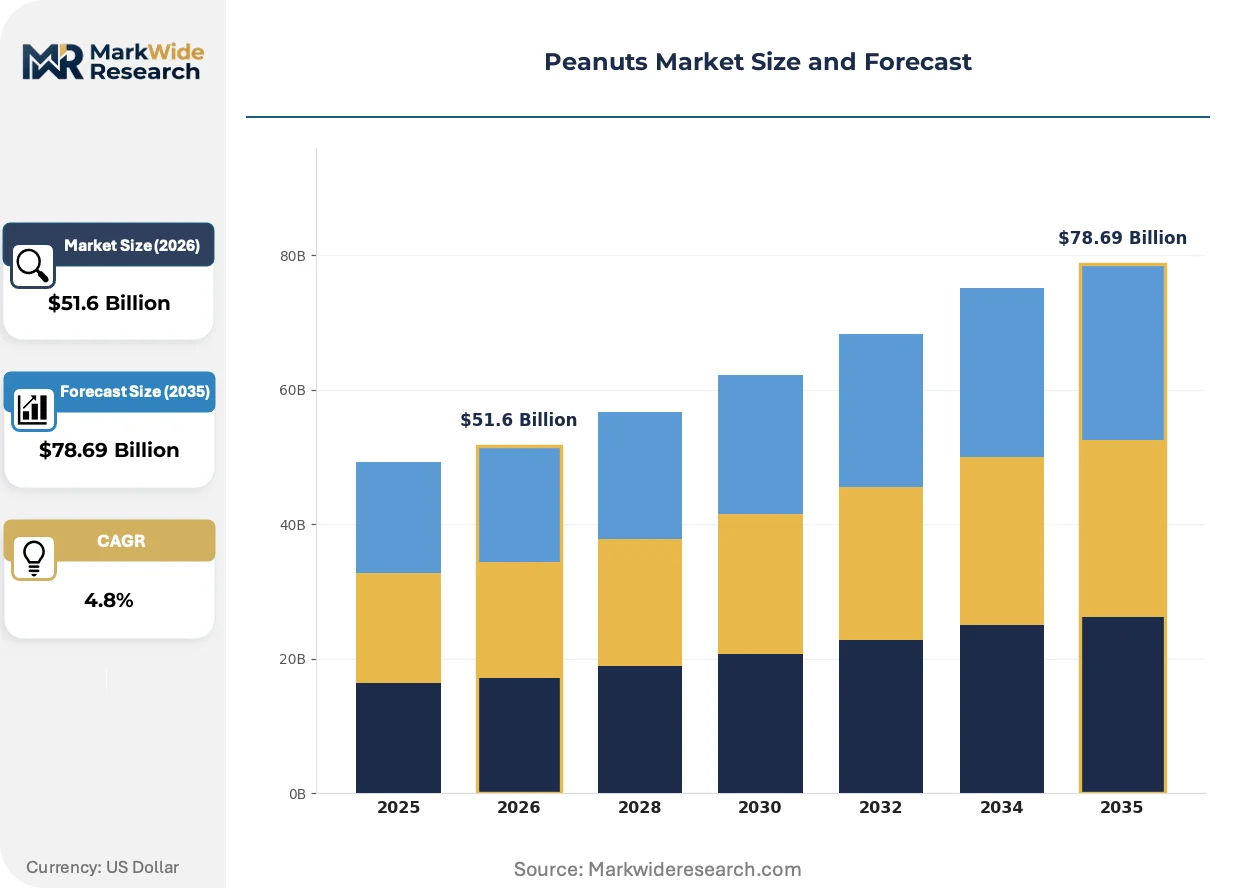
| Market Size in 2026 | $51.6 Billion |
| Market Size in 2035 | $78.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Peanuts, Roasted Peanuts, Peanut Butter, Peanut Flour Packaging Type: Bags, Jars, Tubs, Pouches Sales Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale End User: Food Manufacturers, Snack Producers, Restaurants, Retail Consumers |
| Companies Covered | Hormel Foods Corporation, J.M. Smucker Company, Olam International, Golden Peanut and Tree Nuts, The Hershey Company, Archer Daniels Midland Company, The Kraft Heinz Company, Hampton Farms, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peanuts Market Emerging Trajectories
Digital traceability infrastructure is displacing paper-based lot documentation, while processing automation compresses labor dependence and packaging formats fragment to match occasion-based consumption moments.
Near-infrared spectroscopy for real-time aflatoxin detection is decentralizing quality control away from centralized laboratory testing. Mid-sized shelling operations in Argentina and South Africa are adopting handheld devices that deliver immediate accept-reject decisions at receiving docks. This compression of testing turnaround is enabling direct farm-processor contracting that bypasses traditional cooperative aggregation.
EU REACH chemical registration requirements are tightening solvent residue limits for peanut protein isolates used in plant-based meat analogues. Food manufacturers reformulating with enzymatic extraction methods avoid classification complexities that delay new ingredient approvals. German and Dutch ingredient houses are accelerating clean-label positioning to preempt regulatory friction.
Online grocery platforms are fragmenting traditional wholesale procurement patterns for branded peanut butter. Direct-to-pantry subscription models in the United Kingdom and Australia capture recurring household purchases that supermarkets previously controlled. This channel rotation is forcing legacy distributors to unbundle case-lot minimums and adopt flexible fulfillment infrastructure.
Peanuts Market Segmentation
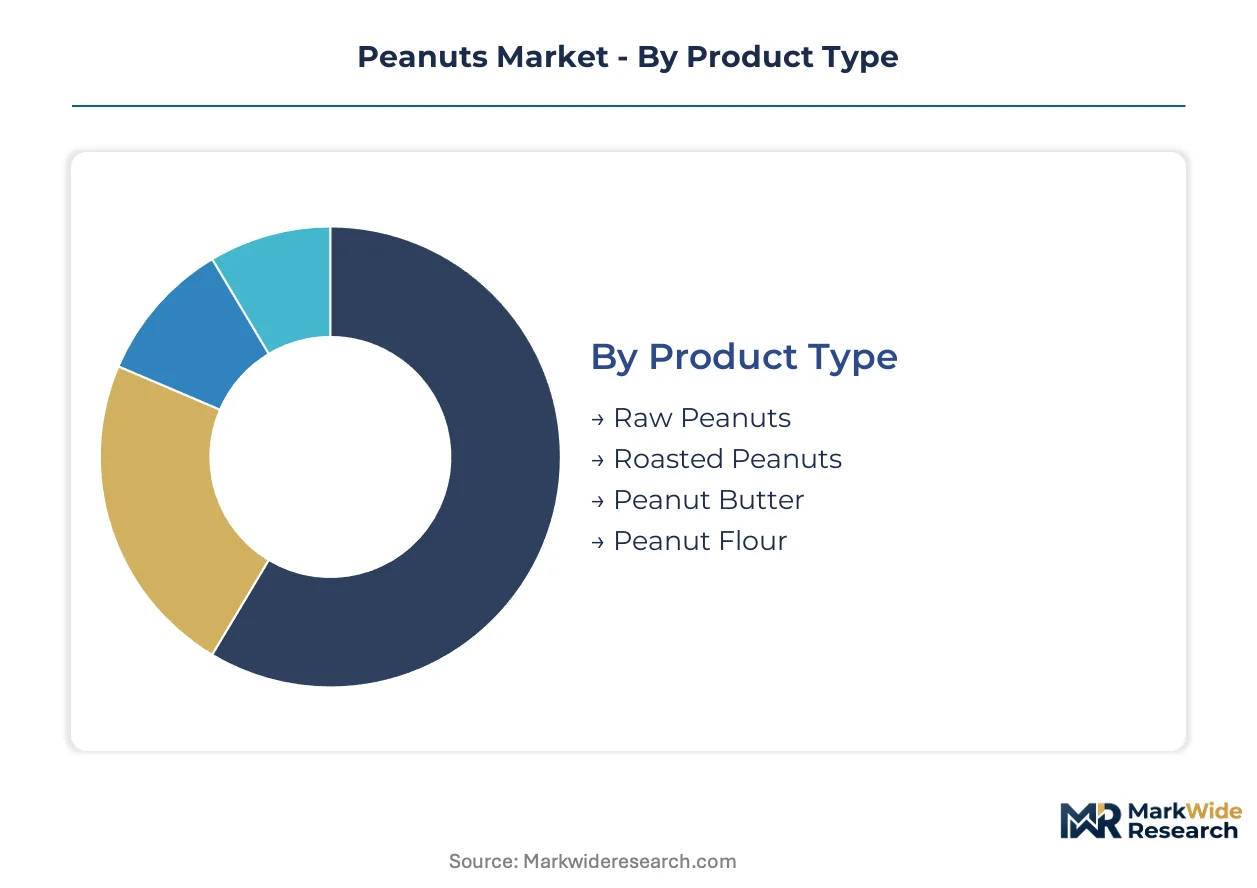
Peanut processors allocate capital across four distinct value chain positions. Each segment demands specialized handling infrastructure, from aflatoxin screening for raw inputs to emulsion stability control for finished spreads.
Product Type:
Raw peanuts operate as standalone commodity inputs while processed formats embed into downstream manufacturing systems.
- Raw Peanuts:Unprocessed kernels retain 48-50% oil content and 25-28% protein by weight, graded by runner, Virginia, Spanish, and Valencia varieties. Oil millers in Gujarat and snack roasters in Georgia compete for runner-grade supply during harvest windows, with crushing demand anchoring volume placements.
- Peanut Butter:Finely ground roasted kernels emulsified with stabilizers deliver shelf-stable spread formats. Household purchase frequency in US supermarkets sustains branded portfolio economics, while foodservice pails supply bakery and confectionery channels.
- Roasted Peanuts:Dry-roasted or oil-roasted kernels packaged for immediate consumption.
- Peanut Flour:Defatted or partially defatted meal fractions serving protein fortification applications.
Volume placements concentrate in Raw Peanuts; the faster expansion belongs to Peanut Butter.
Packaging Type:
Format selection tracks channel economics, with cost tiers separating institutional bulk from retail-ready units.
- Pouches:Flexible single-serve and multi-serve formats with barrier film laminations. Brazilian and Mexican convenience retailers allocate incremental shelf space to portion-controlled packs, displacing traditional bulk-bin distribution with grab-and-go accessibility.
- Jars:Rigid glass or PET containers with wide-mouth closures for spread applications. US and UK supermarkets anchor household replenishment cycles, with direct-to-pantry subscription models fragmenting traditional wholesale procurement patterns.
- Bags:Woven polypropylene or paper sacks for industrial and bulk retail distribution.
- Tubs:Rigid plastic containers for foodservice and institutional volumes.
Volume placements concentrate in Jars; Pouches are climbing the fastest among format options.
Sales Channel:
Channel selection reflects customer type density, with procurement patterns diverging between recurring household demand and project-based industrial buying.
- Supermarkets:Branded and private-label shelf placement commanding impulse and planned purchase traffic. UK and Australian online grocery platforms fragment traditional wholesale dominance, forcing legacy distributors toward flexible fulfillment infrastructure.
- Online Retail:Direct-to-consumer and platform-mediated fulfillment with unbundled case-lot minimums. Subscription models capture recurring pantry replenishment that physical retail previously controlled, compressing distributor margin capture.
- Specialty Stores:Curated assortments targeting health-conscious and premium-positioned buyers.
- Wholesale:Case-lot and bulk distribution to foodservice, manufacturing, and institutional accounts.
Volume placements concentrate in Supermarkets; Online Retail is gaining share fastest among channel options.
End User:
User categories separate embedded industrial demand from standalone consumption, with specification intensity varying by application.
- Food Manufacturers:Ingredient procurement for confectionery, bakery, and sauce formulations. German and Dutch ingredient houses accelerate clean-label peanut protein isolates to preempt EU REACH solvent residue complications in plant-based meat analogues.
- Snack Producers:Roasted and flavored kernel processing for packaged retail distribution. Dedicated supply contracts ahead of crushing season secure preferred runner grades as plant-based protein demand broadens procurement competition.
- Restaurants:Foodservice preparation for direct plate and menu incorporation.
- Retail Consumers:Household purchase for home preparation and direct consumption.
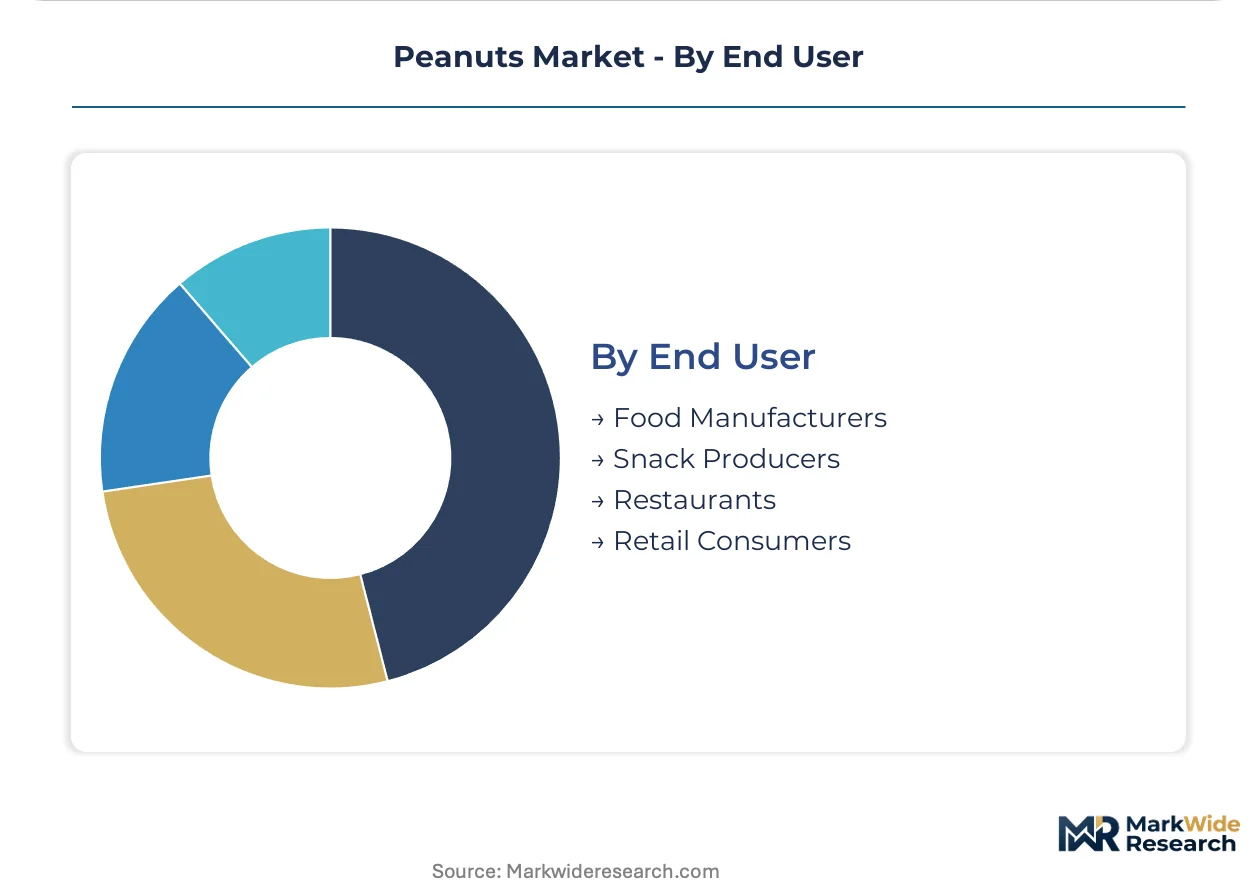
Volume placements concentrate in Food Manufacturers; Snack Producers show the steepest expansion trajectory among user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Andhra Pradesh concentrate Indian peanut processing capacity through tax incentives on oil extraction infrastructure. These zones attract integrated millers who combine crushing operations with solvent extraction units.
United States
Georgia and Alabama growers supply runner-grade kernels to automated peanut butter production lines. FDA's Food Safety Modernization Act mandates laboratory aflatoxin verification that filters smaller handlers from certified supply chains. The Southeast roasting belt around Suffolk, Virginia anchors Hampton Farms' direct farm-to-retail operations.
India
Rural households sustain direct food consumption while Gujarat's oil millers expand crushing capacity for export-oriented refined peanut oil. FSSAI tightened maximum residue limits for pesticide contaminants in imported consignments during 2023. The Saurashtra peninsula cluster processes Gujarat's domestic harvest while sourcing African shipments through Mundra port.
China
Shandong province's crushing mills compete for runner-grade imports from Senegal and Argentina. SAMR enforces national food safety standards on mycotoxin thresholds that exceed baseline CODEX levels. The Qingdao port logistics hub receives West African shipments for redistribution to interior oil processors.
Brazil
São Paulo-based snack manufacturers drive pouch-format demand for portion-controlled retail distribution. ANVISA regulates aflatoxin limits in peanut products for domestic consumption and Mercosur export eligibility. The Ribeirão Preto agricultural corridor concentrates shelling operations that supply both local roasters and Argentine oil mills.
Argentina
Córdoba province's mid-sized shellers adopt handheld near-infrared devices for dockside aflatoxin screening. The national agricultural regulator SENASA certifies export lots for EU and Indian destinations. The General Deheza crushing complex processes runner grades into protein isolates for European plant-based meat manufacturers.
Peanuts Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the peanut value chain. The market structure concentrates volume among integrated agribusinesses with origination networks spanning multiple hemispheres, while regional roasters defend niche positions through direct farm relationships. Three archetypes dominate: global traders with African and South American sourcing infrastructure, branded consumer goods houses with supermarket shelf-space command, and farm-integrated processors with captive supply control. Competitive moves center on forward contracting for preferred runner grades and packaging format innovation for convenience retail channels.
Within the global trading tier, Olam International exemplifies integrated origination capabilities across Senegalese and Argentine growing regions. J.M. Smucker Company occupies a position among branded portfolio houses commanding recurring household purchase frequency in North American supermarkets. Hampton Farms anchors the farm-integrated processor archetype through direct southeastern United States roasting operations that bypass cooperative aggregation layers.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| J.M. Smucker Company |
| Olam International |
| Golden Peanut and Tree Nuts |
| The Hershey Company |
| Archer Daniels Midland Company |
| The Kraft Heinz Company |
| Hampton Farms |
| Cargill |
| Others |
Supply Flow & Price Mechanics
Family-owned shelling operations across Georgia and Alabama anchor runner-grade supply, linking farm-gate pricing discipline to crushing-season contracting rhythms that stabilize processor margins against fertilizer nitrogen volatility.
Pricing Analysis
Margin tightening in food-grade runner segments reflects FSMA laboratory verification costs that filter smaller handlers from certified supply chains. Contract-based long-term offtake dominates, with price differentiation hinging on aflatoxin certification tier and volume scale. Cost-down pressure on Spanish-grade kernels accelerates because Indian oil millers pre-certify against FSSAI residue limits to secure premium crushing contracts. Snack producers show least price sensitivity due to dedicated supply contracts; bulk oil crushers face highest sensitivity to spot kernel differentials.
Supply Chain Analysis
Freight cost spikes through Mundra and Qingdao ports reshape origination economics for West African shipments bound for Gujarat and Shandong millers. Supply concentrates in Senegal, Argentina, and the United States, with raw material flows drawing from fertilizer nitrogen, agricultural labor pools, and moisture-controlled storage infrastructure. Single-source vulnerability runs through Senegalese port congestion that disrupts just-in-time delivery schedules. Distribution runs through integrated agribusinesses with multi-hemisphere origination networks, bypassing traditional cooperative aggregation layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into farm-gate origination and automated roasting infrastructure constitutes the defining competitive race, as players pursue captive supply control to secure preferred runner grades ahead of crushing season.
For Market Incumbents: Cement supply security through forward contracting for African runner grades ahead of harvest windows, countering Olam International's integrated origination network. Invest in continuous-flow roasting systems capable of real-time moisture monitoring, defending against smaller processors who face capital constraints on legacy equipment retrofits. Prioritize FSSAI pre-certification infrastructure to maintain premium access to Indian oil milling contracts.
For New Entrants and Emerging Players: Blockchain-enabled provenance tracking offers a technology-first wedge, commanding retail loyalty through origin-transparent supply chains that bypass established cooperative aggregation. Target Brazilian and Mexican convenience retailers with single-serve pouch formats, exploiting shelf-space reallocation away from bulk-bin distribution. Deploy direct-to-pantry subscription models in UK and Australian markets, capturing recurring household purchases through unbundled case-lot minimums.
For Investors and Strategic Acquirers: FDA enforcement actions against non-compliant aflatoxin handlers are the leading indicator that certified supply chains will concentrate volume among laboratory-capable processors, compressing exit multiples for smaller shellers. Mid-sized Argentine and South African operations with handheld near-infrared screening capabilities represent the optimal acquisition archetype. Watch for Indian FSSAI residue limit expansions to additional pesticide categories as the signal for regulatory-driven supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Origination | Captive runner-grade supply secures crushing-season contracting priority against Olam's African network. |
| Continuous-Flow Roasting System Deployment | Real-time moisture monitoring meets FSMA protocols that filter smaller handlers from certified chains. |
| FSSAI Pre-Certification Infrastructure | Indian residue limit alignment unlocks premium-priced oil milling contracts in Gujarat processing clusters. |
| Blockchain Provenance Tracking Integration | Distributed ledger verification commands retail loyalty through farm-level transparency in subscription channels. |
| Single-Serve Pouch Format Expansion | Brazilian convenience retailers allocate incremental shelf space, displacing traditional bulk-bin distribution. |
Methodological Framework
Document review covered USDA grading standards, FDA FSMA enforcement records, FSSAI regulatory filings, and trade flow databases, complemented by interviews with peanut shelling operation managers, oil mill procurement leads, snack manufacturer R&D directors, and agricultural extension agents. Secondary validation drew from customs records, cooperative aggregation reports, and food safety laboratory certification data. Bottom-up volume modeling triangulated against top-down value chain assessments across runner, Virginia, Spanish, and Valencia variety segments.
Output metrics span product type, packaging format, sales channel, and end-user category across the projection horizon. CAGRs derive from harvest volume trends, crushing capacity expansion rates, and retail channel shift velocities. Model inputs incorporate aflatoxin testing cost structures, fertilizer nitrogen price benchmarks, and convenience retail shelf-space allocation patterns specific to Brazilian and Mexican distribution.
Several conditions sit outside the modeled scope, including political risk disruptions in West African origination zones, extreme weather impacts on Georgia and Alabama yields, and unannounced FSSAI residue limit expansions. Forecasts reflect assumptions about regulatory enforcement continuity and processor capital availability. Stakeholders should weight assumptions against their own operating context and origination network exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
China Fox Nuts Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Fat Free Peanut Butter Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Almond Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
North America Hazelnut Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Saudi Arabia Nuts Market