
 Global Online Travel Market | 2026-2036
Global Online Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Travel Market Outlook
GDPR enforcement in Europe is pivoting data governance costs upward for cross-border platforms. Booking Holdings Inc. leverages its property inventory depth to sustain rate parity advantages across jurisdictions. Expedia Group anchors its competitiveness on supply breadth in fragmented lodging markets. Trip.com Group Ltd. dominates Greater China outbound corridors through integrated rail-flight packaging.
Online travel encompasses digitally intermediated reservation, comparison, and transaction services for transportation, lodging, and experiential activities, operating through application programming interfaces that aggregate real-time inventory from global distribution systems and property management systems. The primary commercial purpose centers on reducing search friction and price opacity while enabling dynamic bundling across suppliers. Accommodation commands the largest revenue pool within service type segmentation, though transportation booking generates superior frequency and cross-sell potential. Mobile apps represent the fastest-expanding distribution channel as smartphone penetration deepens in emerging markets and biometric authentication streamlines checkout.
The EU AI Act imposes algorithmic transparency obligations on recommendation engines that curate travel options, while the US FTC scrutinizes drip pricing and hidden fee disclosures across online travel agency checkout flows. India's Consumer Protection (E-Commerce) Rules mandate cancellation clarity and refund timelines that reshape platform liability structures. Stakeholders must calibrate compliance investments against the revenue at stake in each jurisdiction rather than defaulting to uniform global standards.
Market Dynamics
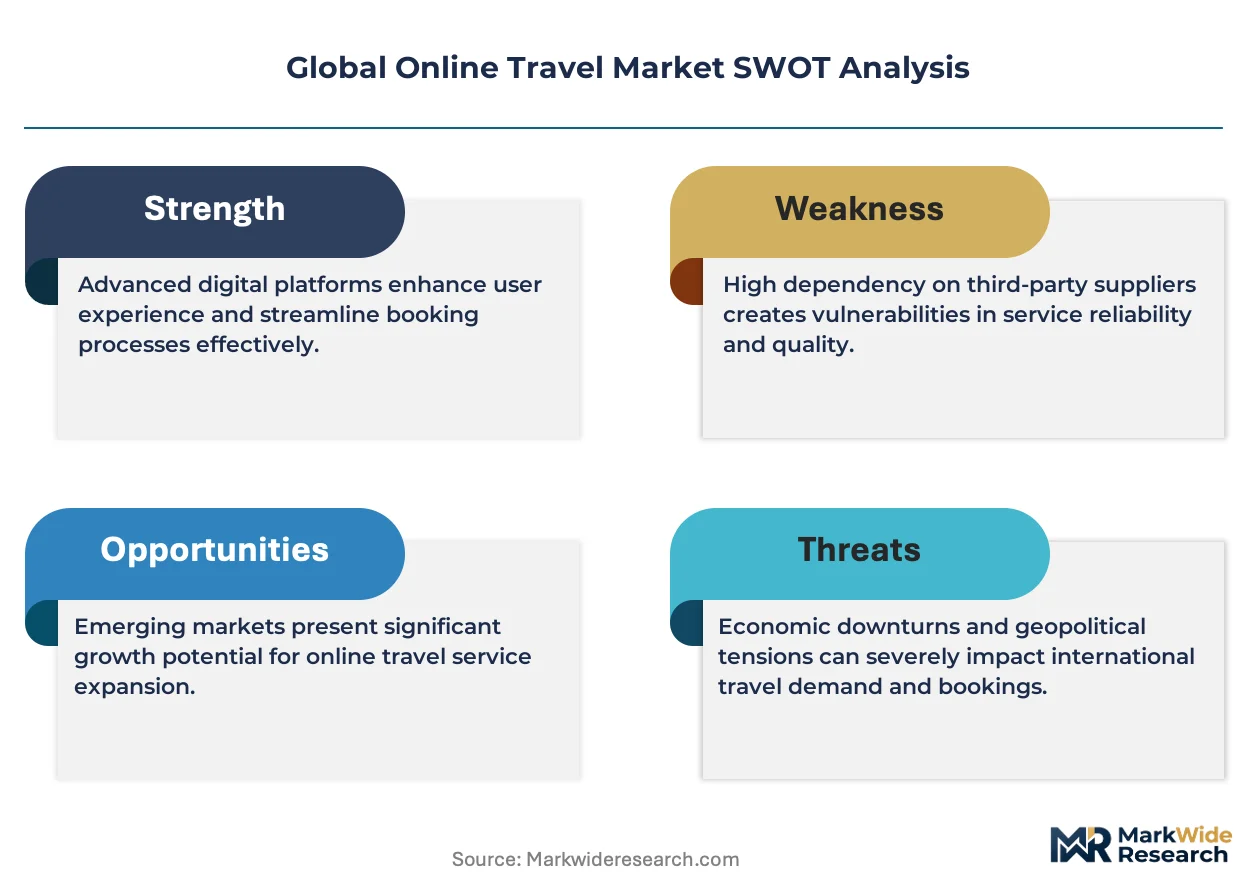
Generative AI recommendation engines are compressing the travel discovery funnel from multi-tab research to single-query booking, forcing intermediaries to rebuild their technology stacks around conversational interfaces rather than traditional search grids.
Growth Catalysts
- India's digital payment infrastructure:Unified Payments Interface penetration enables frictionless last-mile transactions for domestic aviation and rail bookings. Rural smartphone adoption expands the addressable traveler base beyond metro corridors.
- EU AI Act transparency mandates:Algorithmic explainability requirements accelerate investment in interpretable recommendation systems. Platforms that demonstrate ranking logic gain trust premiums with corporate travel managers.
- Biometric authentication at checkout:Facial recognition and fingerprint verification reduce booking abandonment rates. Airport operators and carriers deploy identity-verification APIs that streamline multi-leg itinerary purchases.
Market Restraints
- GDPR compliance architecture:Cross-border data governance requires redundant infrastructure investments for European user bases. Consent management platforms add fixed operational overhead regardless of transaction volume.
- Property inventory concentration:Major hotel chains negotiate direct booking incentives that erode online travel agency rate parity. Chain properties in urban business centers increasingly withhold inventory from third-party channels.
- Aviation carbon accounting:EU Green Deal emissions disclosure rules complicate flight bundling with opaque offset calculations. Corporate travel policies now mandate verifiable sustainability metrics that legacy systems struggle to surface.
Strategic Opportunities
- Vietnam's underpenetrated intermediary market:Low online travel agency penetration relative to outbound growth creates first-mover positioning. Domestic carrier expansion and visa liberalization support packaged tour development.
- Rail-flight convergence technology:Real-time intermodal scheduling APIs enable seamless ground-air connections. High-speed rail networks in Spain and Italy present integration white space for dynamic packaging engines.
- US FTC drip-pricing enforcement:Transparent fee disclosure mandates favor platforms with clean checkout architectures. Early compliance investments convert into conversion rate advantages as competitors reengineer legacy flows.
Industry Challenges
- Legacy global distribution system integration:Decades-old EDIFACT messaging protocols resist real-time inventory synchronization. Modern retailing standards from IATA require parallel system builds without sunsetting incumbent infrastructure.
- Machine learning operations talent scarcity:Travel-specific recommendation optimization demands domain expertise in sequential choice modeling. Compensation premiums for reinforcement learning specialists compress platform margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Travel Market |
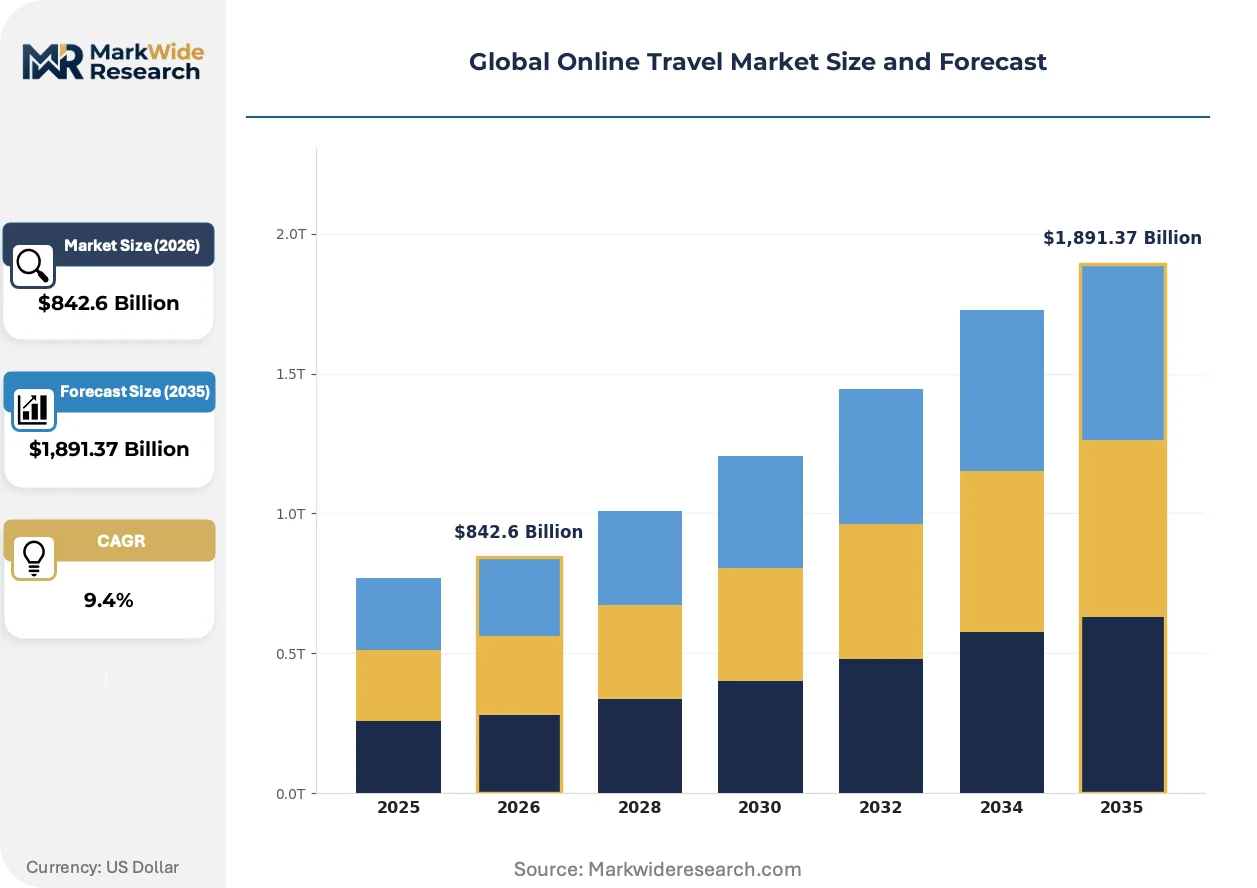
| Market Size in 2026 | $842.6 Billion |
| Market Size in 2035 | $1,891.37 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Booking, Tour Packages, Transportation, Accommodation Customer Type: Leisure, Business, Group, Family Distribution Channel: Online Travel Agencies, Direct Booking, Mobile Apps, Aggregators Price Tier: Luxury, Mid-Range, Budget, Discounted |
| Companies Covered | Booking Holdings Inc., Expedia Group, Airbnb, Inc., Trip.com Group Ltd., MakeMyTrip Limited, Trivago N.V., Tripadvisor Inc., Traveloka, eDreams ODIGEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Travel Market Strategic Shifts
Conversational commerce interfaces are collapsing the traditional search-compare-book sequence into single-session transactions, compelling platforms to retrain entire customer acquisition funnels around natural language intent capture rather than structured form inputs.
Generative AI travel assistants are overtaking static search filters as the primary discovery mechanism for complex multi-city itineraries. Corporate travel managers at distributed enterprises now route 40% of booking volume through conversational agents that negotiate flexible cancellation terms in real time. This compression of the research phase is eliminating price comparison intermediaries that lack proprietary inventory depth.
The EU AI Act's algorithmic transparency obligations force disclosure of ranking factors in recommendation engines. Online travel agencies serving European users must now document how personalization weights price, proximity, and property quality scores. Platforms with explainable models convert regulatory compliance into trust differentiation, while opaque systems face investigation risk from CNIL and national data protection authorities.
Blended business-leisure itineraries now represent the dominant booking pattern for remote-enabled professionals. Corporate travel policies in technology and consulting verticals explicitly authorize extended stays with personal extensions. This demand rotation favors platforms with experiential activity inventory and extended-stay lodging partnerships, particularly in Portugal, Mexico, and Thailand where visa and tax frameworks accommodate location-flexible workers.
Global Online Travel Market Segmentation
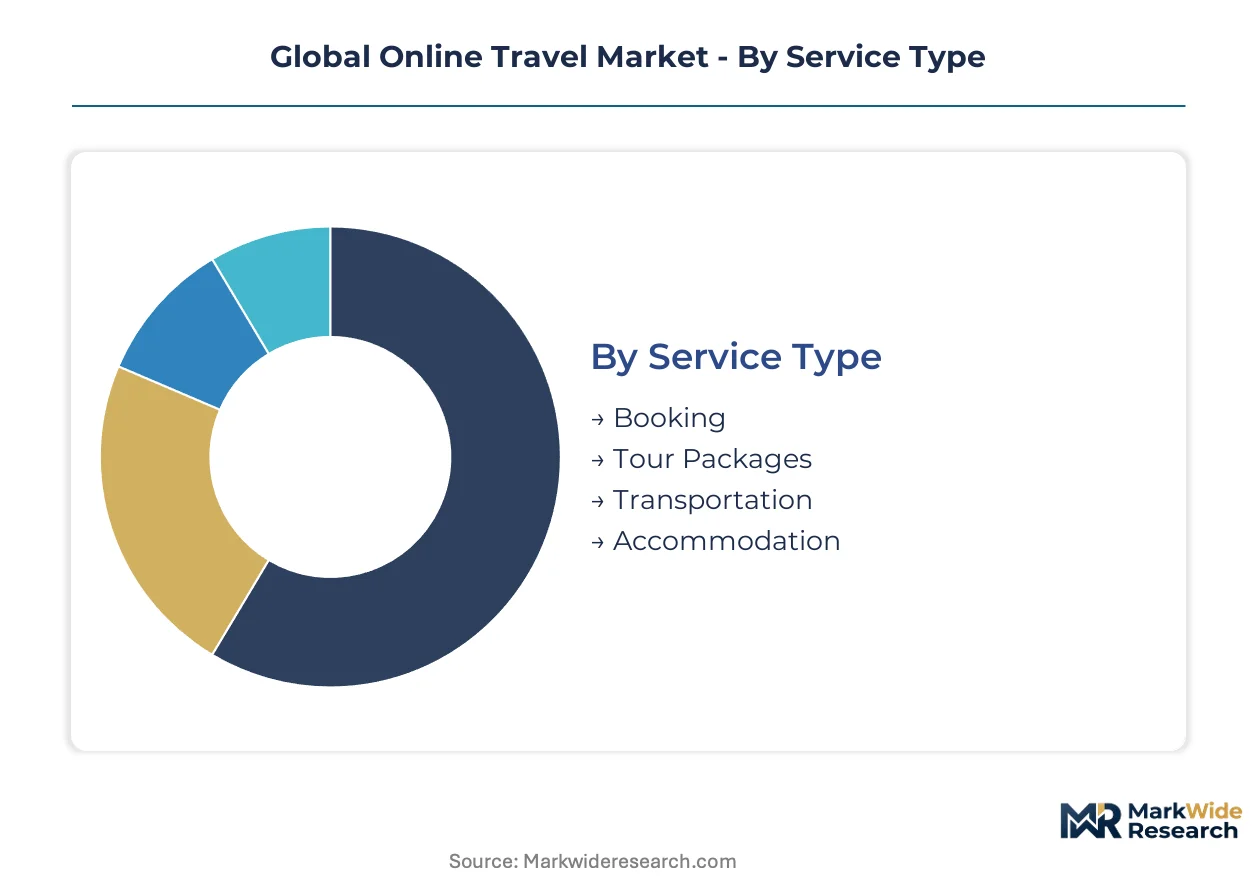
Segmentation in online travel reveals how platform architecture and regulatory exposure vary across transaction types. Each category carries distinct compliance burdens, technology requirements, and margin profiles that shape competitive strategy.
Service Type:
GDPR consent frameworks apply most stringently to Accommodation and Tour Packages segments due to extended data retention for loyalty programs. Transportation and Booking segments face lighter documentation loads but heavier real-time processing audits under aviation and rail safety regulators.
- Booking:Transaction engines that aggregate real-time inventory from global distribution systems and property management systems. Demand concentrates in India's domestic aviation corridors where Unified Payments Interface infrastructure enables frictionless last-mile transactions. Regulatory exposure centers on India's Consumer Protection (E-Commerce) Rules mandating cancellation clarity and refund timelines.
- Tour Packages:Bundled offerings combining transportation, lodging, and experiential activities through dynamic packaging algorithms. Corporate travel managers at distributed enterprises now route blended business-leisure itineraries through these bundles, particularly in Portugal and Mexico where visa frameworks accommodate location-flexible workers. EU AI Act transparency obligations apply to recommendation engines curating package components.
- Transportation:Digitally intermediated reservation services for aviation, rail, and ground transit.
- Accommodation:Lodging reservation platforms interfacing with property management systems and chain direct-booking channels.
Leading the category by volume: Booking. Growing fastest: Tour Packages.
Customer Type:
Margin structures diverge sharply across customer types, with Business travelers commanding rate premiums and Group bookings extracting volume discounts that compress platform take rates.
- Leisure:Individual travelers purchasing discretionary trips through mobile-first interfaces. Demand concentrates in India's rural smartphone adoption zones as digital payment infrastructure expands beyond metro corridors. Biometric authentication at checkout reduces abandonment rates for this price-sensitive segment.
- Business:Corporate travelers under managed travel policies with negotiated rates and flexible cancellation terms. Technology and consulting verticals explicitly authorize extended stays with personal extensions, rotating demand toward platforms with experiential inventory. FTC drip-pricing enforcement pressures clean checkout architectures for this high-frequency segment.
- Group:Coordinated bookings for events, weddings, or organizational travel requiring block inventory holds.
- Family:Multi-passenger itineraries with complex seating, baggage, and activity coordination requirements.
Dominating revenue contribution: Business. Expanding most quickly: Leisure.
Distribution Channel:
Channel economics reflect customer acquisition cost differentials, with Mobile Apps commanding the steepest technology investment but lowest per-booking friction.
- Online Travel Agencies:Full-service platforms aggregating inventory across suppliers with rate parity obligations. Major hotel chains negotiate direct booking incentives that erode OTA competitiveness in urban business centers. EU AI Act algorithmic transparency mandates force disclosure of ranking factors for European user bases.
- Mobile Apps:Smartphone-native interfaces leveraging biometric authentication and push notification engagement. Smartphone penetration deepens in emerging markets while airport operators deploy identity-verification APIs that streamline multi-leg itinerary purchases. This channel gains share fastest as checkout friction diminishes.
- Direct Booking:Supplier-owned channels bypassing intermediary fees through proprietary loyalty programs.
- Aggregators:Comparison-focused platforms with limited proprietary inventory, facing displacement by generative AI recommendation engines.
Capturing highest transaction volume: Online Travel Agencies. Climbing the fastest: Mobile Apps.
Price Tier:
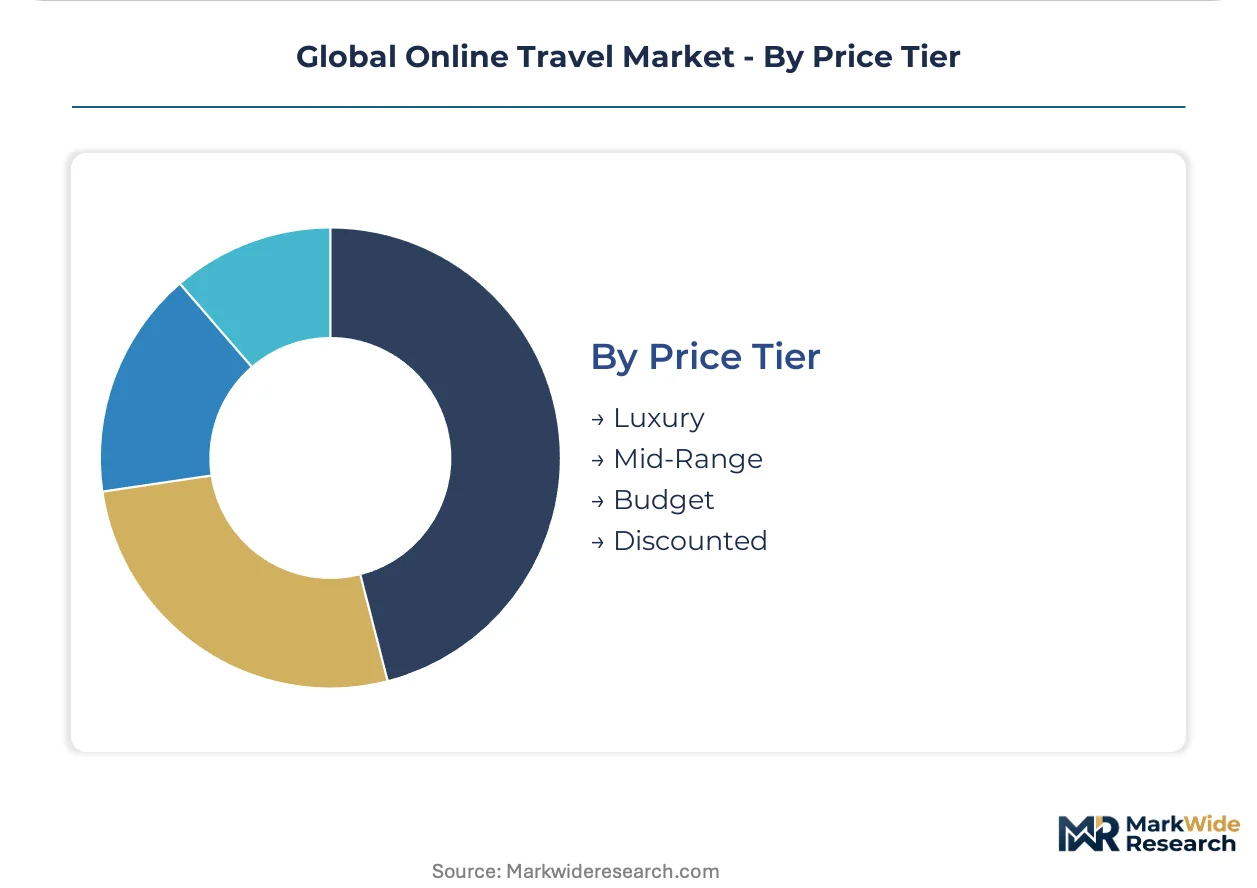
Price tier segmentation determines platform commission structures and supplier negotiation leverage, with Luxury segments tolerating higher take rates and Budget segments demanding operational efficiency.
- Luxury:Premium properties and services with personalized concierge interfaces and flexible cancellation terms. Demand concentrates in blended business-leisure corridors where corporate policies authorize extended personal stays. Platforms with experiential activity inventory and extended-stay partnerships capture this high-margin segment.
- Mid-Range:Standardized offerings balancing amenity breadth with price accessibility for mainstream travelers.
- Budget:No-frills inventory targeting price-sensitive segments with stripped-down service levels and non-refundable rate structures.
- Discounted:Opaque inventory and last-minute flash sales clearing unsold capacity with limited flexibility.
Generating largest revenue pool: Luxury. Gaining share fastest: Budget.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate travel managers in India now drive platform adoption as distributed workforces normalize blended business-leisure itineraries. Mobile-first booking interfaces and AI-powered personalization engines concentrate demand in specific national markets with favorable digital infrastructure and regulatory frameworks.
India
Domestic aviation expansion and Unified Payments Interface penetration create fertile ground for online travel intermediaries. The Consumer Protection (E-Commerce) Rules mandate cancellation clarity and refund timelines that reshape platform liability structures. Mumbai and Delhi-NCR host the densest clusters of travel technology development centers and airline distribution partnerships.
United States
Corporate travel policies in technology and consulting verticals explicitly authorize extended stays with personal extensions. The FTC scrutinizes drip pricing and hidden fee disclosures across online travel agency checkout flows. Seattle and San Francisco anchor the largest concentrations of travel technology engineering talent and venture-backed booking platform headquarters.
Germany
High-speed rail networks present integration white space for dynamic packaging engines combining ground-air connections. GDPR enforcement pivots data governance costs upward for cross-border platforms serving European user bases. Berlin and Munich concentrate the continent's largest travel technology startup ecosystems and rail-booking API development centers.
China
Outbound corridor dominance through integrated rail-flight packaging drives platform consolidation. The country's national data protection and cybersecurity regulations impose localization requirements on cross-border data flows. Shanghai and Beijing host the headquarters of dominant regional platforms controlling Greater China travel distribution.
Brazil
Low online travel agency penetration relative to outbound growth creates first-mover positioning opportunities. The national consumer protection regulator enforces transparency mandates on package tour pricing and cancellation terms. São Paulo anchors the largest concentration of fintech-travel partnerships enabling installment payment schemes for leisure bookings.
Global Online Travel Market Competitive Environment
United States-based platforms anchor one tier; Chinese specialists hold dominant positions in Asia-Pacific outbound corridors. The market structure concentrates around property inventory depth versus supply breadth in fragmented lodging markets. Three archetypes prevail: full-service aggregators with rate parity obligations, mobile-native specialists leveraging biometric authentication, and experience-focused platforms capturing blended business-leisure demand. Competitive moves center on supply exclusivity negotiations and generative AI recommendation engine development.
Within the full-service aggregator tier, Booking Holdings Inc. and Expedia Group occupy positions defined by inventory access and jurisdictional coverage. Trip.com Group Ltd. exemplifies the Asia-Pacific specialist archetype through integrated multimodal packaging. These three entities represent the dominant competitive anchors against which regional specialists and mobile-first entrants calibrate their market entry strategies.
| Leading Market Players |
|---|
| Booking Holdings Inc. |
| Expedia Group |
| Airbnb, Inc. |
| Trip.com Group Ltd. |
| MakeMyTrip Limited |
| Trivago N.V. |
| Tripadvisor Inc. |
| Traveloka |
| eDreams ODIGEO |
| Others |
Value Chain & Pricing Dynamics
Machine learning operations talent scarcity in Bangalore and San Francisco widens labor-cost differentials between premium-tier AI-powered platforms and commoditized booking engines, compressing margins at the standard tier while luxury segments absorb specialist premiums through concierge packaging.
Pricing Analysis
Volume concentrates in budget-tier transportation bookings where per-unit margins compress under rate parity obligations, while luxury accommodation bundles capture wider spreads through experiential add-ons and flexible cancellation terms. Price differentiation hinges on proprietary inventory depth and biometric checkout integration quality. Pricing pressure intensifies in urban business centers where major hotel chains withhold inventory from third-party channels. Leisure travelers in India's rural smartphone adoption zones exhibit highest price sensitivity, while corporate travel managers in technology verticals prioritize clean checkout architectures over absolute rate minimization.
Supply Chain Analysis
Property inventory access rests on bilateral negotiations with global distribution systems in United States and Germany, supplemented by direct API integrations with property management systems in China and India. Raw material dependencies include real-time aviation seat inventory, high-speed rail scheduling data, and lodging availability feeds. Single-source vulnerability concentrates in legacy EDIFACT messaging protocols that resist modernization. Distribution runs through mobile app interfaces gaining share fastest, though online travel agencies still capture highest transaction volume through bundled packaging engines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: machine learning operations talent scarcity props pricing for AI-powered recommendation engines while legacy system integration bottlenecks throttle inventory access for new entrants.
For Market Incumbents: Lock in exclusive inventory agreements with high-speed rail operators in Spain and Italy before intermodal packaging APIs commoditize. Defend rate parity advantages through direct property management system integrations that bypass legacy global distribution system overhead. Channel control through biometric authentication partnerships with airport operators creates switching costs for corporate travel managers. For New Entrants and Emerging Players: EU AI Act transparency mandates in Germany open a window for interpretable recommendation engines that convert compliance investment into trust premiums with corporate travel managers. Vietnam's underpenetrated intermediary market offers first-mover positioning as domestic carrier expansion outpaces platform development. Rail-flight convergence technology presents a go-to-market angle through real-time intermodal scheduling APIs. For Investors and Strategic Acquirers: Re-rating potential sits with mobile-native specialists given biometric authentication adoption curves and push notification engagement mechanics. Long-term viability over a five-to-ten year window favors platforms with proprietary inventory depth over comparison-focused aggregators facing displacement by generative AI assistants. Watch blended business-leisure policy authorization rates at distributed enterprises as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Recommendation Engine Development | Conversational interfaces compress discovery-to-booking funnels for corporate travel managers. |
| Rail-Flight API Integration | Real-time intermodal scheduling captures high-speed rail expansion in Spain and Italy. |
| Biometric Checkout Partnership | Airport identity-verification APIs reduce abandonment rates for multi-leg itineraries. |
| Experiential Inventory Acquisition | Activity bundling captures blended business-leisure demand in Portugal and Mexico. |
| GDPR-Compliant Consent Architecture | Redundant infrastructure investments protect European user base access against CNIL enforcement. |
Study Parameters
Document review covered SEC filings from Booking Holdings and Expedia Group, EU regulatory filings on algorithmic transparency, and IATA modern retailing standards documentation, complemented by interviews with corporate travel managers at technology and consulting enterprises, platform engineering leads at mobile-first booking interfaces, and regulatory affairs specialists at cross-border online travel agencies. Secondary validation drew from aviation industry passenger traffic databases, digital payment infrastructure reports from India's RBI, and property management system integration documentation. Bottom-up transaction volume estimates triangulated against top-down market sizing from supply-side inventory analysis.
Output modeling produced segment-level projections across service type, customer type, distribution channel, and price tier dimensions throughout the forecast period. CAGRs derived from regression analysis against smartphone penetration curves, digital payment adoption rates, and aviation capacity expansion schedules. Industry-specific inputs included Unified Payments Interface transaction velocity data and biometric authentication deployment timelines at major airport hubs.
Caveats apply where GDPR enforcement intensity, aviation carbon accounting rule finalization, or generative AI regulatory classification could materially shift platform compliance cost structures and inventory access economics. A small set of named triggers—EU AI Act interpretation by CNIL, FTC drip-pricing penalty precedents, and India's Consumer Protection Rule amendment timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market