
 Travel Service Platform Market | 2026-2036
Travel Service Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Service Platform Market Insights
The EU Green Deal is consolidating sustainability-linked procurement standards across European travel service platforms. Booking Holdings Inc. leverages its vertically integrated supplier network to secure preferential inventory access across multiple geographies. Expedia, Inc. anchors its competitive stance through proprietary loyalty architecture that locks in repeat booking behavior. Airbnb, Inc. differentiates by controlling host onboarding quality standards that command premium pricing power in alternative accommodation.
A travel service platform constitutes a digital intermediary infrastructure that aggregates inventory from airlines, hotels, ground transport providers, and ancillary service vendors into searchable, bookable interfaces, typically processing transactions through API-connected global distribution systems or direct supplier integrations. These platforms serve the commercial purpose of reducing search friction, standardizing cancellation policies, and centralizing payment reconciliation for fragmented travel supply chains. Flight booking and hotel reservations capture the dominant share of transaction value, while travel insurance represents the fastest-expanding margin pool due to attach-rate optimization at checkout. Mobile apps are displacing desktop online travel agencies as the primary booking channel, driven by push-notification merchandising and one-tap payment wallets.
The EU's GDPR and the Digital Services Act impose data governance and algorithmic transparency obligations on platforms operating across member states, elevating compliance costs but also creating barriers to unregulated entrants. The US FTC scrutinizes drip pricing and hidden fee disclosures, forcing platforms to restructure fare presentation layers. China's SAMR enforces anti-monopoly provisions against preferential treatment of captive inventory, reshaping how Tongcheng Travel and Trip.com structure supplier contracts. Stakeholders must monitor whether emerging AI disclosure mandates in the EU AI Act will require real-time explanation of dynamic pricing algorithms to consumers.
Market Dynamics
Corporate travel management programs are consolidating booking authority onto centralized platforms, while the EU Green Deal's emissions transparency mandates are rewriting supplier qualification criteria across European procurement desks.
Growth Catalysts
- Corporate travel centralization:Enterprises are mandating platform-based booking to enforce spend controls and capture negotiated rates. This procurement shift locks in recurring transaction volumes.
- EU Green Deal compliance:Transport emissions disclosure requirements are forcing platforms to integrate carbon calculators, creating competitive differentiation for early adopters.
- India's digital payment infrastructure:UPI penetration and domestic tourism investment are accelerating platform adoption among first-time online bookers.
Market Restraints
- API dependency concentration:Global distribution system oligopolies in the US and Europe extract fixed per-transaction fees that compress platform margins regardless of booking value.
- GDPR compliance architecture:EU data localization and algorithmic transparency obligations impose fixed overhead costs that scale poorly for mid-tier platforms.
- Airline direct connect substitution:Carriers are bypassing intermediaries through proprietary apps, eroding platform inventory exclusivity on high-frequency routes.
Strategic Opportunities
- Embedded finance convergence:Platforms integrating buy-now-pay-later and travel insurance at checkout are capturing ancillary revenue pools previously ceded to banks.
- AI-powered personalization:Machine learning recommendation engines trained on search abandonment patterns are recovering conversion rates on mobile interfaces.
- Southeast Asia underpenetration:Indonesia and Vietnam's fragmented accommodation supply chains remain underserved by integrated booking infrastructure.
Industry Challenges
- Legacy system integration friction:Property management system heterogeneity forces hotels to maintain multiple API connections, increasing technical debt.
- Dynamic pricing algorithm auditability:EU AI Act disclosure requirements demand explainable pricing logic that conflicts with proprietary machine learning models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Service Platform Market |
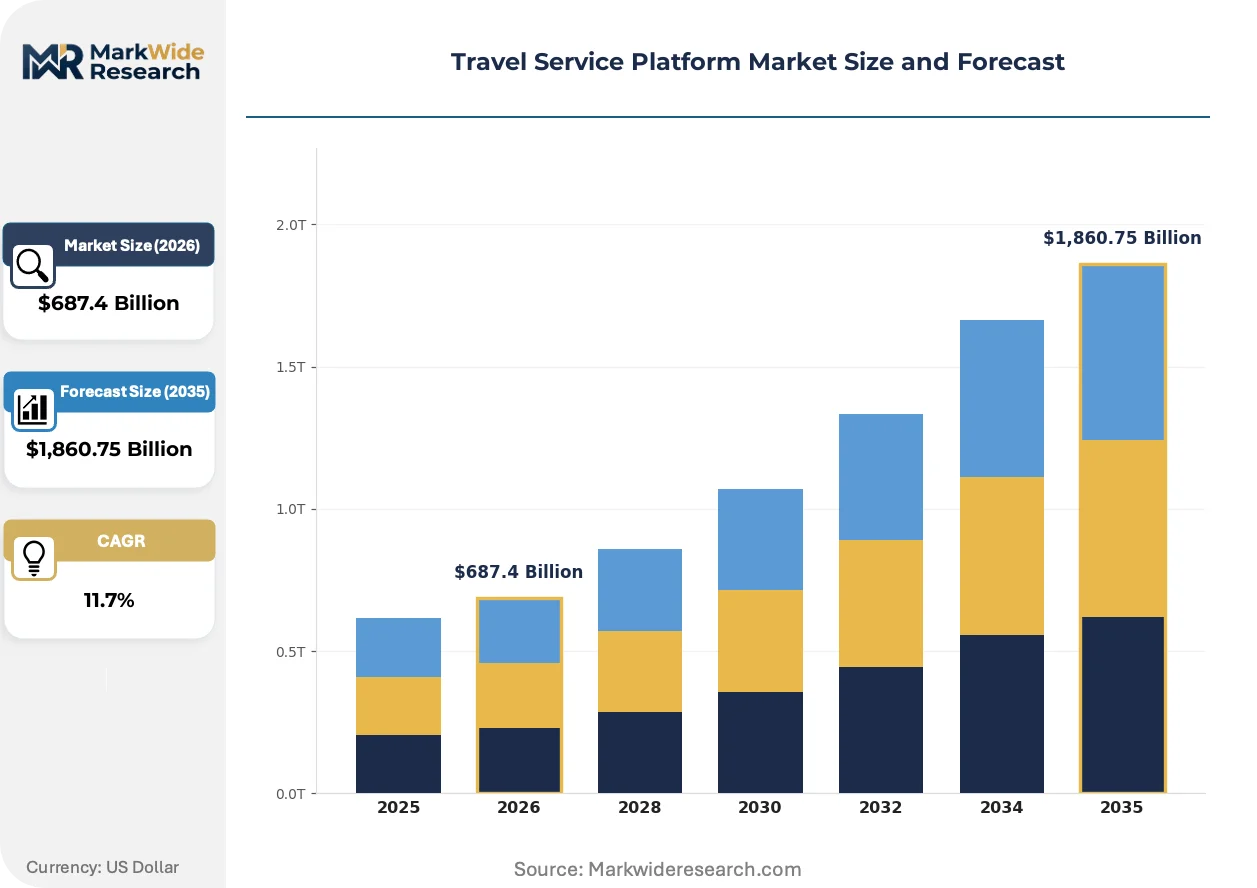
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,860.75 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Flight Booking, Hotel Reservations, Car Rentals, Travel Insurance Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Solo Travelers Booking Channel: Online Travel Agencies, Direct Booking, Mobile Apps, Travel Agents Payment Method: Credit Card, Debit Card, PayPal, Digital Wallets |
| Companies Covered | Booking Holdings Inc., Expedia, Inc., Airbnb, Inc., Trip.com, Tripadvisor LLC, MAKEMYTRIP PVT. LTD., Tongcheng Travel, eDreams ODIGEO, Webjet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Service Platform Market Trends and Innovations
Blockchain-based settlement rails and generative AI search interfaces are restructuring how inventory is discovered, priced, and confirmed across fragmented supplier networks.
Blockchain settlement infrastructure is decentralizing payment reconciliation between platforms and accommodation providers. Smaller hotel chains in Southern Europe are adopting these rails to bypass traditional merchant fee structures. The technology is decentralizing working capital requirements previously concentrated in centralized escrow accounts.
The EU AI Act's algorithmic transparency mandates are compelling platforms to document pricing logic for regulatory inspection. This documentation burden is elevating compliance costs but also creating defensible moats against unregulated entrants. Dynamic packaging engines serving multi-city itineraries face the steepest reengineering requirements.
Mobile wallet dominance is compressing the booking funnel from search to confirmation. Younger travelers in India and Brazil are completing transactions entirely within super-app environments, bypassing traditional desktop agency interfaces. This behavioral shift is most pronounced in markets where UPI, Pix, and similar real-time payment rails have achieved critical mass.
Travel Service Platform Market Segmentation
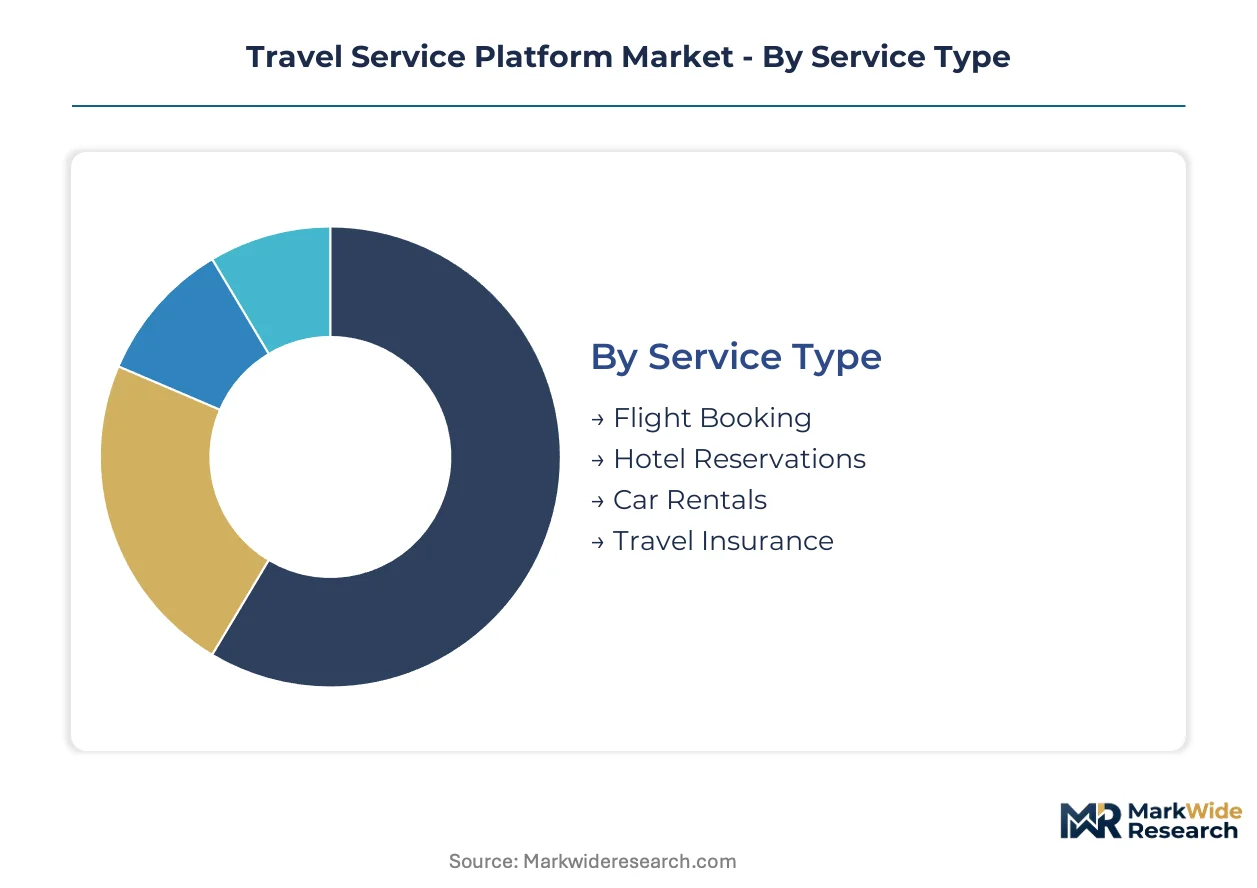
Travel service platforms must balance standardized infrastructure against traveler-specific customization. Each segmentation dimension reveals distinct margin profiles and technical requirements that shape platform architecture decisions.
Service Type:
Customization intensity varies sharply across this category, from commoditized flight inventory to bespoke insurance packaging.
- Flight Booking:GDS-aggregated seat inventory dominates transaction volumes. Corporate procurement desks in India and Brazil are consolidating spend through platform contracts that demand real-time fare transparency.
- Hotel Reservations:Property management system heterogeneity forces platforms to maintain multiple API connections. Alternative accommodation suppliers in Southern Europe are bypassing traditional merchant fee structures through blockchain settlement rails.
- Car Rentals:Fleet availability APIs integrate with ground transport modules. Airport-centric demand clusters around business traveler corridors.
- Travel Insurance:Attach-rate optimization at checkout drives margin expansion. Regulatory disclosure requirements vary by departure jurisdiction.
Most installed capacity flows through Flight Booking. Expansion is steepest in Travel Insurance.
Customer Type:
Volume concentration tilts toward segments with predictable booking patterns and centralized payment authority.
- Business Travelers:Enterprises mandate platform-based booking to enforce spend controls. EU Green Deal emissions disclosure requirements are rewriting procurement qualification criteria across European corporate travel programs.
- Leisure Travelers:Mobile wallet dominance compresses the booking funnel from search to confirmation. Younger travelers in India complete transactions entirely within super-app environments.
- Group Travelers:Bulk inventory holds and split-payment functionality create technical complexity. Destination wedding segments in Southeast Asia drive seasonal demand spikes.
- Solo Travelers:Flexible cancellation policies and single-occupancy pricing transparency determine platform selection. Safety-focused features command premium positioning.
Business Travelers anchor platform revenue stability. Solo Travelers are expanding most quickly as safety-assurance features proliferate.
Booking Channel:
Channel economics reflect diverging customer acquisition costs and lifetime value trajectories.
- Mobile Apps:Push-notification merchandising and one-tap payment wallets displace desktop interfaces. UPI penetration in India and Pix adoption in Brazil accelerate super-app booking concentration.
- Online Travel Agencies:Vertically integrated supplier networks secure preferential inventory access. GDPR compliance architecture imposes fixed overhead costs that scale poorly for mid-tier platforms.
- Direct Booking:Carriers bypass intermediaries through proprietary apps on high-frequency routes. Loyalty program lock-in reduces price sensitivity.
- Travel Agents:Complex multi-city itineraries and corporate policy navigation sustain relevance. Commission structures compress with automated self-service alternatives.
Online Travel Agencies retain the largest installed base. Mobile Apps show the steepest expansion trajectory.
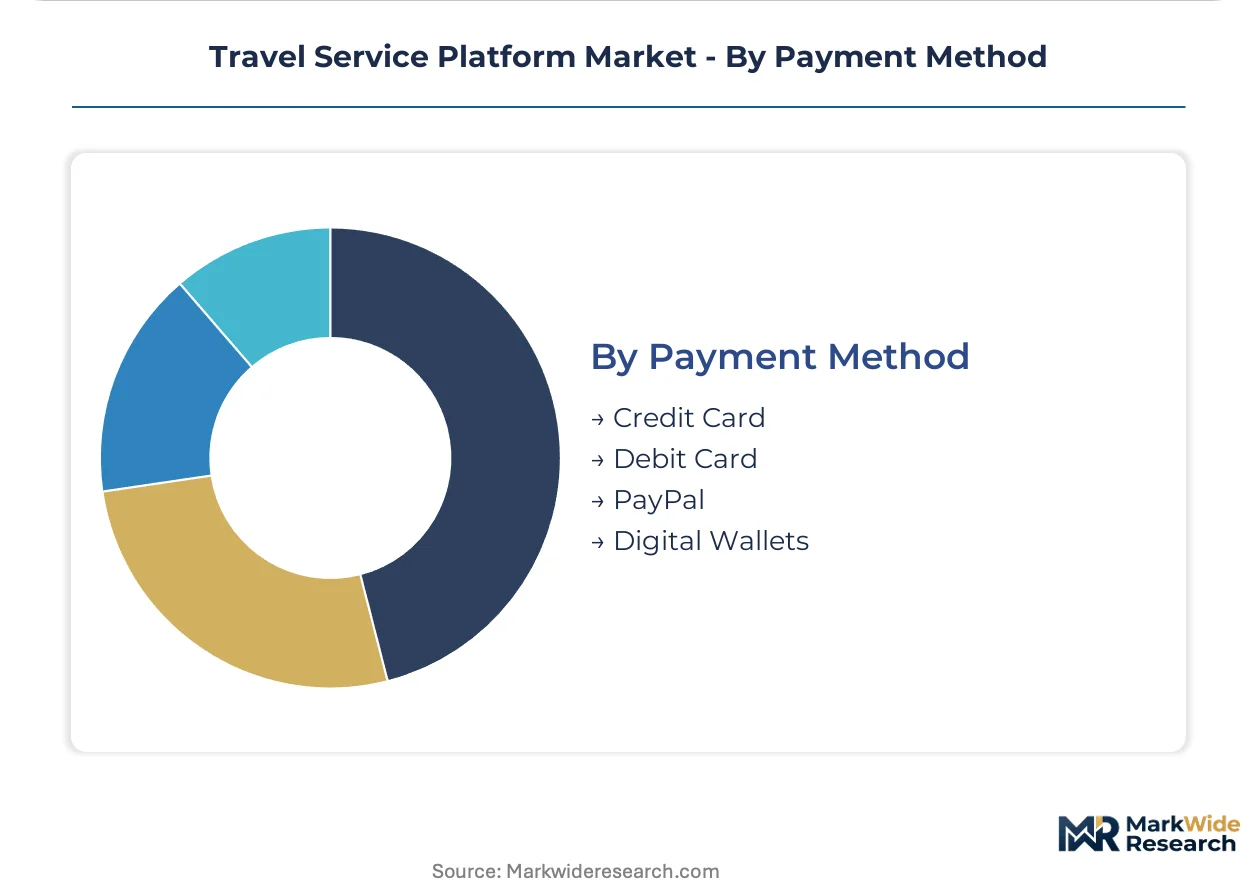
Payment Method:
Payment infrastructure maturity determines geographic penetration ceilings and fraud exposure profiles.
- Digital Wallets:Real-time payment rails achieve critical mass in India and Brazil. Buy-now-pay-later integration captures ancillary revenue pools previously ceded to banks.
- Credit Card:Chargeback protection and travel insurance bundling sustain corporate preference. Interchange fees compress platform margins on high-value transactions.
- PayPal:Buyer protection policies reduce booking abandonment. Cross-border currency conversion adds friction for emerging market travelers.
- Debit Card:Lower interchange rates appeal to price-sensitive leisure segments. Fraud liability exposure limits platform enthusiasm.
Credit Card infrastructure carries the most installed volume. Digital Wallets are climbing the fastest as real-time payment rails mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The travel service platform industry traces its commercial origins to early computerized reservation systems developed in the United States during the 1960s, with Sabre launching the first automated booking platform for American Airlines. Digital marketplace infrastructure subsequently migrated to Europe and Asia-Pacific as internet penetration expanded. Platform economics now concentrate where payment digitization, tourism infrastructure, and regulatory harmonization intersect.
United States
Corporate travel management centralization and loyalty program lock-in sustain platform dominance. The FTC enforces drip pricing disclosure rules that reshape fare presentation layers. Dallas-Fort Worth and Atlanta anchor major airline hub concentration where platform inventory aggregation remains critical for route coverage.
Germany
Business traveler density and outbound tourism volume sustain high platform transaction throughput. The EU Green Deal mandates transport emissions transparency that rewrites procurement qualification criteria. Berlin and Munich host corporate travel management consolidation where centralized booking platforms enforce spend controls.
India
UPI penetration and domestic tourism infrastructure investment accelerate first-time online booking adoption. The RBI oversees digital payment interoperability standards that reduce transaction friction. Bengaluru and Mumbai concentrate platform engineering talent and super-app development where mobile wallet dominance compresses booking funnels.
China
Domestic tourism scale and mobile payment integration sustain platform transaction volumes. The SAMR enforces anti-monopoly provisions against preferential treatment of captive inventory. Shanghai and Beijing anchor supplier contract restructuring where Tongcheng Travel and Trip.com navigate regulatory compliance.
Brazil
Pix real-time payment adoption and leisure travel recovery drive mobile-first booking behavior. The central bank's instant payment infrastructure reduces abandonment at checkout. São Paulo and Rio de Janeiro concentrate alternative accommodation supply where platforms compete for host onboarding quality.
Travel Service Platform Market Competitive Landscape
Capital-heavy inventory aggregators compete with asset-light marketplace operators across divergent margin structures. The vendor base consolidates around three tiers: vertically integrated global platforms with captive supplier networks, regional specialists with localized payment integration, and niche operators focused on alternative accommodation or corporate travel management. Strategic differentiation runs through proprietary loyalty architecture, direct supplier contracting, and embedded finance convergence at checkout. Competitive moves concentrate on M&A for geographic expansion and API infrastructure investments to reduce global distribution system dependency.
Within the vertically integrated tier, Booking Holdings Inc. and Expedia, Inc. occupy positions defined by supplier network scale and multi-brand portfolio architecture. Airbnb, Inc. exemplifies the alternative accommodation archetype through host quality control and premium pricing power. Trip.com anchors the Asia-Pacific regional specialist position with domestic market depth and regulatory navigation capabilities in China.
| Leading Market Players |
|---|
| Booking Holdings Inc. |
| Expedia, Inc. |
| Airbnb, Inc. |
| Trip.com |
| Tripadvisor LLC |
| MAKEMYTRIP PVT. LTD. |
| Tongcheng Travel |
| eDreams ODIGEO |
| Webjet |
| Others |
Pricing and Supply Chain Analysis
Platform engineering talent concentration in Bengaluru and Mumbai creates labor-cost differentials that widen pricing-tier spreads between premium full-service suites and stripped-down API-only offerings. Indian development centers enable mid-tier platforms to undercut US and European rivals on subscription pricing while maintaining feature parity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the competitive landscape. Premium tiers bundle dedicated account management and custom API configurations for enterprise procurement desks, while economy tiers compete on per-transaction fees for independent hoteliers. Price differentiation hinges on GDS access breadth and real-time inventory depth. Pricing pressure stems from airline direct-connect substitution on high-frequency routes, compressing intermediary margins. Small property owners in Southern Europe exhibit highest price sensitivity; multinational corporate travel programs demonstrate lowest sensitivity due to negotiated rate lock-ins.
Supply Chain Analysis
Direct-to-property API connections handle independent hotel inventory, while GDS aggregators manage chain hotel distribution. Supply concentration rests in the United States, Ireland, and Spain where Amadeus, Sabre, and Travelport maintain server infrastructure. Raw material dependencies include cloud compute capacity, payment gateway licenses, and PCI-DSS certification maintenance. Single-source vulnerability pervades GDS oligopolies where three providers control global airline inventory access. Distribution runs through hybrid models blending direct supplier contracts with intermediary aggregation layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU GDPR compliance costs elevate European platform operating expenses against India's lighter regulatory burden and deeper engineering talent pools.
For Market Incumbents: Anticipate SAMR enforcement actions in China forcing contract restructuring that erodes preferential inventory terms. Consolidate supplier relationships through backward integration into property management system development. Prioritize embedded finance capabilities to capture ancillary revenue streams threatened by fintech entrants. For New Entrants and Emerging Players: Solo travelers seeking safety-assurance features represent the most penetrable buyer archetype currently underserved by incumbent personalization engines. Southeast Asia's fragmented accommodation supply chains in Indonesia and Vietnam offer white-space expansion corridors. Deploy AI-powered recommendation systems trained on mobile search abandonment patterns as the primary go-to-market wedge. For Investors and Strategic Acquirers: Corporate travel management platforms with EU Green Deal-compliant carbon calculators are the most active acquirer targets in this space. Long-term viability favors asset-light marketplace operators over inventory-heavy aggregators facing margin compression. Monitor UPI and Pix real-time payment penetration rates as the inflection signal for super-app booking dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Settlement Integration | Southern European hotel chains bypass traditional merchant fees through decentralized payment rails. |
| AI-Powered Personalization Engine | Machine learning models trained on mobile abandonment patterns recover conversion rates for leisure segments. |
| Embedded Finance Convergence | Buy-now-pay-later integration at checkout captures ancillary revenue previously ceded to banking partners. |
| EU Green Deal Compliance Suite | Carbon calculator integration creates procurement differentiation for European corporate travel programs. |
| Super-App Booking Channel Expansion | UPI and Pix penetration enables transaction completion entirely within mobile wallet environments. |
Research Methodology
Bottom-up corporate travel spend modeling reconciled against top-down GDS transaction tracking forms the analytical core of this study. Primary interviews with platform CTOs, airline distribution strategy leads, hotel revenue management directors, and corporate procurement officers were cross-validated against secondary sources including SEC 10-K filings, EU Digital Services Act regulatory texts, and RBI payment system reports. Triangulation between supplier-side capacity disclosures and buyer-side contract values calibrated volume estimates.
Historical booking channel migration patterns and mobile wallet adoption curves anchored the projection framework. Segmentation dimensions modeled include service type, customer archetype, booking channel, and payment method across the analysis window. CAGRs were derived from trendline extrapolation of digital payment penetration rates and corporate travel centralization indices. Forecast inputs incorporated EU AI Act compliance cost assumptions and real-time payment infrastructure buildout timelines.
Inputs from GDS transaction disclosures and platform engineering hiring data were available through the study window; gaps in proprietary airline direct-connect volume introduce uncertainty bands around intermediary market share estimates. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and payment infrastructure maturation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market