
 India Online Travel Market | 2026-2036
India Online Travel Market Size, Share, and Industry Trends Forecast 2026-2036
India Online Travel Market Foresight
India's budget hotel aggregator network is restructuring supply chains across the hospitality sector. MakeMyTrip Limited leverages its captive inventory partnerships to dominate interstate route packaging. Ixigo sustains rail-air multimodal search traffic through proprietary fare prediction algorithms. OYO Rooms anchors extended-stay supply in tier-2 cities through asset-light franchise contracts.
India online travel comprises digital platforms that aggregate, compare, and transact transportation, lodging, and experience bookings through real-time inventory APIs and dynamic pricing engines. These systems process search queries across GDS feeds, direct hotel channel managers, and airline NDC connections to return bookable options with confirmation latency under three seconds. Flight booking and hotel reservation segments command the largest transaction volumes, though package tours extract higher per-booking commissions by bundling opaque inventory. AI-powered recommendations represent the fastest-growing technology layer, converting browse-to-book rates through personalized itinerary ranking.
RBI regulates payment aggregator licensing and escrow protocols, while TRAI oversees telecom infrastructure that underpins mobile app delivery across India's tiered connectivity landscape. BIS certification requirements for data localization shape how foreign platforms architect server infrastructure. Stakeholders must monitor how UPI's international expansion alters cross-border booking settlement flows.
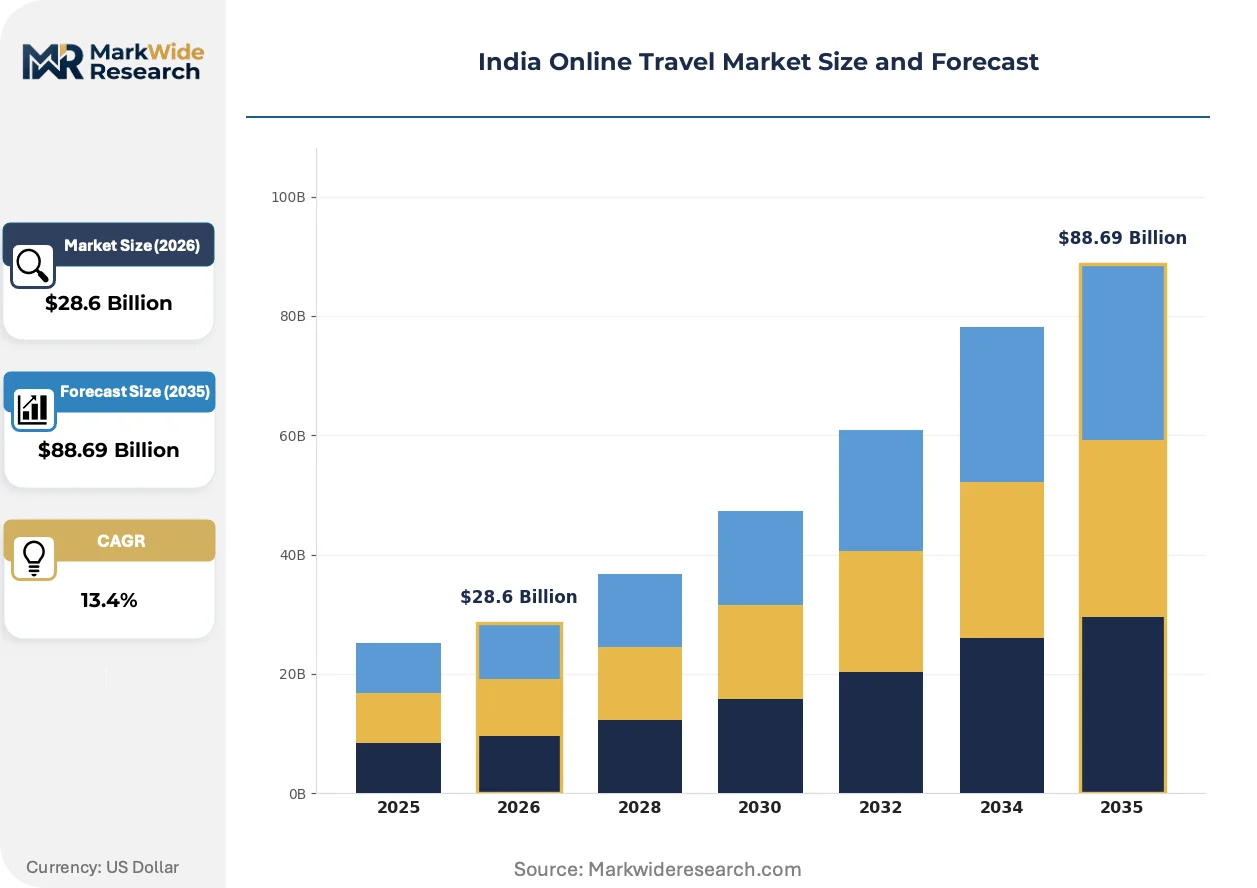
Market Dynamics
UPI's real-time settlement infrastructure is compressing booking confirmation windows from hours to seconds, forcing platforms to rebuild their payment orchestration stacks around RBI's digital rails.
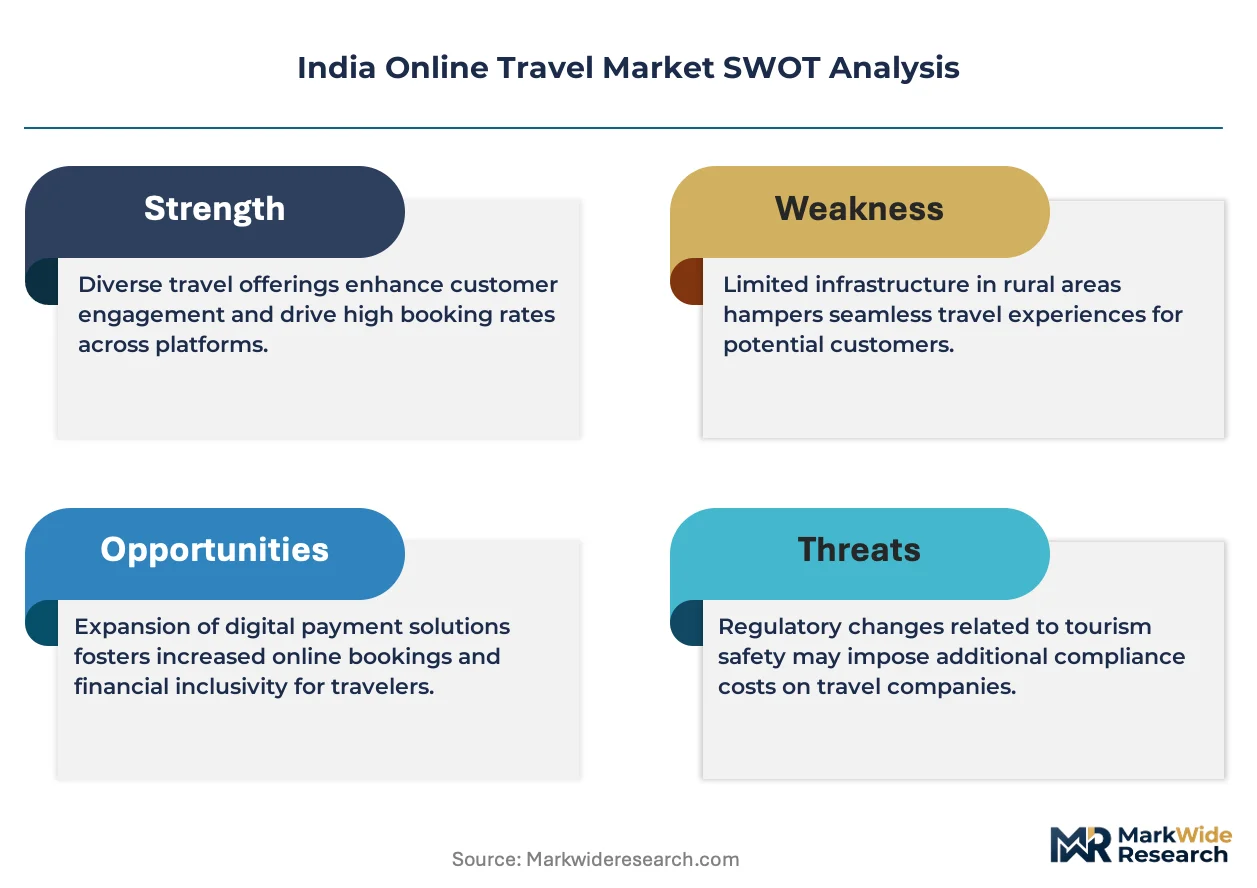
Growth Catalysts
- RBI's Payment Aggregator Licensing:Standardized escrow protocols reduce merchant onboarding friction for hospitality suppliers. Platforms now clear small hoteliers in under 48 hours.
- Tier-3 City Airport Expansion:UDAN scheme connectivity additions unlock leisure demand from Indore, Coimbatore, and Lucknow. These routes now sustain year-round load factors above 75%.
- Multimodal API Convergence:Rail-air-bus inventory unification through NDC and IRCTC feed integration enables single-search itinerary completion. Travelers book complete journeys without platform switching.
Market Restraints
- Aviation Turbine Fuel Volatility:ATF constitutes 35-45% of airline operating costs. Carriers pass through fare instability, compressing OTA commission buffers on domestic routes.
- Fragmented Hotel Supply:Unorganized single-property operators in tier-2 cities lack channel manager adoption. Inventory visibility gaps force platforms to maintain manual reconciliation teams.
- BIS Data Localization Mandates:Server infrastructure requirements add 15-20% to foreign platform compliance costs. Some global OTAs delay India-specific feature rollouts.
Strategic Opportunities
- Medical Tourism Packaging:Chennai and Hyderabad hospital networks seek bundled accommodation-transportation contracts. Platforms can capture high-margin international patient flows.
- Religious Circuit Digitization:Tirupati, Vaishno Devi, and Shirdi darshan bookings remain 60% offline. End-to-end pilgrimage packages with priority access represent untapped wallet share.
- PLI Scheme for Tourism Technology:Domestic software vendors gain production-linked incentives for booking engine development. Indigenous platforms reduce API licensing outflows.
Industry Challenges
- Multilingual Interface Engineering:Vernacular search in Tamil, Telugu, and Marathi requires NLP training data scarcity resolution. Platforms struggle with dialect variation accuracy.
- Legacy PMS Integration:Mid-tier hotels operate 15-year-old property management systems without open APIs. Real-time inventory synchronization demands expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Online Travel Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $88.69 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Flight Booking, Hotel Reservation, Package Tours, Car Rentals Customer Type: Leisure Travelers, Business Travelers, Group Travelers, Solo Adventurers Technology: Mobile Apps, Online Portals, Chatbots, AI-Powered Recommendations Payment Method: Credit/Debit Cards, Digital Wallets, Net Banking, UPI |
| Companies Covered | Cleartrip, OYO Rooms, MakeMyTrip Limited, Airbnb, Booking Holdings, Yatra Online, Ixigo, Thomas Cook (India), EaseMyTrip, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Online Travel Market Shifts & Advancements
Artificial intelligence layers are compressing the discovery-to-transaction funnel, while regulatory pressure on data localization and open network protocols restructures platform architecture decisions.
Generative itinerary builders are unifying fragmented supplier APIs into conversational booking interfaces. Tier-2 city travelers adopt these tools three times faster than metro users. The technology is unifying search, comparison, and payment into single-thread interactions, collapsing traditional category silos.
RBI's Account Aggregator framework mandates consent-based financial data sharing for travel financing products. Lenders now underwrite pay-later products against verified bank transaction histories. EMI penetration in holiday bookings accelerates fastest in Karnataka and Maharashtra where AA adoption concentrates.
Mobile-first discovery has inverted the traditional desktop-planning behavior. Younger travelers in tier-3 cities complete entire booking journeys on smartphones without laptop comparison. This shift compresses consideration windows and rewards platforms with sub-two-second load times, disadvantaging heavy image-dependent interfaces.
India Online Travel Market Segmentation
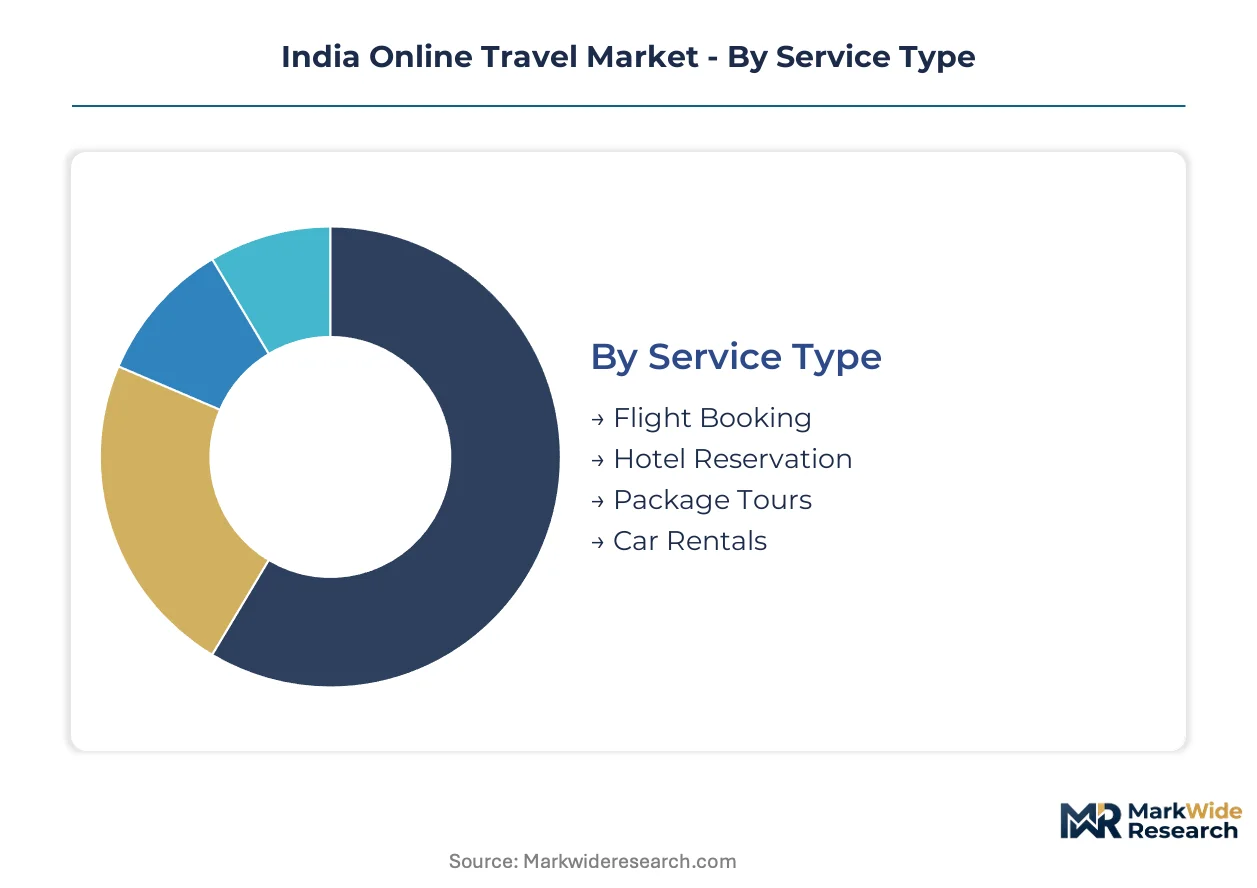
India's online travel market fragments across four intersecting dimensions that determine platform architecture and monetization models. Service type dictates API integration complexity, while customer type shapes retention economics and repeat booking frequency.
Service Type:
Standalone transaction modules dominate high-frequency bookings, whereas embedded package systems capture bundled margin through inventory opacity.
- Flight Booking:Real-time GDS and NDC API integrations process domestic and international air inventory with sub-three-second latency. Maharashtra and Karnataka routes generate the highest search-to-book conversion as airport capacity expansion in these states reduces fare volatility.
- Hotel Reservation:Channel manager connections aggregate budget aggregator networks and direct franchise inventory across tier-2 city supply. Tamil Nadu's hospitality capacity buildup concentrates mid-tier property listings, though fragmented single-property operators in smaller cities create manual reconciliation overhead.
- Package Tours:Bundled opaque inventory through captive supplier contracts extracts premium commissions.
- Car Rentals:Intercity route packaging with rail-air multimodal integration addresses last-mile connectivity gaps.
Volume placements concentrate in Flight Booking; the faster expansion belongs to Package Tours.
Customer Type:
Cost tier stratification separates high-consideration leisure planners from friction-sensitive business bookers.
- Leisure Travelers:Extended research windows and price-sensitive comparison behavior across multiple platforms. Tier-2 and tier-3 city demand acceleration from UDAN route connectivity reshapes platform marketing spend allocation toward vernacular interface development.
- Business Travelers:Corporate negotiated rate programs and expense management system integrations drive loyalty program stickiness. GST-compliant invoice automation and policy enforcement tools determine platform selection for enterprise accounts.
- Group Travelers:Bulk booking workflows and split payment functionality requirements.
- Solo Adventurers:Experience-led discovery patterns and flexible cancellation preference.
Leisure Travelers anchor current transaction volume; Business Travelers are gaining share fastest through corporate digitization mandates.
Technology:
Application maturity separates mass-market mobile interfaces from emerging conversational layers.
- Mobile Apps:Native smartphone applications process complete booking journeys without desktop crossover, particularly in tier-3 cities where smartphone penetration outpaces laptop ownership. RBI's UPI infrastructure enables one-tap payment completion within app environments.
- AI-Powered Recommendations:Personalized itinerary ranking engines convert browse-to-book rates through behavioral prediction models. These systems train on vernacular search patterns where Tamil, Telugu, and Marathi NLP capabilities create competitive differentiation.
- Online Portals:Responsive web interfaces serving comparison-heavy research phases.
- Chatbots:Conversational interfaces reducing customer service touchpoints for routine queries.
Mobile Apps dominate current user sessions; AI-Powered Recommendations show the steepest expansion trajectory as platforms invest in conversion optimization.
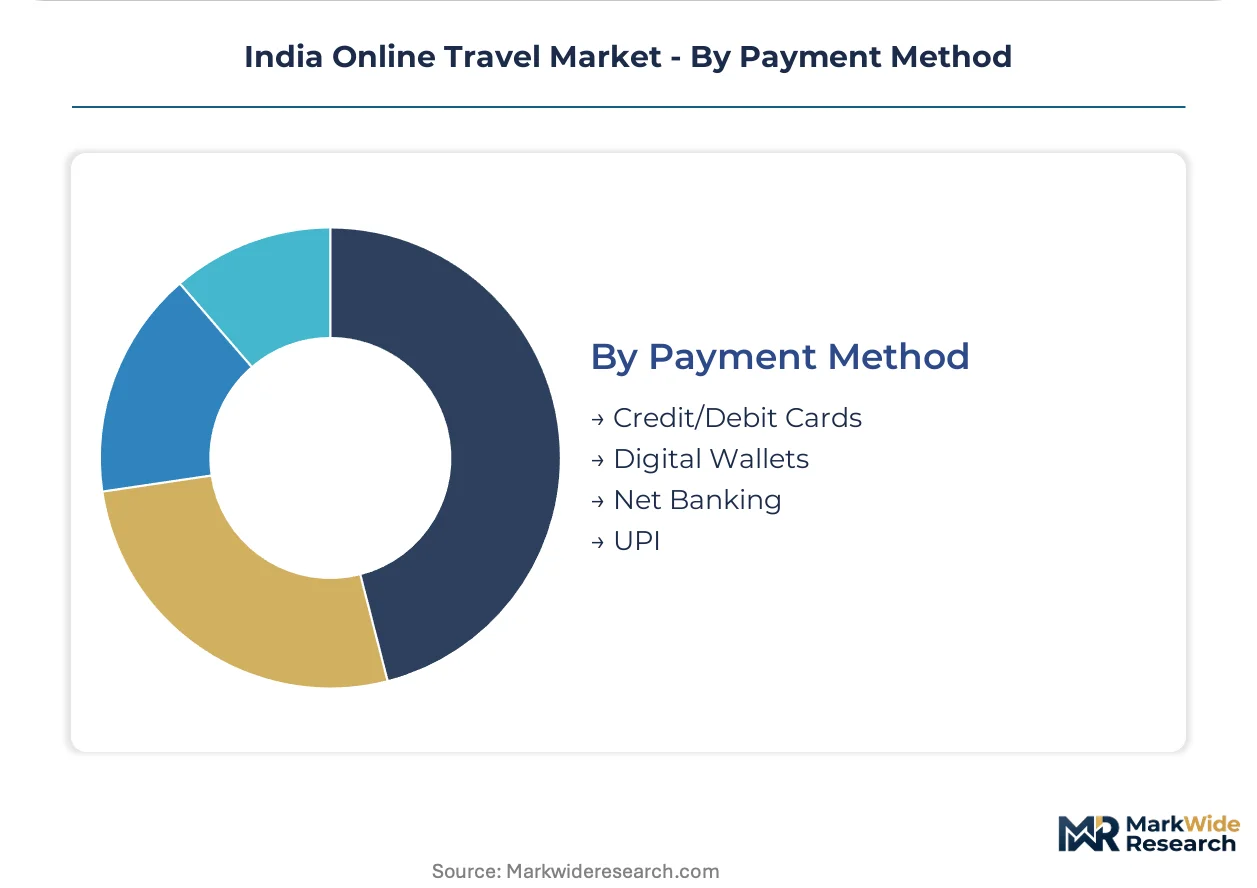
Payment Method:
Settlement infrastructure maturity determines platform onboarding friction and confirmation speed.
- UPI:Real-time settlement through RBI's digital rails compresses booking confirmation from hours to seconds. The infrastructure's international expansion is beginning to alter cross-border booking settlement flows for inbound tourism.
- Digital Wallets:Stored-value instruments with loyalty point integration and travel-specific financing products. Account Aggregator framework consent-based data sharing enables pay-later underwriting against verified bank histories.
- Credit/Debit Cards:Traditional card networks with EMI conversion options for high-ticket holiday bookings.
- Net Banking:Direct bank transfer interfaces for security-conscious segments.
UPI commands the highest transaction volume; Digital Wallets are climbing the fastest through integrated financing product adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's aviation infrastructure anchors India's online travel expansion, with Chhatrapati Shivaji Maharaj International Airport processing the highest OTA search volumes nationwide. Karnataka and Tamil Nadu follow as secondary demand clusters where hospitality capacity additions reshape platform inventory distribution.
Maharashtra
Mumbai-Pune corridor leisure travelers drive the highest flight-hotel bundled transaction frequency on domestic platforms. UDAN scheme connectivity additions at Shirdi and Jalgaon airports unlock tier-3 city demand previously captured by offline agents. Thane and Nashik hotel aggregators now list inventory through channel manager APIs that reduce reconciliation lag to under four hours.
Karnataka
Bengaluru's corporate travel digitization mandates push enterprise accounts toward GST-compliant booking platforms with policy enforcement tools. RBI's Account Aggregator framework adoption concentrates here, enabling pay-later underwriting against verified bank histories for holiday EMI products. Mysuru and Mangaluru leisure routes sustain year-round load factors above 70 percent through OTA-exclusive fare inventory.
Tamil Nadu
Chennai's medical tourism networks seek bundled accommodation-transportation contracts from platforms capturing international patient flows. BIS data localization compliance costs reshape how foreign platforms architect server infrastructure for this state's user base. Coimbatore and Madurai UDAN routes now process real-time UPI settlements that compress confirmation windows to under ten seconds.
Telangana
Hyderabad's hospital clusters generate high-margin inbound tourism packaging opportunities for platforms with captive supplier contracts. TRAI's telecom infrastructure oversight underpins mobile app delivery across the state's tiered connectivity landscape. Warangal and Karimnagar religious circuit digitization remains underpenetrated, with Tirupati-bound pilgrimage bookings still 60 percent offline.
Delhi-NCR
National Capital Region business travelers anchor corporate negotiated rate program volumes with expense management system integrations. DGFT cross-border settlement frameworks intersect with UPI's international expansion to alter inbound tourism payment flows. Gurugram and Noida hotel supply chains restructure around budget aggregator networks with asset-light franchise contracts.
India Online Travel Market Competitive Landscape
Established platforms occupy the standard tier; emerging entrants pursue vernacular interface specialization and religious circuit digitization. The vendor base concentrates around three strategic archetypes: full-service OTAs with captive airline partnerships, budget hotel aggregators with asset-light supply contracts, and rail-air multimodal specialists with proprietary fare prediction engines. Competitive moves center on API convergence investments and tier-2 city franchise expansion programs.
Within the full-service OTA tier, MakeMyTrip Limited and Yatra Online represent the dominant interstate route packaging capability. Ixigo occupies a distinct position as a rail-air multimodal specialist. OYO Rooms anchors extended-stay supply aggregation through franchise contracts concentrated in tier-2 city markets. These three entities exemplify how platform architecture decisions diverge across flight-centric, hotel-centric, and multimodal search specializations.
| Leading Market Players |
|---|
| Cleartrip |
| OYO Rooms |
| MakeMyTrip Limited |
| Airbnb |
| Booking Holdings |
| Yatra Online |
| Ixigo |
| Thomas Cook (India) |
| EaseMyTrip |
| Others |
Supply & Pricing Matrix
Tier-2 city leisure travelers dominate transaction volumes and anchor a commission-based pricing model where platforms extract margin through inventory bundling rather than transparent fee structures. Their price-sensitive comparison behavior across multiple apps compresses standalone booking fees while amplifying demand for opaque package premiums.
Pricing Analysis
Service-bundling separates base transaction fees from value-added layers including cancellation protection, fare prediction guarantees, and loyalty acceleration. Price differentiation rests on booking window timing and inventory opacity, with last-minute domestic routes commanding premium markups over advance-purchase seats. Cost compression in airline commission tiers is intensifying because carriers negotiate direct channel incentives that bypass OTA intermediation. Leisure travelers in tier-3 cities exhibit highest price sensitivity, while corporate accounts with negotiated rate programs show least elasticity due to policy compliance requirements.
Supply Chain Analysis
BIS data localization mandates reshape how foreign platforms architect server infrastructure, forcing domestic data center sourcing that elevates compliance overhead. Inventory feeds draw from GDS providers in United States and Europe, NDC airline connections, and direct hotel channel manager integrations concentrated in India and Southeast Asia. Supply chain risk centers on single-source vulnerability where IRCTC rail inventory monopoly limits multimodal platform flexibility. Distribution runs through API-first mobile architectures with embedded UPI settlement rails replacing legacy card-based reconciliation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around platforms with captive airline partnerships and proprietary fare engines, as regulatory compliance costs and API infrastructure investments force sub-scale operators toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from direct airline NDC channel expansion by deepening vertical integration into budget hotel supply through asset-light franchise contracts. Lock in tier-2 city property exclusivity before emerging entrants capture vernacular-language search traffic. RBI's Account Aggregator framework adoption creates a data moat for pay-later underwriting capabilities that smaller rivals cannot replicate. For New Entrants and Emerging Players: PLI scheme for tourism technology in India opens a window for indigenous booking engine development that reduces API licensing outflows to foreign GDS providers. Religious circuit digitization in Telangana and Tamil Nadu represents the most penetrable white-space target, with Tirupati-bound pilgrimage bookings still majority-offline. Pursue vernacular NLP specialization as the primary go-to-market angle, training models on Marathi and Telugu dialect variation where incumbents struggle. For Investors and Strategic Acquirers: The window for entry favors rail-air multimodal specialists with proprietary fare prediction algorithms and established IRCTC feed relationships. Long-term viability hinges on regulatory compliance architecture that survives BIS data localization enforcement and RBI payment aggregator licensing evolution. Watch UPI international expansion pace as the inflection signal determining cross-border inbound tourism settlement capability.| Strategic Initiative | Industry Significance |
|---|---|
| API Convergence Investment | NDC and IRCTC feed unification enables single-search itinerary completion without platform switching. |
| Vernacular Interface Development | Tamil, Telugu, and Marathi NLP capabilities capture tier-2 and tier-3 city leisure demand acceleration. |
| Captive Hotel Supply Contracts | Asset-light franchise agreements in tier-2 cities lock in extended-stay inventory before competitor aggregation. |
| Account Aggregator Integration | RBI-mandated consent-based financial data sharing enables pay-later underwriting against verified bank histories. |
| Religious Circuit Digitization | End-to-end pilgrimage packages with priority darshan access capture offline wallet share in underpenetrated corridors. |
Research Methodology
Regulatory filings from RBI, TRAI, and BIS, aviation authority route data, and hospitality industry association reports formed the secondary backbone for market sizing and policy trajectory assessment. Primary interviews with OTA platform executives, airline distribution strategists, hotel channel manager operators, and UPI infrastructure architects combined with secondary validation through customs records and SEC filings from listed travel platforms. Bottom-up transaction volume modeling and top-down macroeconomic triangulation anchored the analytical framework.
Historical trendline analysis across domestic aviation passenger growth, UPI transaction velocity, and hotel supply expansion informed projection trajectories throughout the forecast period. Segmentation modeling incorporated service type, customer archetype, technology deployment, and payment method dimensions alongside regional adoption pattern differentials. CAGRs derived from curve-fitting observed growth rates against infrastructure capacity buildout schedules, with UDAN scheme connectivity additions and smartphone penetration curves as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for generative itinerary builders and conversational booking interfaces would alter the outlook for traditional search-to-book conversion metrics. Forecasts reflect assumptions regarding regulatory enforcement consistency, aviation fuel cost stability, and vernacular NLP training data availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market