
 Online Travel Agencies IT Spending Market | 2026-2036
Online Travel Agencies IT Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Online Travel Agencies IT Spending Market Analytics
Asset-light platform leasing is reshaping competitive entry in online travel IT infrastructure, allowing regional challengers to scale without captive data center investment. Booking Holdings leverages extensive cloud partnerships to sustain global reservation throughput across multiple brands. Expedia Group anchors its technology strategy through proprietary property connectivity tools that streamline host onboarding. Trip.com Group dominates Asia-Pacific route density through direct airline API integrations and localized payment rails.
Online Travel Agencies IT Spending encompasses the full technology procurement lifecycle of digital travel intermediaries, spanning cloud infrastructure, customer relationship management software, payment processing systems, and data analytics platforms that process millions of concurrent search and booking transactions with sub-second latency requirements. The primary commercial purpose is to reduce customer acquisition costs while increasing conversion rates through personalized recommendation engines and seamless multi-currency checkout flows. Cloud Solutions within the Service Type category leads absolute spending as OTAs migrate off aging on-premises stacks to elastic compute environments that handle seasonal demand spikes. AI Chatbots under Technology Type represent the fastest-expanding segment, with natural language processing deployments cutting pre-booking service costs while capturing intent data for targeted merchandising. Hybrid Cloud deployments are gaining traction among mid-tier agencies seeking to balance regulatory data residency requirements against public cloud scalability.
The EU AI Act and GDPR impose algorithmic transparency and consent-management obligations on European OTA recommendation engines, directly shaping machine learning procurement specifications. In the United States, the FTC scrutinizes dynamic pricing disclosures while state-level biometric laws constrain facial recognition deployments at airport check-in integrations. China's SAMR and personal information protection standards govern cross-border data flows for multinational platforms operating local entities. Stakeholders must monitor emerging algorithmic accountability frameworks that could redefine competitive advantage from prediction accuracy to explainability standards.
Market Dynamics
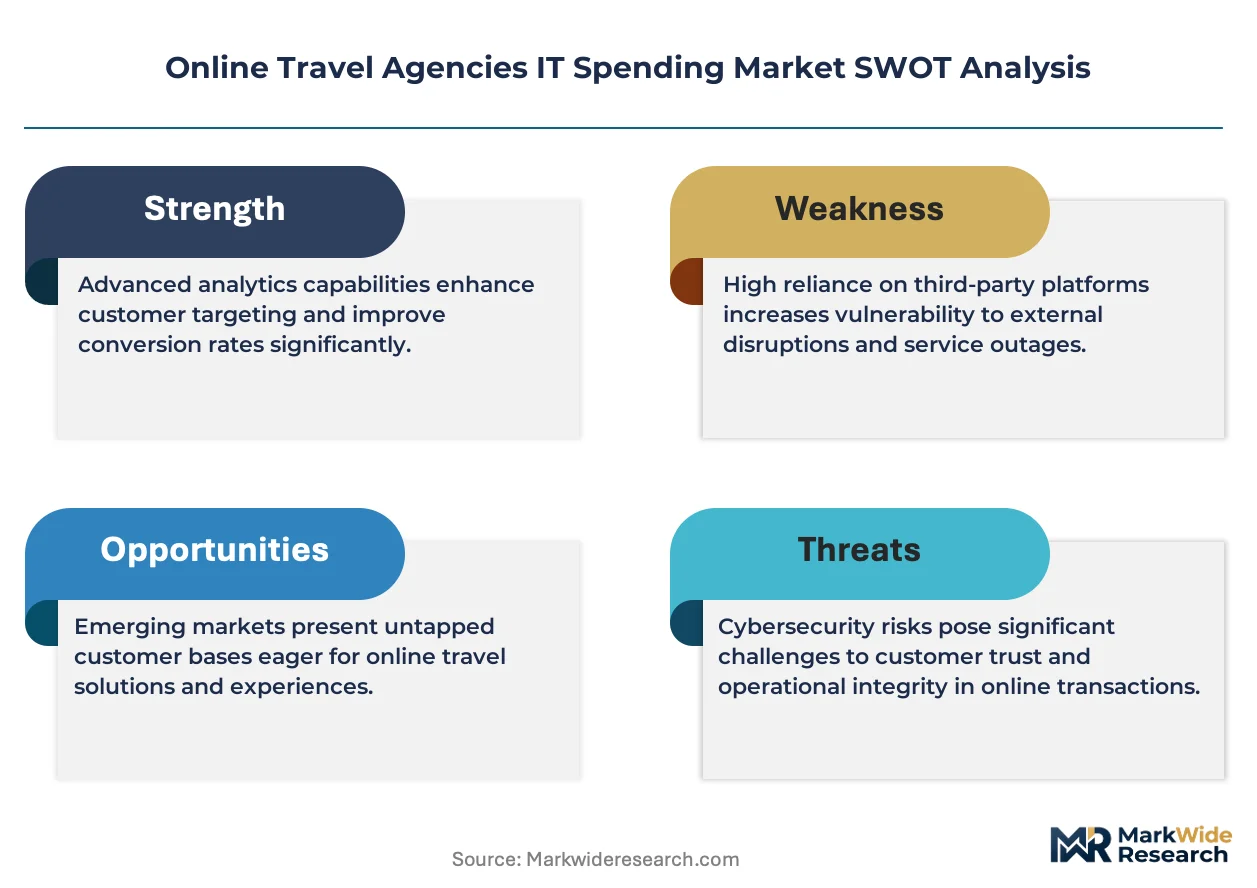
Cloud migration mandates under Europe's GDPR and the EU AI Act are forcing OTAs to replace legacy reservation stacks with elastic infrastructure that balances compliance costs against conversion optimization.
Growth Catalysts
- Hybrid Work Normalization:Corporate travel management platforms are expanding IT procurement as distributed teams sustain business trip booking patterns that require automated policy enforcement.
- EU AI Act Algorithmic Rules:Mandatory transparency obligations for recommendation engines are accelerating procurement of explainable machine learning tools that audit pricing logic.
- Asia-Pacific Payment Rails:Direct airline API integrations and localized checkout systems are concentrating procurement spend in markets with fragmented banking infrastructure.
Market Restraints
- GDPR Data Residency Costs:Strict localization requirements impose redundant infrastructure spend for platforms operating across European member states.
- Biometric Recognition Bans:US state-level facial recognition restrictions constrain airport check-in integration deployments that rely on identity verification automation.
- Cloud Concentration Risk:Dependency on three hyperscale providers creates single-point-of-failure exposure for reservation systems requiring sub-second latency.
Strategic Opportunities
- Mid-Tier Hybrid Cloud:Regional challengers seeking to balance regulatory data residency against public cloud scalability represent underserved infrastructure demand.
- Natural Language Processing Convergence:AI chatbots integrating with property management APIs create white space for intent-capture tools that reduce pre-booking service costs.
- India Digital Payment Expansion:Unified Payments Interface integration offers procurement growth for platforms targeting domestic route density without legacy card network dependencies.
Industry Challenges
- Legacy Reservation Integration:Decades-old mainframe systems resist API modernization, forcing parallel infrastructure runs that duplicate operational overhead.
- Algorithmic Accountability Talent Scarcity:Shortage of compliance engineers capable of auditing machine learning models against emerging transparency standards delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Travel Agencies IT Spending Market |
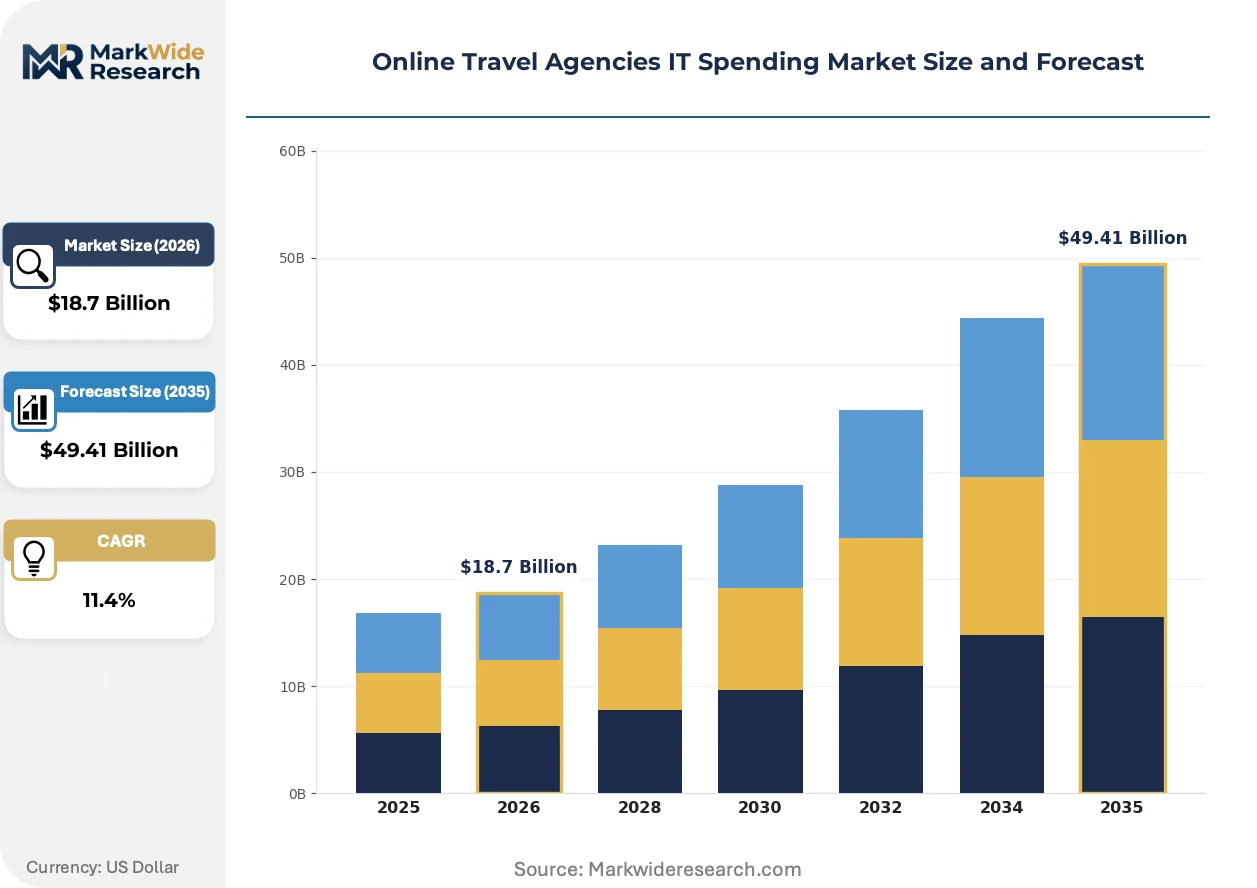
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Solutions, CRM Software, Payment Processing, Data Analytics Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Customer Type: Leisure Travelers, Business Travelers, Travel Agencies, Tour Operators Technology Type: Mobile Applications, Web Platforms, AI Chatbots, Virtual Reality |
| Companies Covered | Trip.com Group, Traveloka, Booking Holdings, Despegar, eDreams ODIGEO, Expedia Group, MakeMyTrip, Hopper, Airbnb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Travel Agencies IT Spending Market Evolving Landscape
IT procurement patterns are fragmenting across compliance-driven replacement cycles, AI-augmented service automation, and infrastructure strategies that segment data by jurisdictional risk.
Edge computing for real-time fare caching is hybridizing reservation architectures. Mid-tier OTAs are adopting distributed nodes to reduce round-trip latency for price-sensitive leisure segments. This topology is hybridizing the traditional hub-and-spoke cloud model into mesh configurations that localize sensitive passenger data.
REACH chemical restrictions and F-Gas Regulation phase-downs are reshaping data center cooling procurement specifications. European co-location providers face retrofit deadlines that favor liquid immersion systems over traditional HVAC. Facility operators in Germany and the Netherlands are consolidating into certified green energy contracts to preempt operational permit risks.
Buyer concentration among managed travel programs is compressing vendor evaluation cycles. Large corporate accounts now mandate quarterly API performance audits that displace annual contract renewals. This pattern is most visible in US financial services verticals where procurement teams unbundle booking platforms from expense management systems.
Online Travel Agencies IT Spending Market Segmentation
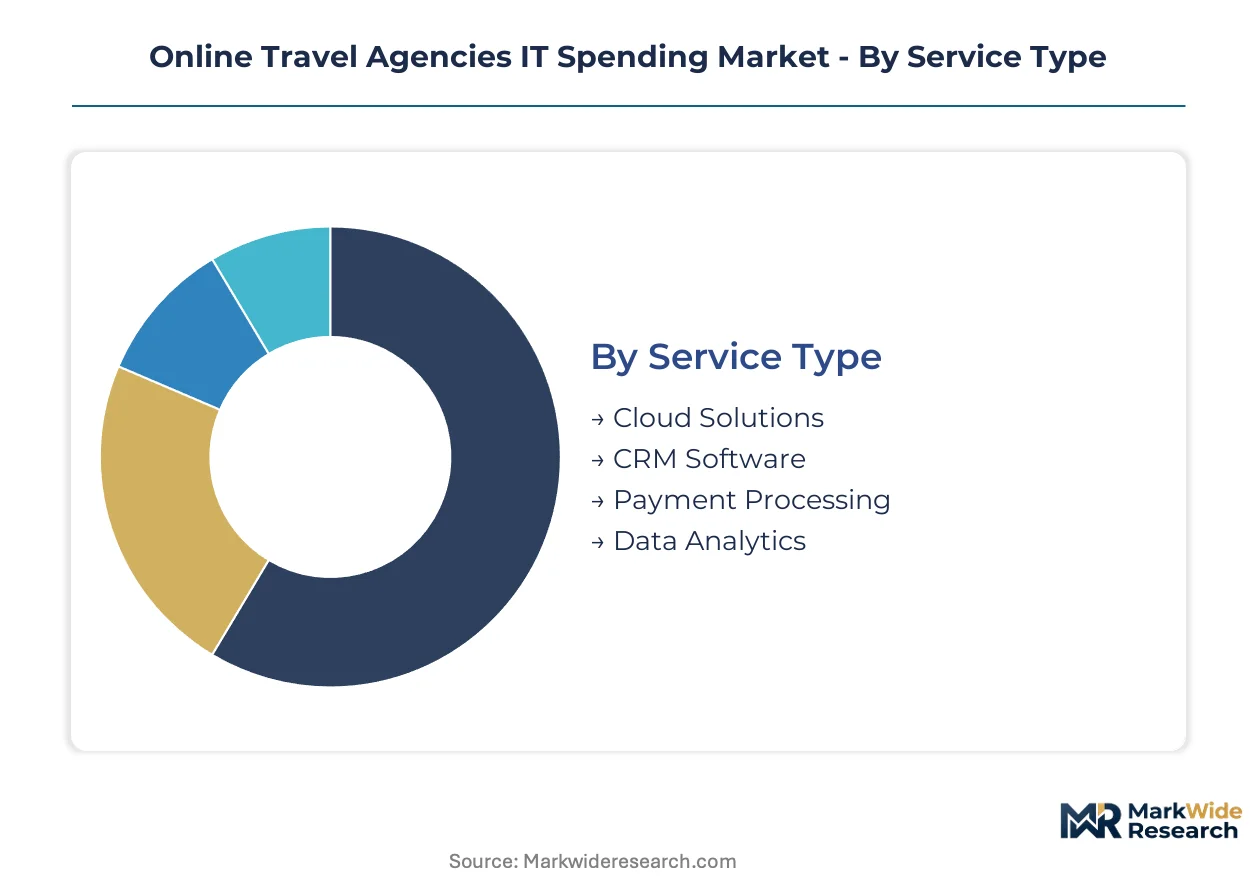
IT procurement patterns across online travel agencies fragment sharply by operational function, infrastructure maturity, and traveler segment requirements. Each segmentation dimension reveals distinct spending priorities that shape vendor selection criteria and deployment timelines.
Service Type:
Cloud Solutions commands the largest procurement envelopes as elastic infrastructure replaces fixed-capacity data centers. CRM Software investments concentrate in loyalty program modernization and automated re-engagement workflows. Payment Processing spending tracks cross-border transaction volume growth and multi-currency settlement complexity. Data Analytics procurement accelerates around real-time personalization engines and demand forecasting models.
- Cloud Solutions:Elastic compute environments handle seasonal demand spikes without stranded capacity. United States-based OTAs lead procurement volume as legacy reservation infrastructure modernization drives forklift migrations to hyperscale environments.
- CRM Software:Customer lifecycle management platforms integrate booking history with predictive intent scoring. Business traveler segments in Germany and France generate concentrated demand for automated policy compliance and traveler safety tracking modules.
- Payment Processing:Multi-currency checkout rails with localized fraud detection.
- Data Analytics:Real-time merchandising engines processing search-to-booking conversion funnels.
Established volume favors Cloud Solutions; emerging adoption favors Data Analytics.
Deployment Model:
Infrastructure topology choices reflect jurisdictional data residency requirements against scalability economics. Public Cloud dominates greenfield deployments while Hybrid Cloud captures compliance-sensitive workloads.
- Hybrid Cloud:Segmented architectures isolate passenger PII in private nodes while bursting transaction processing to public environments. European OTAs facing GDPR localization mandates drive procurement concentration in Germany, France, and the Netherlands.
- Public Cloud:Fully outsourced infrastructure eliminates data center capital expenditure for mid-tier agencies. India and Southeast Asia-based platforms represent the fastest-expanding geography as digital payment integration demands elastic scaling without captive facility investment.
- On-Premises:Legacy mainframe continuity for decades-old reservation systems resisting API abstraction.
- Private Cloud:Dedicated single-tenant environments for sovereign cloud requirements in regulated jurisdictions.
Procurement momentum concentrates in Hybrid Cloud configurations balancing regulatory compliance against operational agility.
Customer Type:
End-user segmentation determines feature prioritization and integration depth with external travel supplier systems.
- Business Travelers:Managed travel programs demand automated policy enforcement, duty-of-care tracking, and consolidated expense reporting. United States financial services verticals compress vendor evaluation cycles through quarterly API performance audits.
- Leisure Travelers:Price-sensitive segments drive investment in real-time fare caching and mobile-first booking flows. Latin American and Southeast Asian markets show steepest expansion trajectory as first-time digital travel adoption accelerates.
- Travel Agencies:White-label platform procurement for offline-to-online transition.
- Tour Operators:Package inventory management with dynamic component bundling.
Business Traveler segments anchor annual contract value; Leisure Traveler volume scales transaction density.
Technology Type:
Interface and automation technologies compete for R&D allocation based on conversion impact and service cost reduction potential.
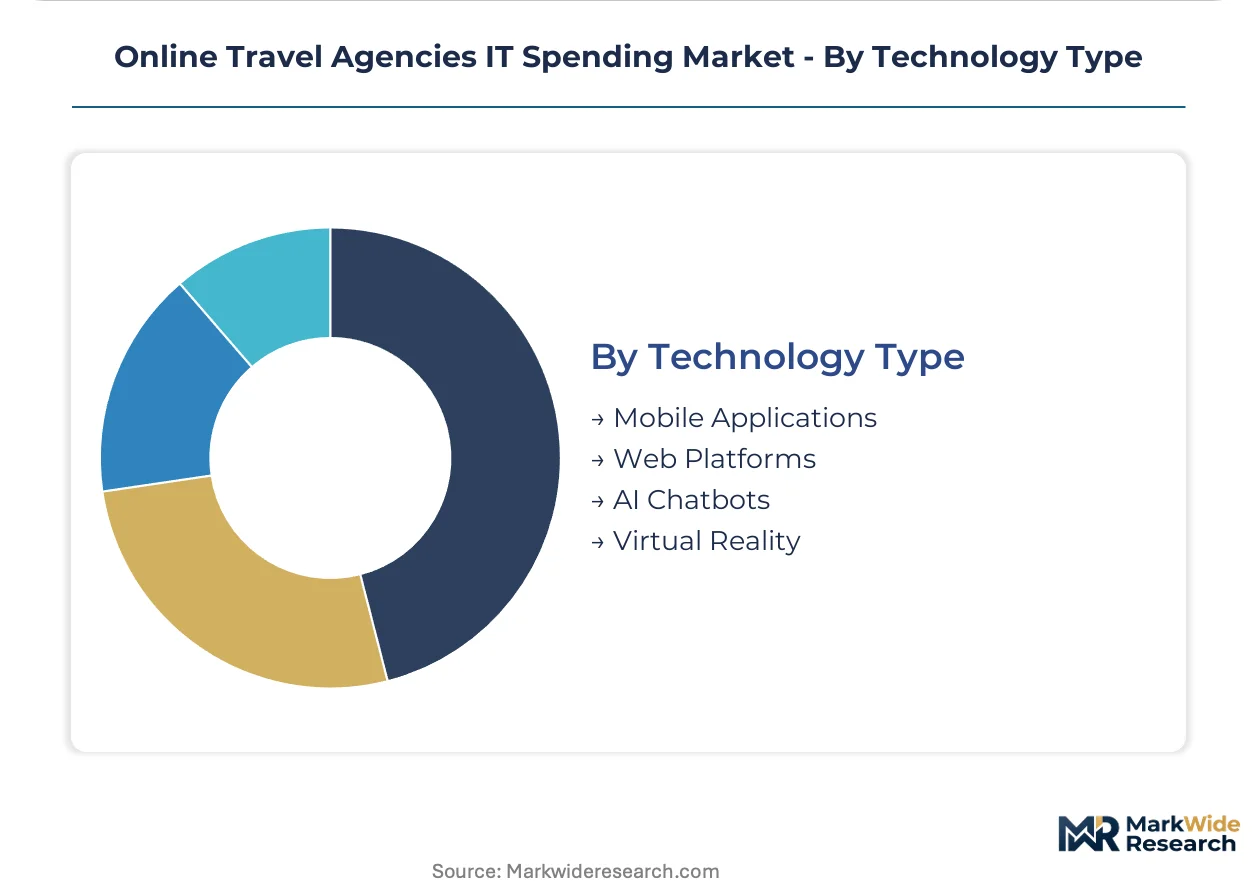
- AI Chatbots:Natural language processing deployments cut pre-booking service costs while capturing search intent for targeted merchandising. Deployment concentrates in Asia-Pacific markets with high mobile messaging platform penetration and fragmented human agent availability.
- Mobile Applications:Native app development prioritizes biometric authentication and wallet-integrated checkout. India and Brazil lead procurement volume as super-app convergence drives travel booking into financial services platforms.
- Web Platforms:Responsive design maintaining parity with native app feature sets.
- Virtual Reality:Immersive property previews for premium accommodation segments.
AI Chatbots gain share fastest in cost-sensitive service automation; Mobile Applications defend booking funnel ownership against platform intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement teams in the United States drive the largest IT spending envelopes for online travel agencies, while European compliance mandates and Asia-Pacific payment fragmentation create distinct regional investment patterns.
United States
Financial services verticals compress vendor evaluation cycles through quarterly API performance audits that displace annual contract renewals. The FTC scrutinizes dynamic pricing disclosures while state-level biometric laws constrain facial recognition deployments at airport check-in integrations. Silicon Valley clusters anchor cloud migration projects for legacy reservation infrastructure modernization.
Germany
REACH chemical restrictions and F-Gas Regulation phase-downs reshape data center cooling procurement specifications for co-location providers. GDPR data residency requirements impose redundant infrastructure spend for platforms operating across European member states. Frankfurt's financial district concentrates managed travel program procurement with automated policy enforcement mandates.
India
Unified Payments Interface integration offers procurement growth for platforms targeting domestic route density without legacy card network dependencies. RBI guidelines govern cross-border data flows for multinational platforms operating local entities. Bangalore and Mumbai clusters lead mobile-first booking flow investments as super-app convergence drives travel into financial services platforms.
China
SAMR and personal information protection standards govern cross-border data flows for multinational platforms operating local entities. Direct airline API integrations concentrate procurement spend in markets with fragmented banking infrastructure. Shanghai and Beijing anchor technology development for AI chatbots processing search intent for targeted merchandising.
United Kingdom
Corporate travel management platforms expand IT procurement as distributed teams sustain business trip booking patterns requiring automated policy enforcement. Post-Brexit data adequacy arrangements create parallel compliance architectures for passenger PII processing. London's fintech corridor drives payment processing investments with multi-currency settlement complexity.
Online Travel Agencies IT Spending Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven incumbents face regional challengers leveraging asset-light platform leasing. The vendor base separates into three strategic archetypes: global reservation infrastructure operators, localized payment rail integrators, and AI-augmented service automation specialists. M&A activity concentrates on property connectivity tools and airline API portfolios, while strategic partnerships dominate cloud migration and compliance technology procurement.
Within the global infrastructure tier, Booking Holdings and Expedia Group occupy positions as scale-driven incumbents with extensive cloud partnerships and proprietary connectivity tools. Trip.com Group exemplifies the regional challenger archetype dominating Asia-Pacific route density through direct airline API integrations. These three entities anchor competitive dynamics across the technology procurement lifecycle.
| Leading Market Players |
|---|
| Trip.com Group |
| Traveloka |
| Booking Holdings |
| Despegar |
| eDreams ODIGEO |
| Expedia Group |
| MakeMyTrip |
| Hopper |
| Airbnb |
| Others |
Value Network & Pricing Analysis
Trans-Pacific fiber-optic cable routes anchor cost dynamics for cloud infrastructure procurement, concentrating supplier leverage among hyperscale providers while forcing downstream price differentiation between latency-sensitive reservation systems and batch-processed analytics workloads.
Pricing Analysis
Cost-plus contracts with CPU/GPU indexation dominate hyperscale infrastructure procurement, insulating providers against silicon volatility while passing through margin pressure to mid-tier agencies. Three-tier pricing structure across premium, standard, and economy levels separates dedicated bare-metal instances from reserved capacity pools and spot-market compute. Pricing pressure stems from cloud concentration risk as three providers control elastic capacity. Budget-constrained regional challengers exhibit highest price sensitivity; enterprise managed travel programs demonstrate lowest due to policy compliance mandates.
Supply Chain Analysis
Export control regimes under US Commerce Department restrictions on advanced GPU shipments to China fragment AI training hardware flows, forcing procurement arbitrage across Singapore and UAE intermediary hubs. Taiwan, South Korea, and the United States concentrate advanced semiconductor fabrication. Supply chains draw from rare earth elements for magnetic storage, high-purity silicon for chip substrates, and liquid cooling fluids for thermal management. Single-source vulnerability concentrates in TSMC's leading-edge node capacity. Distribution runs through direct hyperscale partnerships and certified regional co-location operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards organizations that secure scarce compliance engineering talent capable of auditing machine learning models against algorithmic transparency mandates, creating acquisition premiums for teams with EU AI Act implementation experience.
For Market Incumbents: Entrench hybrid cloud architectures that isolate passenger PII in GDPR-compliant private nodes while bursting transaction processing to public environments. Acquire property connectivity tool vendors before regional challengers consolidate airline API portfolios. Vertical integration into proprietary payment rails defends margin position against fintech platform intermediation. For New Entrants and Emerging Players: Establish a beachhead in India's Unified Payments Interface ecosystem, where domestic route density expansion outpaces legacy card network dependencies. Target mid-tier hybrid cloud configurations balancing regulatory data residency against public cloud scalability. Lead with natural language processing intent-capture tools that reduce pre-booking service costs for cost-sensitive leisure segments. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward explainable machine learning tool vendors with existing OTA deployments. Long-term viability centers on platforms with demonstrated compliance automation rather than prediction accuracy alone. The signal to watch is quarterly API performance audit adoption rates among US financial services verticals as a proxy for procurement centralization.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Deployment | GDPR-compliant architectures balance data residency mandates against elastic scaling for seasonal demand spikes. |
| AI Chatbot Integration | Natural language processing deployments cut pre-booking service costs while capturing intent data for targeted merchandising. |
| Airline API Portfolio Acquisition | Direct carrier integrations concentrate procurement spend in Asia-Pacific markets with fragmented banking infrastructure. |
| Payment Rail Localization | Unified Payments Interface integration unlocks domestic route density without legacy card network dependencies in India. |
| Compliance Engineering Investment | Explainable machine learning tools audit pricing logic against EU AI Act algorithmic transparency obligations. |
Research Methodology
The analysis maps cloud infrastructure procurement, AI service automation, payment processing integration, and data analytics deployment, each validated through CTOs, IT procurement officers, platform engineers, and airline distribution specialists. Primary interviews combine with secondary validation against SEC hyperscaler capex disclosures, EU regulatory filings, and customs trade data for semiconductor equipment. Bottom-up vendor spend estimates triangulate against top-down market sizing across deployment models.
Assumptions hold GDPR enforcement intensity and EU AI Act implementation timelines fixed while varying cloud migration pace and hybrid work normalization trajectories across the projection horizon. Segmentation dimensions span service type, deployment model, customer type, and technology type, with geographic regulatory cluster as an industry-specific overlay. CAGRs derive from elasticity modeling of infrastructure spend against transaction volume growth, incorporating airline API integration rates and payment localization indices as forecast inputs.
Sensitivities concentrate around cloud concentration risk mitigation strategies and algorithmic accountability talent availability. Forecasts reflect documented assumptions regarding compliance cost pass-through and seasonal demand elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market