
 Online Accommodation Booking Market | 2026-2036
Online Accommodation Booking Market Size, Share, and Industry Trends Forecast 2026-2036
Online Accommodation Booking Market Analysis
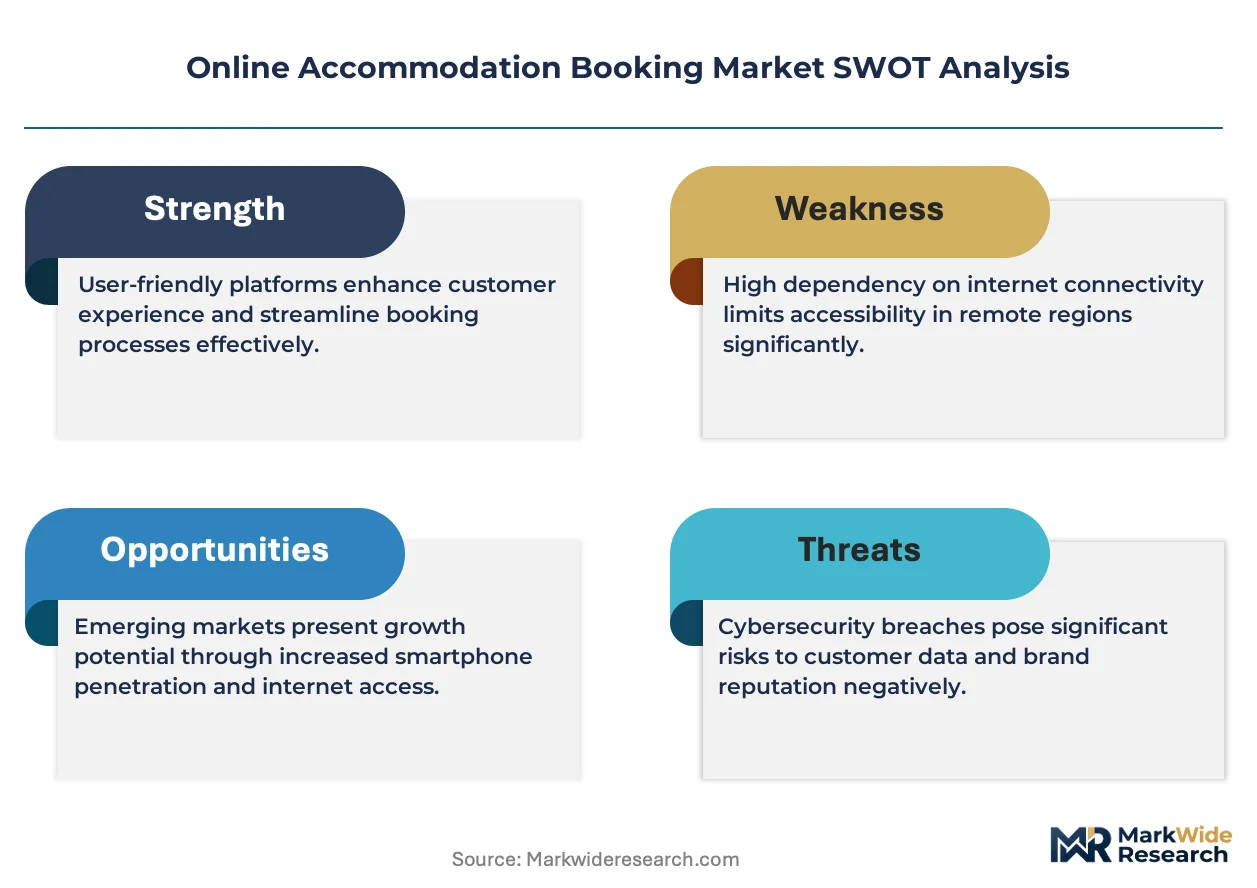
The EU Digital Services Act is realigning how online accommodation platforms manage content moderation and algorithmic transparency across European jurisdictions. Booking.com leverages its direct contracting relationships with property managers to sustain rate parity advantages in key metropolitan markets. Expedia Group anchors its competitive posture through integrated flight-hotel bundling technology that reduces customer acquisition costs. Airbnb differentiates via its host-guest review ecosystem and proprietary trust architecture that controls quality signaling across its inventory base.
Online accommodation booking denotes the digital reservation of temporary lodging inventory through web-based platforms or mobile applications, typically involving real-time availability verification, dynamic rate calculation, and instant confirmation protocols. The primary commercial purpose centers on reducing friction between fragmented lodging supply and dispersed consumer demand while capturing commission or service fee revenue per transaction. Vacation rentals within the Service Type dimension now represent the fastest-growing margin pool as property management software integration enables professionalized host operations at scale. Mobile Apps under Booking Channel lead transaction volume growth in emerging markets where smartphone penetration outpaces desktop access, while Online Travel Agents retain the largest consolidated revenue share through negotiated wholesale rate agreements with branded hotel chains.
The EU Digital Services Act and GDPR collectively impose data governance and transparency obligations that shape platform operational costs and host onboarding procedures across European markets. The US Federal Trade Commission scrutinizes drip pricing and hidden fee disclosures, directly affecting how platforms present total cost estimates to American consumers. Japan's METI maintains specific innkeeper licensing requirements that platforms must verify before listing traditional ryokan properties. Stakeholders must monitor evolving short-term rental caps in Barcelona, Amsterdam, and New York City as municipal enforcement tightens inventory availability in high-demand urban cores.
Market Dynamics
Algorithmic transparency mandates under the EU Digital Services Act are forcing platforms to expose ranking methodologies to hosts, reshaping competitive dynamics across European short-term rental corridors.
Growth Catalysts
- Mobile-first booking penetration:Smartphone transaction volume in Brazil, India, and Indonesia outpaces desktop access, expanding addressable traveler bases beyond traditional credit-card-holding demographics.
- GDPR-driven trust infrastructure:European data governance standards create compliance moats that professionalized property managers leverage to differentiate against informal host competition.
- Urban corridor inventory concentration:Lisbon, Bangkok, and Mexico City short-term rental density attracts cross-border investment in property management software and automated pricing tools.
Market Restraints
- Municipal licensing friction:Barcelona, Amsterdam, and New York City enforcement of short-term rental caps directly constricts platform inventory availability in high-ADR urban cores.
- Payment infrastructure fragmentation:Emerging market cash-on-delivery preferences and local wallet dominance create checkout abandonment at rates exceeding developed market benchmarks.
- Host supply volatility:Discretionary listing behavior by individual property owners generates availability unpredictability that corporate property managers exploit to capture rate parity advantages.
Strategic Opportunities
- Professionalized host tooling:Revenue management systems and dynamic pricing algorithms enable mid-size property managers to scale inventory without proportional operational headcount expansion.
- Flight-hotel bundling integration:Cross-vertical packaging technology reduces customer acquisition costs by capturing travelers at the trip-planning inception point rather than the accommodation-search phase.
- Ryokan and heritage lodging digitization:Japan METI licensing verification workflows, once automated, unlock traditional inventory categories previously excluded from platform distribution.
Industry Challenges
- Algorithmic audit compliance:EU Digital Services Act documentation requirements demand engineering resources that smaller platforms struggle to allocate without margin compression.
- Trust architecture maintenance:Review system integrity against fraudulent host-guest ratings requires continuous machine learning investment that scales with transaction volume.
- Legacy property management system integration:Branded hotel chain central reservation systems resist API standardization, fragmenting connectivity development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Accommodation Booking Market |
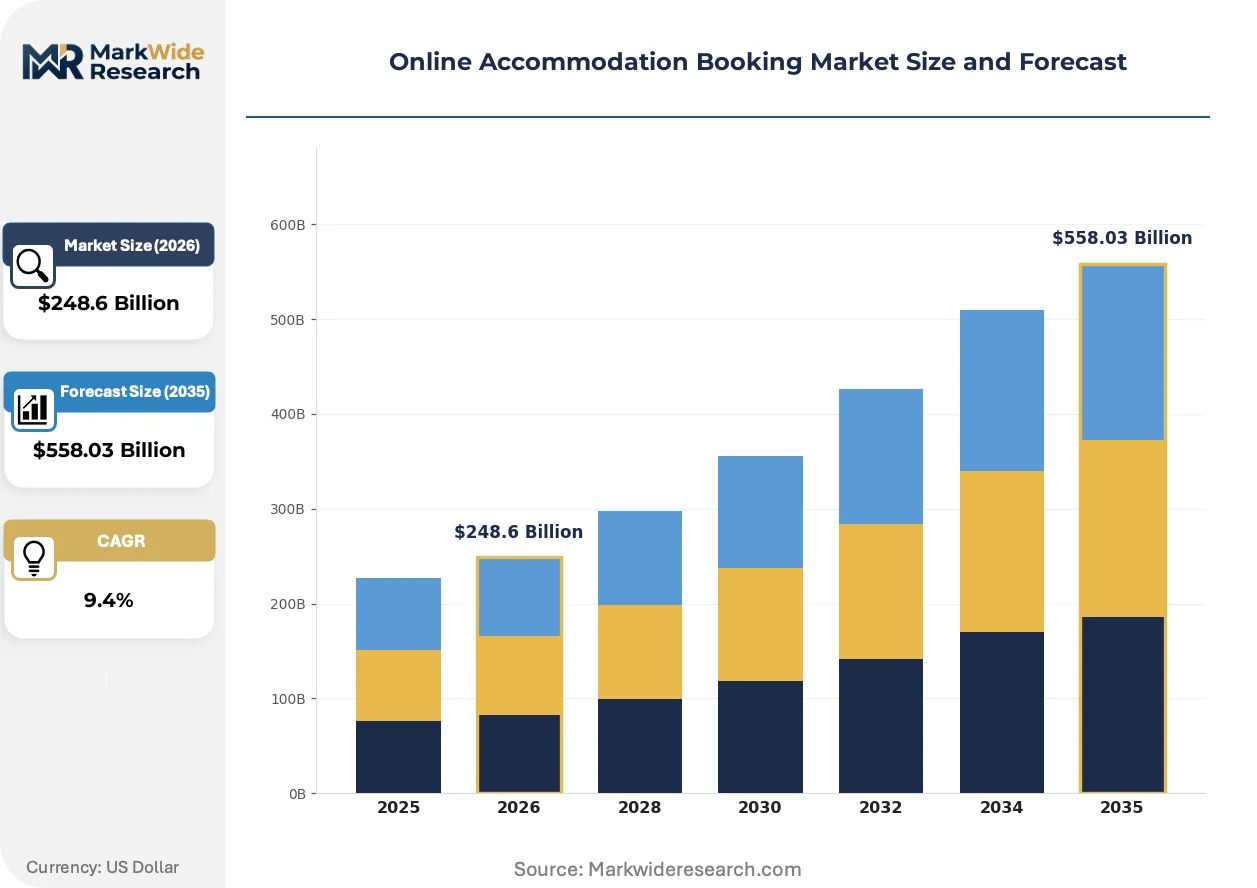
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $558.03 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hotels, Hostels, Vacation Rentals, Bed & Breakfasts Customer Type: Business Travelers, Leisure Travelers, Group Bookings, Long-term Stays Booking Channel: Direct Booking, Online Travel Agents, Mobile Apps, Meta-search Engines Price Tier: Economy, Mid-range, Luxury, Budget |
| Companies Covered | Trip.com Group, Hotels.com, Booking.com, Priceline, MakeMyTrip, Expedia Group, Agoda, Trivago, Airbnb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Accommodation Booking Market Emerging Trajectories
Real-time pricing infrastructure and automated host operations are compressing the operational gap between individual property owners and institutional hospitality operators.
Property management software is unifying channel management, guest communication, and dynamic pricing into single-stack solutions. Professional hosts in Portugal and Thailand adopt these platforms at accelerating velocity. This technology convergence is unifying previously fragmented operational workflows, enabling mid-size managers to compete with branded chains on service consistency.
The EU Digital Services Act disclosure requirements are mandating algorithmic ranking transparency for platforms operating across European jurisdictions. Hosts in France and Germany now receive explanatory documentation on search result positioning. Urban short-term rental operators are responding by diversifying listing presence across multiple platforms to reduce algorithmic dependency.
Leisure traveler booking windows have compressed from multi-week planning cycles to last-minute mobile transactions. Urban corridor demand in Mexico City and Bangkok now concentrates within 72-hour pre-arrival windows. This behavioral shift is most visible in emerging markets where smartphone penetration enables impulse-driven trip construction without desktop research phases.
Online Accommodation Booking Market Segmentation
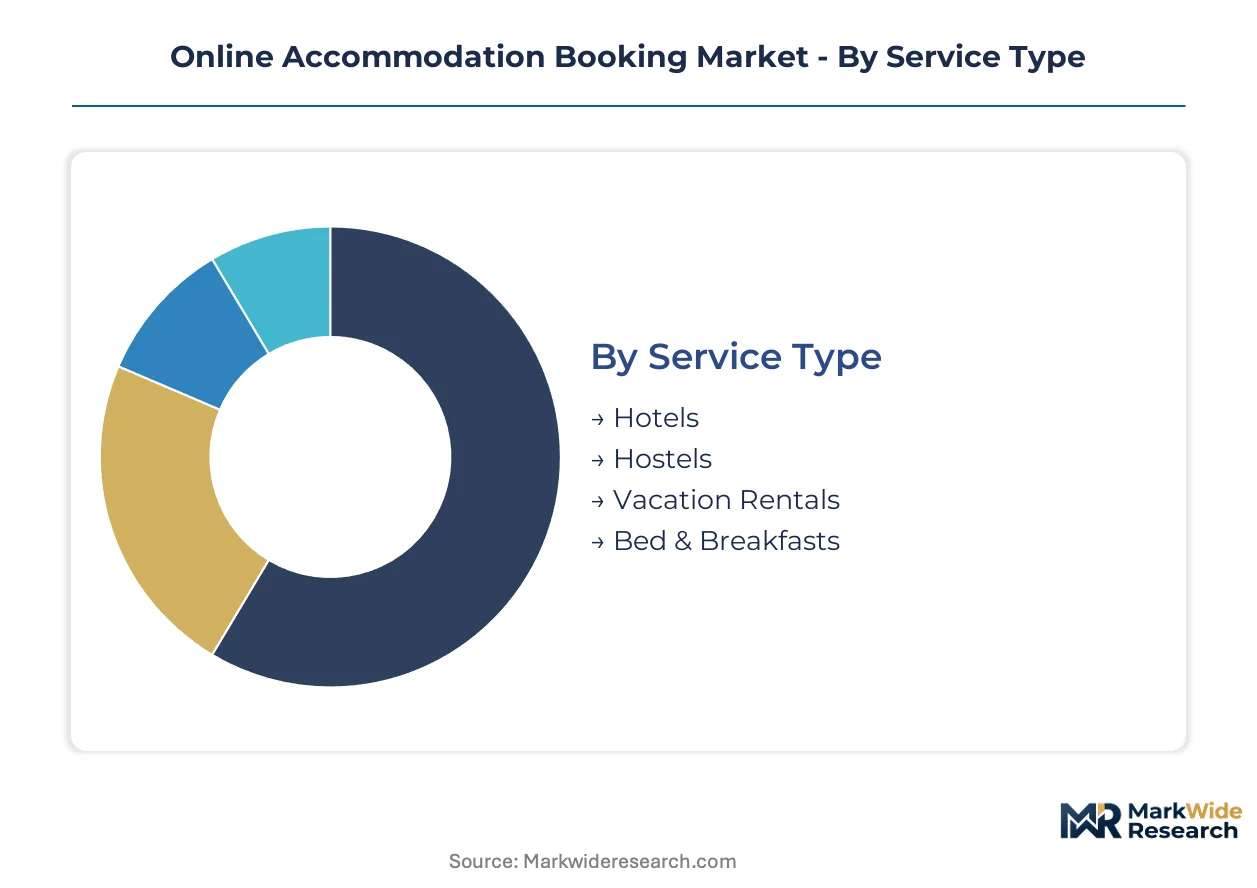
Segmentation in online accommodation booking reveals how platform architecture and traveler behavior fragment across service modalities, device preferences, and price sensitivity thresholds. Each dimension carries distinct margin profiles and operational complexity that shape platform resource allocation and host onboarding strategies.
Service Type:
Property-level operational intensity and inventory standardization create divergent platform economics across lodging categories.
- Hotels:Central reservation systems and standardized amenity protocols enable seamless API connectivity and instant confirmation workflows. Demand concentrates in urban business corridors across Germany and Japan where corporate rate negotiations lock in predictable occupancy. Branded chain consolidation limits host-side volatility but compresses commission margins through volume-based contracting.
- Vacation Rentals:Entire-unit inventory with variable amenity configurations requires proprietary trust architecture and professionalized host tooling to reduce booking friction. Lisbon, Bangkok, and Mexico City corridors attract cross-border investment in property management software as mid-size operators scale inventory without proportional headcount expansion.
- Hostels:Shared-room inventory with bunk-bed density targets budget-conscious solo travelers and student segments in European city centers.
- Bed & Breakfasts:Owner-occupied properties with breakfast-included positioning appeal to experiential leisure travelers seeking localized hospitality in heritage districts.
Mature deployment sits with Hotels. Newer deployment is concentrated in Vacation Rentals.
Customer Type:
Trip purpose and duration length dictate platform interface design, payment timing, and cancellation policy flexibility.
- Leisure Travelers:Discretionary trip planners with compressed booking windows and smartphone-driven impulse transactions now dominate platform traffic across North America and Europe. Mobile-first penetration in Brazil and Indonesia expands addressable bases beyond traditional credit-card demographics.
- Business Travelers:Expense-account-funded bookings with corporate negotiated rates and loyalty program integration sustain higher average daily rates in Frankfurt and Singapore financial districts.
- Group Bookings:Multi-room coordination requirements for events and celebrations generate higher cart values but increase customer service touchpoints.
- Long-term Stays:Extended-duration reservations with monthly rate negotiations attract remote workers and relocation segments in Lisbon and Mexico City urban cores.
Volume leadership belongs to Leisure Travelers. Steepest expansion trajectory attaches to Long-term Stays.
Booking Channel:
Device and platform selection determines customer acquisition cost structures and rate parity enforcement complexity.
- Online Travel Agents:Consolidated inventory aggregation with negotiated wholesale rate agreements captures the largest revenue share through flight-hotel bundling technology that reduces acquisition costs. Direct contracting relationships with property managers sustain rate parity advantages in metropolitan markets.
- Mobile Apps:Smartphone-native interfaces with push-notification pricing alerts and one-tap booking completion lead transaction volume growth in emerging markets. Brazil, India, and Indonesia penetration outpaces desktop access, enabling impulse-driven trip construction.
- Direct Booking:Host-owned websites with zero-commission positioning attract repeat guests but require independent marketing investment.
- Meta-search Engines:Price comparison aggregation across multiple platforms reduces traveler search friction while increasing platform bidding competition for placement.
Revenue concentration rests with Online Travel Agents. Fastest share gains belong to Mobile Apps.
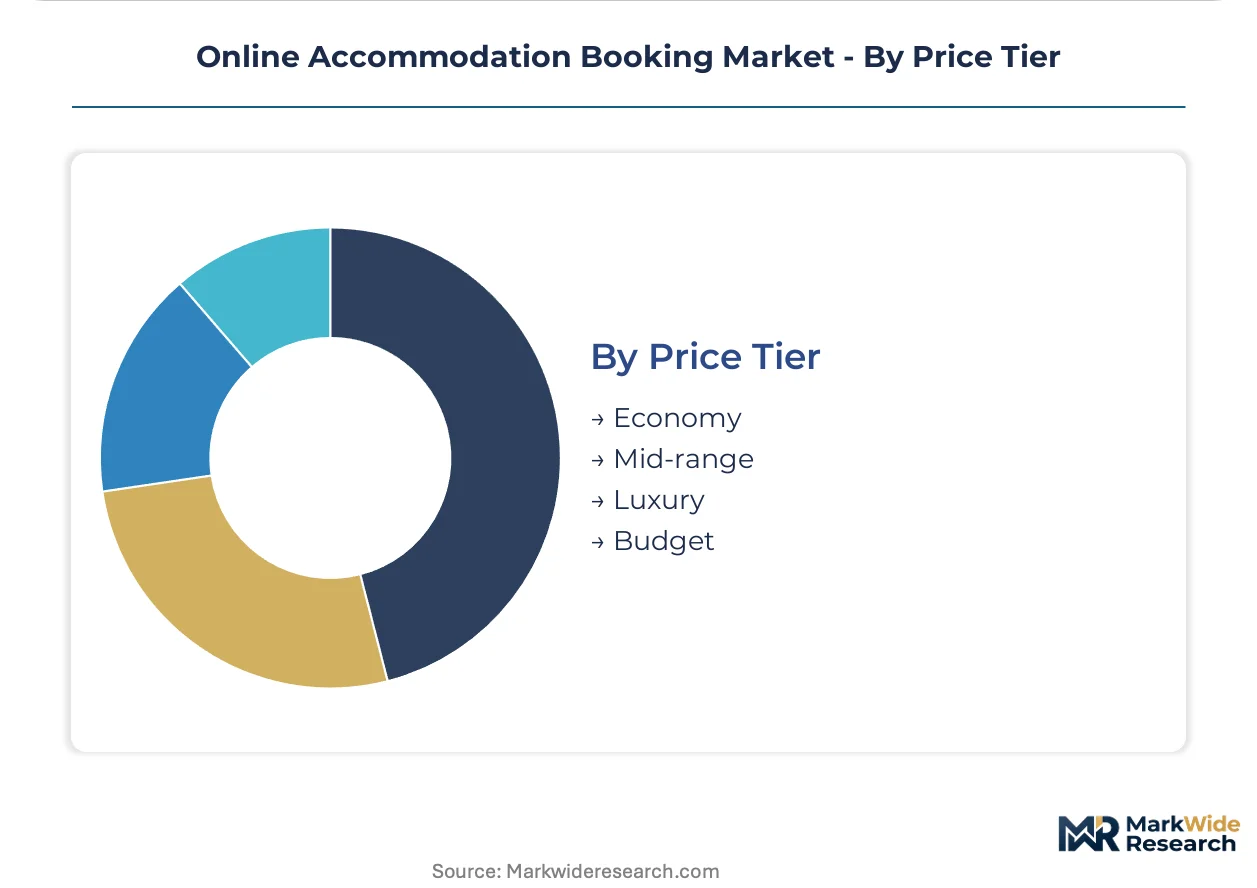
Price Tier:
Rate positioning correlates with service expectation calibration, review sensitivity, and host professionalization requirements.
- Luxury:High-ADR inventory with concierge service integration and amenity standardization commands premium platform commission rates in Paris and Dubai corridors. Trust architecture demands intensify as guest expectation thresholds escalate.
- Mid-range:Three-star equivalent positioning with consistent cleanliness and WiFi reliability attracts the broadest traveler demographic across European urban centers.
- Economy:No-frills lodging with minimal service interaction targets price-sensitive segments in high-density backpacker districts.
- Budget:Ultra-low rate positioning with shared facilities and self-check-in protocols minimizes operational overhead for individual hosts.
Margin optimization concentrates in Luxury. Volume scaling dominates Mid-range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lisbon's short-term rental corridors attract cross-border investment in property management software as leisure travelers compress booking windows to 72-hour pre-arrival cycles. Urban density in Bangkok and Mexico City concentrates platform inventory growth where smartphone penetration outpaces desktop access.
United States
Leisure travelers command dominant platform traffic through mobile-first interfaces in Florida and California coastal markets. The FTC scrutinizes drip pricing disclosures, forcing platforms to present total cost estimates upfront. New York City's short-term rental caps constrict inventory availability in Manhattan's high-ADR urban core.
Germany
Business travelers sustain higher average daily rates in Frankfurt's financial district through corporate negotiated rate agreements. GDPR compliance creates operational moats that professionalized property managers leverage against informal host competition. Berlin's urban corridor faces municipal enforcement tightening inventory availability.
Japan
Experiential leisure travelers seek localized hospitality in heritage districts where traditional ryokan properties command premium positioning. METI maintains specific innkeeper licensing requirements that platforms must verify before listing. Tokyo's Kanto region concentrates mobile transaction volume growth among domestic travelers.
Brazil
Smartphone transaction volume outpaces desktop access, expanding addressable traveler bases beyond traditional credit-card-holding demographics. Local wallet dominance and cash-on-delivery preferences create checkout abandonment challenges. Rio de Janeiro's coastal corridors attract cross-border investment in automated pricing tools.
Thailand
Urban short-term rental density in Bangkok attracts professionalized host tooling adoption at accelerating velocity. Property management software unifies channel management and dynamic pricing for mid-size operators. The country's tourism-dependent economy drives platform commission rate negotiations in Phuket and Chiang Mai resort corridors.
Online Accommodation Booking Market Vendor Landscape
Premium-margin players sit above commodity-margin players across algorithmic trust architecture and direct contracting relationships. The market structures around three tiers: integrated travel conglomerates with flight-hotel bundling technology, pure-play accommodation specialists with proprietary host-guest review ecosystems, and meta-search aggregators dependent on platform bidding competition. Consolidation pressure intensifies as customer acquisition costs escalate. Dominant competitive moves include vertical integration into property management software and cross-vertical packaging technology that captures travelers at trip-planning inception.
Within the integrated conglomerate tier, Booking.com and Expedia Group occupy positions defined by negotiated wholesale rate agreements and direct contracting relationships with property managers. Airbnb exemplifies the pure-play specialist archetype through its host-guest review ecosystem. Trip.com Group anchors the Asia-Pacific expansion vector.
| Leading Market Players |
|---|
| Trip.com Group |
| Hotels.com |
| Booking.com |
| Priceline |
| MakeMyTrip |
| Expedia Group |
| Agoda |
| Trivago |
| Airbnb |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up property management specialists in Lisbon and Bangkok have consolidated fragmented host supply, creating rate parity enforcement power that compresses margins for individual listers while sustaining platform commission structures.
Pricing Analysis
Yield-based pricing anchors platform revenue models, with commission percentages tied to booking value rather than fixed subscription tiers. Price differentiation separates luxury inventory with concierge integration from mid-range standardized units and economy self-check-in properties. Pricing pressure stems from municipal short-term rental caps in Barcelona and New York City that constrict high-ADR urban inventory. Leisure travelers exhibit highest price sensitivity through mobile price-comparison behavior, while business travelers with corporate negotiated rates show lowest sensitivity.
Supply Chain Analysis
Software engineering talent scarcity in Portugal and Thailand constrains property management platform development velocity. Supply concentrates in India for back-end development, the United States for cloud infrastructure, and Germany for data compliance architecture. Raw material dependencies include server hardware, payment gateway APIs, and mapping geolocation services. Single-source vulnerability sits with dominant cloud providers for hosting redundancy. Distribution runs through mobile app stores and direct web platforms to reach end-hosts and travelers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over property management software determines host loyalty and rate parity enforcement power.
For Market Incumbents: Extend direct contracting relationships with professionalized property managers to lock in inventory exclusivity against platform-hopping behavior. Invest in automated pricing algorithm development to match revenue management capabilities that mid-size operators currently source from third-party vendors. Regulatory pressure from EU Digital Services Act transparency mandates demands engineering resource allocation that smaller competitors cannot match. For New Entrants and Emerging Players: AI-powered dynamic pricing tools for individual hosts offer a technology-first wedge against established platform incumbents. Target Brazil and Indonesia where mobile-first booking penetration outpaces incumbent localization efforts. White-space exists in ryokan digitization workflows for Japan's heritage lodging segment. Go-to-market through channel partnerships with regional property management associations rather than direct host acquisition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size property management software specialists in Thailand and Mexico where tourism-dependent economies create valuation compression. Long-term viability hinges on host supply consolidation trends and algorithmic transparency compliance costs across European jurisdictions. Watch municipal enforcement intensity in Barcelona, Amsterdam, and New York City as inventory availability inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Property Management Software Acquisition | Captures host loyalty and rate parity enforcement power against platform competitors. |
| Flight-Hotel Bundling Technology Deployment | Reduces customer acquisition costs by intercepting travelers at trip-planning inception. |
| Ryokan Licensing Verification Automation | Unlocks traditional Japanese inventory previously excluded from platform distribution. |
| Mobile-First Interface Localization | Expands addressable base in Brazil and Indonesia beyond credit-card demographics. |
| Algorithmic Transparency Documentation | Builds compliance moats under EU Digital Services Act that informal hosts cannot replicate. |
Methodological Framework
Multi-period observation of booking window compression, platform commission structures, and host professionalization rates anchored the trend analysis, supplemented by interviews with property management software executives, revenue management specialists, municipal licensing officers, and platform engineering directors. Secondary validation drew from SEC filings of listed travel conglomerates, EU Digital Services Act implementation guidance, Japan METI innkeeper registry data, and customs records for property technology hardware imports. Bottom-up host and traveler segmentation triangulated against top-down platform revenue estimates.
Input-output matrices modeled transaction volume flows across service type, customer segment, booking channel, and price tier dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included smartphone penetration curves in emerging markets and municipal short-term rental enforcement intensity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory restriction scenarios or payment infrastructure disruption in cash-preferred markets. Forecasts reflect documented assumptions on host supply elasticity and platform commission rate stability. Material deviation in EU algorithmic audit timelines or Brazil digital wallet consolidation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market