
 Online Travel Agent Market | 2026-2036
Online Travel Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Online Travel Agent Market Insights
The EU Digital Services Act is recalibrating compliance costs for cross-border travel platforms entering European markets. Booking Holdings leverages its merchant model infrastructure to sustain rate parity advantages across multiple jurisdictions. Expedia Group anchors its competitiveness through supply breadth in vacation rentals and alternative accommodations. Trip.com Group dominates inbound-outbound China corridor inventory through direct airline partnerships.
An online travel agent functions as a digital intermediary aggregating transportation, lodging, and experience inventory through application programming interfaces and global distribution system connections, processing search, comparison, and transaction completion within unified platforms. These platforms reduce search friction and consolidate fragmented supplier ecosystems for consumers and corporate procurement functions. Flight bookings and hotel reservations represent the mature revenue core, while travel packages capture higher margin per transaction through bundled commission stacking. Mobile apps represent the fastest-growing distribution channel, displacing desktop platforms in emerging markets where smartphone penetration exceeds fixed broadband access.
The EU Digital Services Act, GDPR, and CE marking requirements for payment security modules collectively elevate operational compliance thresholds for platform operators serving European consumers. The US FTC monitors deceptive pricing displays and drip-fee disclosure practices, while China's SAMR enforces algorithmic transparency in personalized pricing. Stakeholders must monitor regulatory divergence between data localization mandates and cross-border payment licensing as these rules determine market access feasibility and technology stack architecture.
Market Dynamics
Mobile-first distribution architectures are compressing customer acquisition costs while fragmenting loyalty economics across Southeast Asian corridors. The shift from desktop to smartphone booking interfaces is redrawing platform infrastructure priorities.
Growth Catalysts
- EU Digital Services Act:Platform liability harmonization is creating predictable compliance baselines for cross-border travel intermediaries entering European markets.
- Corporate travel procurement:Enterprise booking platform adoption is expanding as procurement functions consolidate fragmented supplier relationships through unified interfaces.
- Indonesia-Vietnam-Philippines mobile penetration:Smartphone-first travel adoption across these markets is outpacing fixed broadband infrastructure development.
Market Restraints
- GDPR-DSA compliance layering:European data governance obligations create overlapping audit requirements that elevate operational overhead for platform operators.
- Payment security module certification:CE marking requirements for embedded payment systems extend hardware procurement cycles and vendor qualification timelines.
- Direct airline inventory disintermediation:Carrier native apps and loyalty program direct booking incentives threaten platform commission capture on high-frequency routes.
Strategic Opportunities
- Vietnam domestic tourism infrastructure:Underdeveloped hotel property management system connectivity creates first-mover consolidation potential for platform aggregators.
- China outbound corridor recovery:Direct airline partnership structures with Chinese carriers offer exclusive inventory access as cross-border mobility normalizes.
- Alternative accommodation supply:Vacation rental inventory expansion into secondary European cities captures margin premium through bundled experience packaging.
Industry Challenges
- API standardization fragmentation:Property management system integration protocols vary across Southeast Asian markets, forcing redundant connector development.
- Algorithmic pricing transparency mandates:China's SAMR enforcement of personalized pricing disclosure requirements complicates dynamic yield management system architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Travel Agent Market |
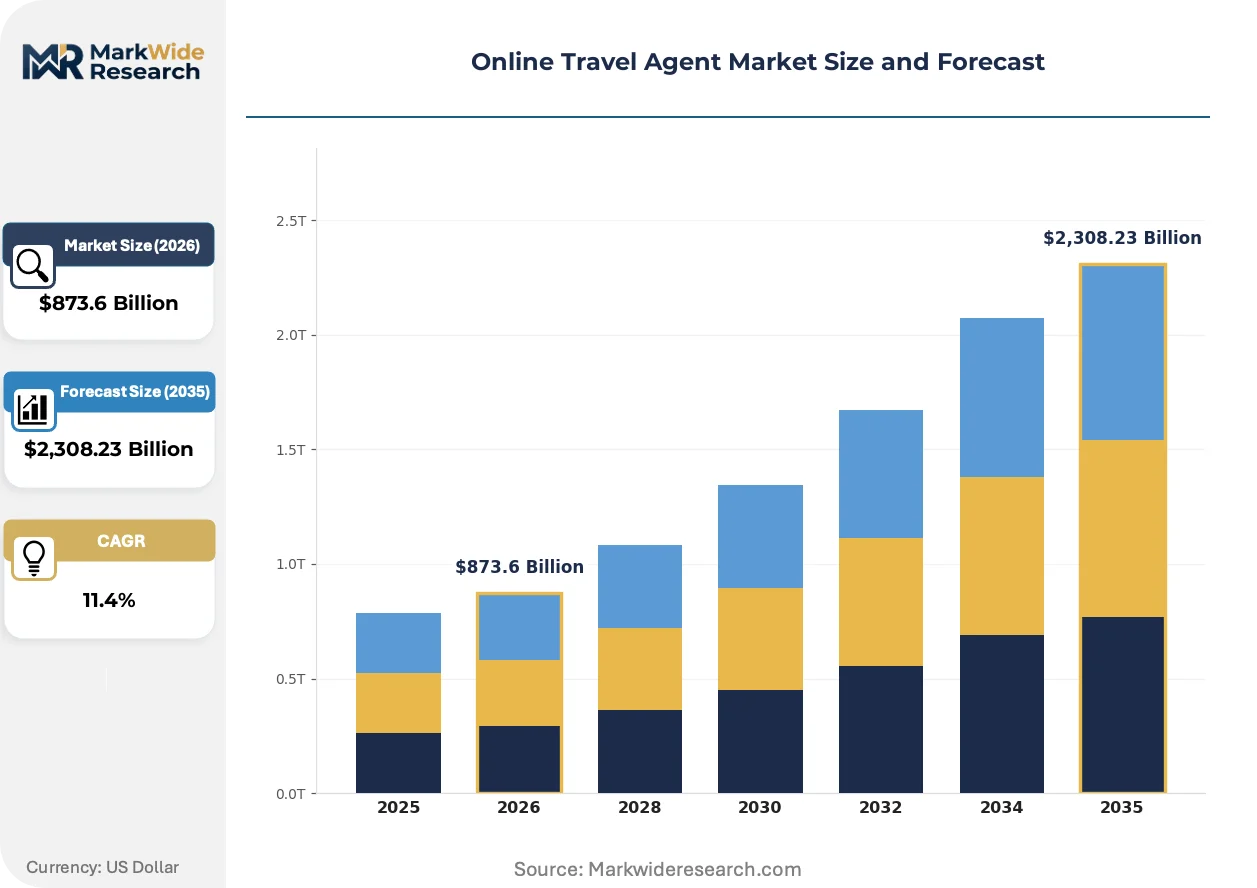
| Market Size in 2026 | $873.6 Billion |
| Market Size in 2035 | $2,308.23 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Flight Bookings, Hotel Reservations, Travel Packages, Car Rentals Customer Type: Leisure Travelers, Business Travelers, Corporates, Agents Distribution Channel: Online Platforms, Mobile Apps, Brick-and-Mortar Agencies, Social Media Pricing Model: Dynamic Pricing, Fixed Prices, Commission-Based, Subscription |
| Companies Covered | Booking Holdings, Expedia Group, Airbnb, Trip.com Group, MakeMyTrip, Tongcheng Travel, Tripadvisor, Webjet, eDreams ODIGEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Travel Agent Market Trends and Innovations
Platform operators are rebuilding core infrastructure around real-time inventory synchronization and embedded financial services. These investments target friction reduction at search-to-transaction conversion points.
Generative artificial intelligence is integrating conversational search interfaces that parse natural language trip specifications into structured booking parameters. Leisure travelers are adopting these tools for complex multi-city itinerary construction. The technology is integrating supplier recommendation engines with customer service automation, compressing pre-sale inquiry handling costs.
The EU Digital Services Act is mandating algorithmic transparency disclosures for recommendation systems used in travel search ranking. Platform operators must document how sorting logic weights commercial agreements against relevance signals. Vacation rental segments face heightened documentation requirements for host verification and content moderation workflows.
Corporate procurement departments are unbundling managed travel programs from single-platform exclusivity. Large enterprises are negotiating direct supplier contracts while retaining platforms for booking fulfillment only. This pattern is most visible in North American technology and professional services sectors where travel spend concentration supports bilateral supplier negotiations.
Online Travel Agent Market Segmentation
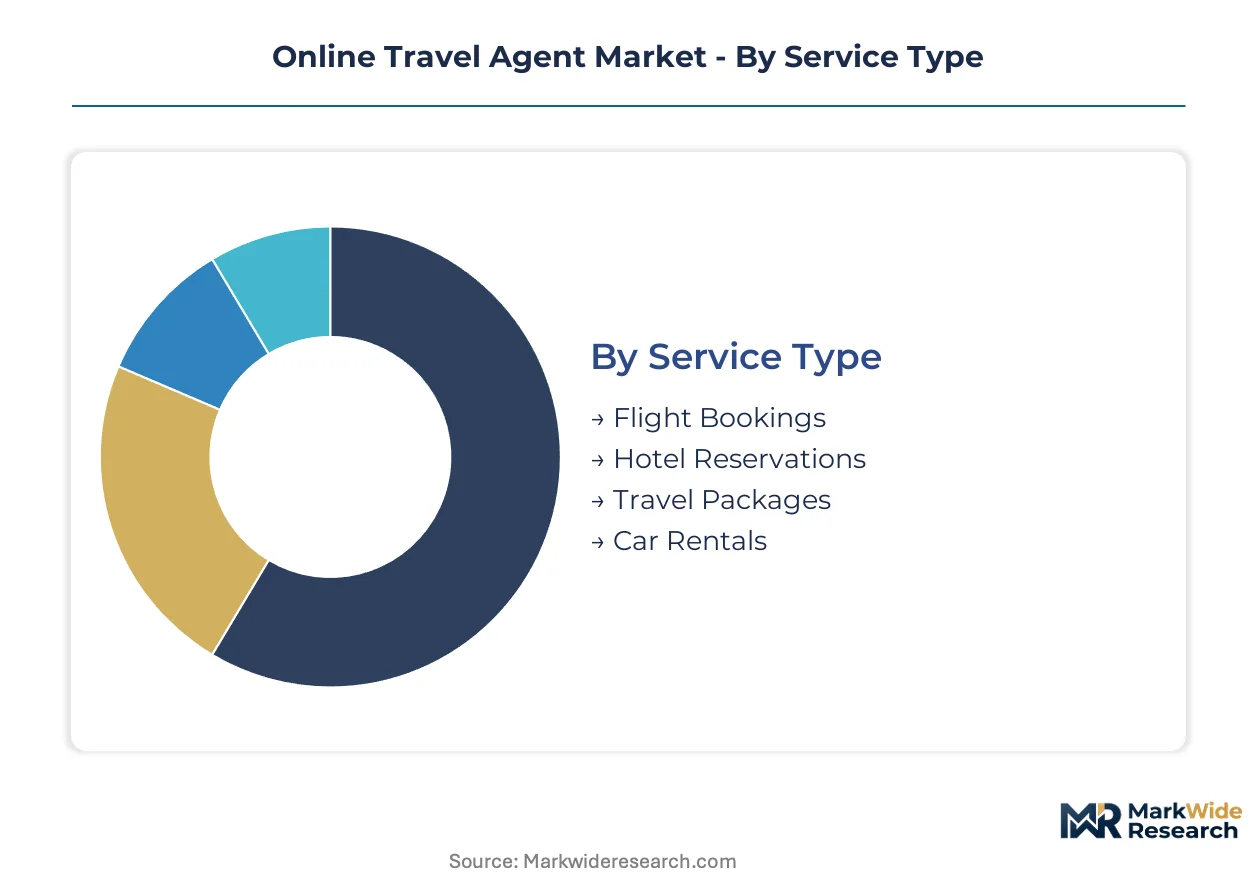
Online travel agent platforms segment their operations across four critical dimensions that determine technology architecture, partnership structures, and margin capture. Each category reflects distinct procurement behaviors and supplier integration requirements.
Service Type:
Upgrade cycles in service type reflect shifting traveler priorities from transactional bookings toward integrated trip experiences.
- Flight Bookings:Airline inventory aggregation through global distribution system APIs and direct carrier connections. Demand concentrates on high-frequency business corridors between Frankfurt and Singapore, driven by corporate procurement consolidation and negotiated volume discounts.
- Hotel Reservations:Property management system integrations spanning independent hotels and chain inventory. Southeast Asian markets in Indonesia and Vietnam show accelerating adoption as domestic tourism infrastructure digitizes.
- Travel Packages:Bundled inventory combining flights, accommodation, and experiences. Commission stacking delivers premium margins.
- Car Rentals:Fleet availability coordination with international and local operators. Urban mobility integration is expanding.
Flight bookings sit at the top of the volume ranking, with travel packages climbing the fastest.
Customer Type:
Customer type segmentation tracks procurement sophistication from individual leisure planning to enterprise-managed travel programs.
- Leisure Travelers:Individual trip planners utilizing comparison interfaces and review-driven selection. Mobile-first adoption in the Philippines is compressing search-to-booking cycles.
- Business Travelers:Frequent flyers requiring flexible change policies and loyalty program integration. Policy compliance tools are mandatory.
- Corporates:Enterprise procurement functions negotiating direct supplier contracts with platform fulfillment overlay. North American technology sector unbundling is visible.
- Agents:Traditional intermediaries accessing platform inventory through white-label or affiliate arrangements. Legacy commission structures persist.
Leisure travelers dominate transaction volume, while corporates show the steepest expansion trajectory in platform spend per account.
Distribution Channel:
Channel mix reflects infrastructure maturity and device penetration patterns across target geographies.
- Online Platforms:Desktop and mobile web interfaces handling complex multi-city itinerary construction. Conversion optimization drives continuous UX investment.
- Mobile Apps:Native smartphone applications with embedded payment and real-time notification systems. Indonesia-Vietnam corridors show smartphone penetration exceeding fixed broadband.
- Brick-and-Mortar Agencies:Physical locations serving cash-preferred segments and complex visa-assisted bookings. Declining share in digitized markets.
- Social Media:Influencer-driven discovery and in-platform booking through integrated commerce features. Visual content drives impulse conversion.
Online platforms maintain volume leadership, with mobile apps gaining share fastest across emerging Southeast Asian corridors.
Pricing Model:
Pricing architecture determines revenue recognition timing and supplier relationship economics.
- Dynamic Pricing:Algorithmic rate adjustment responding to inventory scarcity and demand signals. SAMR transparency mandates in China are complicating yield management system design.
- Fixed Prices:Guaranteed rates for contracted periods, common in corporate travel agreements. Budget certainty drives procurement preference.
- Commission-Based:Percentage fees on completed transactions, the traditional OTA revenue core. Rate parity enforcement varies by jurisdiction.
- Subscription:Recurring fees for premium features, loyalty tiers, or corporate platform access. Predictable revenue streams attract investor valuation premiums.
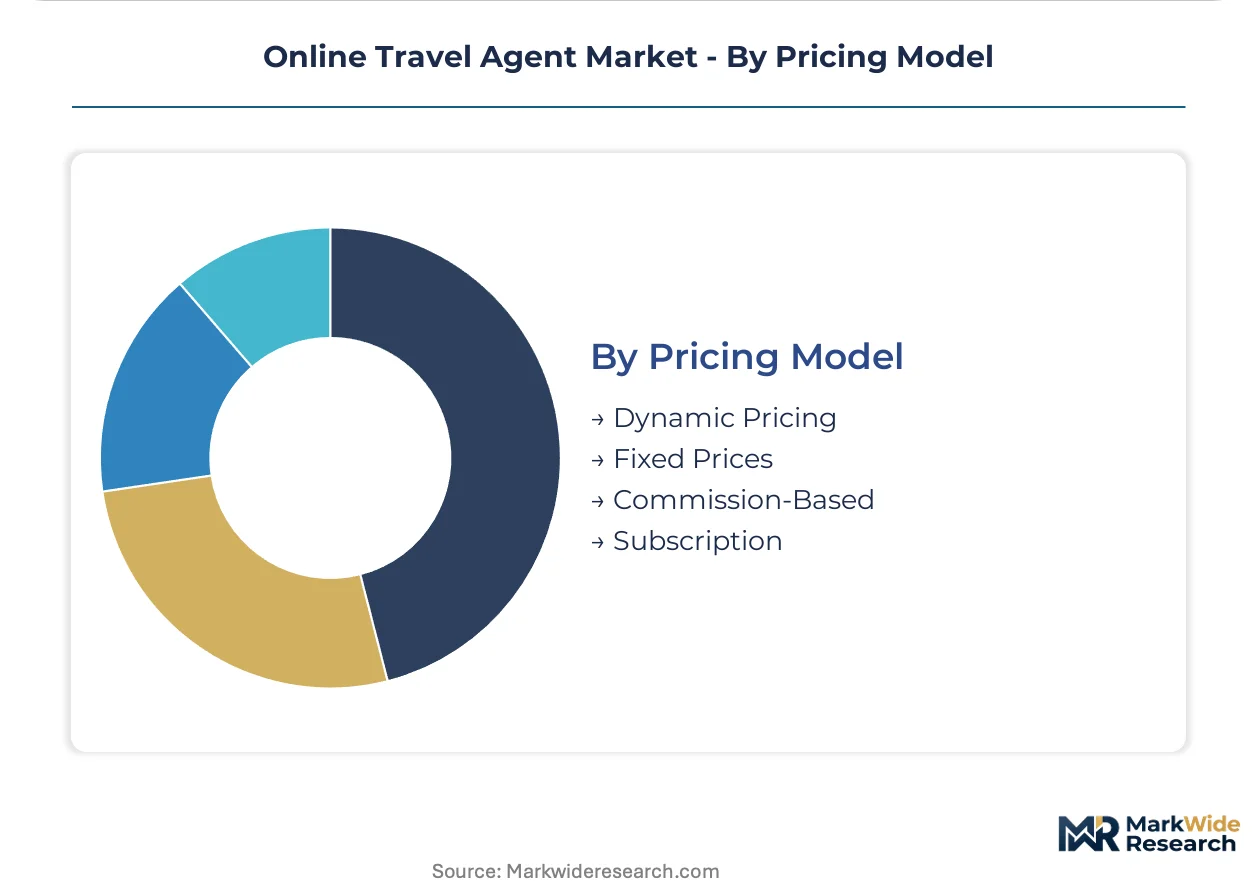
Commission-based models anchor current revenue, with subscription structures expanding most quickly in corporate segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Singapore, Berlin, and Shenzhen anchor platform development centers, while commercial operations concentrate in major metropolitan corridors across five distinct national markets.
United States
Corporate travel procurement consolidation and leisure package bundling drive platform adoption across the Northeast and California corridors. The FTC enforces drip-fee disclosure mandates for online booking interfaces. Dallas-Fort Worth hosts major airline partnership negotiation hubs where direct inventory agreements are restructured.
China
Cross-border mobility normalization and outbound tourism recovery accelerate booking volume through direct carrier integrations. SAMR mandates algorithmic transparency in personalized pricing systems. Shanghai's Pudong corridor anchors airline partnership headquarters managing China-Europe and China-Southeast Asia inventory flows.
Germany
Business travel policy compliance tools and managed corporate program unbundling reshape platform procurement patterns. The EU Digital Services Act imposes recommendation system documentation requirements. Berlin's startup ecosystem concentrates alternative accommodation aggregator development targeting secondary European city expansion.
Indonesia
Smartphone-first travel adoption and domestic tourism digitization outpace fixed broadband infrastructure rollout. The central bank regulates cross-border payment licensing for platform operators. Jakarta's metropolitan corridor hosts property management system integration teams addressing fragmented hotel connectivity.
Vietnam
Underdeveloped hospitality technology infrastructure and rising middle-class leisure travel create aggregator consolidation opportunities. The Ministry of Industry and Trade monitors e-commerce platform transparency in travel bookings. Ho Chi Minh City anchors mobile app development centers optimizing for Southeast Asian user experience patterns.
Online Travel Agent Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Merchant model operators with payment processing infrastructure sit alongside agency model platforms dependent on supplier commission flows. Technology-forward aggregators emphasize API connectivity breadth while experience curators prioritize inventory curation depth. Dominant competitive moves include direct airline partnership exclusivity negotiations and vacation rental supply expansion into secondary markets.
Within the diversified platform tier, Booking Holdings and Expedia Group occupy positions spanning multiple service verticals and geographic markets. Trip.com Group anchors the Asia-Pacific corridor specialist archetype through China-focused inventory control. These three entities exemplify divergent strategic postures: one emphasizes merchant model payment infrastructure, another prioritizes alternative accommodation supply breadth, and the third concentrates on direct carrier partnerships within a specific regional corridor.
| Leading Market Players |
|---|
| Booking Holdings |
| Expedia Group |
| Airbnb |
| Trip.com Group |
| MakeMyTrip |
| Tongcheng Travel |
| Tripadvisor |
| Webjet |
| eDreams ODIGEO |
| Others |
Pricing and Supply Chain Analysis
Corporate procurement functions in North American technology and professional services sectors anchor pricing power through volume concentration and direct supplier contract negotiations. Their unbundling of managed travel programs from single-platform exclusivity compresses commission rates while elevating fulfillment-only fee structures.
Pricing Analysis
Bundled travel packages command premium margins through commission stacking, while unbundled flight and hotel transactions face rate parity enforcement and direct booking incentives. Three-tier pricing structure across premium, standard, and economy levels segments corporate policy compliance tools from leisure comparison interfaces. Pricing pressure stems from airline native apps disintermediating high-frequency routes with loyalty program direct booking rewards. Leisure travelers in Southeast Asian mobile-first markets exhibit highest price sensitivity, while corporate procurement functions prioritize policy compliance over unit cost.
Supply Chain Analysis
Global distribution system connectivity rests on legacy technology infrastructure concentrated in the United States, Germany, and Singapore. Property management system integration protocols, airline direct connect APIs, and payment security module certification form critical input dependencies. Single-source vulnerability concentrates in global distribution system providers for airline inventory aggregation. Distribution runs through merchant model payment processing infrastructure alongside agency model commission flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
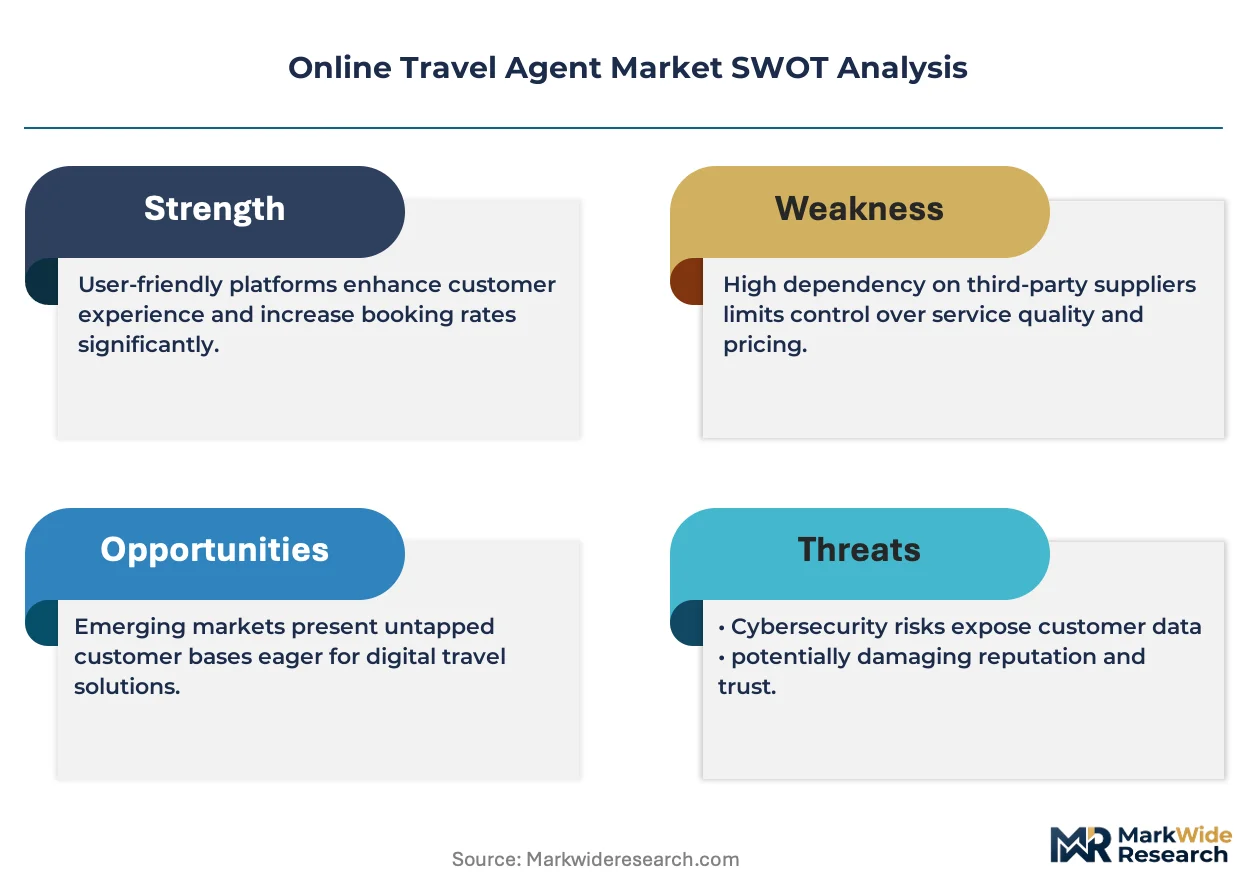
The online travel agent market functions as a stable compounder anchored by corporate travel procurement consolidation and mobile-first adoption in underpenetrated Southeast Asian corridors.
For Market Incumbents: Lock in direct airline partnership exclusivity on high-frequency business corridors to defend against carrier native app disintermediation. Deepen property management system integration in Vietnam and Indonesia where fragmented hotel connectivity creates consolidation moats. Prioritize merchant model payment infrastructure investment to sustain rate parity advantages across GDPR-DSA regulated European markets. For New Entrants and Emerging Players: Conversational artificial intelligence interfaces offer a technology-first wedge into complex multi-city itinerary construction where legacy platforms rely on form-based search. Target Vietnam's underdeveloped hospitality technology infrastructure where first-mover property management system aggregation captures domestic tourism digitization. Deploy influencer-driven social commerce discovery tools optimized for Philippines mobile-first impulse conversion patterns. For Investors and Strategic Acquirers: Travel technology conglomerates seeking Asia-Pacific corridor expansion are the most active acquirer in this space. Platform operators with direct carrier partnership structures and exclusive inventory access present acquisition profiles aligned with long-term cross-border mobility normalization. Watch China outbound corridor recovery velocity as the signal indicating inflection in regional inventory control valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Airline Partnership Negotiation | Exclusive inventory access on Frankfurt-Singapore and Shanghai-Pudong corridors locks in corporate procurement volume. |
| Vacation Rental Supply Expansion | Secondary European city penetration captures margin premium through bundled experience packaging beyond mature urban markets. |
| Mobile App Infrastructure Localization | Indonesia-Vietnam-Philippines optimization addresses smartphone penetration exceeding fixed broadband infrastructure development. |
| Algorithmic Transparency Compliance | EU Digital Services Act documentation for recommendation systems prevents regulatory exclusion from European market access. |
| Corporate Platform Unbundling Response | Fulfillment-only service tiers retain enterprise accounts as procurement functions negotiate direct supplier contracts. |
Research Methodology
Coverage spans the United States, China, Germany, Indonesia, and Vietnam, with primary inputs from each market informing demand calibration. Interviews with corporate travel procurement managers, airline distribution executives, property management system vendors, and mobile app product directors combined with secondary validation from SEC filings, EU regulatory databases, and national tourism authority statistics. Bottom-up property-level inventory aggregation triangulates against top-down sector expenditure estimates.
Granularity-level modeling disaggregates service type, customer type, distribution channel, and pricing model dimensions across the projection horizon. CAGRs derive from trend extrapolation of mobile adoption curves, corporate procurement platform spend per account trajectories, and cross-border mobility normalization patterns. Forecast inputs incorporate EU Digital Services Act compliance cost layering and SAMR algorithmic transparency mandate implementation timelines.
The model holds under stable regulatory enforcement and cross-border payment licensing continuity; deviation in tariff exposure or data localization mandate expansion would shift supplier integration economics. A small set of named triggers—China outbound corridor velocity, Vietnam property management system consolidation pace, and EU recommendation system audit enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market