
 United Kingdom Online Travel Market | 2026-2036
United Kingdom Online Travel Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Online Travel Market Analytics
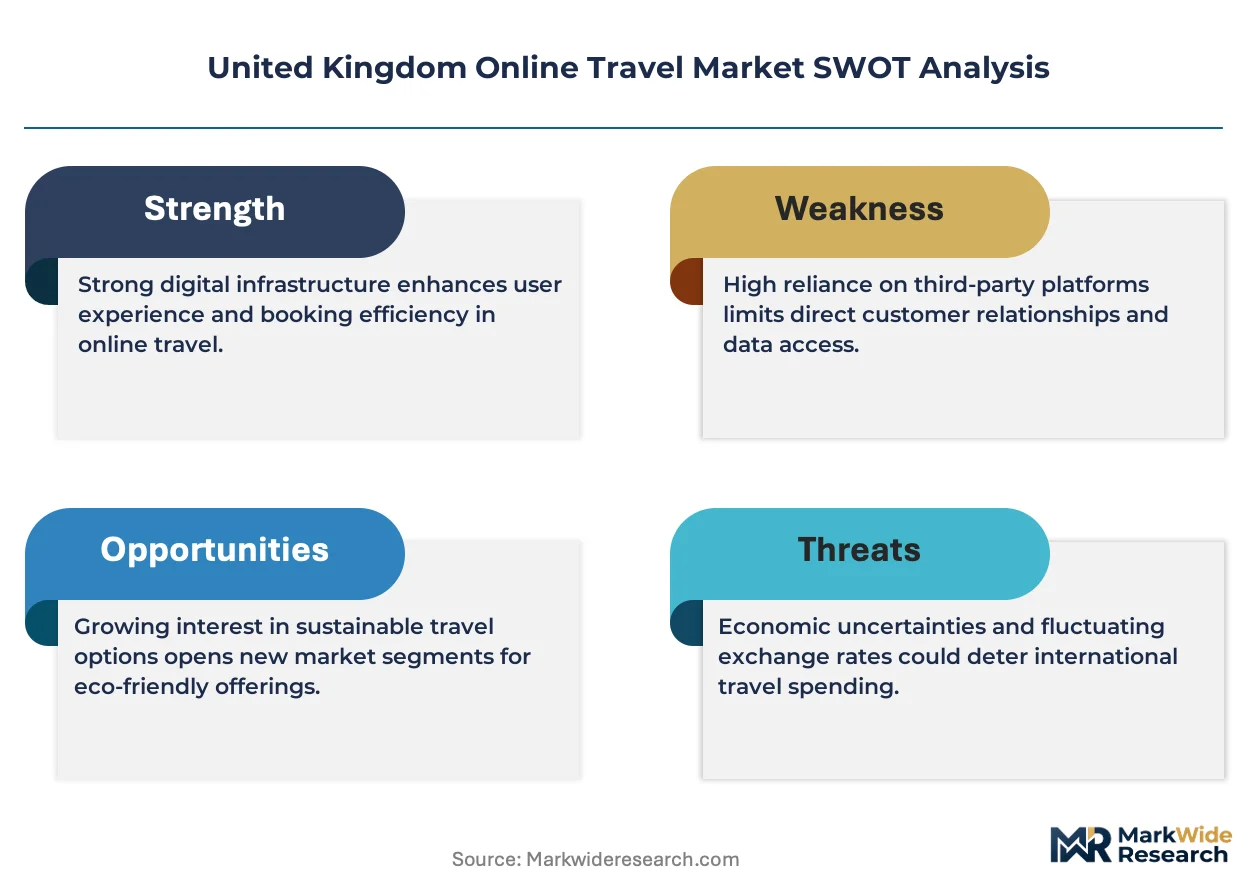
Generative AI in itinerary planning is fragmenting the traditional online travel agency model by enabling dynamic, personalized trip assembly outside legacy platform architectures. Booking Holdings Inc. leverages its global supply network to sustain rate parity advantages across UK inventory. easyJet plc anchors its position through direct-channel control of short-haul seat stock. Skyscanner Ltd. differentiates via metasearch aggregation that bypasses traditional booking fees.
The United Kingdom Online Travel sector encompasses digitally intermediated travel commerce, spanning platform-based booking engines, algorithmic fare aggregation, and API-connected inventory distribution systems that match traveler demand with transportation, accommodation, and experience supply. Its primary commercial purpose is to reduce search friction and transaction costs between fragmented travel suppliers and heterogeneous buyer segments. Booking Platforms currently lead service type revenue due to scale economies in user acquisition and supplier onboarding. Leisure Travelers dominate customer type composition, though Business Travelers generate higher per-trip commission yields. Domestic Travel retains volume leadership within travel type segmentation, while International Travel captures premium margin pools from currency-denominated cross-border transactions.
The UK Competition and Markets Authority enforces platform transparency rules that constrain dark pattern design in checkout flows. The Package Travel and Linked Travel Arrangements Regulations 2018 impose insolvency protection and refund obligations on sellers, elevating compliance costs for smaller tour operators. The Financial Conduct Authority's oversight of buy-now-pay-later travel financing is tightening credit accessibility standards. Stakeholders must monitor evolving liability frameworks as AI-generated recommendations blur the line between information service and regulated travel advice.
Market Dynamics
Generative AI is compressing itinerary planning cycles and eroding the informational advantage that traditional online travel agencies have held over direct supplier channels, forcing platforms to reconstitute their value propositions around real-time personalization and loyalty integration.
Growth Catalysts
- Mobile-First Booking Infrastructure:Smartphone penetration across England and Scotland enables frictionless same-day reservations, expanding addressable demand into spontaneous travel segments previously captured by walk-up counters.
- Consumer Rights Act Enforcement:Mandatory refund transparency and cancellation clarity reduce purchase hesitation, lowering cart abandonment rates for package travel products sold through digital channels.
- API-Connected Inventory Distribution:Real-time seat and room availability feeds from rail operators and boutique hotel chains compress search-to-book latency, improving conversion funnels for metasearch intermediaries.
Market Restraints
- Heathrow Slot Concentration:Limited runway capacity at the UK's primary international gateway constrains outbound seat supply growth, capping inventory available for third-party platform distribution during peak periods.
- Payment Interchange Cost Volatility:Card scheme fee fluctuations directly erode thin commission margins on low-value domestic bookings, pressuring profitability in the high-frequency short-haul segment.
- Package Travel Regulations 2018:Mandatory insolvency protection and refund obligations impose fixed compliance burdens that disproportionately burden smaller tour operators, consolidating seller concentration toward capitalized platforms.
Strategic Opportunities
- Wales and Northern England Digital Infrastructure:Underserved regional markets outside London and the South East present first-mover advantages for platforms investing in localized supplier onboarding and targeted user acquisition.
- Buy-Now-Pay-Later Travel Financing:Financial Conduct Authority oversight standardization creates regulatory clarity for embedded credit products, enabling installment penetration into higher-aspiration international booking segments.
- AI-Native Itinerary Assembly:Convergence of large language models with real-time pricing APIs enables dynamic package construction outside legacy GDS architectures, opening margin capture previously retained by traditional intermediaries.
Industry Challenges
- Legacy GDS Integration Complexity:Proprietary data formats and long-term contracts with global distribution systems constrain platform agility, delaying real-time inventory unification across air, rail, and accommodation suppliers.
- AI-Generated Recommendation Liability:Ambiguity between informational service and regulated travel advice under evolving Competition and Markets Authority guidance exposes platforms to novel compliance risks as algorithmic suggestions approach personalized consultancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Online Travel Market |
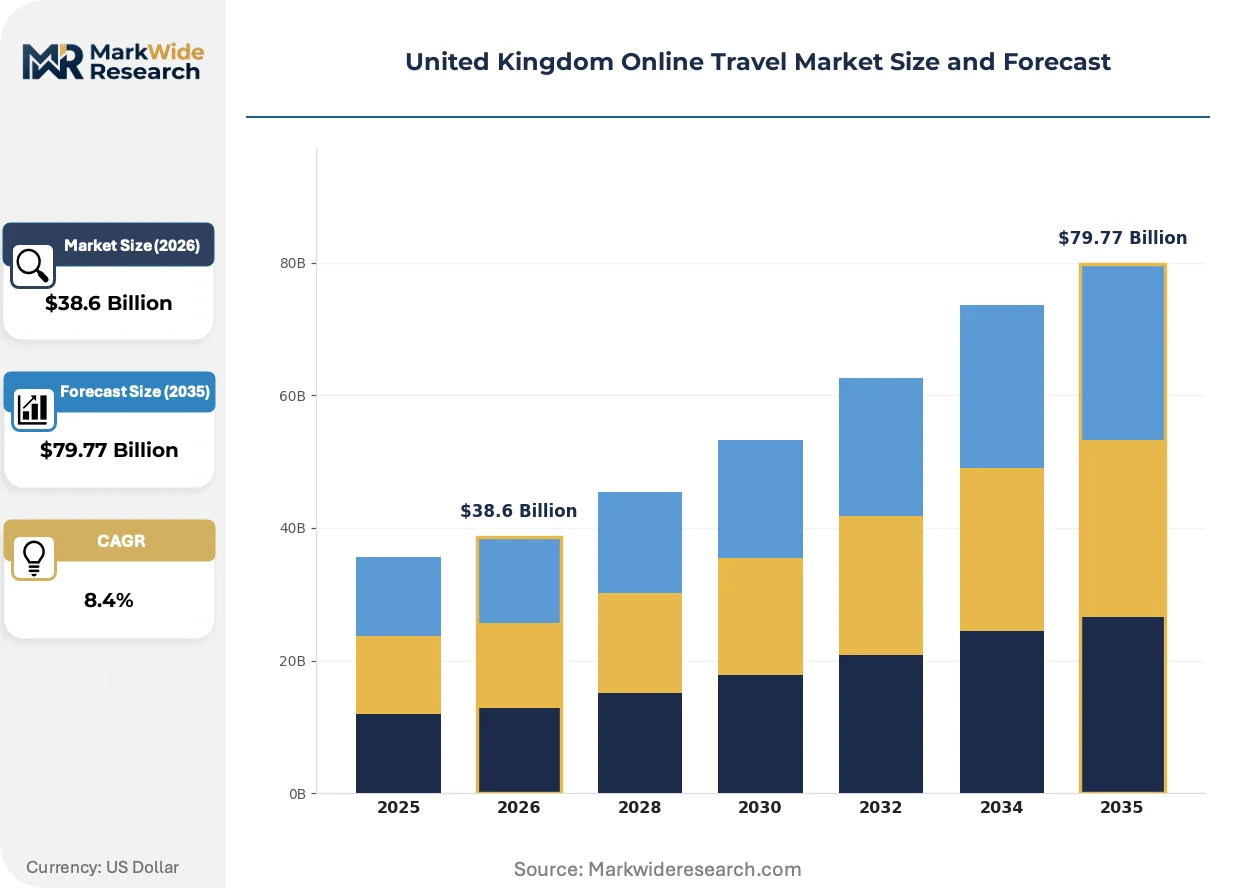
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Booking Platforms, Travel Agencies, Tour Operators, Online Aggregators Customer Type: Leisure Travelers, Business Travelers, Solo Travelers, Family Travelers Payment Method: Credit Cards, Debit Cards, PayPal, Mobile Payments Travel Type: Domestic Travel, International Travel, Adventure Travel, Cultural Travel |
| Companies Covered | TUI Group, loveholidays Ltd., Booking Holdings Inc., easyJet plc, Skyscanner Ltd., Expedia Group Inc., On the Beach Group plc, Jet2 plc, Airbnb Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Online Travel Market Evolving Landscape
Digital distribution architectures are fragmenting as travelers bypass consolidated platforms in favor of direct supplier relationships and AI-mediated discovery, compressing the traditional OTA intermediary role while elevating data sovereignty and personalization as competitive battlegrounds.
Conversational AI is hybridizing search and booking workflows by enabling natural-language trip specification that bypasses rigid form-based interfaces. Leisure travelers under 35 are adopting these tools at the fastest pace, with voice and chat interfaces capturing growing query share. This technology is hybridizing the discovery phase, collapsing the distinction between inspiration and transaction and compressing the traditional funnel into single-session completion.
The UK Competition and Markets Authority's platform transparency rules are mandating disclosure of ranking algorithms and fee structures at checkout. This regulatory intervention is forcing redesign of dark-pattern interfaces that previously obscured total cost breakdowns. Mid-tier booking platforms serving price-sensitive domestic segments are responding most aggressively, stripping optional add-on pre-selections to demonstrate compliance.
Subscription-based travel clubs are displacing commission-driven transaction models among frequent leisure travelers. These membership programs offer guaranteed rate discounts and flexible cancellation in exchange for annual fees, capturing high-intent repeat bookers who previously distributed purchases across multiple platforms. This behavioral pivot is most visible in London and the South East, where digital literacy and travel frequency concentrate demand for loyalty-based value propositions.
United Kingdom Online Travel Market Segmentation
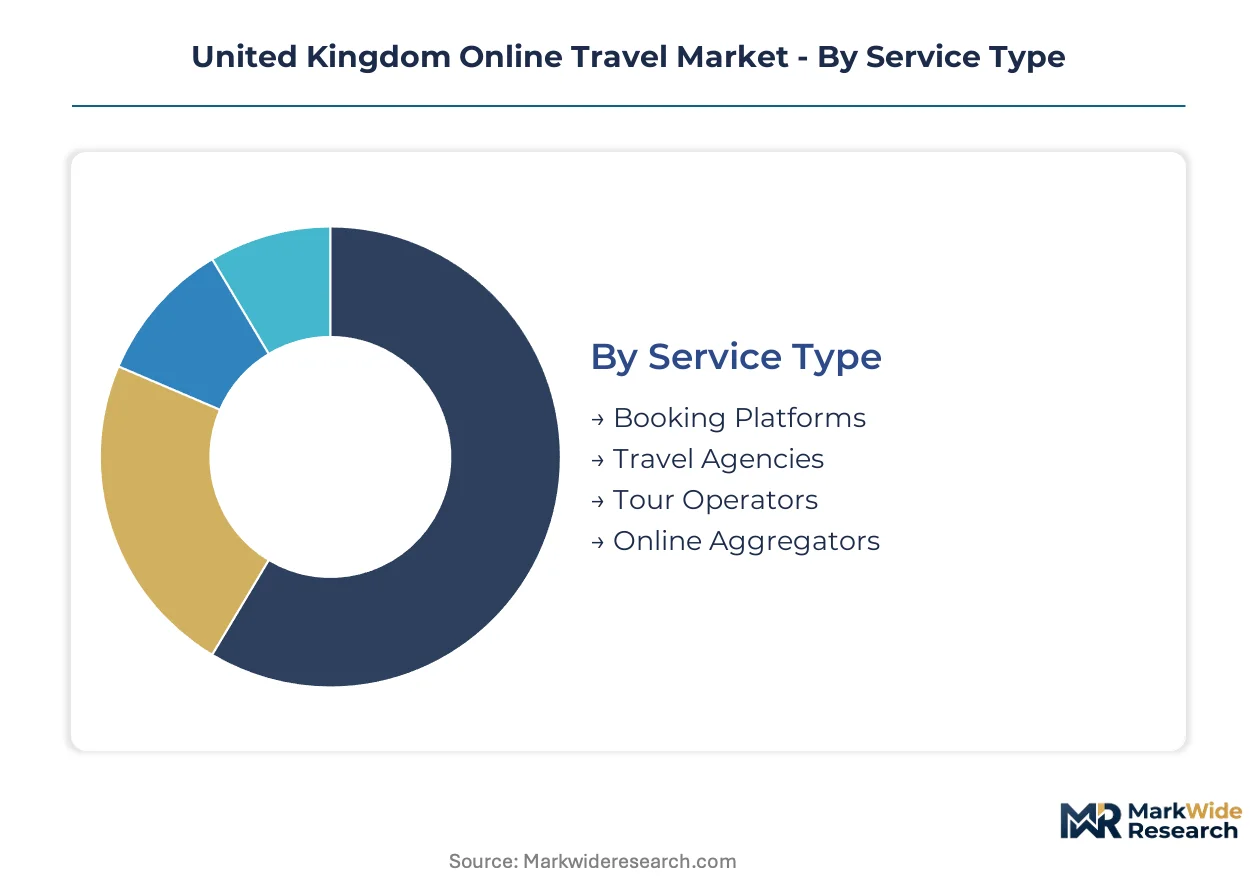
Segmentation in UK online travel reveals how platform economics, traveler behavior, and payment infrastructure intersect to create distinct commercial opportunities. Each dimension exposes different margin structures and regulatory exposure, from commission-heavy booking intermediaries to direct-channel tour operators navigating Package Travel Regulations.
Service Type:
After-sales-service intensity varies dramatically across service models, with platforms bearing ongoing liability for booking modifications while aggregators offload disruption handling to original suppliers.
- Booking Platforms:These digital intermediaries maintain direct contractual relationships with travelers, absorbing refund processing and customer service overhead. Demand concentrates in London and the South East where digital literacy and flight connectivity density support platform loyalty. Scale economies in user acquisition and supplier onboarding cement revenue leadership despite regulatory compliance burdens.
- Travel Agencies:Human-assisted booking retains relevance for complex multi-leg itineraries and corporate account management. Demand clusters among business travelers requiring invoice reconciliation and duty-of-care documentation. The segment faces margin compression as AI tools replicate advisory functions previously requiring specialist labor.
- Tour Operators:Curated package assembly combines transportation, accommodation, and experiences under single commercial responsibility. Fixed insolvency protection requirements under Package Travel Regulations 2018 elevate operational costs.
- Online Aggregators:Metasearch architectures display comparative pricing without assuming booking liability, capturing advertising and referral revenue. Mobile-first adoption in England and Scotland drives query volume.
Booking Platforms holds the largest share; momentum sits with Online Aggregators.
Customer Type:
Cost tier stratification separates high-yield corporate accounts from price-sensitive leisure segments, with distinct acquisition economics and retention strategies.
- Leisure Travelers:Discretionary trip planners dominate transaction volume across domestic short breaks and international holidays. Demand concentrates in peak school holiday periods and bank holiday weekends. Generative AI adoption for itinerary inspiration is expanding fastest among under-35 cohorts in urban centers.
- Business Travelers:Corporate account procurement generates elevated per-trip commission yields through negotiated rate contracts and change-flexibility premiums. Demand clusters in London's financial and professional services corridors. Duty-of-care requirements and expense management integration sustain platform stickiness despite direct airline corporate programs.
- Solo Travelers:Individual bookers exhibit higher platform switching frequency and price elasticity. Mobile payment adoption runs above population average.
- Family Travelers:Multi-passenger bookings amplify cart values but introduce complexity around cancellation terms and child pricing policies.
Leisure Travelers commands volume leadership; Business Travelers delivers superior margin per transaction.
Payment Method:
Volume concentration in card-based settlement reflects UK banking infrastructure maturity, while alternative methods capture specific demographic and use-case niches.
- Credit Cards:Revolving credit products dominate high-value international bookings, offering Section 75 consumer protection and reward point accumulation. Demand concentrates in premium leisure and business segments. Interchange fee volatility directly erodes platform margins on large transactions.
- Debit Cards:Direct bank account debiting prevails in domestic travel and price-sensitive segments. Lower processing costs appeal to platforms but lack chargeback protections drive higher dispute handling overhead.
- PayPal:Digital wallet adoption spans age demographics seeking checkout speed without card data entry. Guest checkout functionality reduces account creation friction.
- Mobile Payments:Apple Pay and Google Pay penetration accelerates among spontaneous same-day bookings. Smartphone-native travelers in Scotland and Northern England show adoption rates exceeding national average.
Credit Cards retains the largest transaction value; Mobile Payments is climbing the fastest.
Travel Type:
Geographic scope determines regulatory jurisdiction, supplier fragmentation, and currency exposure, with domestic and international segments operating under divergent margin structures.
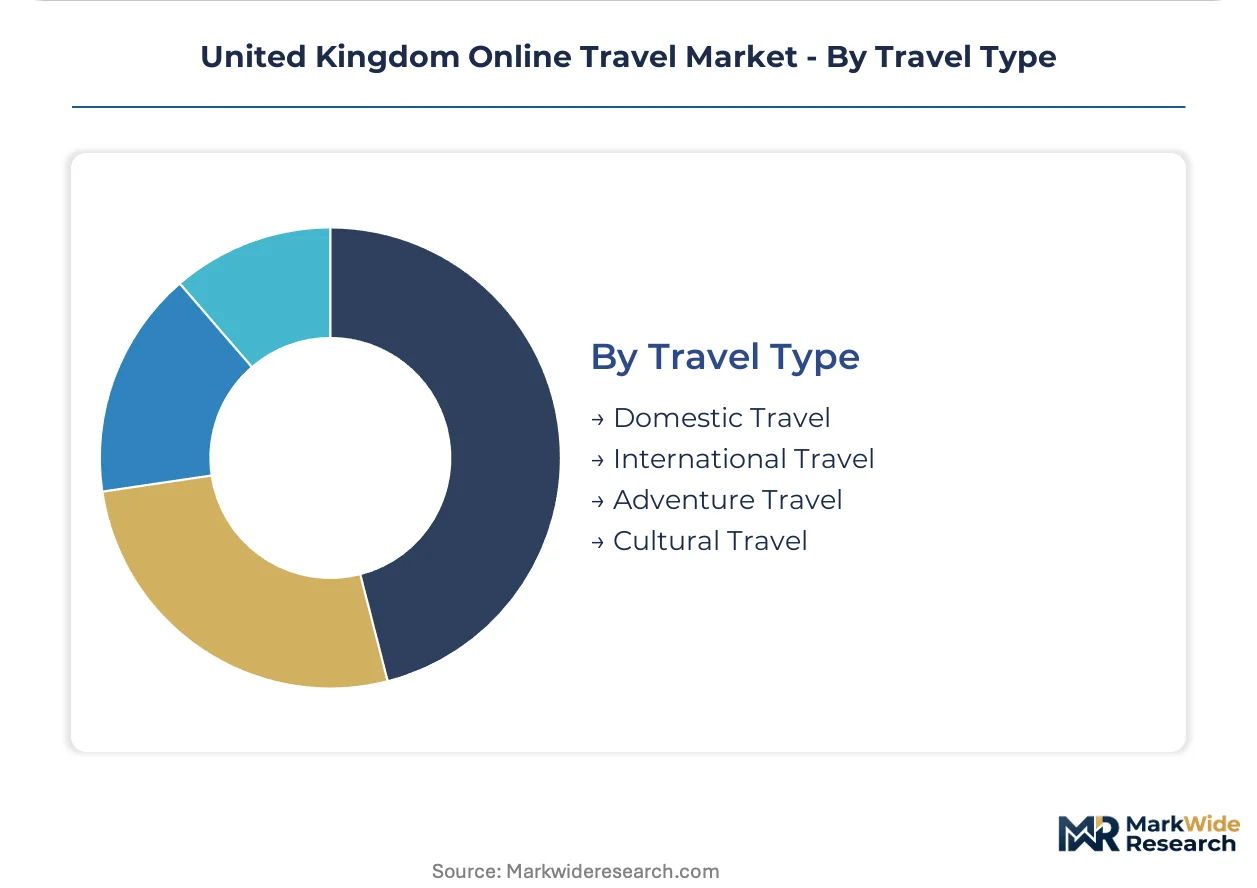
- Domestic Travel:Intra-UK trips retain volume leadership through rail, coach, and short-haul air connectivity. Demand concentrates in weekend leisure patterns and regional business corridors. Lower average transaction values compress commission yields, requiring high-frequency repeat booking to sustain platform economics.
- International Travel:Cross-border journeys capture premium margin pools from currency-denominated transactions and complex itinerary assembly fees. Demand clusters in long-haul outbound from London Heathrow and Gatwick. Package Travel Regulations impose insolvency protection obligations that favor capitalized platforms over smaller specialists.
- Adventure Travel:Activity-centered trips require specialized supplier relationships and safety certification verification. Niche positioning supports rate premiums.
- Cultural Travel:Heritage and arts-focused itineraries exhibit longer planning horizons and higher advance booking ratios.
Domestic Travel leads by transaction volume; International Travel delivers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK online travel platforms export digital distribution services to outbound leisure travelers across Europe and long-haul destinations. London Heathrow and Gatwick anchor this trade flow with dense flight connectivity that feeds platform inventory aggregation.
London and the South East
Digital infrastructure density and outbound flight connectivity concentrate platform demand in this corridor. The UK Competition and Markets Authority enforces platform transparency rules that constrain checkout flow design. FinTech adoption in the City of London accelerates embedded payment innovation for travel financing products.
Scotland
Mobile-first booking adoption runs above the UK average among leisure travelers in Edinburgh and Glasgow. The Package Travel and Linked Travel Arrangements Regulations 2018 impose uniform insolvency protection obligations across Scottish tour operators. Aberdeen's energy sector sustains corporate travel platform loyalty through duty-of-care contract requirements.
North England
Underserved regional markets present first-mover advantages for platforms investing in localized supplier onboarding. The Consumer Rights Act mandates refund transparency that reduces purchase hesitation for domestic short-break bookings. Manchester's aviation growth challenges Heathrow slot concentration with expanding long-haul connectivity.
Wales
Digital infrastructure gaps relative to England create whitespace for platforms targeting localized user acquisition. The Financial Conduct Authority's buy-now-pay-later oversight standardizes credit accessibility for higher-aspiration international bookings. Cardiff's emerging tech cluster supports niche travel platform development focused on adventure and cultural segments.
Midlands
Rail connectivity density supports domestic travel platform volume leadership through frequent short-haul corridors. The Package Travel Regulations elevate compliance costs that consolidate seller concentration toward capitalized platforms. Birmingham's airport expansion captures growing low-cost carrier distribution outside London's slot-constrained infrastructure.
United Kingdom Online Travel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidated platform scale dominates user acquisition economics while fragmented supplier-direct channels capture margin through inventory control. Strategic archetypes include global supply aggregators, short-haul seat stock controllers, and metasearch advertising intermediaries. Competitive moves center on API-connected inventory unification and loyalty-based subscription program deployment.
Within the global aggregator tier, Booking Holdings Inc. and Expedia Group Inc. exemplify scale-driven platform architectures that leverage cross-border supply networks. easyJet plc and Jet2 plc occupy positions as airline-integrated tour operators controlling direct-channel seat distribution. TUI Group anchors the traditional package tour segment with vertically integrated destination management capabilities. Skyscanner Ltd. and On the Beach Group plc represent metasearch and dynamically packaged holiday specialists respectively.
| Leading Market Players |
|---|
| TUI Group |
| loveholidays Ltd. |
| Booking Holdings Inc. |
| easyJet plc |
| Skyscanner Ltd. |
| Expedia Group Inc. |
| On the Beach Group plc |
| Jet2 plc |
| Airbnb Inc. |
| Others |
Value Network & Pricing Analysis
Heathrow slot concentration risk determines both commission compression in domestic short-haul segments and platform dependency on rail and regional airport inventory diversification. Payment interchange cost volatility feeds directly into margin tier spreads, with high-frequency low-value bookings absorbing cost pressure that premium international transactions resist.
Pricing Analysis
Legacy GDS integration pricing gaps separate API-native platforms from legacy intermediary tiers, with real-time inventory unification commanding rate premiums over batch-updated systems. Price differentiation hinges on after-sales service bundling and mobile payment infrastructure depth. Cost compression in domestic rail and coach segments intensifies as card scheme fees erode thin commissions. Leisure travelers in Northern England and Wales exhibit highest price sensitivity, while corporate accounts in London's financial corridors accept flexibility premiums.
Supply Chain Analysis
Airline direct-channel capacity concentration among easyJet plc and Jet2 plc controls short-haul seat stock distribution, constraining third-party platform margin capture. Inventory sourcing draws from UK rail operators, European low-cost carriers, and boutique hotel chains across England, Scotland, and Ireland. Single-source vulnerability concentrates in Heathrow and Gatwick slot holdings. Distribution runs through API-connected booking engines, metasearch aggregation layers, and direct supplier mobile applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK online travel market represents a service-attach opportunity where subscription-based loyalty programs and embedded travel financing expand faster than transactional commission revenue. Recurring membership fees and installment credit products now outpace pure booking margin growth.
For Market Incumbents: Entrench platform position by deepening API-native inventory unification across rail, air, and accommodation suppliers to outflank legacy GDS-dependent competitors. Expand subscription-based loyalty program deployment in London and the South East, where travel frequency supports annual fee economics. Counter generative AI itinerary tools by integrating real-time personalization layers that preserve booking completion within owned channels.
For New Entrants and Emerging Players: Build out white-space presence in Wales and Northern England through localized supplier onboarding and targeted user acquisition below incumbent radar. Penetrate the underserved regional domestic travel segment where digital infrastructure gaps delay platform saturation. Pursue buy-now-pay-later travel financing specialization under standardized Financial Conduct Authority oversight to capture higher-aspiration international booking segments.
For Investors and Strategic Acquirers: AI-native itinerary assembly platforms with proprietary large language model integrations represent the highest-conviction acquisition archetype for medium-term consolidation. Long-term viability across the analysis window favors platforms controlling direct-channel inventory or owning metasearch query volume. Monitor generative AI adoption rates among under-35 leisure travelers as the critical inflection signal for platform displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Inventory Unification | Real-time rail and hotel feed integration bypasses legacy GDS latency constraints for Booking Holdings Inc. |
| Subscription Loyalty Program Launch | Annual fee models capture high-intent repeat bookers previously distributed across multiple platforms. |
| Buy-Now-Pay-Later Financing Expansion | Financial Conduct Authority clarity enables installment penetration into premium international segments. |
| Generative AI Itinerary Integration | Large language model deployment collapses discovery-to-booking friction for Skyscanner Ltd. query volume. |
| Regional Supplier Onboarding Push | Wales and Northern England first-mover positioning exploits digital infrastructure whitespace. |
Research Methodology
Operator-level perspectives from platform engineering directors, airline distribution strategists, hotel chain revenue managers, and metasearch product leads anchored the qualitative base. Primary interview insights combined with secondary validation from Companies House filings, Civil Aviation Authority passenger statistics, Competition and Markets Authority enforcement notices, and rail industry open data feeds. Bottom-up transaction volume modeling and top-down digital commerce penetration analysis provided triangulation across the UK online travel ecosystem.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning service type, customer archetype, payment method, and travel geography. CAGRs derived from historical digital booking penetration curves, mobile payment adoption rates, and regulatory compliance cost trajectories. Forecast inputs incorporated Heathrow slot capacity constraints, Payment Services Directive interchange developments, and generative AI adoption velocity among leisure traveler cohorts.
The forecast holds incumbent behavior within observed patterns; aggressive direct-channel expansion by low-cost carriers or AI-native platform entrants would shift outcomes substantially. Model sensitivity reflects assumptions around Consumer Rights Act enforcement intensity and Package Travel Regulations compliance cost trajectories. Quarterly review of mobile booking share trends and generative AI query penetration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market