
 Global Online Airline Booking Platform Market | 2026-2036
Global Online Airline Booking Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Airline Booking Platform Market Foresight
The EU AI Act is realigning the cost-of-entry calculus for online airline booking platforms operating across European jurisdictions. Booking Holdings leverages its cloud-native architecture to sustain compliance automation at scale, while Amadeus IT Group anchors its competitive position through specialized API integration layers that navigate regulatory complexity. Trip.com Group differentiates by controlling mobile-first distribution channels across multiple Asian markets.
An online airline booking platform constitutes a digital intermediary system that aggregates flight inventory through global distribution system connections, processes real-time fare calculations, and completes secure payment transactions via encrypted protocols. These platforms serve the primary commercial purpose of reducing search friction and enabling instant confirmation for air travel purchases. The mobile platforms segment leads transaction volume globally as smartphone penetration deepens, while API integration represents the fastest-growing technology layer as airlines pursue direct-connect strategies to bypass traditional distribution costs. Corporate booking maintains premium margin pools due to negotiated rate structures and bundled duty-of-care services.
The US FAA coordinates with DOT consumer protection rules to shape refund timelines and fee disclosure standards that directly affect platform interface design. India's TRAI and RBI jointly govern data localization and payment security frameworks that determine foreign platform market access conditions. China's SAMR enforces anti-monopoly provisions affecting super-app bundling of travel services. Stakeholders must monitor how fragmented regulatory timelines across the US, EU, and India create compliance arbitrage opportunities that favor platforms with modular technical architectures.
Market Dynamics
The online airline booking platform market faces a structural inflection point as airlines accelerate direct-connect API strategies to bypass legacy global distribution system fees, compressing intermediary margins while forcing platforms to rebuild value around ancillary bundling and corporate duty-of-care services.
Growth Catalysts
- India's PLI scheme for digital infrastructure:Government incentives are expanding data center capacity and payment rail modernization, enabling platform localization that aligns with RBI data residency requirements for foreign operators.
- Corporate duty-of-care mandates:Post-pandemic travel risk management protocols are expanding adoption of managed booking platforms with real-time traveler tracking and emergency response integration.
- Smartphone penetration in Southeast Asian markets:Mobile-first transaction behavior is displacing desktop bookings, with platforms optimizing for Android-dominant user bases and localized wallet integrations.
Market Restraints
- Airline direct-connect cost pressures:Carriers including Lufthansa and British Airways are imposing distribution surcharges on GDS bookings, eroding platform commission structures.
- EU AI Act algorithmic transparency requirements:Recommendation engines must now provide explainability documentation, increasing compliance overhead for dynamic pricing systems.
- Payment processor concentration:Visa and Mastercard dominance in cross-border settlement creates single-point-of-failure risk for platforms operating multi-currency operations.
Strategic Opportunities
- Underserved SME corporate travel in Brazil:Mid-market enterprises lack negotiated rate access, creating white space for platforms offering aggregated buying power without enterprise implementation complexity.
- NDC (New Distribution Capability) standard adoption:IATA-mandated XML messaging protocols enable richer content transmission, allowing platforms to merchandise seats and ancillaries previously restricted to airline direct channels.
- Saudi Arabia's tourism visa liberalization:Giga-project development and religious tourism expansion are generating inbound booking volume that lacks mature platform infrastructure.
Industry Challenges
- Legacy PSS integration complexity:Platforms must maintain costly adapter layers to connect with Sabre, Amadeus, and TravelSky host systems that resist API standardization.
- Real-time fare caching accuracy:Inventory volatility requires sub-second price validation, straining computational infrastructure during high-demand booking windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Airline Booking Platform Market |
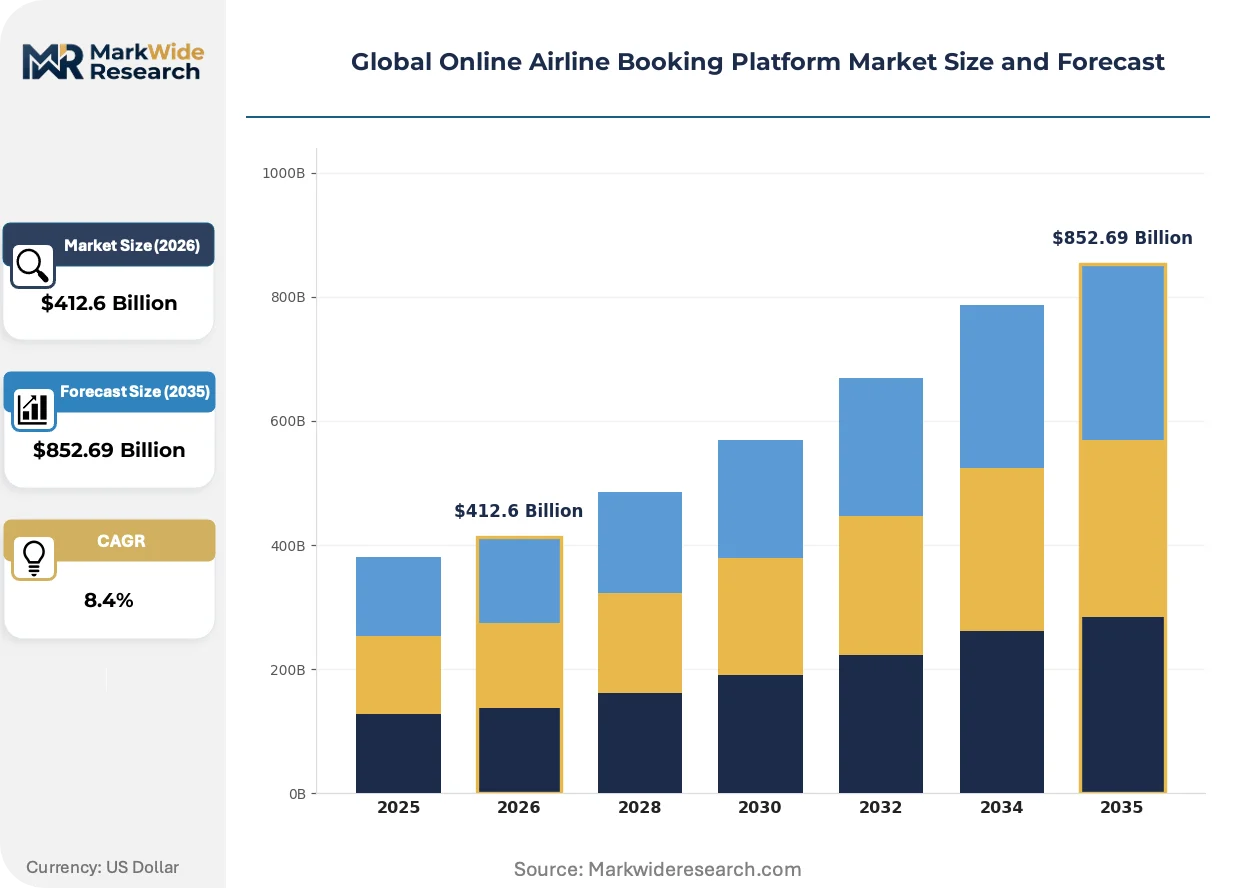
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $852.69 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Direct Booking, Third-Party Agents, Mobile Apps, Corporate Booking Customer Type: Leisure Travelers, Business Travelers, Travel Agents, Corporate Clients Payment Model: Pay-per-Booking, Subscription, Commission-based, Freemium Technology: Mobile Platforms, Web Applications, API Integration, Cloud Solutions |
| Companies Covered | Expedia Group, Booking Holdings, Amadeus IT Group, Trip.com Group, Sabre Corporation, Travelport, eTraveli Group, Kiwi.com, CheapOair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Airline Booking Platform Market Shifts & Advancements
Artificial intelligence deployment is shifting from customer-facing chatbots to back-office revenue optimization, with machine learning models now governing fare forecasting, overbooking algorithms, and personalized ancillary bundling at scale.
Blockchain-based settlement infrastructure is decentralizing payment reconciliation between airlines, hotels, and ground transport providers. Platform operators in the Middle East are piloting smart contracts for instant commission distribution upon flight completion. This architecture is compressing working capital cycles and reducing chargeback dispute overhead for cross-border transactions.
The EU AI Act's risk-based classification system is forcing platform operators to document training data provenance and algorithmic decision logic for dynamic pricing engines. High-risk systems must undergo conformity assessment before deployment in European markets. Corporate booking platforms serving multinational clients are establishing dedicated AI governance functions to manage this compliance layer.
Subscription-based travel purchasing is displacing per-transaction commission models among frequent business travelers. Platforms offering fixed monthly fees for unlimited booking changes and waived service charges are capturing road-warrior segments in the US and UK. This model compresses revenue per transaction but extends customer lifetime value through reduced churn.
Global Online Airline Booking Platform Market Segmentation
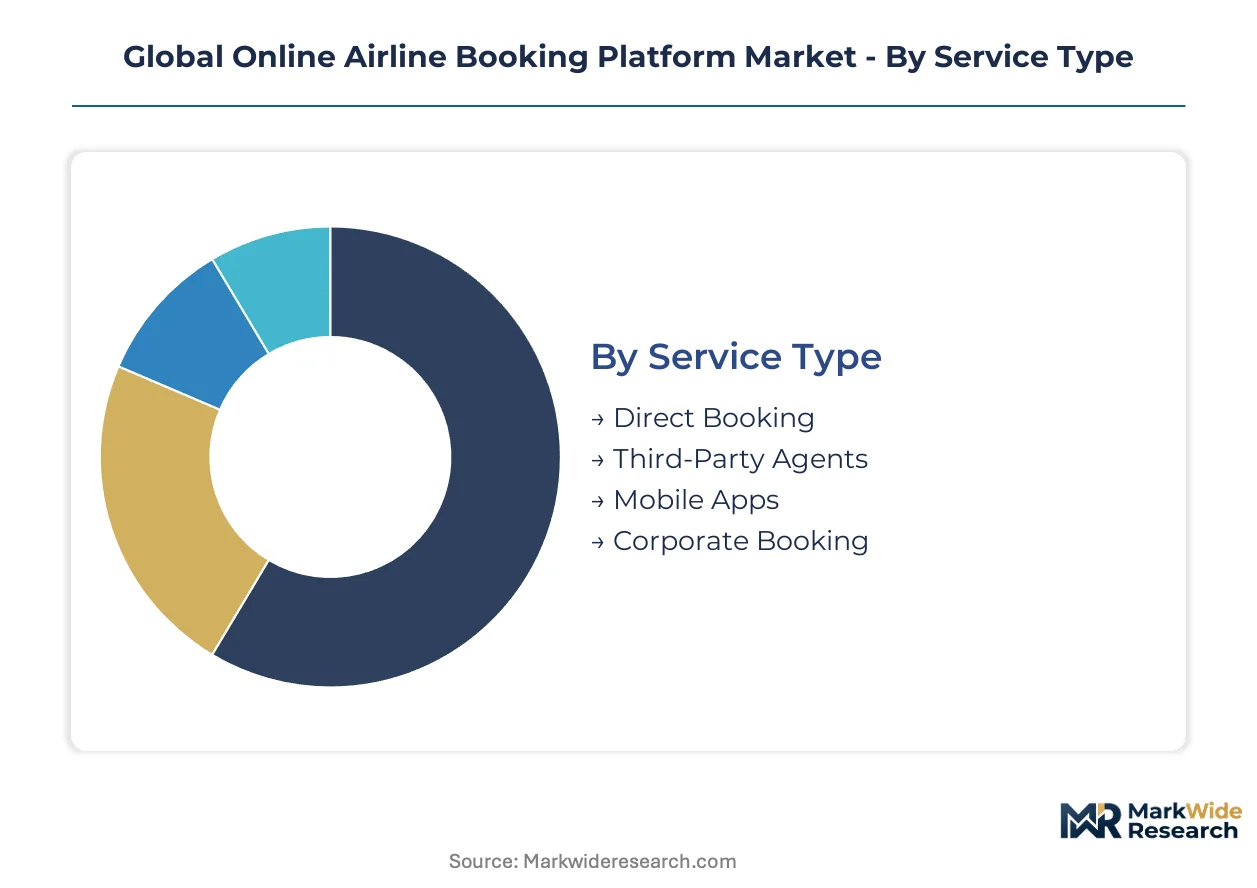
Online airline booking platforms serve heterogeneous demand clusters with divergent interface requirements and margin profiles. Segmentation reveals how technology architecture and commercial model choices determine competitive defensibility across traveler types and transaction modes.
Service Type:
Standardized interfaces dominate high-volume leisure segments while customized workflows capture corporate duty-of-care requirements and negotiated rate management.
- Direct Booking:Airlines operate proprietary channels with NDC-enabled rich content merchandising ancillaries previously restricted to agent platforms. Lufthansa and British Airways impose distribution surcharges on indirect bookings, accelerating carrier investment in native app ecosystems and loyalty-integrated payment rails.
- Third-Party Agents:Aggregators consolidate multi-carrier inventory through GDS connections, earning commissions on flight transactions and markups on package bundling. India's outbound tourism surge concentrates demand here as travelers seek fare comparison across international carriers lacking local direct channels.
- Mobile Apps:Smartphone-optimized interfaces with biometric authentication and wallet integration dominate Southeast Asian markets where Android penetration exceeds desktop access.
- Corporate Booking:Managed platforms embed policy enforcement, traveler tracking, and emergency response protocols demanded by post-pandemic risk management mandates.
Most installed capacity flows through Third-Party Agents. Expansion is steepest in Corporate Booking.
Customer Type:
Volume concentrates in price-sensitive leisure segments while margin pools concentrate in contractual corporate relationships with negotiated rate structures.
- Leisure Travelers:Individual consumers booking discretionary trips drive transaction velocity but compress margins through price comparison behavior and low ancillary attachment rates.
- Business Travelers:Road-warrior segments with flexible change policies and premium cabin preference sustain yield per transaction; subscription models capturing this cohort in the US and UK displace per-booking commissions with fixed monthly fees.
- Travel Agents:Human intermediaries persist in complex multi-leg itineraries and visa-sensitive destinations where travelers demand consultation assurance.
- Corporate Clients:Multinational enterprises with centralized travel management contracts generate recurring revenue through implementation fees and managed service retainers.
Transaction volume peaks with Leisure Travelers. Revenue per user climbs fastest among Corporate Clients.
Payment Model:
Upfront subscription revenue is displacing contingent commission streams as platforms seek predictable cash flow and reduced booking abandonment.
- Pay-per-Booking:Traditional transaction fees applied at checkout remain prevalent in emerging markets where credit card penetration limits subscription adoption and travelers resist recurring commitments.
- Subscription:Fixed monthly fees for unlimited changes and waived service charges extend customer lifetime value through reduced churn; this model is gaining share fastest among frequent business travelers in mature markets.
- Commission-based:Percentage-of-fare structures tied to GDS segment fees face compression as airlines impose direct-connect surcharges and bypass traditional distribution.
- Freemium:Basic search and comparison tools with premium tiers for price alerts, seat selection, and loyalty optimization attract price-sensitive users before conversion to paid features.
Commission-based structures still dominate transaction value. Subscription adoption is accelerating most quickly in North American and Western European markets.
Technology:
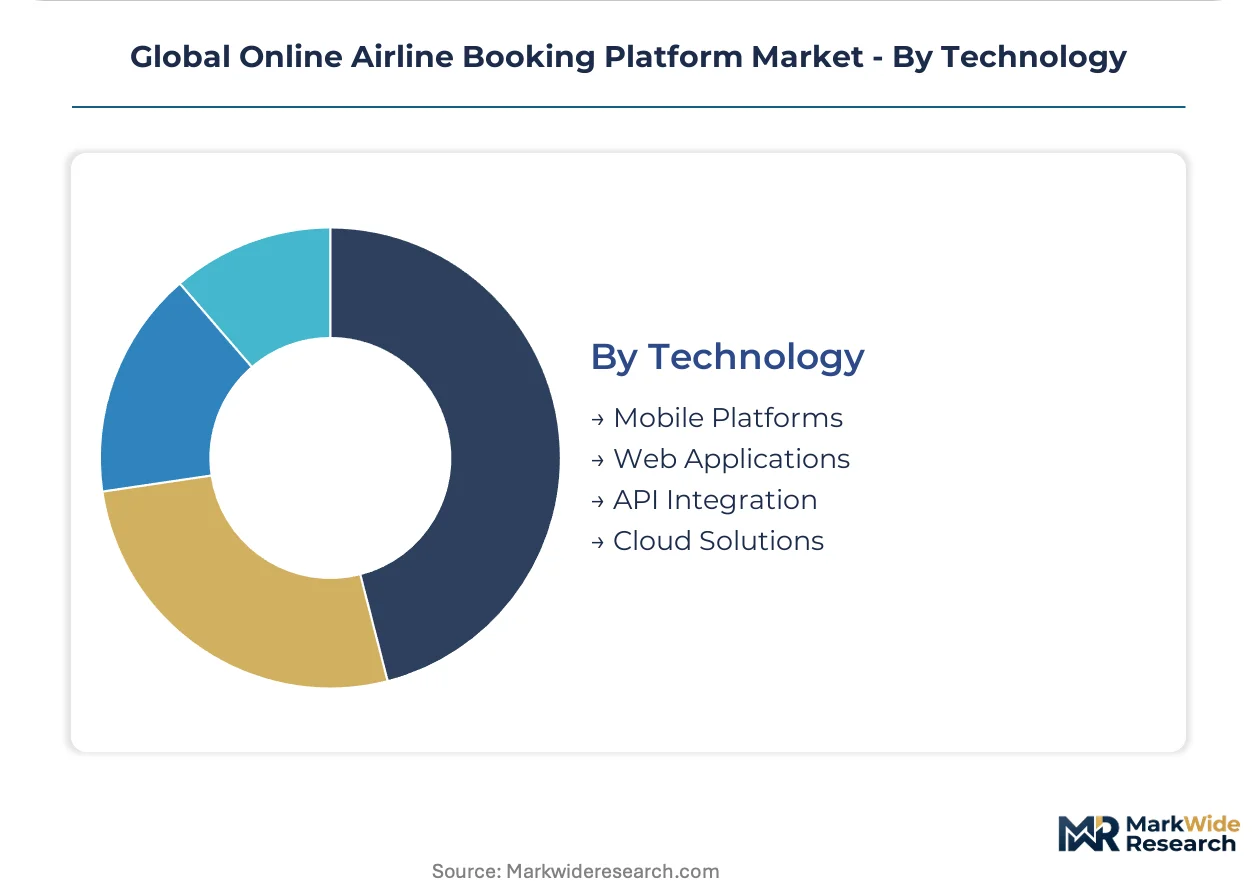
Cloud-native architectures enable compliance automation at scale while API layers determine connectivity flexibility across fragmented airline host systems.
- Mobile Platforms:Native iOS and Android applications with offline boarding pass storage and push notification rebooking dominate transaction volume globally as smartphone penetration deepens.
- Web Applications:Browser-based interfaces retain relevance for complex multi-city searches and corporate policy administration where screen real estate and keyboard input improve productivity.
- API Integration:Direct-connect protocols bypassing legacy GDS infrastructure represent the fastest-expanding technology layer as airlines pursue NDC standardization and platforms rebuild value around ancillary bundling.
- Cloud Solutions:Elastic infrastructure enables sub-second fare caching during high-demand windows and automates EU AI Act compliance documentation for algorithmic pricing systems.
Mobile Platforms carry the heaviest transaction load. API Integration is climbing the fastest as distribution disintermediation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in Bangalore, Shenzhen, and San Francisco anchor platform development capacity. These concentrations feed product innovation cycles while regulatory divergence across jurisdictions fragments compliance architecture.
United States
Corporate travel management spend and subscription-based booking models drive platform revenue. The FAA coordinates with DOT consumer protection rules to shape refund timelines and fee disclosure standards. San Francisco Bay Area hosts cloud-native architecture development for compliance automation at scale.
India
Outbound tourism surge and smartphone-first transaction behavior concentrate demand. TRAI and RBI jointly govern data localization and payment security frameworks that determine foreign platform market access. Bangalore anchors engineering centers building mobile-optimized interfaces for Android-dominant user bases.
Germany
Lufthansa's distribution surcharge strategy accelerates airline direct-connect investment. The EU AI Act's algorithmic transparency mandates reshape recommendation engine operations. Berlin hosts compliance documentation centers for dynamic pricing systems.
China
Super-app bundling of travel services and domestic aviation volume sustain platform engagement. SAMR enforces anti-monopoly provisions affecting service integration depth. Shenzhen anchors mobile payment infrastructure development for wallet-integrated booking flows.
Saudi Arabia
Giga-project development and religious tourism expansion generate inbound booking volume lacking mature platform infrastructure. The central bank's fintech licensing framework determines payment processor market entry. Riyadh concentrates platform localization investment for Arabic-language service deployment.
Global Online Airline Booking Platform Market Competitive Landscape
The competitive structure tilts toward integrated technology providers with GDS connectivity depth. Market concentration reflects high barriers to airline host system integration and real-time fare caching infrastructure. Three archetypes dominate: legacy distribution system operators, cloud-native platform aggregators, and mobile-first regional specialists. M&A activity concentrates on API layer capabilities and corporate duty-of-care service portfolios.
Among North American-based operators, Expedia Group and Booking Holdings occupy positions spanning leisure aggregation and corporate travel management. Amadeus IT Group anchors the European tier through specialized distribution infrastructure. These three exemplify how scale-driven platform economics and regulatory compliance automation determine competitive defensibility across fragmented airline distribution channels.
| Leading Market Players |
|---|
| Expedia Group |
| Booking Holdings |
| Amadeus IT Group |
| Trip.com Group |
| Sabre Corporation |
| Travelport |
| eTraveli Group |
| Kiwi.com |
| CheapOair |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up corporate travel platforms anchor pricing discipline through negotiated rate bundling while compressing supplier payment cycles to offset airline distribution surcharge pressures. Their ownership structure incentivizes margin extraction via ancillary merchandising and subscription lock-in rather than transactional commission recovery.
Pricing Analysis
The bundled-vs-unbundled service split governs revenue architecture across platform tiers. Subscription models capturing frequent business travelers in the US and UK displace per-booking commissions with fixed monthly fees for unlimited changes. Price differentiation hinges on corporate policy enforcement depth and real-time traveler tracking integration. Pricing pressure stems from Lufthansa and British Airways imposing GDS distribution surcharges that erode intermediary margins. Leisure travelers exhibit highest price sensitivity through fare comparison behavior, while corporate clients with duty-of-care mandates accept premium positioning.
Supply Chain Analysis
Workforce availability constraints in Bangalore, Shenzhen, and San Francisco Bay Area shape platform development capacity and API integration velocity. Supply concentrates in India for mobile-optimized engineering, China for super-app payment infrastructure, and the US for cloud-native compliance automation. Raw material dependencies include GDS segment connectivity, NDC protocol standardization, and real-time fare caching infrastructure. Single-source vulnerability runs through Visa and Mastercard dominance in cross-border settlement rails. Distribution runs through direct airline proprietary channels, third-party aggregator platforms, and corporate managed booking systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through ancillary bundling sophistication and subscription revenue displacement of volatile commission streams. Platform operators capturing corporate duty-of-care mandates command pricing power unavailable in leisure aggregation.
For Market Incumbents: Acquire API integration specialists with NDC-certified direct-connect capabilities to bypass GDS surcharge compression. Consolidate corporate duty-of-care service portfolios through targeted capability additions. Reinforce defensive positioning against airline direct-channel encroachment by embedding policy enforcement and traveler tracking that carrier-native platforms cannot replicate. Prioritize certification investment for EU AI Act algorithmic transparency documentation. For New Entrants and Emerging Players: Capture underserved SME corporate travel in Brazil where mid-market enterprises lack negotiated rate access and implementation complexity blocks incumbent penetration. Target white-space opportunities in Saudi Arabia's inbound tourism infrastructure gap following visa liberalization. Deploy mobile-first distribution with localized wallet integration as the primary go-to-market angle across Southeast Asian markets. For Investors and Strategic Acquirers: Valuations sit cheapest among regional mobile-first specialists with Android-optimized interfaces and limited corporate travel exposure. Long-term viability favors platforms with modular technical architectures capable of compliance arbitrage across fragmented US, EU, and Indian regulatory timelines. Watch NDC adoption velocity as the inflection signal determining whether API-native entrants or legacy GDS-integrated incumbents capture airline direct-connect margin pools.| Strategic Initiative | Industry Significance |
|---|---|
| NDC API Integration | IATA-mandated XML protocols enable ancillary merchandising previously restricted to airline direct channels. |
| Corporate Duty-of-Care Platform Buildout | Post-pandemic risk management mandates expand recurring revenue through traveler tracking and emergency response integration. |
| Subscription Model Migration | Fixed monthly fees for unlimited booking changes extend customer lifetime value through reduced churn in US and UK markets. |
| EU AI Act Compliance Automation | Cloud-native architectures sustain algorithmic transparency documentation at scale for dynamic pricing engine deployment. |
| Mobile-First Localization | Android-optimized interfaces with biometric authentication capture smartphone-dominant transaction behavior in India and Southeast Asia. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing demand calibration and regulatory divergence assessment. The analysis combines structured interviews with corporate travel managers, airline distribution executives, platform engineering leads, and payment infrastructure specialists with secondary validation through IATA NDC implementation reports, SEC filings from listed travel technology providers, EU AI Act regulatory documentation, and RBI data localization compliance disclosures. Bottom-up transaction volume modeling and top-down market sizing triangulate segment-level estimates.
Rate-of-change decomposition across the projection horizon isolates volume drivers from pricing dynamics and mix-shift effects. Segmentation dimensions modeled include service type, customer archetype, payment model, and technology layer, with additional granularity on NDC adoption stage and corporate travel policy complexity. CAGRs derive from logistic curve fitting against smartphone penetration trajectories and airline direct-connect investment cycles. Forecast inputs incorporate PLI scheme implementation pace in India and EU AI Act enforcement timelines.
Airline distribution surcharge escalation, NDC standardization velocity, and central bank digital payment framework changes are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding regulatory compliance cost trajectories and carrier bypass strategies. Material deviation in surcharge implementation breadth or NDC technical specification finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Japan Hotel Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market