
 Japan Hotel Booking Market | 2026-2036
Japan Hotel Booking Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Hotel Booking Market Insights
Domestic leisure travelers is unwinding the historical dominance of business travelers in Japan's hotel booking landscape. Rakuten Travel leverages its super-app ecosystem to capture repeat domestic bookings through integrated loyalty currency. Jalan anchors rural and onsen property inventory, sustaining deep supply relationships with traditional ryokan networks. Booking.com competes aggressively on inbound foreign demand, positioning multilingual interfaces and international payment rails.
Japan hotel booking encompasses the digital intermediation of accommodation reservations through online platforms, mobile applications, and global distribution systems that aggregate real-time room inventory, pricing, and availability data across property types. The system operates on API-driven connectivity between property management systems and consumer-facing interfaces, enabling instant confirmation and dynamic yield management for hotel operators. Online Travel Agencies currently lead transaction volume but face margin compression as Direct Booking channels gain traction among luxury hotel chains seeking to own customer relationships. Mobile Apps represent the fastest-growing booking platform segment, driven by smartphone penetration and one-tap payment integration, while Budget Hotels within the Service Type dimension attract platform investment due to higher turnover and price-sensitive demand elasticity.
METI's tourism infrastructure policies and the Japan Tourism Agency's accommodation registration standards shape platform compliance requirements and property eligibility for listing. PMDA oversight extends to health and safety certifications for lodging facilities, particularly post-pandemic sanitation protocols that platforms must verify before onboarding. JIS standards govern payment security and data handling, constraining how booking engines process consumer financial information. Stakeholders must monitor whether METI advances interoperability mandates that would force platforms to share inventory data, potentially eroding the competitive moats of vertically integrated operators.
Market Dynamics
Mobile-first booking behavior is compressing commission structures as domestic leisure travelers abandon desktop platforms for super-app ecosystems, forcing intermediaries to rebuild their technology stacks around one-tap payment integration and loyalty currency fungibility.
Growth Catalysts
- METI Tourism Digitization:Infrastructure grants accelerate property management system upgrades, expanding bookable inventory on domestic platforms.
- Smartphone Penetration:One-tap payment integration reduces booking abandonment rates among younger domestic leisure cohorts.
- Domestic Leisure Recovery:Post-pandemic preference for rural onsen and ryokan properties diversifies platform supply beyond urban business hotels.
Market Restraints
- OTA Commission Compression:Direct booking incentives from luxury chains erode intermediary margins on high-value transactions.
- JIS Payment Security Compliance:Data handling certification requirements increase onboarding friction for smaller ryokan operators.
- Platform Concentration Risk:Three domestic super-apps control loyalty currency circulation, limiting new entrant customer acquisition.
Strategic Opportunities
- Inbound Foreign Demand:Multilingual interface investment captures recovery in international arrivals to Tokyo-Osaka-Kyoto corridor.
- Rural Inventory Aggregation:Deep supply relationships with untiered onsen properties unlocks pricing power in experiential travel.
- Interoperability Mandates:Potential METI inventory-sharing requirements would erode moats of vertically integrated operators.
Industry Challenges
- Legacy Property Management Integration:API connectivity gaps at traditional ryokan properties delay real-time availability updates.
- Sanitation Certification Verification:Post-pandemic PMDA protocols require manual documentation review before platform onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Hotel Booking Market |
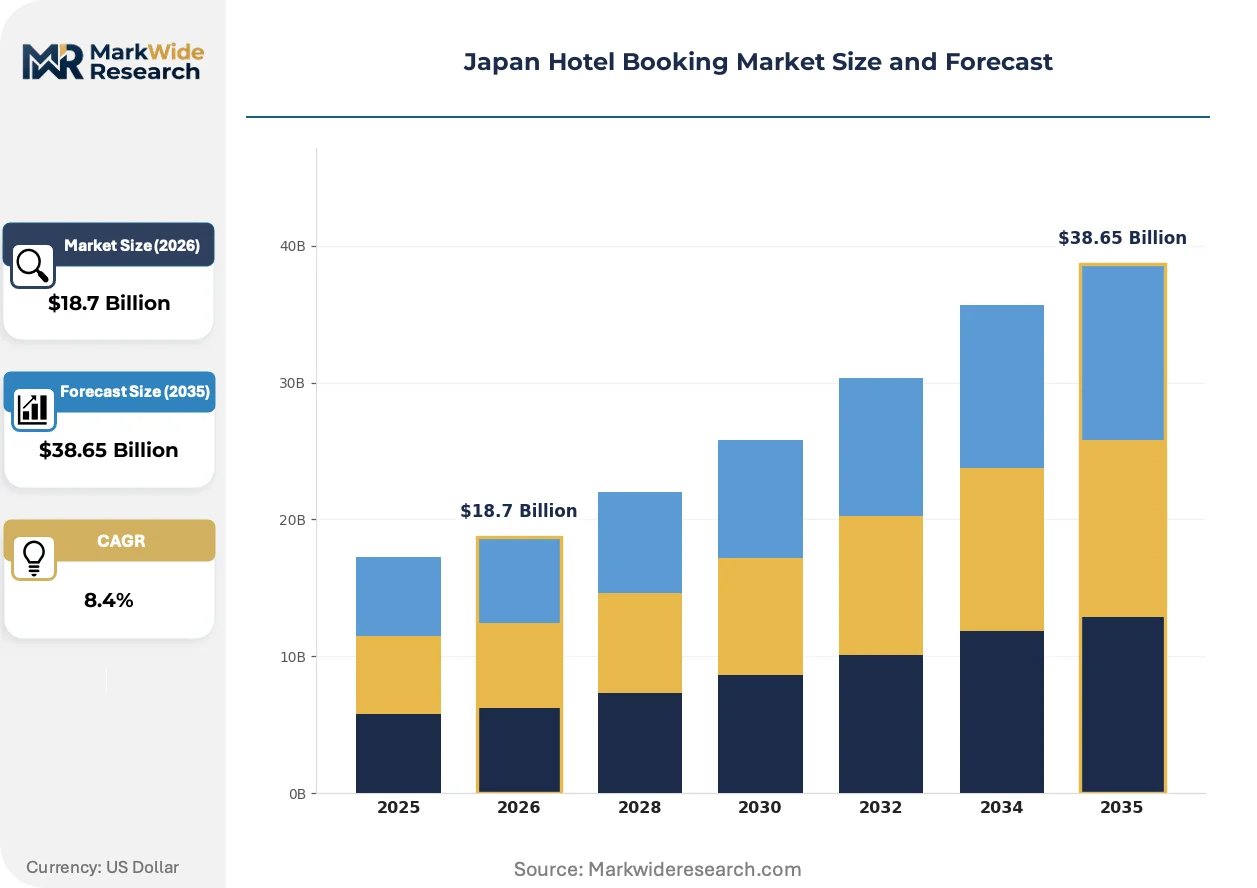
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Booking Platform: Online Travel Agencies, Direct Booking, Mobile Apps, GDS Customer Segment: Leisure Travelers, Business Travelers, Group Travelers, Families Service Type: Luxury Hotels, Budget Hotels, Boutique Hotels, Hostels Payment Method: Credit Card, Debit Card, PayPal, Bank Transfer |
| Companies Covered | Rakuten Travel, Jalan, Booking.com, Expedia Group, Agoda, JAPANiCAN, Hotels.com, Yahoo Travel, JTB Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Hotel Booking Market Trends and Innovations
Artificial intelligence recommendation engines and dynamic yield algorithms are reshaping how inventory surfaces to travelers, creating divergence between price-sensitive automated bookings and high-touch concierge-assisted reservations.
Dynamic pricing algorithms is bifurcating the market between opaque discount inventory and premium direct-rate channels. Budget hotel chains deploy automated yield management to maximize occupancy, while luxury properties resist algorithmic discounting to protect brand positioning. The technology is compressing margin capture for mid-tier properties caught between these strategies.
METI's accommodation registration standards tighten eligibility requirements for platform listing, particularly for unlicensed minpaku and vacation rental operators. Properties must demonstrate fire safety compliance and sanitation certification before API integration. Urban hotels in Tokyo and Osaka face accelerated compliance timelines compared to rural counterparts.
Domestic travelers now complete bookings within single-session mobile interactions, abandoning multi-day comparison behavior. This pattern compresses OTA retargeting windows and privileges platforms with stored payment credentials. Younger leisure segments in metropolitan areas exhibit the shortest booking-to-stay lead times.
Japan Hotel Booking Market Segmentation
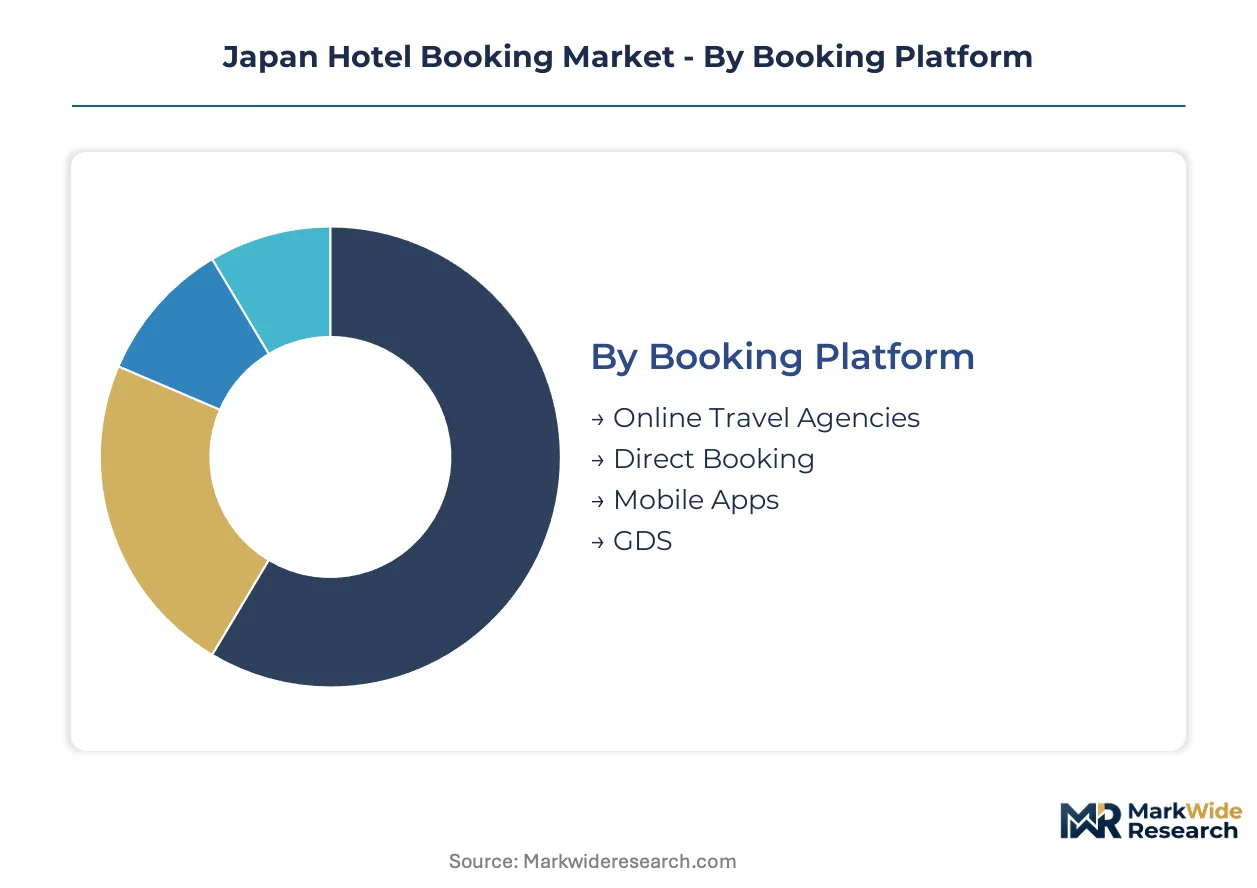
Segmentation in Japan's hotel booking market reveals how platform architecture, customer behavior, and service tiers interact with regulatory frameworks. Understanding these dimensions clarifies where METI digitization grants concentrate impact and which channels capture mobile-first domestic leisure demand.
Booking Platform:
Domestic platforms anchor transaction volume through super-app ecosystems, while foreign-facing channels depend on inbound arrival recovery to urban corridors.
- Online Travel Agencies:These intermediaries aggregate inventory through API connectivity to property management systems, capturing price-sensitive leisure demand across Tokyo-Osaka-Kyoto. Commission compression from luxury chain direct-booking incentives now threatens margin sustainability on high-value transactions.
- Mobile Apps:One-tap payment integration and stored credential systems enable single-session booking completion, with Rakuten Travel leveraging loyalty currency fungibility to lock in repeat domestic users. Younger metropolitan cohorts exhibit the shortest booking-to-stay lead times here.
- Direct Booking:Luxury hotel chains deploy this channel to own customer relationships and bypass intermediary fees, requiring substantial investment in proprietary reservation infrastructure.
- GDS:Legacy global distribution systems maintain relevance for corporate travel management and international chain inventory, though smartphone penetration erodes their share among leisure segments.
Online Travel Agencies command the established base. The steepest expansion runs through Mobile Apps.
Customer Segment:
Cost tier differentiation separates high-frequency low-margin leisure volume from premium business yield, with group dynamics introducing unique platform requirements.
- Leisure Travelers:Domestic leisure cohorts drive mobile-first migration, with post-pandemic preference shifting toward rural onsen and ryokan properties. METI's Go To Travel campaign infrastructure accelerated platform modernization for this segment.
- Business Travelers:Historical market anchors now face displacement as leisure demand scales, though corporate rate negotiations and loyalty program integration sustain OTA relevance for urban business hotels.
- Group Travelers:Coordination complexity favors platforms with block-booking capabilities and flexible cancellation terms, particularly for educational and corporate retreat segments.
- Families:Multi-room booking requirements and child-policy filtering create demand for platforms with advanced search granularity and package bundling features.
Leisure Travelers command the established base. The steepest expansion runs through Families.
Service Type:
Margin structure varies sharply across tiers, with budget properties accepting algorithmic yield management while luxury operators resist dynamic discounting to protect brand positioning.
- Budget Hotels:Automated occupancy maximization and high turnover attract platform investment, with price-sensitive demand elasticity enabling rapid inventory turnover through opaque discount channels.
- Luxury Hotels:Concierge-assisted reservations and premium direct-rate channels dominate, as brand protection concerns limit participation in algorithmic pricing systems. These properties prioritize customer relationship ownership.
- Boutique Hotels:Curated experiential positioning targets design-conscious leisure travelers, requiring platforms with rich media capabilities and review aggregation.
- Hostels:Bed-level inventory granularity and social atmosphere marketing appeal to inbound foreign demand and younger domestic segments.
Budget Hotels command the established base. The steepest expansion trajectory belongs to Boutique Hotels.
Payment Method:
JIS standards govern security certification requirements, with compliance friction disproportionately impacting smaller ryokan operators seeking platform onboarding.
- Credit Card:Stored credential systems enable one-tap completion, with domestic issuers integrating deeply into super-app loyalty ecosystems.
- Debit Card:Real-time settlement reduces chargeback risk for platforms, though lower spending limits constrain average transaction value.
- PayPal:Cross-border payment rails serve inbound foreign demand, particularly for Booking.com and international OTA transactions.
- Bank Transfer:Traditional settlement persists for corporate accounts and group bookings, though manual reconciliation delays confirmation speed.
Credit Card commands the established base. The steepest expansion runs through PayPal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's hotel booking infrastructure funnels domestic leisure demand through Tokyo-Osaka-Kyoto corridor platforms, while inbound foreign traffic concentrates in gateway cities with multilingual service capabilities.
Kanto/Tokyo
Corporate travel management and high-frequency leisure transactions dominate platform volume in the capital region. METI's tourism digitization grants accelerated property management system upgrades across Shinjuku and Shibuya hotel clusters. Platform competition intensifies around one-tap mobile completion rates among younger metropolitan cohorts.
Kansai/Osaka
Universal Studios and convention center proximity sustains group booking demand through specialized OTA channels. JIS payment security compliance requirements filter smaller ryokan operators from platform onboarding in Osaka Prefecture. Luxury chains in Umeda and Namba districts prioritize direct-booking infrastructure to capture customer relationship ownership.
Chubu/Nagoya
Manufacturing sector business travel historically anchored this region's platform demand, though leisure displacement is accelerating. PMDA sanitation certification verification creates documentation friction for traditional inn properties seeking listing eligibility. Platform investment concentrates on Nagoya Station vicinity inventory for transit-connected convenience.
Kyushu
Onsen and rural experiential properties attract post-pandemic domestic leisure migration away from urban corridors. Deep supply relationships with untiered ryokan networks unlock pricing power for platforms specializing in curated destination content. Fukuoka's startup ecosystem incubates niche booking applications targeting younger traveler segments.
Hokkaido
Seasonal ski resort and summer outdoor activity demand creates sharp occupancy volatility requiring dynamic yield algorithms. Sapporo and Niseko clusters concentrate platform inventory aggregation, with multilingual interfaces capturing inbound foreign recovery. Legacy property management integration gaps delay real-time availability updates at remote onsen properties.
Japan Hotel Booking Market Competitive Landscape
Listed platform operators compete with private specialists across loyalty ecosystem integration and supply relationship depth. The market structure bifurcates between vertically integrated super-app ecosystems controlling domestic transaction volume and foreign-facing intermediaries dependent on inbound arrival recovery. Three strategic archetypes dominate: domestic loyalty-integrated platforms, international OTA multinationals, and traditional travel agency digitizers. Competitive moves concentrate on API connectivity expansion and direct-booking incentive countermeasures.
Among domestic platform operators, Rakuten Travel exemplifies super-app ecosystem leverage through loyalty currency fungibility, while Jalan occupies a position anchoring rural and onsen inventory relationships. Booking.com represents the inbound-focused multinational archetype competing on multilingual interface investment and international payment rail integration.
| Leading Market Players |
|---|
| Rakuten Travel |
| Jalan |
| Booking.com |
| Expedia Group |
| Agoda |
| JAPANiCAN |
| Hotels.com |
| Yahoo Travel |
| JTB Group |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements between platform operators and hotel chains lock in preferential inventory access while anchoring commission visibility across the Tokyo-Osaka-Kyoto corridor. These contractual structures concentrate pricing power with vertically integrated super-app ecosystems that bundle lodging with payment rails and loyalty currencies.
Pricing Analysis
Platform-generation pricing gaps separate API-native mobile ecosystems from legacy GDS-dependent intermediaries, with newer entrants commanding premium placement fees for one-tap completion infrastructure. Three-tier pricing structure across premium direct-booking, standard OTA commission, and economy opaque inventory segments reflects property tier and customer ownership strategy. Cost compression in standard OTA tiers intensifies because luxury chains deploy direct-booking incentives to bypass intermediary fees. Budget hotel operators exhibit highest price sensitivity, while luxury properties prioritize brand protection over algorithmic discount participation.
Supply Chain Analysis
Real-time inventory lead times compress to seconds at API-integrated urban properties while extending to hours at legacy ryokan operations lacking property management system connectivity. Platform supply draws from Japan's domestic hotel infrastructure, South Korea's technology middleware providers, and Singapore's cloud hosting clusters for regional latency optimization. API connectivity modules, payment security certification layers, and multilingual interface localization constitute critical input dependencies. Single-source vulnerability concentrates in Rakuten's loyalty currency ecosystem, which controls repeat domestic booking circulation. Distribution runs through super-app marketplaces, direct proprietary channels, and international OTA aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform fragmentation creates acquisition opportunities as mobile-first leisure demand splinters across specialized rural inventory aggregators, experiential content curators, and foreign-facing multilingual intermediaries. Post-pandemic booking behavior shifts toward single-session mobile completion, opening niches for niche supply relationships and loyalty currency innovation.
For Market Incumbents: Shield commission structures from erosion by accelerating proprietary payment credential storage and deepening ryokan supply exclusivity. Counter Booking.com's multilingual interface investment with targeted inbound partnership programs. Vertical integration into property management system middleware preserves API connectivity advantages against interoperability mandates. For New Entrants and Emerging Players: Lead with rural onsen inventory aggregation where Jalan's supply relationships remain penetrable through curated experiential content and dynamic yield tools for untiered properties. Target Kyushu and Hokkaido regional corridors where platform concentration is lowest. Deploy influencer-driven destination marketing to bypass super-app loyalty lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward boutique platform operators with deep supply relationships in rural experiential inventory and demonstrated mobile conversion optimization. Five-to-ten year viability hinges on METI interoperability mandate outcomes and inbound foreign arrival recovery trajectory. Monitor PMDA sanitation certification automation as inflection signal for ryokan onboarding friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| API Connectivity Expansion | Real-time inventory synchronization with legacy ryokan property management systems reduces booking abandonment. |
| Loyalty Currency Fungibility Program | Cross-platform point interoperability erodes Rakuten's super-app ecosystem moat and unlocks customer acquisition. |
| Multilingual Interface Investment | Japanese-English-Chinese-Korean localization captures inbound foreign demand recovery in gateway cities. |
| Direct Booking Incentive Deployment | Luxury chains bypass OTA commission compression through proprietary reservation infrastructure ownership. |
| Rural Inventory Aggregation Partnership | Deep supply relationships with untiered onsen properties unlock pricing power in experiential travel segments. |
Research Methodology
A standing panel of platform product managers, hotel chain revenue directors, ryokan association representatives, and METI tourism policy officers provided ongoing calibration against market developments. Primary interviews with OTA executives, property management system vendors, and mobile payment integration specialists combined with secondary validation through JTB Group travel trend reports, METI tourism digitization grant disclosures, and JIS standards documentation. Bottom-up transaction volume modeling and top-down macroeconomic triangulation anchored value estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include booking platform architecture, customer segment behavior, service type tier, and payment method compliance tier. CAGRs derived from historical trajectory analysis adjusted for policy intervention timing and technology adoption S-curves. Smartphone penetration curves and METI infrastructure grant disbursement schedules served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in METI tourism digitization frameworks and JIS payment security regimes; material policy shifts would require re-modeling. Pandemic protocol evolution and inbound foreign arrival volatility constitute specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies IT Spending Market
Online Travel Agencies (OTAs) and Booking Platforms
Europe Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Latin America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Accommodation Booking Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agencies (Otas) Services Market
Online Travel Agencies (OTAs) and Booking Platforms
Travel Service Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
India Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
North America Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Global Online Airline Booking Platform Market
Online Travel Agencies (OTAs) and Booking Platforms
United Kingdom Online Travel Market
Online Travel Agencies (OTAs) and Booking Platforms
Online Travel Agent Market