
 Airline Retailing Market | 2026-2036
Airline Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Airline Retailing Market Insights
NDC-based distribution is fragmenting legacy GDS-centric retail architectures across commercial aviation. Travelport anchors its position through API-first connectivity layers that bypass traditional EDIFACT pipes. United Airlines leverages direct channel investments to capture higher-margin ancillary revenue outside conventional booking flows. American Airlines competes via aggressive NDC content partitioning that steers price-sensitive segments toward proprietary platforms.
Airline retailing encompasses the merchandising of goods and services to passengers across pre-flight, in-flight, and post-flight touchpoints, utilizing dynamic pricing engines and personalized offer management systems to maximize per-passenger yield. Duty-free goods and in-flight merchandise represent mature margin pools where inventory turnover and concession economics determine profitability, while mobile apps and loyalty programs constitute the fastest-growing channels as carriers embed retail into frequent flyer ecosystems. Food and beverage segments retain structural importance on long-haul routes where captive audience economics sustain premium pricing.
FAA oversight of in-flight safety standards shapes product screening protocols for items sold aboard US-registered aircraft, while IATA's One Order framework redefines settlement compliance across international itineraries. The EU Green Deal's sustainable aviation fuel mandates indirectly pressure retailers to certify supply chain emissions for airport concession contracts. Stakeholders must monitor how NDC adoption rates among mid-tier carriers reshape access negotiations between airlines and airport retail concessionaires.
Market Dynamics
NDC-based distribution architectures are fragmenting legacy GDS-centric retail structures across commercial aviation, forcing carriers to rebuild merchandising capabilities around direct API connectivity and personalized offer management systems.
Growth Catalysts
- IATA One Order Framework:This settlement standard modernizes order management across international itineraries, eliminating legacy document fragmentation. Carriers adopting One Order reduce operational complexity in multi-leg retail transactions.
- Mobile-First Loyalty Integration:Frequent flyer ecosystems now embed retail touchpoints into app-based engagement loops. Passengers convert points into duty-free purchases at higher rates than traditional redemption catalogs.
- Hub Airport Premiumization:Concentrated passenger flows at major US gateway airports create captive audiences for luxury concession partnerships. Dallas-Fort Worth and Atlanta generate disproportionate per-passenger retail yield.
Market Restraints
- Aviation Fuel Cost Volatility:Jet fuel price swings compress operating margins, diverting capital from cabin retrofit programs and retail space expansion. Carriers defer onboard inventory investments during fuel spike periods.
- Concession Revenue Concentration:Three global duty-free operators control majority share of prime airport retail contracts. New entrants face prohibitive minimum revenue guarantees to secure shelf space.
- Legacy PSS Integration Friction:Older passenger service systems lack real-time inventory synchronization with retail platforms. Airlines running Amadeus Altéa or SabreSonic face extended API development timelines.
Strategic Opportunities
- India Domestic Route Expansion:Low retail penetration on Indian carriers' narrow-body fleets creates first-mover advantage for onboard F&B and merchandise programs. IndiGo and Air India operate combined fleet exceeding 1,500 aircraft with minimal retail infrastructure.
- EU Green Deal Supply Chain Certification:Sustainable aviation fuel mandates pressure airport concessionaires to verify Scope 3 emissions. Retailers certifying carbon-neutral product lines gain preferential contract terms at Amsterdam Schiphol and Frankfurt.
- Biometric Payment Convergence:Facial recognition boarding gates now integrate with tokenized payment systems. United and Delta trial touchless retail transactions where passenger identity triggers personalized offers without card presentation.
Industry Challenges
- Merchandising Talent Scarcity:Airlines lack personnel combining aviation operations expertise with retail category management. Legacy crew scheduling systems conflict with inventory replenishment cycles.
- Cabin Space Reconfiguration Costs:Installing retail stowage and point-of-sale hardware requires FAA-certified modification programs. Each aircraft type demands separate supplemental type certificate applications.
- Cross-Border Tax Complexity:Duty-free pricing engines must reconcile destination country VAT rules, origin country export restrictions, and overflight jurisdiction requirements in real time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airline Retailing Market |
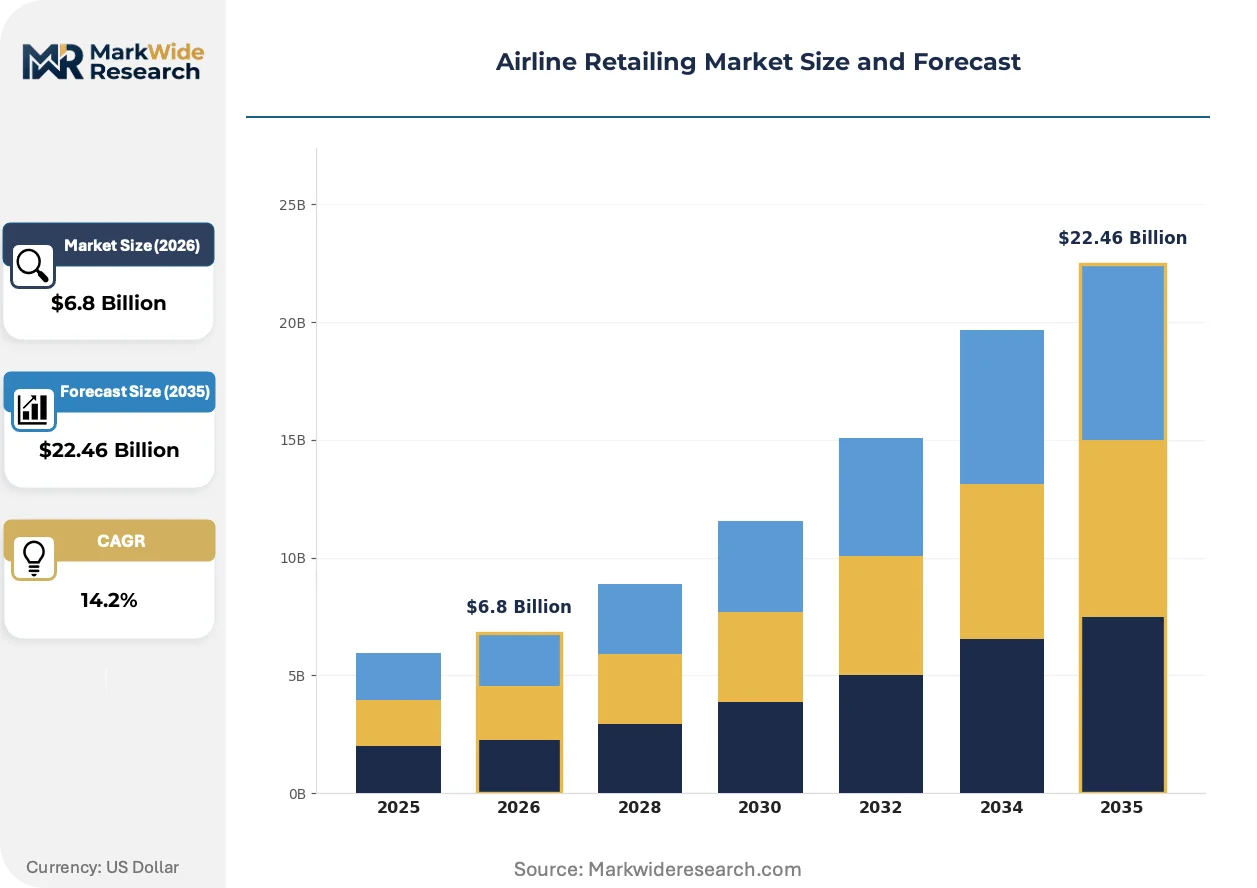
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Duty-Free Goods, In-Flight Merchandise, Travel Accessories, Food & Beverage Sales Channel: Online Booking, Airport Retail, In-Flight Sales, Mobile Apps Customer Type: Leisure Travelers, Business Travelers, Group Bookings, Frequent Flyers Service Type: Pre-Flight Services, In-Flight Services, Post-Flight Services, Loyalty Programs |
| Companies Covered | Travelport, Threedot, United Airlines, Alaska Airlines, American Airlines, Iberia, Vantage Group, Munich Airport, Icelandair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airline Retailing Market Trends and Innovations
Virtual retail environments and AI-driven personalization engines are compressing the path between passenger intent and transaction completion across every flight phase.
Distributed ledger technology is virtualizing settlement reconciliation between airlines, airport concessionaires, and payment processors. Carriers including Lufthansa Group pilot blockchain-based duty-free revenue sharing that eliminates 30-day reconciliation lags. This architecture compresses working capital requirements for inventory-heavy retail operations.
EU Green Deal sustainable aviation fuel mandates are reshaping concession procurement criteria. Airport authorities at Paris Charles de Gaulle and Munich now require retail partners to submit product-level carbon footprint documentation. Luxury brands responding with certified sustainable packaging gain shelf placement priority in renovated terminals.
Pre-order behavior is displacing impulse purchasing as the dominant duty-free transaction pattern. Passengers on Emirates and Qatar Airways now complete retail selections 48 hours pre-departure via mobile apps, with goods delivered seat-side. This shift concentrates demand forecasting accuracy requirements onto digital channels rather than cabin inventory management.
Airline Retailing Market Segmentation
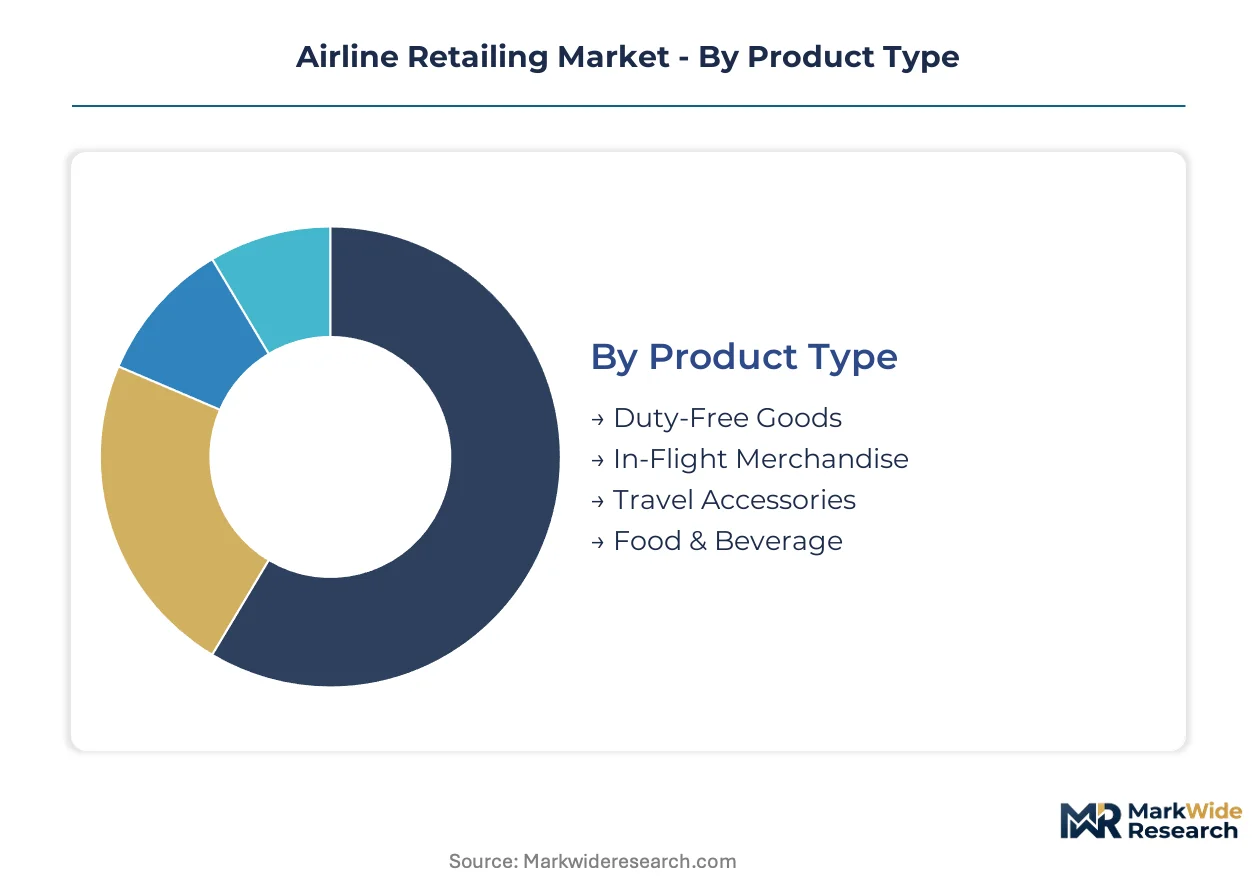
Segmentation in airline retailing determines how carriers allocate merchandising investments across passenger touchpoints and purchasing contexts. Each dimension shapes inventory planning, pricing architecture, and partnership negotiations with airport concessionaires.
Product Type:
Duty-free goods and in-flight merchandise anchor opposite ends of the margin spectrum, with travel accessories and F&B occupying intermediate positions based on route length and cabin class.
- Duty-Free Goods:High-margin luxury categories including fragrances, cosmetics, and spirits dominate revenue pools at hub airports. Dubai Duty Free and Seoul Incheon generate disproportionate per-passenger yield from Chinese and Middle Eastern travelers. Regulatory complexity around liquid restrictions and destination country import limits constrains category expansion.
- In-Flight Merchandise:Curated electronics, branded apparel, and destination-specific souvenirs sold through seat-back catalogs and crew trolley service. Narrow-body fleets on domestic US and European routes show minimal penetration, creating whitespace for equipment retrofit programs.
- Travel Accessories:Neck pillows, noise-canceling headphones, and power adapters address immediate passenger pain points. IndiGo and Ryanair extract ancillary revenue through pre-positioned seat-back inventory on high-frequency short-haul sectors.
- Food & Beverage:Buy-on-board menus and premium cabin dining drive per-passenger yield on long-haul routes where captive audience economics sustain pricing power.
The dominant share belongs to Duty-Free Goods, while Food & Beverage is closing the gap fastest through dynamic pricing engines and pre-order mobile integration.
Sales Channel:
Channel strategy determines whether airlines capture retail margin directly or concede revenue share to airport concessionaires and GDS intermediaries.
- Online Booking:Ancillary bundling during ticket purchase captures passenger commitment before travel friction accumulates. Lufthansa and British Airways embed seat upgrades, baggage, and lounge access into dynamic package builders at checkout.
- Airport Retail:Concession-operated duty-free stores at Heathrow Terminal 5 and Singapore Changi T3 generate fixed rent plus revenue-share structures. Three global operators control majority shelf space, extracting minimum revenue guarantees from luxury brand suppliers.
- In-Flight Sales:Crew-assisted transactions and seat-back catalog orders rely on inventory stowage capacity and payment terminal connectivity. FAA certification requirements for onboard point-of-sale hardware extend deployment timelines.
- Mobile Apps:Frequent flyer ecosystems embed retail touchpoints with biometric payment integration. United and Delta trial facial recognition-triggered offers that eliminate card presentation friction.
Mobile Apps command the steepest expansion trajectory as loyalty program digitization accelerates, though Airport Retail retains absolute transaction volume.
Customer Type:
Passenger mix varies by route network, with hub-and-spoke carriers serving distinct retail profiles compared to point-to-point low-cost operators.
- Leisure Travelers:Price-sensitive segments with high propensity for duty-free impulse purchases and destination merchandise. Vacation routes to Orlando and Las Vegas show elevated spend per passenger on in-flight F&B.
- Business Travelers:Time-constrained passengers prioritizing convenience and quality over price sensitivity. Priority boarding bundles and premium cabin upgrades capture margin without extending ground time.
- Group Bookings:Consolidated purchasing power from tour operators and corporate travel managers. Volume discounts compress per-unit margin while guaranteeing inventory turnover.
- Frequent Flyers:Loyalty program members converting points into retail redemptions at rates exceeding traditional catalog options. American AAdvantage and Delta SkyMiles drive engagement through app-based retail touchpoints.
Frequent Flyers deliver the highest lifetime retail value, while Leisure Travelers provide the broadest volume base for inventory amortization.
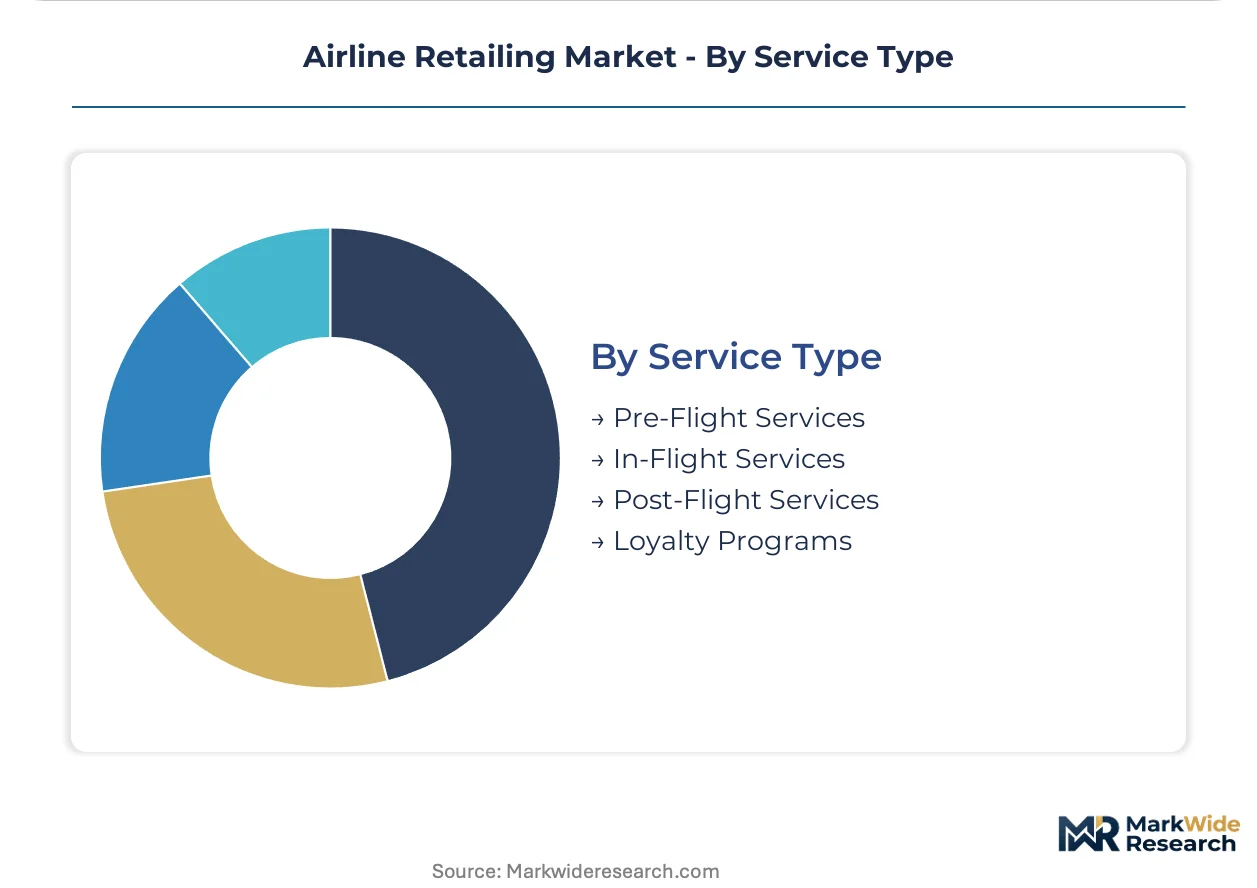
Service Type:
Temporal positioning relative to flight departure determines system integration requirements and partnership structures with ground handlers and airport authorities.
- Pre-Flight Services:Lounge retail, curbside baggage handling, and priority security lanes monetize ground dwell time. Emirates and Qatar Airways extend retail selection windows through 48-hour pre-departure mobile ordering with seat-side delivery.
- In-Flight Services:Cabin-based merchandising requires FAA-certified equipment modifications and crew training programs. Each aircraft type demands separate supplemental type certificate applications for retail stowage installation.
- Post-Flight Services:Arrival duty-free, baggage delivery, and ground transportation bookings capture spend after passenger release from cabin constraints. Limited infrastructure constrains scale outside major hub airports.
- Loyalty Programs:Points-based retail ecosystems embed merchandising into engagement loops. Singapore Airlines KrisFlyer and Cathay Pacific Asia Miles drive higher conversion rates than standalone redemption catalogs.
In-Flight Services retain structural importance for margin capture, though Pre-Flight Services is expanding most quickly through mobile pre-order adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Duty-free merchandise flows from European and Middle Eastern hub airports toward high-spending travelers from Asia-Pacific markets, with passenger traffic patterns dictating retail revenue distribution across origin-destination corridors.
United States
Hub-and-spoke carriers at Dallas-Fort Worth and Atlanta drive premium concession yields through concentrated international transfer traffic. FAA certification requirements for onboard point-of-sale hardware extend deployment timelines for cabin retail retrofits. Miami International Airport anchors Latin America-bound duty-free flows, with Spanish-language merchandising capturing outbound leisure segments.
United Arab Emirates
Dubai Duty Free generates disproportionate per-passenger spend from Chinese and Middle Eastern travelers transiting through Emirates' hub network. The country's aviation regulator mandates fire-safety screening protocols for all inflight retail inventory. Dubai International Airport Terminal 3 concentrates luxury brand concession contracts under long-term revenue-share arrangements.
Germany
Lufthansa Group pilots blockchain-based duty-free settlement reconciliation that eliminates month-long payment lags between carriers and concessionaires. EU Green Deal sustainable aviation fuel mandates pressure Frankfurt and Munich airport authorities to require product-level carbon footprint documentation from retail partners. Munich Airport operates integrated retail-development subsidiaries that control concession economics directly.
China
Outbound tourism recovery at Shanghai Pudong and Beijing Capital drives fragrance and cosmetics category expansion in renovated terminal retail zones. The country's national aviation regulator maintains strict liquid-restriction enforcement that shapes duty-free packaging formats. Hainan Island's offshore duty-free policy diverts spending from traditional airport channels through city-center retail licenses.
United Kingdom
Heathrow Terminal 5 concession structures extract minimum revenue guarantees from luxury suppliers seeking access to transatlantic business travelers. UK customs regulations post-EU exit complicate VAT-free pricing engines for multi-leg European itineraries. London Gatwick's low-cost carrier terminals show minimal retail penetration, creating whitespace for equipment retrofit programs.
Airline Retailing Market Competitive Landscape
On the supply side, the industry is bifurcated between global distribution system incumbents and carrier-direct retail platforms, with airport concessionaires occupying an intermediate position that extracts rent from both technology providers and airlines. Three strategic archetypes dominate: API-first connectivity platforms, loyalty-integrated carrier direct channels, and hub-airport retail operators controlling physical concession space. Competitive moves concentrate on NDC content partitioning and biometric payment convergence rather than traditional capacity expansion.
Among carrier-direct retail specialists, United Airlines and American Airlines exemplify the platform-control archetype, while Travelport occupies the connectivity-layer position bridging legacy GDS infrastructure and modern API distribution. Alaska Airlines and Icelandair represent mid-tier carriers experimenting with retail monetization outside traditional hub economics. Iberia anchors European carrier retail development through Madrid-Barajas hub concentration, with Vantage Group and Threedot sitting within the technology-enablement tier that supplies personalization engines and dynamic pricing infrastructure to airline retail operations.
| Leading Market Players |
|---|
| Travelport |
| Threedot |
| United Airlines |
| Alaska Airlines |
| American Airlines |
| Iberia |
| Vantage Group |
| Munich Airport |
| Icelandair |
| Others |
Pricing and Supply Chain Analysis
Dubai Duty Free's concentrated luxury concession capacity at Terminal 3 creates asymmetric pricing power over European and Asian hub competitors, with Emirates' transfer passenger volumes dictating margin extraction rates from fragrance and cosmetics suppliers seeking shelf access.
Pricing Analysis
Legacy EDIFACT-based distribution technology commands lower revenue-share terms than NDC-enabled API connectivity, creating a two-tier pricing structure where carriers with direct channel investments capture higher ancillary margins. Price differentiation rests on certification level—IATA One Order compliance versus legacy settlement fragmentation—and on vertical integration depth into loyalty program ecosystems. Cost compression in duty-free merchandise is intensifying because three global concessionaires extract minimum revenue guarantees that compress supplier margins. Leisure travelers on vacation routes show highest price sensitivity, while frequent flyers redeeming points demonstrate lowest effective price elasticity.
Supply Chain Analysis
Heinemann, Dufry, and Lotte Duty Free control majority contract-manufacturing capacity for airport retail inventory, with their procurement offices concentrated in Switzerland, Germany, and South Korea. Raw material dependencies center on certified sustainable packaging substrates, EU Green Deal-compliant aviation fuel documentation, and blockchain-enabled settlement infrastructure. Single-source vulnerability runs through the concentrated concessionaire tier, where loss of one major hub contract would strand inventory across multiple supplier relationships. Distribution feeds from centralized European and Middle Eastern bonded warehouses into hub airport retail zones via customs-controlled logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airline retailing operates as a defensive-moat market where regulatory entrenchment through FAA certification requirements and IATA settlement standards creates durable barriers against new platform entrants.
For Market Incumbents: Build switching-cost moats through deeper API-first loyalty integration that embeds retail touchpoints into frequent flyer app ecosystems. Incumbent carriers should secure supplemental type certificates for retail stowage modifications before fuel price volatility diverts capital, and should deepen backward integration into pre-flight mobile ordering platforms to capture margin outside concessionaire revenue-share structures.
For New Entrants and Emerging Players: India's domestic narrow-body fleet penetration gap offers first-mover positioning for onboard F&B and merchandise programs before IndiGo and Air India retrofit retail infrastructure. New entrants should target biometric payment convergence trials at secondary US hubs where United and Delta have not yet deployed facial recognition retail triggers, and should pursue white-label technology supply to mid-tier carriers lacking in-house NDC development capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors connectivity-layer specialists bridging legacy GDS infrastructure and modern API distribution over carrier-direct retail platforms facing capital intensity headwinds. Long-term viability across the projection horizon rests on acquisition of personalization engine providers serving multiple airline clients rather than single-carrier captive technology. Investors should monitor NDC adoption rates among mid-tier carriers as the inflection signal for connectivity platform valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| NDC API Platform Integration | Travelport's connectivity layer bypasses legacy EDIFACT pipes to capture higher-margin direct distribution. |
| Biometric Payment Convergence | United and Delta trials of facial recognition retail eliminate card friction and accelerate transaction velocity. |
| Sustainable Supply Chain Certification | EU Green Deal mandates at Frankfurt and Munich pressure concessionaires to verify Scope 3 emissions documentation. |
| Pre-Flight Mobile Ordering Expansion | Emirates and Qatar Airways extend retail windows through 48-hour advance ordering with seat-side delivery. |
| Blockchain Settlement Pilot | Lufthansa Group eliminates 30-day reconciliation lags through distributed ledger duty-free revenue sharing. |
Research Methodology
The analysis maps duty-free merchandise, in-flight retail, loyalty program ecosystems, and pre-flight mobile ordering, each validated through airline merchandising executives, airport concession managers, GDS platform engineers, and IATA standardization leads. Primary interview insights triangulate against secondary sources including IATA settlement documentation, FAA certification filings, EU Green Deal regulatory texts, and airport authority concession contract disclosures. Bottom-up passenger spend modeling and top-down market sizing converge through carrier-reported ancillary revenue disclosures and duty-free operator financial statements.
Assumption sets hold jet fuel price volatility within historical bands and NDC adoption rates at mid-tier carriers within observed trajectories across the projection horizon. Segmentation dimensions modeled include product category, sales channel architecture, customer loyalty tier, and service timing relative to flight departure. CAGRs derive from passenger traffic forecasts, per-passenger retail spend elasticity curves, and channel mix shift assumptions. Industry-specific inputs incorporate IATA One Order implementation timelines and biometric payment trial expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive direct-channel investment by legacy network carriers or rapid regulatory relaxation of cabin retail certification would shift outcomes. Model boundaries exclude city-center duty-free diversion effects and non-aviation loyalty program cross-over spending. Quarterly review of NDC adoption metrics, fuel price volatility indices, and concession contract renewal activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
Flower Delivery Services Market
Travel and Tourism
Leisure Travel Market
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
United Kingdom Casino Tourism Market
Travel and Tourism
Vietnam Online Travel Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
Japan Tourism Market
Travel and Tourism
Special Interest Tourism Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
South Korea Travel Retail Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
Camping and Caravanning Market
Travel and Tourism
Yacht Charter Market
Travel and Tourism
Sustainable Tourism Market
Travel and Tourism
Asia-Pacific MICE Tourism Market