
 Global Subscription Analytics Software Market | 2026-2036
Global Subscription Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Subscription Analytics Software Market Foresight
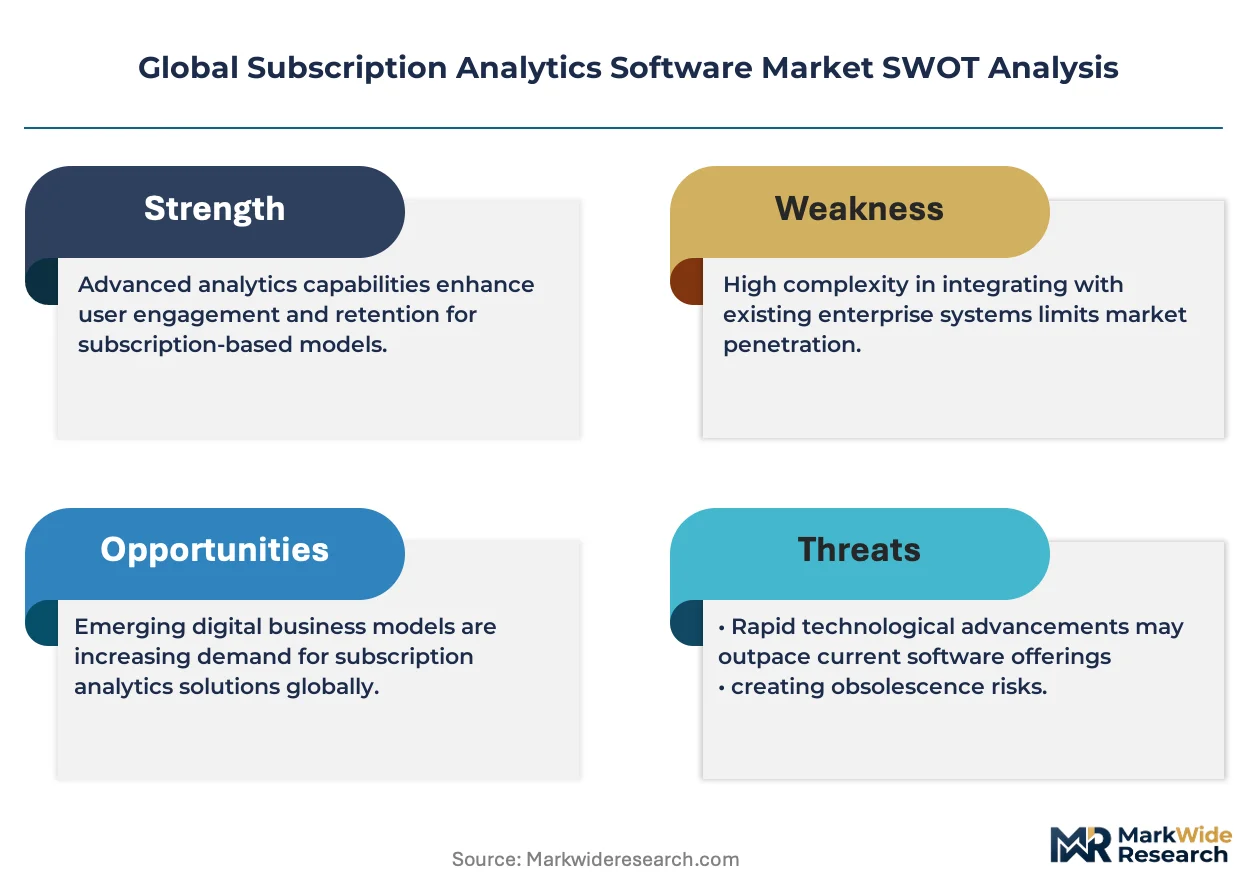
Data science talent scarcity is unwinding implementation timelines for advanced subscription analytics platforms. Chargebee leverages embedded analytics to deepen platform stickiness among mid-market SaaS vendors. Zuora sustains category leadership through its native integration with enterprise billing workflows. ChartMogul competes on pricing transparency, attracting European scale-ups seeking cost-efficient cohort analysis.
Subscription analytics software encompasses cloud-deployed applications that ingest recurring revenue streams, normalize billing events, and output predictive metrics such as net revenue retention and customer lifetime value. These systems process high-velocity event data from payment gateways, CRM instances, and product telemetry to surface monetization risks and expansion opportunities. Cloud-based deployment leads solution uptake due to elastic infrastructure and faster time-to-value, while churn prediction commands disproportionate R&D investment as vendors race to reduce false-positive cancellation signals. Revenue optimization modules are gaining share fastest among financial services end users seeking dynamic pricing experimentation.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that constrain model architecture choices for vendors serving European SaaS and media clients. The US lacks federal privacy parity, though state-level frameworks such as California's CCPA create compliance fragmentation that increases implementation complexity. Stakeholders must evaluate whether their analytics stacks can adapt to emerging algorithmic accountability standards without degrading real-time inference latency.
Market Dynamics
Recurring revenue normalization is forcing vendors to rebuild analytics architectures around event-stream ingestion rather than batch processing, compressing implementation timelines and elevating data engineering talent costs.
Growth Catalysts
- EU AI Act compliance mandates:European SaaS operators must deploy algorithmic transparency tools for automated churn scoring, creating procurement urgency for explainable ML modules.
- Embedded finance proliferation:Banking-as-a-Service integrations in subscription platforms generate granular payment telemetry that feeds predictive retention models.
- Netherlands SaaS cluster density:Amsterdam's concentration of scale-ups operating under GDPR creates concentrated demand for residency-compliant analytics infrastructure.
Market Restraints
- Cloud egress cost volatility:Cross-border data movement between payment processors and analytics engines exposes operators to unpredictable bandwidth pricing from hyperscalers.
- Model interpretability constraints:Black-box neural approaches for churn prediction face rejection by risk committees at financial services end users requiring auditable decision trails.
- GDPR algorithmic audit requirements:Article 22 provisions mandate human-in-the-loop overrides that degrade real-time inference throughput for European deployments.
Strategic Opportunities
- India PLI scheme for SaaS:Production-linked incentives for software exports create cost arbitrage for analytics vendors establishing development centers in Bangalore and Hyderabad.
- Edge inference convergence:On-device telemetry processing at payment terminals merges with cloud analytics, enabling sub-second cancellation risk alerts without full data centralization.
- Revenue recognition automation:ASC 606 and IFRS 15 compliance workflows represent adjacent white space for vendors bundling analytics with audit-ready reporting.
Industry Challenges
- Data engineering talent scarcity:Pipeline construction for high-velocity billing event streams requires specialized Spark and Kafka expertise that commands premium compensation in competitive labor markets.
- CRM integration complexity:Multi-instance Salesforce and HubSpot environments at enterprise clients demand bespoke connector development that fragments vendor engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Subscription Analytics Software Market |
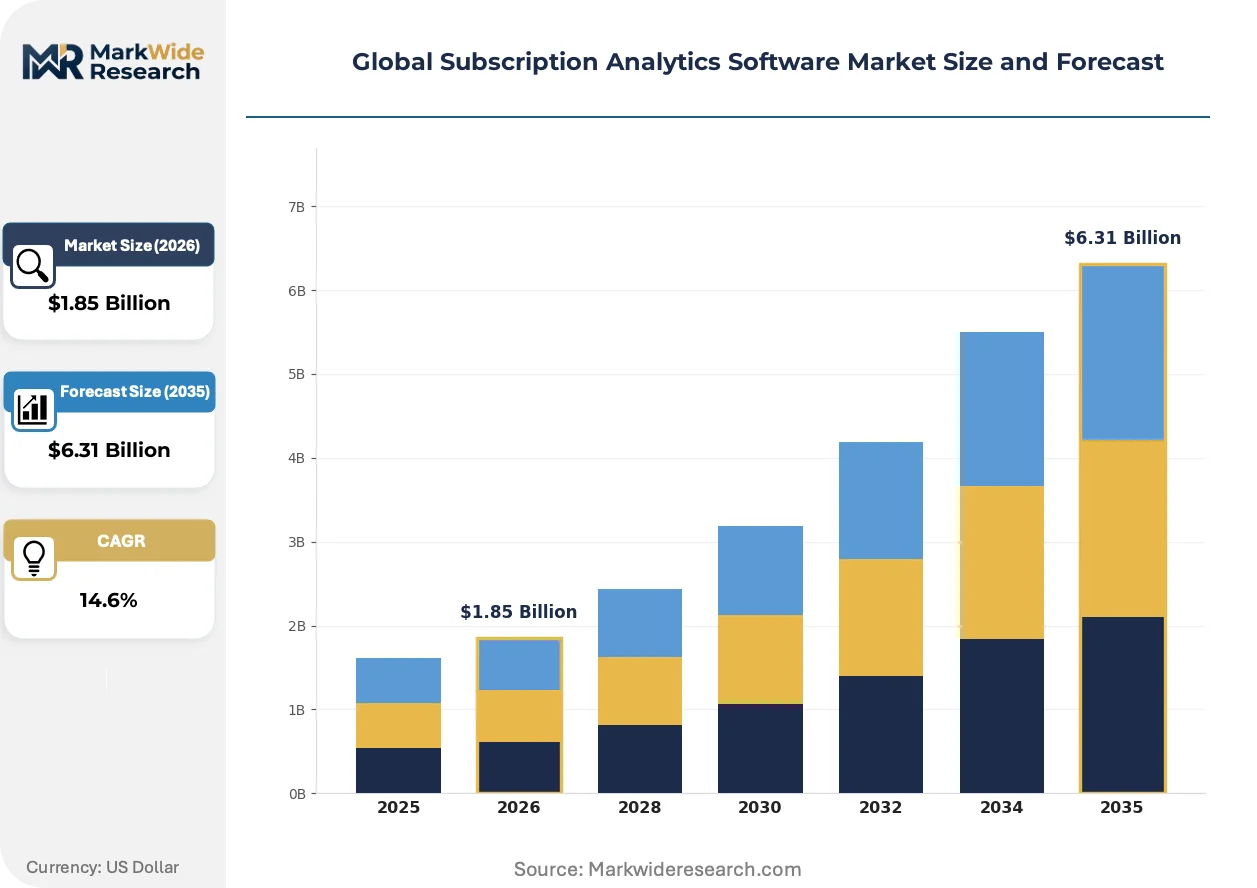
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Hosted Solution Type: Churn Prediction, Customer Segmentation, Revenue Optimization, Usage Analytics, Pricing Strategy Use Case: Customer Retention, Market Expansion, Sales Forecasting, Subscription Management, Fraud Detection End User Industry: Telecom Providers, SaaS Companies, Media & Entertainment, Financial Services, E-Learning Platforms |
| Companies Covered | Chargebee, Maxio, ChartMogul, Baremetrics, ProfitWell, Recurly, Zuora, RevenueCat, Fincome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Subscription Analytics Software Market Shifts & Advancements
Real-time feature engineering is compressing the gap between raw billing events and actionable retention signals, reshaping how vendors architect streaming data infrastructure.
Embedded machine learning is displacing standalone predictive analytics modules. SaaS platforms now ingest pre-trained churn models directly into their billing stacks, eliminating the latency of external API calls. Mid-market vendors in the United States are adopting this pattern fastest, prioritizing sub-100-millisecond inference over model sophistication. The shift is displacing traditional BI-tool integrations that required manual data exports and overnight batch processing.
The EU AI Act's risk classification framework is restructuring vendor roadmaps. High-risk algorithmic systems for credit scoring and churn prediction face mandatory conformity assessments before deployment. European SaaS operators serving financial services clients are rebuilding model governance workflows to satisfy these requirements. Germany's KBA and France's CNIL are already issuing interpretive guidance that tightens documentation standards beyond baseline EU text.
Usage-based pricing experimentation is altering procurement patterns. Enterprise buyers now pilot analytics tools on consumption metrics rather than seat-based licenses, compressing initial contract values while extending evaluation cycles. This pattern is most visible among Series C software companies in California and New York, where finance teams demand direct linkage between tool cost and measured revenue impact.
Global Subscription Analytics Software Market Segmentation
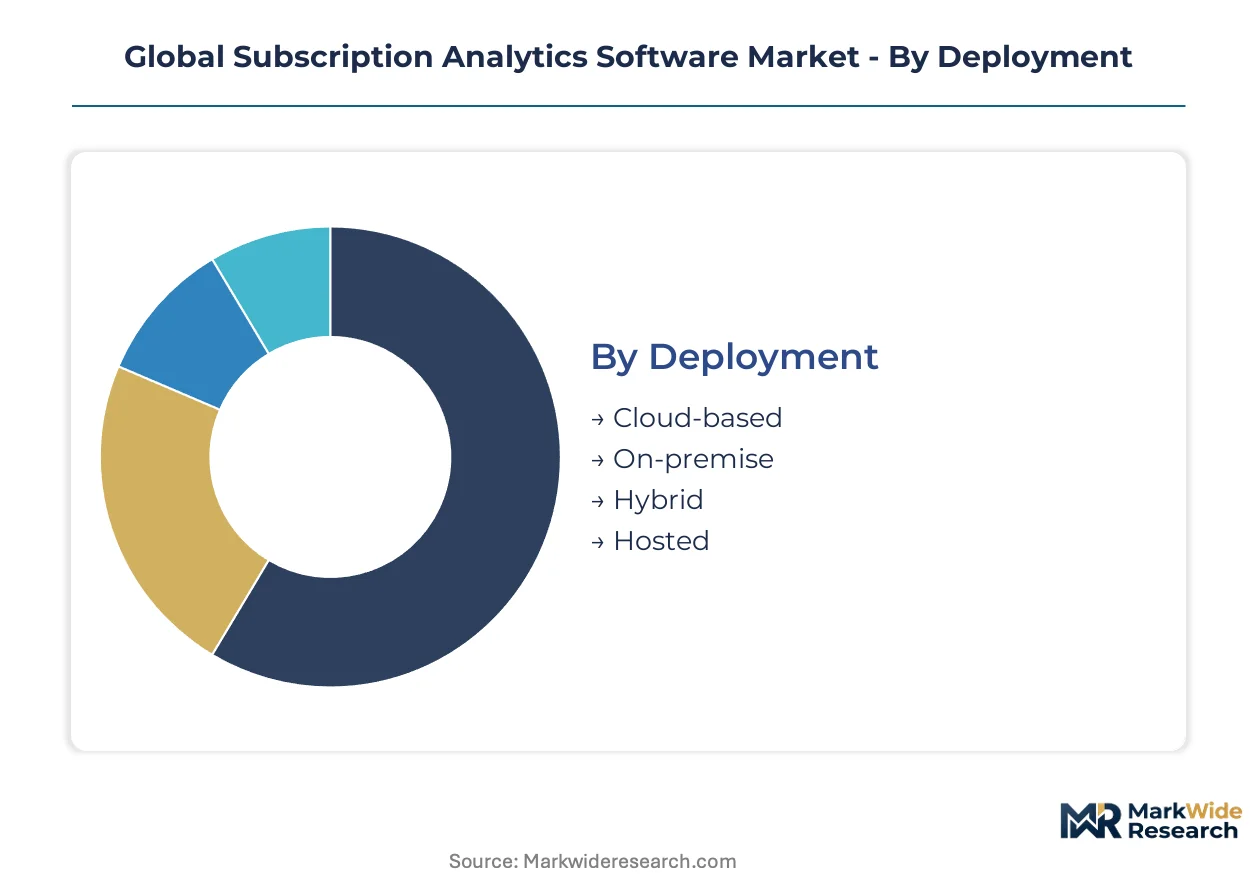
Deployment architecture determines infrastructure cost structures and compliance posture for subscription analytics implementations. Solution type segmentation reveals where vendors concentrate R&D investment against churn and revenue leakage. Use case and end-user splits expose which industries generate the highest event-stream volumes and the most stringent latency requirements.
Deployment:
Margin pools concentrate in cloud-native configurations that amortize infrastructure across multi-tenant deployments.
- Cloud-based:Elastic compute and storage resources scale with billing event velocity. SaaS companies in the United States favor this model for sub-hour deployment timelines and reduced data engineering headcount.
- On-premise:Dedicated hardware installations satisfy data residency mandates in regulated sectors. Financial services institutions in Germany maintain these deployments to satisfy BaFin audit requirements for algorithmic decision trails.
- Hybrid:Sensitive customer data remains on local servers while compute-intensive model training leverages cloud burst capacity. Telecom providers in India adopt this pattern to balance TRAI data localization rules with GPU access.
- Hosted:Single-tenant managed services reduce operational burden without full cloud migration. Mid-market SaaS vendors in the Netherlands select this option to meet GDPR processor agreement standards.
The dominant share belongs to Cloud-based, while Hybrid is closing the gap fastest as regulatory fragmentation intensifies.
Solution Type:
Application intensity varies sharply by module, with predictive capabilities commanding premium pricing against descriptive analytics.
- Churn Prediction:Machine learning models score cancellation probability from product usage telemetry and support ticket sentiment. Financial services end users in the United States drive demand for explainable outputs that satisfy internal risk committee review.
- Revenue Optimization:Dynamic pricing experiments and expansion revenue identification algorithms process cohort behavior patterns. SaaS companies in California deploy these tools to automate upsell timing based on feature adoption velocity.
- Customer Segmentation:Clustering algorithms group subscribers by behavioral similarity for targeted retention campaigns. Media companies in the United Kingdom apply this to reduce voluntary churn among high-lifetime-value viewer cohorts.
- Usage Analytics:Event-stream processing quantifies feature engagement and consumption patterns. E-learning platforms in Australia leverage this data to identify at-risk learners before subscription renewal windows.
- Pricing Strategy:Conjoint analysis and willingness-to-pay modeling inform packaging decisions. Telecom providers in South Korea utilize these modules to optimize tier structures against competitive pressure.
Churn Prediction retains the largest revenue share, though Revenue Optimization is expanding most quickly as usage-based pricing proliferates.
Use Case:
Functional priority shifts with business maturity, with retention-focused applications dominating early-stage deployments.
- Customer Retention:Intervention workflows trigger at-risk alerts to customer success teams. SaaS companies in the United States prioritize this use case to protect net revenue retention metrics ahead of fundraising cycles.
- Sales Forecasting:Pipeline projections incorporate historical conversion rates and expansion probability. Financial services firms in Singapore apply these capabilities to subscription revenue planning under MAS disclosure requirements.
- Market Expansion:Cohort analysis identifies geographic or vertical segments with highest acquisition efficiency. E-learning platforms in India utilize this to prioritize emerging market entry against domestic saturation.
- Subscription Management:Lifecycle orchestration automates provisioning, billing, and renewal workflows. Telecom providers in Brazil deploy these tools to reduce operational overhead in high-volume prepaid-to-postpaid conversions.
- Fraud Detection:Anomaly identification flags payment instrument abuse and account sharing. Media companies in the United Kingdom implement these systems to combat credential stuffing attacks on streaming services.
Customer Retention commands the dominant deployment volume, while Fraud Detection is climbing the fastest as subscription abuse vectors multiply.
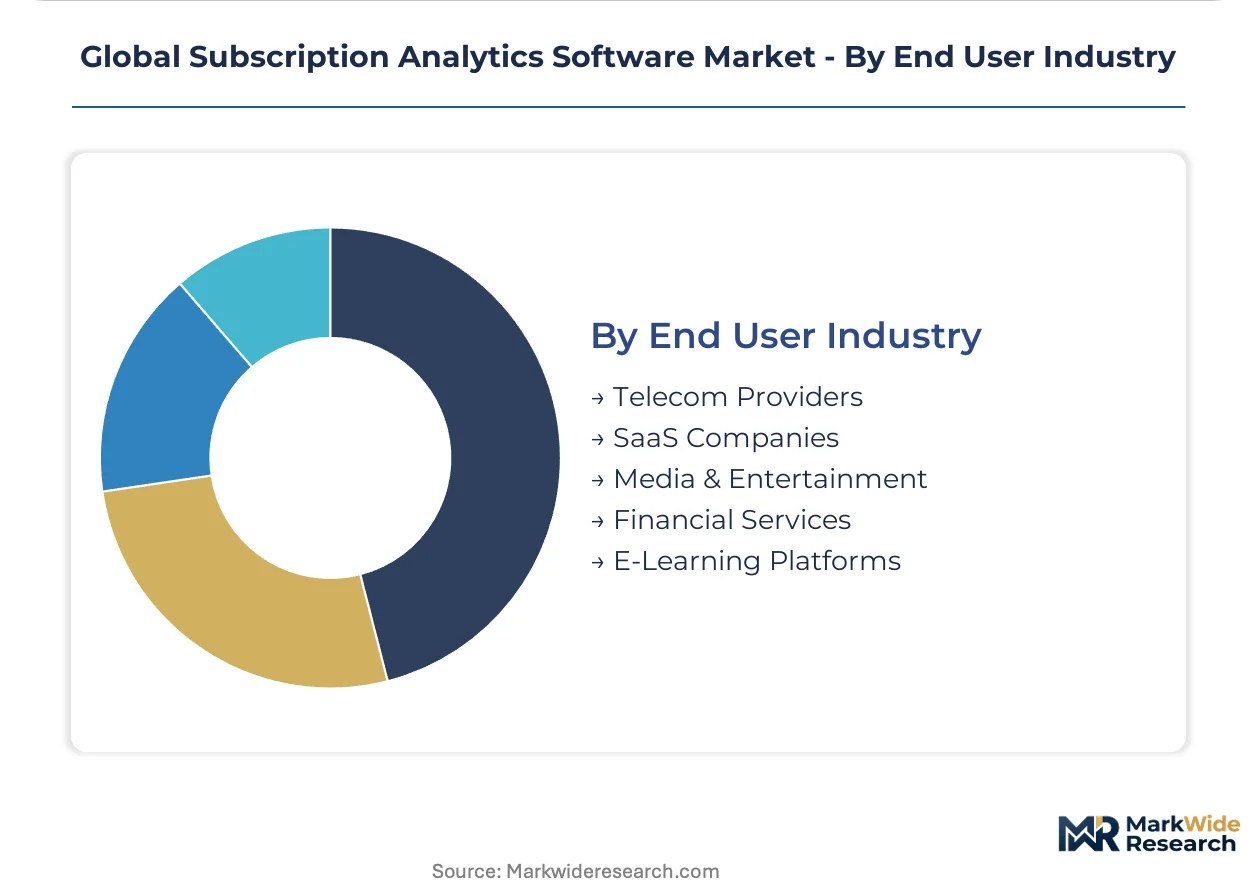
End User Industry:
Data complexity and event velocity create divergent technical requirements across vertical applications.
- SaaS Companies:Product-led growth models generate granular feature telemetry that feeds predictive models. Vendors in the United States represent the most mature demand segment with established data infrastructure.
- Financial Services:Regulatory scrutiny demands auditable model governance and human-in-the-loop overrides. Institutions in Germany and France face EU AI Act conformity assessments for automated credit and churn scoring.
- Telecom Providers:Massive subscriber bases and prepaid complexity require specialized ingestion pipelines. Operators in India manage event volumes exceeding ten million daily transactions across fragmented regional networks.
- Media & Entertainment:Seasonal content releases create spiky usage patterns that stress batch processing architectures. Streaming services in the United Kingdom optimize for peak concurrency during live sports broadcasts.
- E-Learning Platforms:Engagement metrics substitute for traditional usage signals in retention modeling. Providers in Australia and South Korea leverage completion rates and assessment performance to predict renewal likelihood.
SaaS Companies hold the dominant share, with Financial Services gaining share fastest as embedded finance expands subscription billing into regulated products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States operators prioritize real-time inference speed and embedded machine learning workflows. European deployments emphasize algorithmic transparency and data residency compliance under the EU AI Act and GDPR.
United States
Enterprise SaaS vendors in California and New York drive demand for churn prediction modules with sub-100-millisecond latency. The CCPA and emerging state privacy frameworks create compliance fragmentation that elevates implementation complexity. Seattle and San Francisco host the densest concentrations of Series C software companies piloting usage-based pricing analytics.
Germany
BaFin-regulated financial institutions require auditable decision trails for automated churn scoring systems. The EU AI Act mandates conformity assessments for high-risk algorithmic applications before production deployment. Berlin and Munich clusters concentrate vendors rebuilding model governance workflows to satisfy KBA interpretive guidance.
Netherlands
Amsterdam's scale-up density generates concentrated procurement of GDPR-compliant analytics infrastructure with processor agreement standards. The Dutch Data Protection Authority enforces strict data localization requirements for cross-border telemetry processing. Randstad-region SaaS operators lead European adoption of hosted single-tenant deployments.
India
The PLI scheme for software exports creates cost arbitrage for analytics vendors establishing development centers in Bangalore and Hyderabad. TRAI data localization rules for telecom providers drive hybrid deployment architectures balancing GPU access with regulatory compliance. Mumbai financial services firms represent the fastest-growing demand segment for revenue recognition automation.
United Kingdom
Media streaming services in London optimize analytics architectures for peak concurrency during live sports broadcasts. The Information Commissioner's Office applies GDPR Article 22 provisions that mandate human-in-the-loop overrides for automated retention decisions. Manchester and Edinburgh clusters host specialized vendors serving e-learning platforms with engagement-based renewal prediction.
Global Subscription Analytics Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on pricing transparency and vertical depth. The upper tier commands premium positioning through native billing workflow integration and enterprise-grade compliance tooling. Mid-market specialists differentiate via embedded analytics and cohort analysis efficiency. Competitive moves concentrate on strategic partnerships with payment processors and geographic expansion into GDPR-aligned European markets.
Within the integrated platform tier, Zuora and Chargebee exemplify contrasting approaches to market positioning. Zuora anchors enterprise-grade deployments with deep billing system integration. Chargebee occupies a position among mid-market SaaS vendors leveraging embedded analytics for platform stickiness. ChartMogul represents the transparency-focused specialist archetype, attracting European scale-ups seeking cost-efficient cohort analysis without enterprise complexity.
| Leading Market Players |
|---|
| Chargebee |
| Maxio |
| ChartMogul |
| Baremetrics |
| ProfitWell |
| Recurly |
| Zuora |
| RevenueCat |
| Fincome |
| Others |
Supply & Pricing Matrix
Event-stream processing infrastructure is displacing batch-based analytics architectures, simultaneously shifting supply geography toward cloud hyperscaler regions and compressing pricing power for legacy on-premise vendors. This substitution dynamic forces established players to absorb data engineering talent premiums while consumption-based pricing models erode seat-license revenue pools.
Pricing Analysis
Contract structures stratify across annual subscriptions, usage-based consumption tiers, and project-based professional services engagements. Three-tier pricing separates enterprise-grade churn prediction with dedicated model governance from mid-market SaaS bundles and entry-level cohort visualization tools. Price differentiation hinges on integration complexity with billing workflows and SOC 2 Type II certification status. Pricing pressure stems from open-source feature stores and embedded ML modules that commoditize standalone predictive analytics. Mid-market SaaS vendors in the United States exhibit highest price sensitivity, while BaFin-regulated German financial institutions accept premium positioning for auditable decision trails.
Supply Chain Analysis
The United States and Ireland anchor cloud infrastructure supply for North American and European deployments, while India feeds development engineering through Bangalore and Hyderabad centers. Raw material dependencies center on GPU compute capacity from NVIDIA and AMD, Apache Kafka streaming infrastructure, and Snowflake or Databricks data warehousing. Supply chain risk concentrates in single-source vulnerability for specialized ML inference hardware subject to export control restrictions. Distribution runs through direct enterprise sales teams, hyperscaler marketplace listings, and embedded partnerships with billing platforms like Stripe and PayPal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Revenue recognition automation services are expanding faster than core analytics licensing, creating attach-rate opportunities for vendors bundling ASC 606 and IFRS 15 compliance workflows with predictive modules.
For Market Incumbents: Consolidate engineering resources around real-time feature pipelines to defend against embedded ML displacement from billing platforms. Acquire specialized GDPR compliance tooling to satisfy EU AI Act conformity assessments before German and French regulators tighten interpretive guidance. Prioritize backward integration into data residency infrastructure to capture margin pools shifting toward hosted single-tenant deployments. For New Entrants and Emerging Players: ISO 27001 and SOC 2 fast-track certification opens procurement doors at Series C SaaS companies in California and New York. Target Netherlands scale-ups seeking processor-agreement-compliant analytics without enterprise complexity. Penetrate through usage-based pricing pilots that link contract value directly to measured revenue retention impact, compressing sales cycles against incumbent annual commitments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed billing platforms seeking analytics adjacencies to deepen platform stickiness. Five-to-ten-year viability favors vendors with native integration into high-velocity payment telemetry rather than standalone BI tools requiring manual data exports. Watch for inflection signals in EU AI Act enforcement intensity from Germany's KBA and France's CNIL as predictors of compliance-tooling demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding into Stripe and PayPal billing stacks reduces customer acquisition friction for mid-market SaaS vendors. |
| Geographic Expansion | GDPR-aligned European presence captures Amsterdam scale-up demand for residency-compliant hosted deployments. |
| Acquisition of Specialist Firm | Revenue recognition automation targets ASC 606 and IFRS 15 compliance workflows adjacent to core analytics. |
| Strategic Partnership | Banking-as-a-Service alliances with embedded finance providers feed granular payment telemetry into retention models. |
| Product Launch | Explainable ML modules satisfy EU AI Act algorithmic transparency mandates for automated churn scoring in financial services. |
Research Methodology
Desk research of SEC filings from publicly traded SaaS vendors, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with CTOs, customer success operations leads, and data engineering directors at subscription-native enterprises. Primary fieldwork validated deployment architecture preferences and procurement timelines against secondary data from billing platform partner ecosystems. Bottom-up sizing of vendor-reported customer counts and average contract values triangulated with top-down estimates from aggregate enterprise software spending.
Variance decomposition across deployment models, organization size tiers, and vertical industry segments shaped the analytical framework over the projection horizon. Modeled dimensions encompassed cloud versus hybrid infrastructure, SaaS versus financial services end-use, and real-time versus batch processing latency requirements. CAGRs were derived from logistic adoption curves fitted to historical billing event velocity growth and regulatory compliance spending patterns. Forecast inputs incorporated TRAI data localization mandates and EU AI Act risk classification timelines.
Decision-makers should treat outputs as directional under assumptions of sustained cloud infrastructure cost declines and stable GDPR enforcement intensity; material deviation in GPU supply constraints or algorithmic accountability standards would warrant model refresh. Recalibration cycles align with material shifts in EU AI Act interpretive guidance and embedded finance penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Personal Analytics Market
Analytics
SME Big Data Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
France Contact Center Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Global Data Analysis Software Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Audio and Video Analytics Software Market
Analytics
Europe Crowd Analytics Market
Analytics
Data Analytics Outsourcing Market
Analytics
Mobile Business Intelligence Market
Analytics
Active Data Warehousing Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Israel Geospatial Analytics Market
Analytics
APAC Operational Intelligence Market
Analytics
Cyprus ICT Market