
 Contact Center Intelligence Market | 2026-2036
Contact Center Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Center Intelligence Market Intelligence
Buyer concentration among Fortune 500 enterprises is hardening as telecommunications and financial services providers consolidate vendor relationships around integrated platforms. Amazon Web Services leverages its cloud infrastructure dominance to anchor multi-channel deployments across North America. Microsoft competes through embedded AI capabilities within productivity suites that reduce agent training overhead. Oracle sustains its position through deep CRM integration that unifies customer data across touchpoints.
Contact center intelligence encompasses AI-driven systems that analyze voice, text, and behavioral data to automate routing, coach agents, and predict customer intent using natural language processing engines processing sub-200-millisecond response thresholds. These platforms serve commercial and government operations seeking to reduce average handle time while improving first-contact resolution rates. Speech analytics and AI-powered solutions represent the fastest-expanding technology categories as real-time sentiment detection becomes standard in premium deployments. Cloud-based delivery dominates new implementations, though hybrid architectures persist in regulated sectors where data residency requirements constrain full migration.
The EU AI Act and GDPR impose algorithmic transparency mandates on automated customer interactions, while the FCC enforces telemarketing consent rules that shape outbound campaign architectures in the United States. HIPAA constrains health insurance contact centers from deploying certain predictive models without audit trails, creating compliance-driven demand for explainable AI modules. Stakeholders must evaluate whether their current vendor roadmaps address emerging biometric consent requirements and cross-border data localization standards before committing to long-term platform contracts.
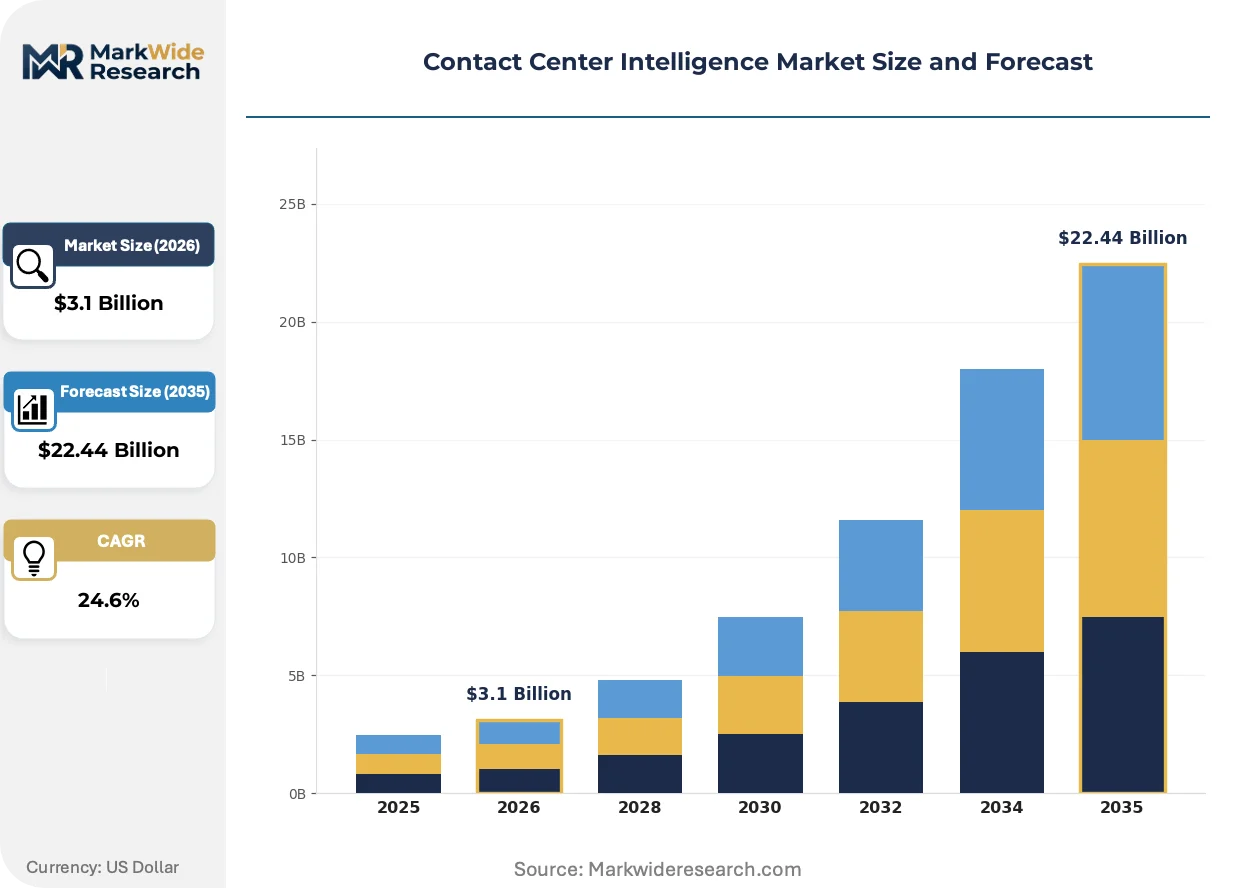
Market Dynamics
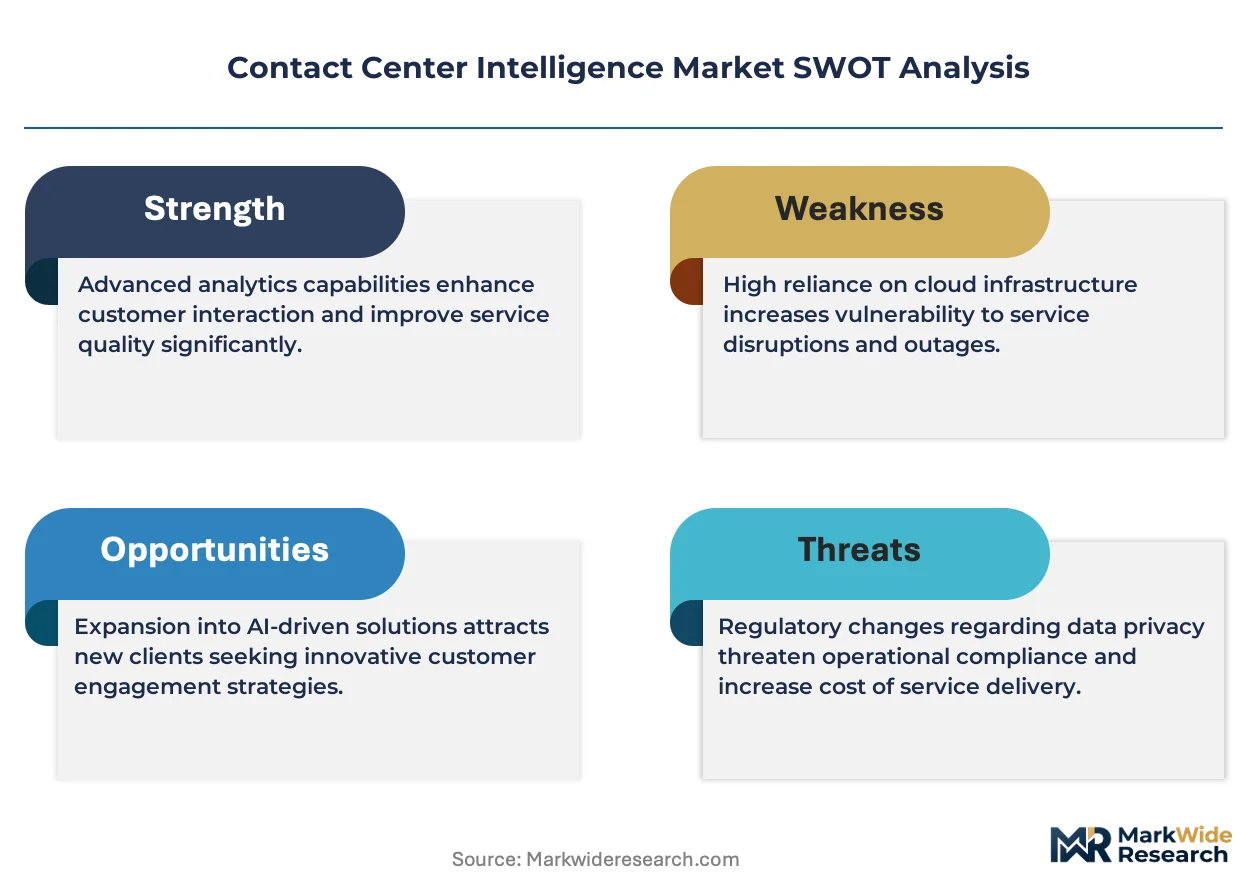
The Contact Center Intelligence Market faces intensifying pressure from the EU AI Act's algorithmic transparency mandates, which force vendors to rearchitect black-box sentiment models into auditable decision trees. This regulatory compression coincides with Fortune 500 buyers consolidating vendor relationships around cloud-native platforms that unify voice, chat, and behavioral analytics.
Growth Catalysts
- EU AI Act Compliance:The EU AI Act's risk-classification framework for automated decision systems is accelerating procurement of explainable AI modules among European banking and insurance contact centers. Vendors offering built-in audit trails capture premium positioning.
- Real-Time Sentiment Detection:Sub-200-millisecond NLP response thresholds are overtaking batch analytics as the standard for agent-assist deployments. Financial services providers in the United States prioritize live emotion scoring to reduce escalation rates.
- Cloud Migration:Hybrid architectures in regulated sectors are yielding to full cloud deployments as data residency solutions mature. Telecommunications operators across Germany, France, and the United Kingdom lead this infrastructure transition.
Market Restraints
- GPU Compute Costs:Training and inference workloads for large language models driving contact center automation depend on concentrated NVIDIA supply chains, creating input cost volatility that compresses vendor margins.
- Biometric Consent Fragmentation:The FCC's telemarketing consent rules and emerging state-level voiceprint regulations in the United States impose conflicting technical requirements that fragment product roadmaps.
- Legacy CRM Integration:Decades-old on-premise customer databases in healthcare and government sectors resist API-based connectivity, extending implementation timelines and inflating professional services costs.
Strategic Opportunities
- Explainable AI Modules:HIPAA-constrained health insurance contact centers require interpretable predictive models with full audit trails. Vendors delivering SHAP-value visualization and decision-path documentation capture this compliance-driven white space.
- Agent Coaching Automation:Real-time performance guidance systems are converging with workforce management platforms to reduce supervisor headcount. This technology pairing targets mid-market contact centers in India and the Philippines.
- Cross-Border Data Localization:GDPR Article 44 transfer mechanisms and emerging national data sovereignty laws create demand for region-specific cloud instances. Vendors operating EU-only or country-dedicated infrastructure gain procurement preference.
Industry Challenges
- Conversational AI Talent Scarcity:The intersection of linguistics, machine learning engineering, and domain expertise in financial services or healthcare remains difficult to staff. Vendors compete for scarce PhD-level NLP specialists capable of tuning transformer models for low-latency production environments.
- Multi-Modal Integration Complexity:Unifying voice biometrics, chat transcripts, and screen interaction data into coherent customer journey maps requires expensive data engineering pipelines. Implementation failure rates run high when buyers underestimate schema normalization effort.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Center Intelligence Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $22.44 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Speech Analytics, Workforce Optimization, Customer Engagement, AI-Powered Solutions Application: Omni-channel Support, Call Routing, Performance Monitoring, Quality Management End User: Large Enterprises, SMEs, Government Agencies, NGOs Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions |
| Companies Covered | IBM Corporation, Oracle, Amazon Web Services, Zendesk, SAP SE, TENEO.AI, Microsoft, Talkdesk, Avaya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Center Intelligence Market Strategic Shifts & Innovations
Transformer-based architectures are compressing response latencies below human perception thresholds while regulatory frameworks force architectural transparency. These dual pressures are reshaping vendor R&D priorities and buyer evaluation criteria simultaneously.
Real-time speech analytics is overtaking post-call transcription as the dominant intelligence layer in premium contact center deployments. These systems process acoustic and lexical signals simultaneously to flag escalation risks during live conversations. Banking contact centers in the United States deploy these capabilities to intercept compliance violations before call termination. The structural consequence is collapsing demand for quality assurance staff performing retrospective call reviews.
The EU AI Act's high-risk system classification for credit-scoring and insurance underwriting algorithms imposes conformity assessment obligations on automated customer interaction systems. Vendors must now maintain technical documentation, human oversight protocols, and accuracy metrics subject to market surveillance authority audit. European financial services providers are responding by demanding model cards and bias testing reports as standard procurement deliverables.
Subscription-based platform pricing is displacing perpetual license models as buyers prioritize operational flexibility over capital ownership. Mid-market contact center operators in the United Kingdom and Germany favor consumption-aligned contracts that scale with seasonal volume fluctuations. This shift compresses vendor cash conversion cycles while accelerating competitive displacement of legacy on-premise installations.
Contact Center Intelligence Market Segmentation
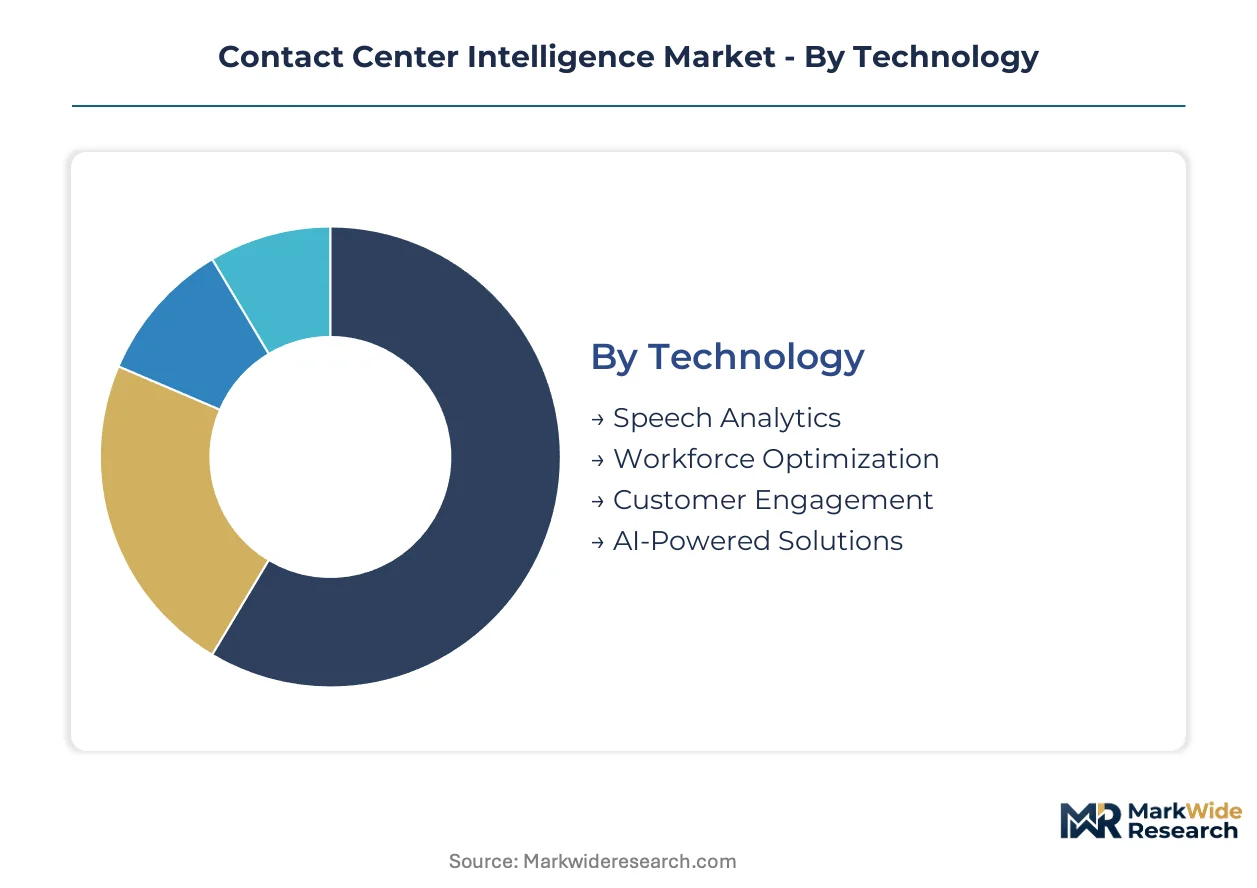
Contact center intelligence platforms fragment across four distinct axes that determine buyer procurement criteria and vendor positioning strategies. Technology maturity, regulatory constraints, operational scale, and infrastructure legacy collectively shape segment-level competitive dynamics and pricing architectures.
Technology:
Buyer sophistication and compliance exposure separate procurement patterns across technology categories, with financial services and healthcare providers driving premium-tier demand.
- Speech Analytics:Real-time acoustic and lexical signal processing enables live escalation risk detection during customer conversations. Banking contact centers in the United States deploy these systems to intercept compliance violations before call termination, collapsing retrospective quality assurance staffing requirements.
- AI-Powered Solutions:Transformer-based natural language processing engines achieve sub-200-millisecond response thresholds for agent-assist applications. European insurance carriers prioritize these deployments to satisfy EU AI Act algorithmic transparency mandates while reducing average handle time.
- Workforce Optimization:Scheduling and forecasting modules integrate with real-time adherence tracking to reduce supervisor headcount.
- Customer Engagement:Proactive outreach and journey orchestration tools unify inbound and outbound interaction management.
Volume sits with Speech Analytics; growth tilts toward AI-Powered Solutions.
Application:
Functional deployment determines integration complexity and professional services intensity, with omni-channel architectures commanding the longest implementation timelines.
- Omni-channel Support:Unified voice, chat, email, and social media routing requires extensive API connectivity to legacy CRM systems. Fortune 500 telecommunications operators consolidate vendor relationships around these integrated platforms to reduce point-solution fragmentation.
- Call Routing:Intent-based automatic call distribution using predictive models directs inquiries to optimal agent skill sets. Cloud-native deployments dominate new implementations as data residency solutions mature for regulated sectors.
- Performance Monitoring:Real-time dashboards and scorecards track agent productivity metrics against service level agreements.
- Quality Management:Automated evaluation frameworks replace manual call sampling with comprehensive interaction assessment.
Call Routing captures the largest installed base; omni-channel support climbs the fastest.
End User:
Organizational scale dictates deployment architecture preferences and pricing model negotiations, with procurement sophistication varying sharply across buyer types.
- Large Enterprises:Fortune 500 contact center operators modernize legacy infrastructure through multi-year platform contracts with integrated professional services. These buyers demand explainable AI modules, full audit trails, and region-specific cloud instances to satisfy cross-border data localization requirements.
- Government Agencies:Federal and state-level operations face stringent security certification requirements and hybrid architecture constraints due to classified data handling protocols.
- SMEs:Mid-market operators favor consumption-aligned subscription contracts that scale with seasonal volume fluctuations.
- NGOs:Non-profit contact centers prioritize cost-minimized solutions with grant-funded implementation support.
Large Enterprises dominate current procurement volume; SMEs represent the steepest expansion trajectory.
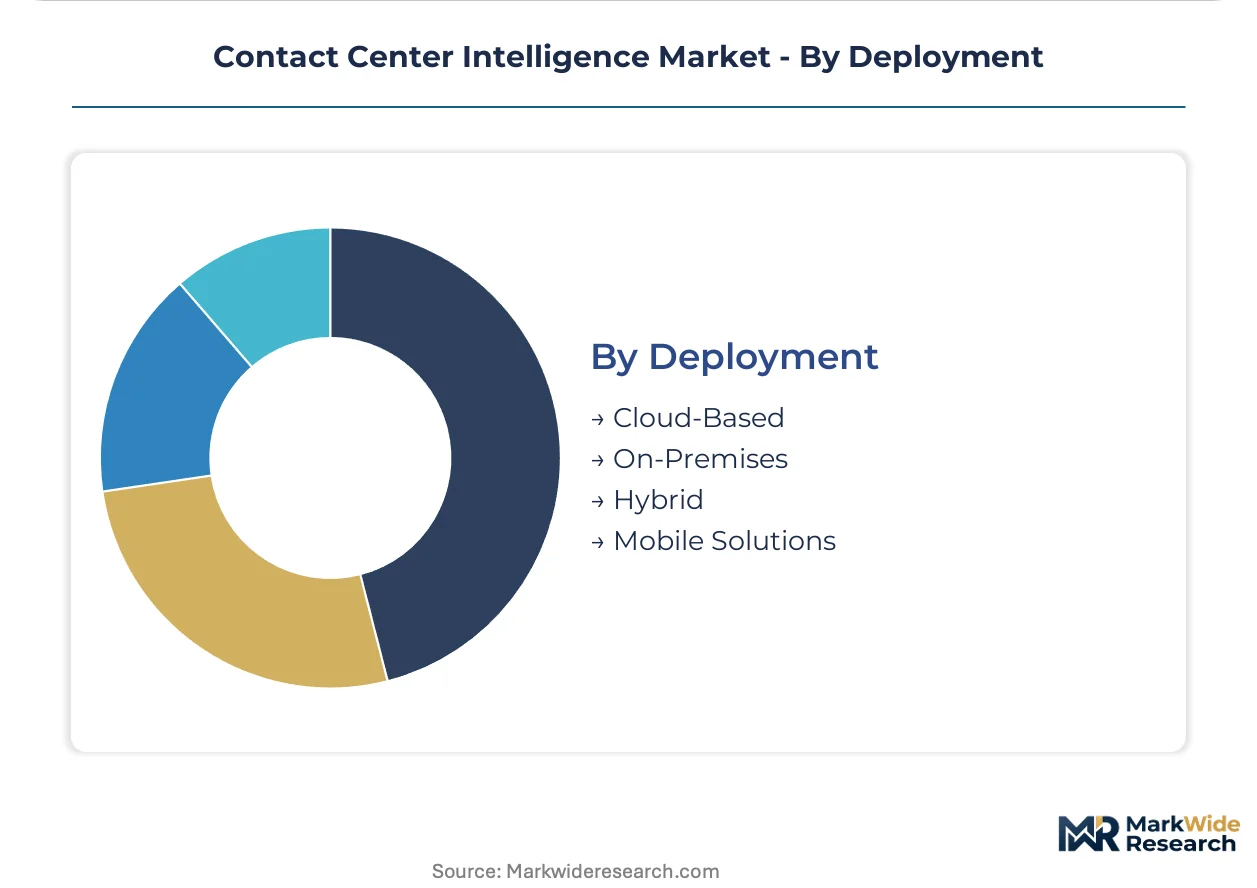
Deployment:
Infrastructure location determines compliance scope, latency performance, and total cost of ownership calculations across buyer evaluations.
- Cloud-Based:Fully managed SaaS delivery eliminates capital expenditure and accelerates feature deployment cycles. Telecommunications operators across Germany, France, and the United Kingdom lead this infrastructure transition as GDPR Article 44 transfer mechanisms mature.
- Hybrid:Split architectures preserve sensitive data on-premise while leveraging cloud scalability for non-regulated workloads. HIPAA-constrained health insurance contact centers maintain this posture for biometric voiceprint storage.
- On-Premises:Self-managed installations persist in government and defense sectors with air-gapped security requirements.
- Mobile Solutions:Agent-facing smartphone applications extend platform access to remote and field-based customer service operations.
Cloud-Based deployments command the largest share of new implementations; Hybrid architectures retain critical importance in regulated verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 contact center operators in the United States drive the largest share of platform procurement, while European banking and insurance carriers accelerate adoption under tightening algorithmic transparency mandates. Cloud migration trajectories diverge sharply across jurisdictions based on data localization requirements and sector-specific compliance exposure.
United States
Financial services providers in New York and Chicago deploy real-time sentiment detection to reduce escalation rates and intercept compliance violations during live conversations. The FCC enforces telemarketing consent rules that shape outbound campaign architectures and biometric voiceprint collection protocols. Dallas-Fort Worth anchors a major cluster of telecommunications operators modernizing legacy infrastructure through multi-channel cloud deployments.
Germany
Banking and insurance contact centers in Frankfurt and Munich prioritize explainable AI modules to satisfy EU AI Act conformity assessment obligations for high-risk automated decision systems. The national data regulator enforces GDPR Article 44 transfer mechanism compliance, driving demand for EU-dedicated cloud instances. Berlin hosts a concentration of mid-market operators transitioning from hybrid to full cloud architectures as data residency solutions mature.
United Kingdom
Telecommunications providers in London and Manchester consolidate vendor relationships around integrated omni-channel platforms to reduce point-solution fragmentation. The Financial Conduct Authority scrutinizes algorithmic transparency in credit-scoring and insurance underwriting applications. Edinburgh anchors a growing cluster of health insurance contact centers constrained by HIPAA-equivalent data handling protocols requiring full audit trails.
France
Insurance carriers in Paris deploy transformer-based NLP engines to achieve sub-200-millisecond response thresholds for agent-assist applications while maintaining auditable decision paths. CNIL enforces biometric consent requirements that complicate voiceprint authentication rollouts. Lyon hosts specialized contact center operators serving European banking clients with strict cross-border data localization demands.
India
Mid-market business process outsourcing operators in Bengaluru and Hyderabad favor consumption-aligned subscription contracts that scale with seasonal volume fluctuations. TRAI regulations shape telecommunications infrastructure investments affecting cloud connectivity reliability. Mumbai anchors the largest concentration of agent coaching automation deployments targeting supervisor headcount reduction in workforce management platforms.
Contact Center Intelligence Market Key Industry Players
United States-based technology conglomerates anchor one tier; European enterprise software specialists hold differentiated positions through regulatory compliance depth. Market structure concentrates around cloud-native platform providers with embedded AI capabilities, while point-solution vendors face consolidation pressure from integrated suite offerings. Three archetypes dominate: hyperscale cloud infrastructure operators, CRM-embedded intelligence providers, and vertical-specific compliance specialists. Competitive dynamics center on strategic partnerships with telecommunications carriers and geographic expansion through region-specific cloud instance deployments.
Within the hyperscale tier, Amazon Web Services and Microsoft exemplify infrastructure-anchored platform strategies, while Oracle occupies a position unifying customer data across touchpoints through deep CRM integration. IBM Corporation represents the compliance-specialist archetype with emphasis on auditable AI modules for regulated sectors. These companies illustrate how vendor positioning increasingly depends on explainable architecture roadmaps and data residency capabilities rather than raw NLP performance metrics.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle |
| Amazon Web Services |
| Zendesk |
| SAP SE |
| TENEO.AI |
| Microsoft |
| Talkdesk |
| Avaya |
| Others |
Cost & Logistics Intelligence
PhD-level NLP specialists concentrated in Bengaluru and San Francisco command compensation premiums that widen spreads between premium-tier explainable AI modules and economy-tier workforce optimization tools. Labor-cost differentials between North American engineering hubs and Indian deployment centers translate directly into three-tier pricing stratification across subscription contracts.
Pricing Analysis
Volume concentrates in mid-market SaaS subscriptions while margins accrue to premium explainable AI tiers with built-in EU AI Act compliance documentation. Price differentiation separates audit-trail-enabled deployments for European banking clients from stripped-down agent-coaching tools targeting Philippine BPO operators. Pricing pressure stems from NVIDIA GPU supply constraints inflating inference costs for transformer-based sentiment models. SME buyers in India exhibit highest price sensitivity; Fortune 500 operators in the United States prioritize compliance bundling over unit cost.
Supply Chain Analysis
EU AI Act local-content requirements for algorithmic transparency documentation are reshaping vendor sourcing toward European data residency infrastructure. GPU hardware concentrates in Taiwan, South Korea, and the United States; cloud compute capacity clusters in Ireland, Germany, and Virginia. Transformer model training draws from concentrated NVIDIA supply chains creating single-source vulnerability for real-time NLP inference. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales teams serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance mandates are compressing vendor margins and forcing consolidation among point-solution providers lacking explainable AI roadmaps. Market structure favors integrated platform operators with pre-built audit capabilities.
For Market Incumbents: Extend explainable AI module portfolios to capture EU banking procurement requirements before regulatory deadlines eliminate black-box competitors. Anchor multi-year contracts through region-specific cloud instances satisfying GDPR Article 44 transfer constraints. GPU supply concentration threatens margin stability; negotiate long-term capacity reservations with hyperscale infrastructure partners. For New Entrants and Emerging Players: HIPAA-constrained health insurance contact centers represent an underserved buyer archetype requiring interpretable predictive models with SHAP-value visualization. White-space exists in mid-market agent coaching automation converging with workforce management platforms. Go-to-market through channel partnerships with existing HR tech vendors reduces direct sales overhead. For Investors and Strategic Acquirers: The window for entry favors vertical-specific compliance specialists with pre-built EU AI Act documentation and established healthcare audit trail capabilities. Long-term viability rests on explainable architecture roadmaps rather than raw NLP performance benchmarks. Watch for inflection when European banking RFPs mandate model cards and bias testing reports as standard deliverables.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Module Development | EU AI Act conformity assessments require auditable decision trees for high-risk automated customer interactions. |
| Region-Specific Cloud Instance Deployment | GDPR Article 44 transfer mechanisms drive procurement preference for EU-dedicated infrastructure among Frankfurt banking clients. |
| Agent Coaching Automation Platform Integration | Workforce management convergence targets supervisor headcount reduction in Bengaluru and Hyderabad BPO operations. |
| Biometric Consent Compliance Layer | CNIL and FCC voiceprint regulations fragment product roadmaps; unified consent management captures cross-border deployments. |
| Legacy CRM API Connectivity Investment | On-premise healthcare databases resist integration; professional services revenue accrues to vendors with pre-built connectors. |
Research Approach
Multi-period observation of vendor pricing disclosures, regulatory filing timelines, and cloud infrastructure capex patterns anchored the trend analysis, supplemented by interviews with contact center operations directors, AI procurement officers at Fortune 500 enterprises, compliance leads at European insurance carriers, and platform engineering heads at hyperscale providers. Secondary validation drew from SEC 10-K filings, EU AI Act implementation guidance, GDPR enforcement actions, FCC consent rule dockets, and hyperscaler data center expansion announcements. Bottom-up deployment estimates triangulated against top-down addressable market calculations across technology and application segments.
Input-output matrices modeled relationships between GPU supply constraints, labor-cost differentials, and pricing-tier spreads across the projection horizon. Segmentation dimensions included technology category, deployment architecture, organization scale, and regional regulatory cluster. CAGRs derived from curve-fitting observed adoption velocities against infrastructure maturity indicators. Forecast inputs incorporated transformer model latency benchmarks, data residency solution availability, and biometric consent regulatory fragmentation indices.
Revisions become necessary when EU AI Act enforcement intensity exceeds modeled scenarios, NVIDIA supply chain disruptions extend beyond current contract coverage periods, or major economies impose data sovereignty requirements conflicting with existing cloud architectures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Geospatial Analytics Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
AI Performance Marketing Market
Analytics
Identity Analytics Market
Analytics
Global Performance Analytics Market
Analytics
Asia-Pacific Emotion Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Global Visual Analytics Market
Analytics
Operational Intelligence Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Global Systems of Insight Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Middle East Geospatial Analytics Market
Analytics
Legal Analytics Market