
 Workforce Analytics Market | 2026-2036
Workforce Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Workforce Analytics Market Analysis
EU CSRD disclosure mandates for workforce metrics is shifting procurement priorities toward auditable analytics platforms. SAP SE leverages its embedded HCM footprint to sustain renewal rates among European multinationals. Oracle Corporation dominates database-to-analytics pipelines for public-sector workforce modernization. Visier, Inc. specializes in standalone people analytics, competing on depth of pre-built workforce KPI libraries.
Workforce analytics comprises software systems that ingest HR, operational, and external labor market data to model staffing scenarios, attrition probability, and productivity variance using statistical inference and machine learning classifiers. These platforms serve industrial and commercial purposes by translating human capital signals into capital-expenditure-grade forecasts for boards and CFOs. Cloud-based deployment leads segment adoption as enterprises retire on-premise HR systems, while AI-powered analytics captures the fastest expansion due to natural language interfaces that democratize query access for line managers. Talent management anchors current revenue pools, though workforce planning is deepening margin contribution as scenario-modeling complexity rises.
US EEOC algorithmic fairness guidance and EU GDPR automated decision-making rules are tightening vendor accountability for biased model outputs, directly shaping product roadmaps and liability structures. ISO 30414 human capital reporting standards are creating cross-border certification demand that opens market access for compliant platforms. Stakeholders must monitor regulatory divergence between US federal agency guidance and EU binding rules when selecting architecture and vendor geography.
Market Dynamics
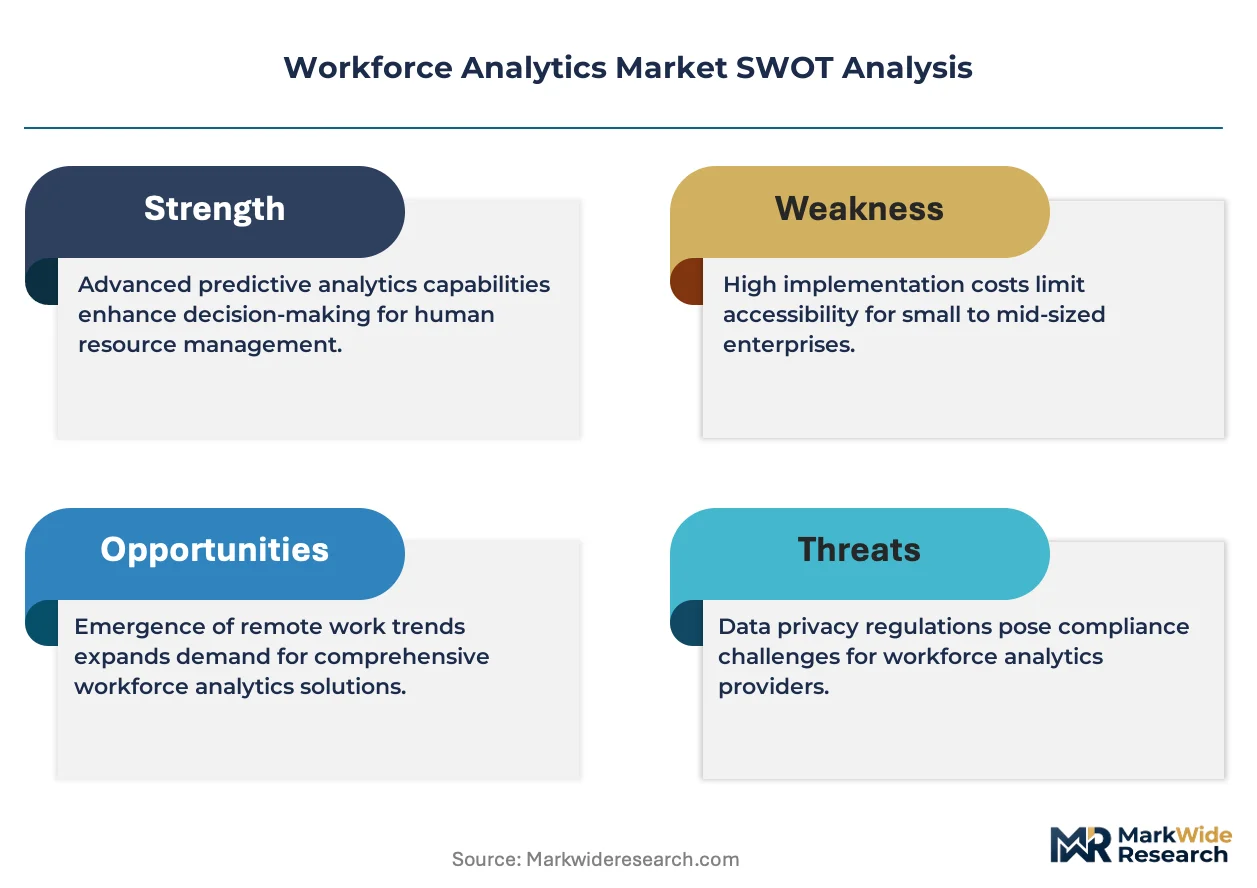
Algorithmic accountability mandates from the EU AI Act and US EEOC are forcing vendors to reengineer model architectures for explainability, transforming procurement criteria from feature depth to audit trail completeness.
Growth Catalysts
- EU CSRD workforce disclosure mandates:Large employers must report granular human capital metrics, creating mandatory demand for auditable analytics infrastructure.
- Cloud HCM platform consolidation:Enterprises retiring on-premise Workday and SAP installations are triggering analytics module attach-rate expansion.
- Natural language query interfaces:Line managers without statistical training now access predictive models, democratizing workforce intelligence consumption.
Market Restraints
- GDPR automated decision-making constraints:Article 22 restrictions on solely automated employment decisions limit deployment of black-box attrition predictors in EU jurisdictions.
- Data engineering talent scarcity:Shortage of HR data scientists capable of integrating fragmented payroll, engagement, and external labor market sources inflates implementation timelines.
- Legacy system data fragmentation:Decades of siloed HRIS investments in multinational corporations resist API-based unification without expensive middleware layers.
Strategic Opportunities
- ISO 30414 certification services:Human capital reporting standardization opens adjacent revenue streams for audit-ready analytics platforms seeking differentiation.
- Public-sector workforce modernization:Government agencies replacing civil service classification systems with skills-based architectures require scenario-modeling capabilities.
- AI-powered succession planning:Convergence of organizational network analysis with generative role-matching creates new module categories for executive talent pipelines.
Industry Challenges
- Algorithmic bias remediation:Proving demographic parity across protected class intersections demands continuous model retraining and expensive fairness auditing.
- Cross-border data residency conflicts:Workforce analytics spanning EU, US, and APAC operations face irreconcilable requirements for data localization versus centralized modeling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workforce Analytics Market |
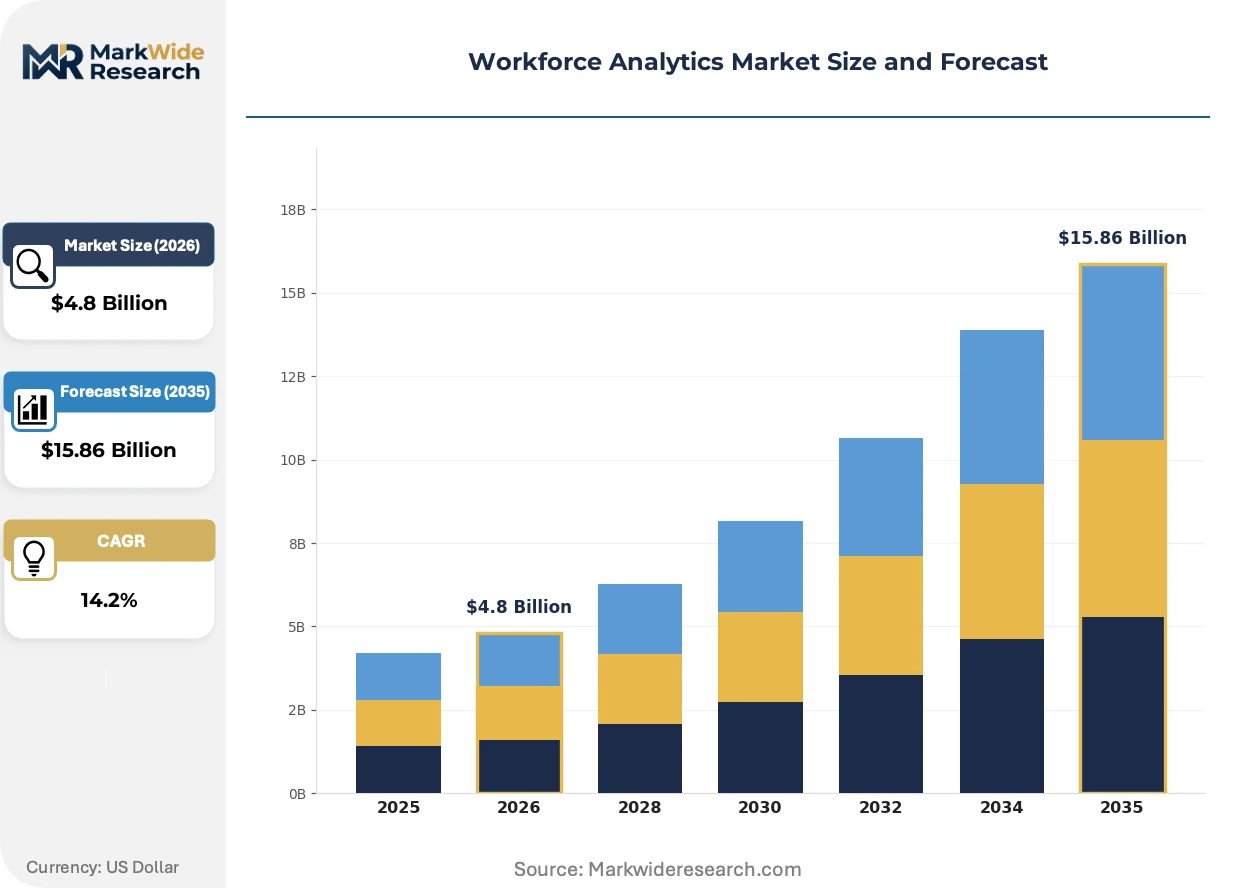
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Talent Management, Performance Optimization, Employee Engagement, Workforce Planning Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing End User: Enterprises, SMEs, Consulting Firms, Educational Institutions Technology: AI-Powered Analytics, Predictive Analytics, Real-Time Monitoring, Machine Learning |
| Companies Covered | International Business Machines Corporation, Ultimate Kronos Group, SAP SE, Ceridian HCM, Inc., Visier, Inc., Oracle Corporation, Automatic Data Processing, Inc., Cornerstone OnDemand, Inc., Workday, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workforce Analytics Market Emerging Trajectories
Workforce analytics platforms are absorbing adjacent capabilities from financial planning and operational intelligence systems, dissolving historical boundaries between HR technology and enterprise performance management.
Graph neural networks for organizational network analysis are unifying previously separate engagement survey, email metadata, and project staffing data into unified relationship maps. Fortune 500 CHROs are deploying these tools to identify hidden influencers and collaboration bottlenecks. This unifying architecture is compressing the traditional 12-18 month organizational design consulting cycle into self-service scenario testing.
The EU AI Act's risk-based classification system is mandating human-in-the-loop overrides for high-stakes workforce decisions including terminations and compensation adjustments. Vendors must now maintain dual model versions: fully automated for US clients, intervention-gated for EU deployments. Financial services firms with dual EU-US footprints face the steepest compliance architecture costs.
Buyers are consolidating vendor relationships around integrated talent intelligence platforms rather than standalone people analytics point solutions. CHROs at North American manufacturers are terminating contracts with specialized attrition vendors in favor of embedded modules within their core HCM suites. This preference shift is squeezing standalone providers into niche workforce planning scenarios or forcing strategic exits.
Workforce Analytics Market Segmentation
Workforce analytics segmentation reveals how procurement priorities diverge between enterprises seeking embedded HCM modules and those demanding standalone depth. Buyers weigh integration friction against analytical sophistication when allocating budget across deployment architectures and application layers.
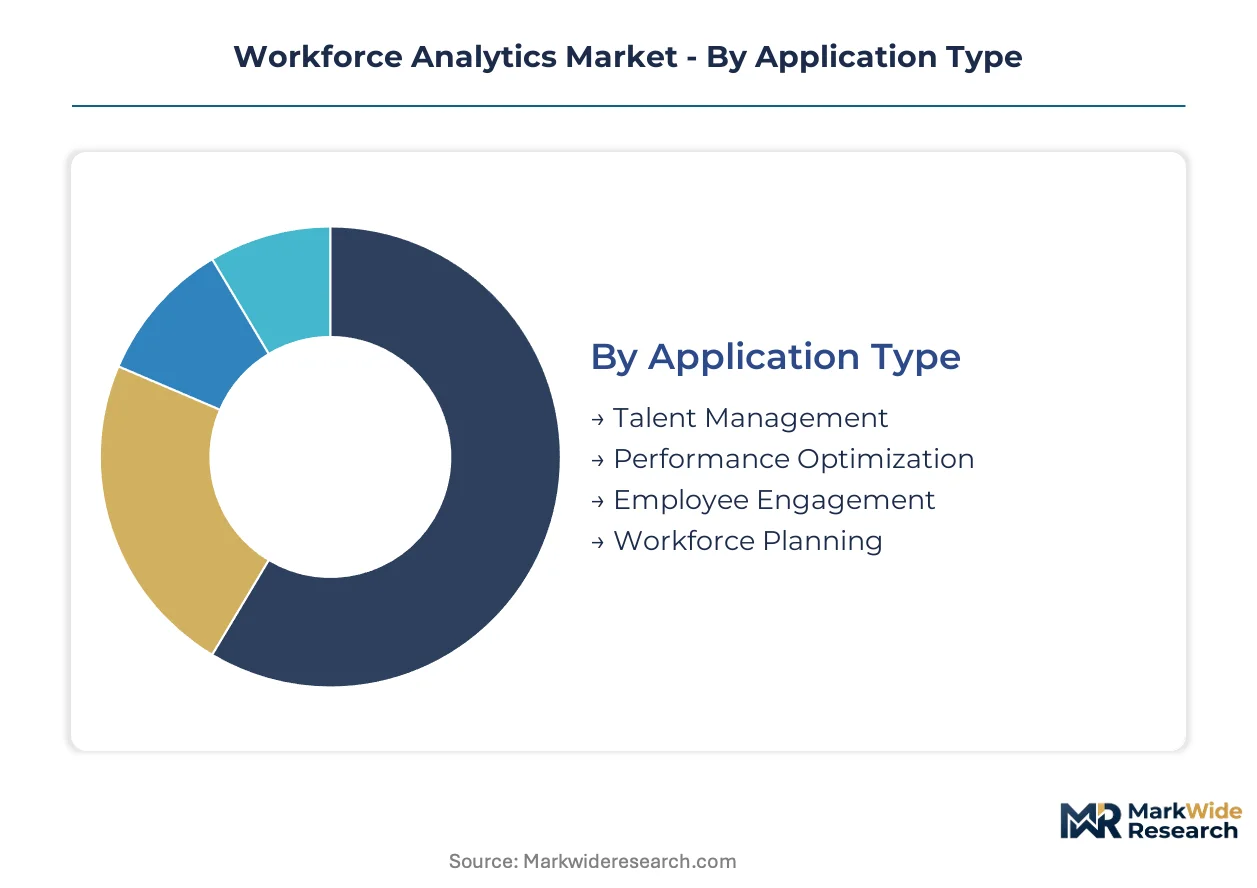
Application Type:
Integration depth varies sharply across use cases, with some applications functioning as embedded HCM features while others require specialized platforms.
- Workforce Planning:Scenario-modeling engines project headcount requirements against revenue forecasts and skills gaps. Financial services firms in the United States deploy these tools for capital-expenditure-grade staffing forecasts. Margin contribution deepens as Monte Carlo simulation complexity rises.
- Talent Management:Succession pipelines and competency mapping modules anchor current revenue pools. Large European multinationals under CSRD mandates prioritize auditable talent metrics for board disclosures. Embedded deployment dominates as Workday and SAP attach rates expand.
- Performance Optimization:Productivity variance analysis tools isolate high-performer behavioral patterns.
- Employee Engagement:Sentiment analysis platforms process pulse surveys and collaboration metadata.
Talent Management leads volumes today; Workforce Planning is gaining share fastest.
Deployment Model:
Cost tier stratification separates legacy on-premise estates from cloud-native architectures, with hybrid deployments capturing mid-market transition budgets.
- Cloud-Based:Multi-tenant SaaS platforms with API-first data ingestion dominate new procurement. US federal agencies retiring legacy HRIS systems drive public-sector modernization waves. Natural language interfaces democratize access for line managers without statistical training.
- Hybrid:Sensitive payroll data remains on-premise while analytics processing shifts to cloud infrastructure. German automotive manufacturers with works council agreements favor this architecture for co-determination compliance. Implementation timelines stretch due to dual-environment orchestration.
- On-Premise:Air-gapped installations persist in defense and intelligence sectors with classified workforce data.
- Edge Computing:Factory-floor analytics for shift optimization in manufacturing environments.
Cloud-Based deployment commands the largest installed base; Hybrid architectures are expanding most quickly among regulated industries.
End User:
Customer type determines feature depth requirements, with consulting firms acting as demand amplifiers rather than direct consumers.
- Enterprises:Fortune 500 CHROs consolidate around integrated talent intelligence platforms, terminating standalone point solutions. North American manufacturers favor embedded modules within core HCM suites over specialized attrition vendors. Procurement criteria now prioritize audit trail completeness over feature depth.
- SMEs:Mid-market buyers adopt pre-configured workforce KPI libraries from cloud-native specialists. UK professional services firms leverage out-of-box templates without dedicated HR data science teams. Price sensitivity limits customization scope.
- Consulting Firms:McKinsey and Deloitte deploy organizational network analysis for client transformation programs.
- Educational Institutions:Universities model faculty retirement waves and research staffing pipelines.
Enterprises dominate absolute spending; SMEs are expanding their share of new license growth.
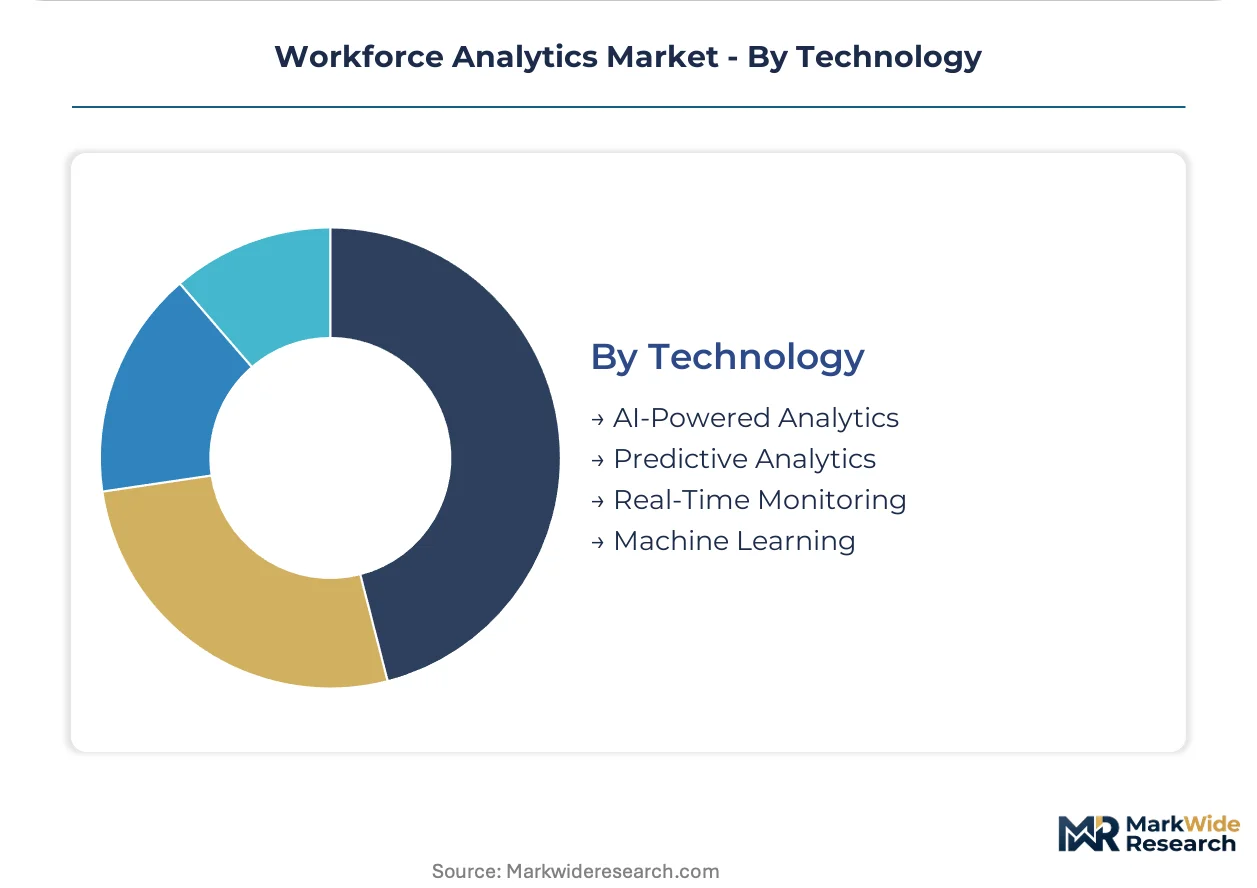
Technology:
Technology maturity separates production-grade machine learning from experimental AI interfaces, with regulatory divergence forcing architectural branching.
- AI-Powered Analytics:Generative interfaces translate natural language queries into statistical models without coding. EU AI Act mandates human-in-the-loop overrides for high-stakes decisions including terminations. Vendors maintain dual versions: fully automated for US clients, intervention-gated for EU deployments.
- Predictive Analytics:Attrition probability models and flight-risk scoring anchor proven use cases. GDPR Article 22 constraints on solely automated employment decisions limit black-box predictor deployment in EU jurisdictions. Model explainability requirements inflate engineering costs.
- Machine Learning:Supervised classifiers for skills taxonomy and role matching.
- Real-Time Monitoring:Streaming dashboards for contact center staffing and shift management.
Predictive Analytics retains the largest installed base; AI-Powered Analytics is climbing the fastest amid interface democratization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce analytics originated in the United States during the early 2000s with the emergence of dedicated people analytics teams at technology and financial services firms. This lineage established American enterprises as the proving ground for predictive attrition models and talent intelligence platforms before regulatory complexity forced architectural divergence.
United States
Financial services firms in New York and Chicago deploy capital-expenditure-grade workforce planning tools for board-level staffing forecasts. The EEOC's algorithmic fairness guidance tightens vendor accountability for biased model outputs across protected class intersections. Silicon Valley technology companies consolidate talent intelligence platforms, terminating standalone point solutions in favor of embedded HCM modules.
Germany
Automotive manufacturers with works council agreements favor hybrid cloud architectures for co-determination compliance. The EU AI Act mandates human-in-the-loop overrides for high-stakes employment decisions including terminations. Stuttgart and Munich industrial clusters drive demand for auditable analytics infrastructure under CSRD workforce disclosure mandates.
United Kingdom
Professional services firms in London leverage pre-configured workforce KPI libraries without dedicated HR data science teams. GDPR Article 22 restrictions on solely automated employment decisions limit black-box predictor deployment. The City of London financial district anchors adoption of scenario-modeling engines for headcount projections.
India
IT services exporters in Bangalore and Hyderabad integrate workforce analytics for global delivery center optimization. The country's central bank guidelines on outsourcing governance shape procurement criteria for multinational back-office operations. Mumbai financial institutions deploy attrition probability models for retention investment allocation.
Japan
Manufacturing conglomerates in the Nagoya industrial corridor apply organizational network analysis to identify hidden influencers. METI's human capital disclosure guidelines create certification demand for ISO 30414-compliant platforms. Tokyo-headquartered enterprises consolidate vendor relationships around integrated talent intelligence suites.
Workforce Analytics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across audit trail completeness and model explainability dimensions. The vendor base stratifies between embedded HCM suite providers and standalone people analytics specialists. Three archetypes dominate: database-to-analytics pipeline owners, cloud-native standalone platforms, and legacy workforce management extenders. Consolidation through HCM module attach-rate expansion and strategic exits by point-solution providers reshape positioning.
Within the embedded suite tier, SAP SE and Oracle Corporation occupy positions anchored to decades of enterprise HCM footprint. Visier, Inc. exemplifies the standalone specialist archetype competing on depth of pre-built workforce KPI libraries. Workday, Inc. sits at the convergence point between native cloud architecture and integrated talent intelligence platform consolidation.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Ultimate Kronos Group |
| SAP SE |
| Ceridian HCM, Inc. |
| Visier, Inc. |
| Oracle Corporation |
| Automatic Data Processing, Inc. |
| Cornerstone OnDemand, Inc. |
| Workday, Inc. |
| Others |
Supply Flow & Price Mechanics
EU CSRD disclosure mandates for workforce metrics are forcing procurement departments to prioritize auditable analytics platforms over lower-cost alternatives, compelling vendors to absorb compliance engineering costs while maintaining subscription accessibility for mid-market buyers. This demand-side specification shift is compressing margins on entry-tier SaaS offerings while reinforcing premium pricing power for ISO 30414-certified platforms.
Pricing Analysis
Subscription tiers segmented by deployment complexity and audit-readiness anchor vendor revenue models. Price differentiation rests on certification grade and customization depth, with EU AI Act-compliant human-in-the-loop architectures commanding premiums over standard automated versions. Cost compression in the mid-market tier is intensifying because cloud-native entrants are undercutting legacy suite providers on implementation timelines. SMEs exhibit highest price sensitivity, while Fortune 500 CHROs prioritize audit trail completeness over license cost.
Supply Chain Analysis
Refurbishment and retraining flows for AI model versions—driven by regulatory divergence between EU and US jurisdictions—create reverse-logistics complexity for vendors maintaining dual deployment architectures. Engineering talent concentrates in the United States, India, and Germany, with HR data science expertise drawing from Bangalore, Silicon Valley, and Berlin labor pools. Supply chain risk centers on single-source vulnerability for specialized organizational network analysis components. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workforce analytics market functions as a stable compounder underpinned by mandatory disclosure regimes that institutionalize recurring demand for compliant infrastructure.
For Market Incumbents: Anticipate consolidation pressure from embedded HCM suite providers by deepening vertical integration into organizational network analysis capabilities and securing ISO 30414 certification ahead of competitor roadmaps. Defend renewal rates through API-first architectures that reduce client switching costs while expanding module attach rates within existing accounts. For New Entrants and Emerging Players: Cloud-native deployment routes through AWS Marketplace and Microsoft Azure commercial channels offer lowest-friction customer acquisition paths. White-space opportunity concentrates in mid-market professional services firms across the United Kingdom and India, where pre-configured workforce KPI libraries address talent scarcity without dedicated HR data science teams. For Investors and Strategic Acquirers: Asymmetric upside sits with standalone people analytics specialists possessing depth in pre-built workforce KPI libraries and established EU AI Act compliance architectures. Long-term viability favors platforms with demonstrated attach-rate expansion within Fortune 500 accounts rather than point-solution providers facing HCM suite displacement. Monitor CSRD implementation timelines for early signals of procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded HCM suite consolidation at Workday and SAP is squeezing standalone providers into niche scenarios. |
| Acquisition of Specialist Firm | Organizational network analysis capabilities from graph neural network startups deepen talent intelligence differentiation. |
| Geographic Expansion | EU AI Act compliance investments in Stuttgart and Munich industrial clusters capture CSRD-mandated procurement waves. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure accelerate mid-market distribution through pre-validated deployment templates. |
| Product Launch | Human-in-the-loop override modules satisfy EU AI Act risk classification requirements for high-stakes employment decisions. |
Methodological Framework
Multiple input streams—primary interviews with CHROs and workforce analytics vendors, regulatory filing analysis, and enterprise procurement database review—were reconciled to construct demand-side estimates. Conversations with HR technology procurement officers, HCM platform integration specialists, and EU compliance consultants informed deployment preference shifts. Secondary validation drew from SEC 10-K disclosures, EU CSRD implementation guidance, and ISO 30414 certification registries. Bottom-up license count estimates and top-down enterprise spending surveys were triangulated to anchor market sizing.
Data-stream reconciliation across deployment model, application type, organization size, and regional regulatory cluster produced segment-level projections across the analysis window. CAGRs were derived from modeled adoption curves weighted by compliance mandate enforcement timelines. Forecast inputs incorporated cloud HCM migration velocity, works council negotiation patterns in German manufacturing, and natural language interface adoption rates among line managers without statistical training.
Regulatory enforcement delays, cross-border data residency conflicts, and HR data science talent availability are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about CSRD disclosure granularity and EU AI Act implementation consistency across member states. Practitioners should monitor national regulator guidance publication timelines and hyperscaler marketplace growth rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Voice Analytics Market
Analytics
India Contact Center Analytics Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Assortment Analytics Market
Analytics
Sentiment Analytics Market
Analytics
Audio and Video Analytics Software Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Global Operational Analytics Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Product Analytics Market
Analytics
Complex Event Processing Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Content Analytics Market