
 Europe Workforce Management Software Market | 2026-2036
Europe Workforce Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Workforce Management Software Market Foresight
Legacy on-premises infrastructure is hardening into a cost burden as cloud-native architectures replace capital-intensive server deployments. SAP SE leverages deep ERP integration to anchor enterprise accounts across German manufacturing corridors. Oracle Corporation competes through database-layer connectivity that sustains complex workforce analytics pipelines. ATOSS Software AG specializes in time and attendance precision, dominating mid-market industrial clients in Austria and Switzerland.
Workforce management software orchestrates labor allocation, time capture, scheduling optimization, and compliance tracking through integrated digital platforms that typically process real-time biometric or mobile clock-in data against shift rosters and pay rules. Its primary commercial purpose is to minimize labor cost leakage while enforcing working-time regulations such as EU Directive 2003/88/EC on maximum weekly hours. Cloud-Based deployment leads segment expansion as manufacturers abandon on-site server maintenance, while Analytics functionality captures margin pools by converting workforce data into predictive labor models. SMEs represent the fastest-growing customer type as subscription pricing dismantles upfront licensing barriers that previously excluded smaller operators.
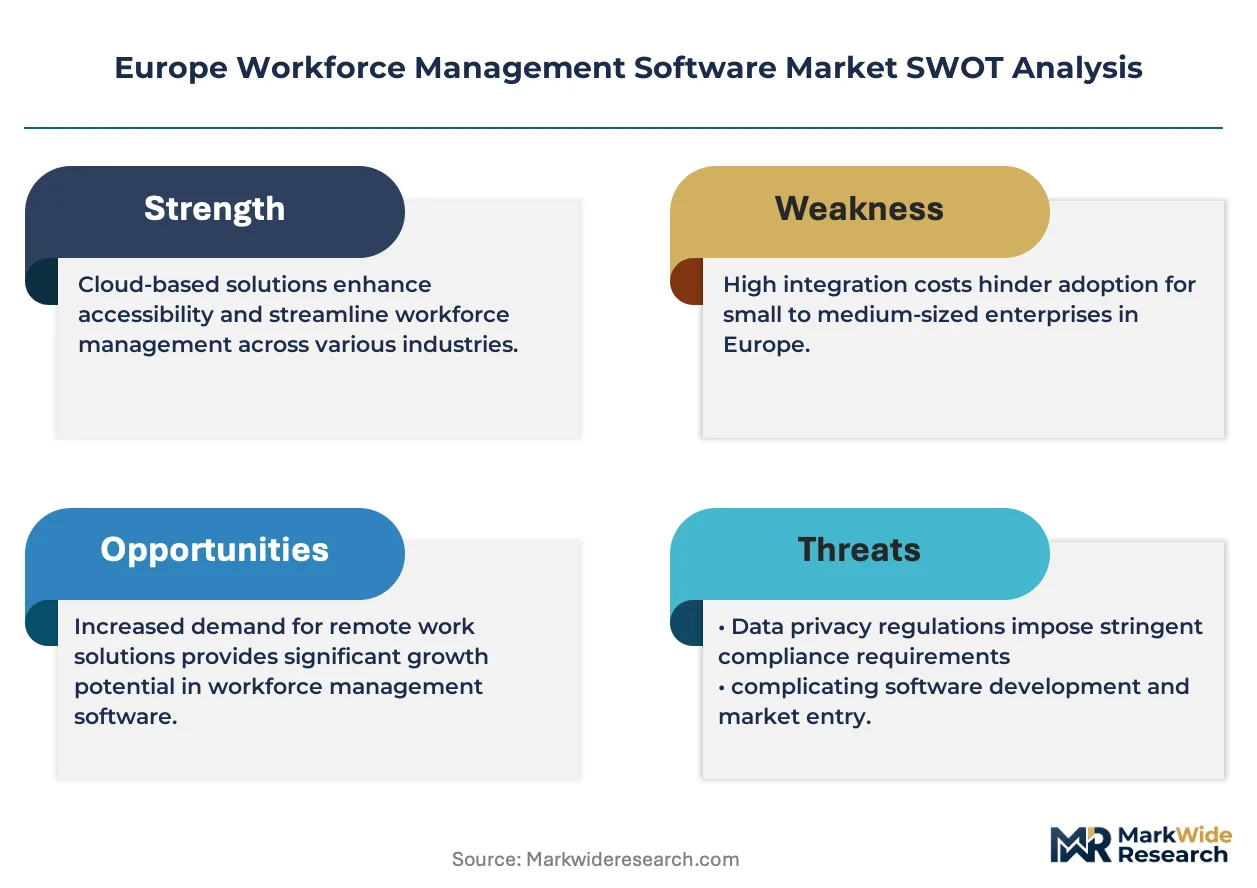
GDPR shapes how vendors process biometric attendance data and employee behavioral analytics, forcing architectural investments in EU-sovereign data residency. The EU AI Act imposes risk-classification obligations on automated scheduling algorithms that affect worker assignments, creating compliance differentiation among platform providers. REACH and RoHS indirectly influence hardware-dependent time-clock manufacturers supplying European facilities. Stakeholders must monitor how the CSRD's workforce disclosure requirements will expand demand for granular labor analytics that trace equity metrics across shift allocations and pay outcomes.
Market Dynamics
Cloud-native workforce management platforms are compressing deployment timelines from quarters to weeks across European manufacturing and healthcare, while GDPR and the EU AI Act impose architectural costs that favor established vendors with compliance infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:Automated scheduling algorithms now face risk-classification obligations, forcing employers toward certified platforms that embed algorithmic transparency and human oversight controls.
- Healthcare workforce complexity:Hospitals and long-term care facilities deploy integrated scheduling to manage 24/7 clinician rotations, union rule sets, and fatigue-monitoring requirements under the Working Time Directive.
- Industrial IoT convergence:Manufacturing plants in Germany and Poland connect workforce systems to machine-state data, enabling demand-responsive labor allocation tied to real-time production signals.
Market Restraints
- Legacy system entrenchment:German automotive and chemical producers maintain decades-old on-premises ERP integrations that resist cloud migration without multimillion-euro replacement cycles.
- Biometric data processing costs:GDPR's strict consent and storage requirements for fingerprint and facial recognition attendance systems inflate implementation budgets and legal review timelines.
- Skills concentration in Central Europe:Implementation and integration expertise clusters in Germany, Austria, and Switzerland, creating vendor availability constraints for Southern and Eastern European deployments.
Strategic Opportunities
- CSRD workforce disclosure requirements:The Corporate Sustainability Reporting Directive mandates granular labor analytics, expanding demand for platforms that trace pay equity and shift allocation patterns across gender and contract types.
- SME subscription penetration:Mid-sized industrial firms in Spain and Italy abandon spreadsheet scheduling as per-employee SaaS pricing dismantles upfront licensing barriers that previously excluded smaller operators.
- Predictive absence management:Machine learning models that forecast sick-leave patterns and auto-trigger float-pool activation are gaining traction among Dutch and Belgian healthcare networks.
Industry Challenges
- Algorithmic bias auditing:HR teams lack internal capability to validate that automated scheduling tools do not discriminate against part-time workers or specific demographic groups in shift quality allocation.
- Cross-border data residency:Multinational employers operating across Germany, France, and Poland must architect workforce data flows that satisfy divergent national implementations of GDPR and sector-specific labor authority requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Workforce Management Software Market |
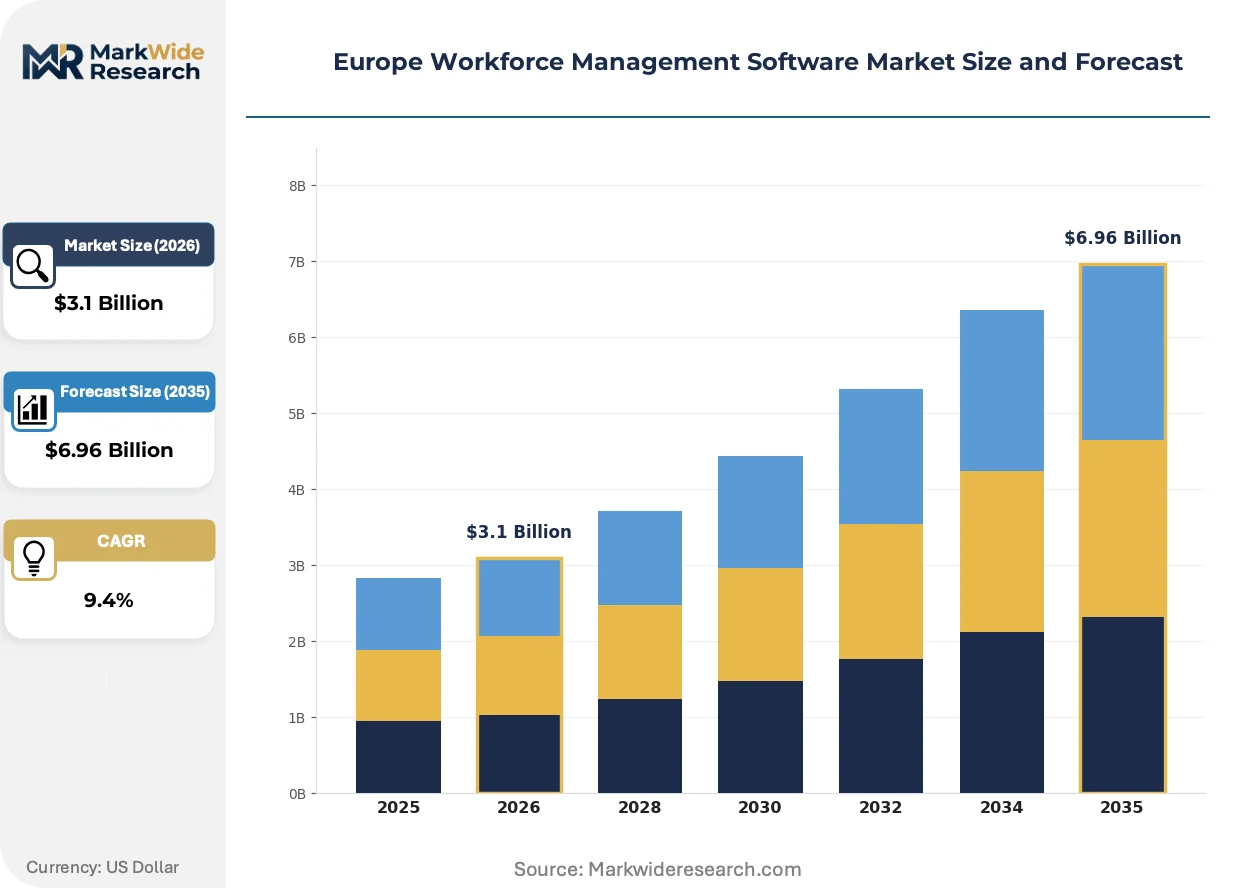
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.96 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time & Attendance, Scheduling, Payroll, Analytics End User: Manufacturing, Retail, Healthcare, Hospitality Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Customer Type: SMEs, Large Enterprises, Public Sector, Non-Profits |
| Companies Covered | ATOSS Software AG, Oracle Corporation, IBM Corporation, Automatic Data Processing, Inc. (ADP), SAP SE, UKG Inc., Workday, Inc., Verint Systems Inc., Infor Global Solutions, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Workforce Management Software Market Shifts & Advancements
Workforce management technology is absorbing adjacent capabilities from HR analytics, compliance automation, and employee experience platforms, compressing the traditional vendor stack into unified systems.
AI-powered shift optimization is absorbing rules-engine complexity from legacy scheduling systems, enabling real-time reallocation based on demand signals, worker preferences, and regulatory constraints. German automotive suppliers and French hospital networks are deploying these tools at scale. The technology is absorbing margin pools previously captured by manual workforce planners and external staffing agencies.
The EU AI Act's risk-based classification framework is reshaping how vendors architect automated decision systems, particularly for shift allocation algorithms that affect worker assignments. High-risk applications now require conformity assessments, human oversight protocols, and bias monitoring. Healthcare and logistics sectors in Germany and the Netherlands are experiencing the steepest compliance adaptation curves.
Subscription-based procurement is displacing perpetual licensing across mid-market manufacturing and retail chains in Italy, Spain, and Portugal. Buyers now prioritize vendors offering rapid deployment templates and pre-configured compliance modules over customization depth. This preference shift is compressing implementation timelines and elevating vendors with standardized vertical solutions.
Europe Workforce Management Software Market Segmentation
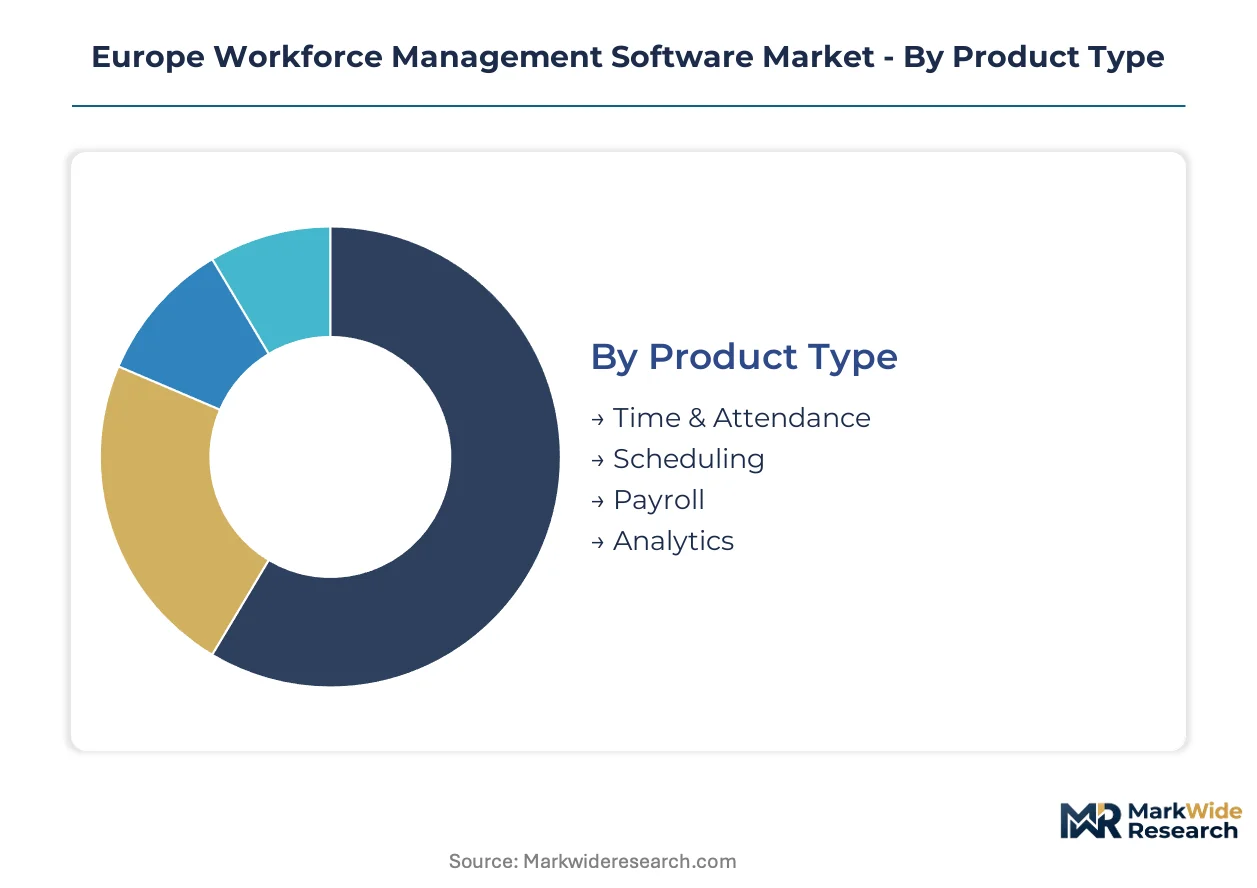
Workforce management software segments diverge sharply in capital requirements, with cloud-native architectures demanding minimal upfront infrastructure while on-premises deployments anchor long-tail replacement cycles. Understanding these investment profiles clarifies why vendor strategies and customer migration patterns vary across European manufacturing and healthcare corridors.
Product Type:
Capital intensity escalates from standalone time-capture modules through integrated analytics suites that demand data warehouse investments and specialized implementation expertise.
- Time & Attendance:Biometric and mobile clock-in systems process real-time entry-exit data against shift rosters and pay rules. German automotive suppliers and Polish manufacturing plants drive replacement demand as GDPR compliance costs render legacy fingerprint systems uneconomical.
- Scheduling:Algorithmic shift optimization engines balance worker preferences, union rule sets, and fatigue-monitoring requirements under EU Directive 2003/88/EC. French hospital networks and Dutch healthcare chains deploy these tools at scale to manage 24/7 clinician rotations.
- Payroll:Compensation calculation engines integrate with national tax authorities and collective bargaining agreements across Germany, France, and Italy.
- Analytics:Predictive labor models convert historical workforce data into demand-forecasting pipelines. CSRD disclosure mandates are accelerating adoption among listed European manufacturers.
Most installed capacity flows through Time & Attendance. Expansion is steepest in Analytics.
End User:
Application complexity scales with shift volatility and regulatory oversight intensity, separating routine retail scheduling from healthcare's union-negotiated rotation management.
- Manufacturing:Industrial IoT convergence connects workforce systems to machine-state data, enabling demand-responsive labor allocation. German automotive corridors and Polish electronics plants lead integration investments.
- Healthcare:Clinician scheduling manages 24/7 rotations, fatigue-monitoring, and EU Working Time Directive compliance. German hospital networks and Belgian long-term care facilities anchor regional demand.
- Retail:Seasonal demand fluctuations and part-time worker density drive adoption among Spanish and Italian mid-market chains.
- Hospitality:Event-driven staffing patterns and high turnover rates concentrate demand in French and Italian tourism clusters.
Healthcare commands the highest per-seat pricing. Manufacturing delivers the largest aggregate contract values.
Deployment:
Migration economics favor subscription models that eliminate server maintenance burdens, though data residency requirements preserve hybrid architectures for sensitive biometric processing.
- On-Premises:Capital-intensive server deployments persist among German chemical producers and automotive suppliers with decades-old ERP integrations resisting cloud migration without multimillion-euro replacement cycles.
- Cloud-Based:SaaS delivery compresses implementation timelines from quarters to weeks. Italian and Spanish mid-market manufacturers abandon on-site maintenance as subscription pricing dismantles upfront licensing barriers.
- Hybrid:Split architectures satisfy GDPR data residency mandates while capturing cloud scalability for non-sensitive scheduling functions.
- Mobile:Smartphone-native clock-in and shift-swapping applications gain traction among retail and hospitality workforces with limited desktop access.
Cloud-Based deployment is gaining share fastest. On-Premises retains entrenched positions in German industrial corridors.
Customer Type:
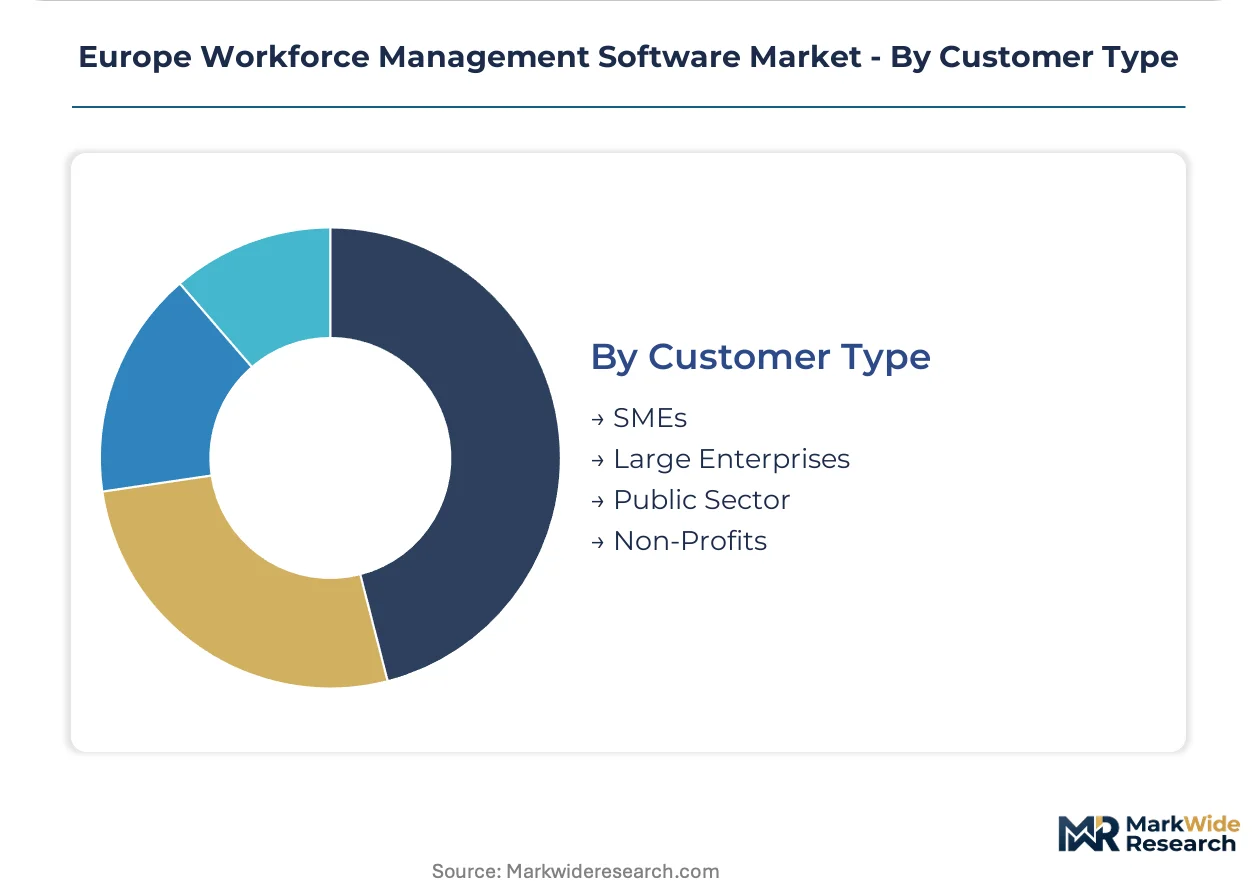
Procurement sophistication and compliance surface area separate enterprise buyers with dedicated vendor management offices from resource-constrained SMEs seeking rapid deployment templates.
- SMEs:Mid-sized industrial firms in Spain and Italy adopt standardized vertical solutions as per-employee SaaS pricing eliminates upfront licensing barriers that previously excluded smaller operators.
- Large Enterprises:Multinational employers operating across Germany, France, and Poland architect workforce data flows satisfying divergent national GDPR implementations and sector-specific labor authority requirements.
- Public Sector:Government and municipal buyers prioritize pre-configured compliance modules and algorithmic transparency under EU AI Act risk-classification obligations.
- Non-Profits:Budget-constrained organizations favor subscription tiers with essential scheduling and time-capture functionality over predictive analytics capabilities.
Large Enterprises concentrate vendor profitability. SMEs are climbing the fastest as subscription penetration dismantles historical exclusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and chemical corridors anchor European workforce management software demand, where industrial IoT convergence and stringent labor regulations drive platform sophistication. Cloud migration accelerates across Southern Europe while Central European markets grapple with legacy ERP entrenchment. National labor authority implementations of GDPR and the EU AI Act create divergent compliance surface areas.
Germany
Automotive suppliers in Baden-Württemberg and chemical producers in North Rhine-Westphalia deploy demand-responsive labor allocation tied to machine-state data. The KBA and sector-specific labor authorities enforce strict working-time documentation under the Working Time Directive. Stuttgart's manufacturing clusters lead integration investments connecting workforce systems to real-time production signals.
France
French hospital networks in Île-de-France manage 24/7 clinician rotations through algorithmic scheduling balancing union rule sets and fatigue-monitoring requirements. ANSM and CNIL impose layered oversight on biometric attendance data and automated decision systems. Parisian healthcare clusters anchor regional demand for integrated workforce analytics platforms.
United Kingdom
London-based financial services and retail chains adopt cloud-native scheduling to manage hybrid work patterns and part-time worker density. Post-Brexit data residency requirements diverge from EU GDPR implementations, creating architectural complexity for cross-border employers. The Southeast corridor concentrates SaaS procurement among mid-market enterprises.
Italy
Mid-market manufacturing firms in Lombardy and Emilia-Romagna abandon spreadsheet scheduling as per-employee SaaS pricing dismantles upfront licensing barriers. Italian labor authority interpretations of EU Directive 2003/88/EC shape local compliance module configurations. Milan's industrial districts lead subscription penetration among previously excluded smaller operators.
Netherlands
Dutch healthcare networks and logistics operators deploy predictive absence management models that forecast sick-leave patterns and auto-trigger float-pool activation. The country's progressive labor market policies accelerate adoption of worker preference-matching algorithms. Rotterdam's logistics hubs and Amsterdam's hospital clusters drive machine learning integration in workforce planning.
Europe Workforce Management Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors integrate adjacent HR analytics and compliance automation capabilities to compress traditional technology stacks. The vendor base stratifies across three tiers: ERP-anchored enterprise suites, specialized time-and-attendance precision players, and cloud-native challengers with rapid-deployment templates. Two strategic archetypes prevail—incumbents leveraging deep system integration and insurgents attacking mid-market subscription penetration. M&A activity and vertical solution development represent the dominant competitive vectors reshaping market structure.
Within the ERP-anchored tier, SAP SE and Oracle Corporation exemplify vendors sustaining complex workforce analytics pipelines through database-layer connectivity and manufacturing corridor relationships. ATOSS Software AG occupies a specialist position exemplifying mid-market industrial precision in German-speaking markets. UKG Inc. and Workday, Inc. represent cloud-native challengers capturing subscription growth among employers prioritizing rapid deployment over customization depth. These company patterns illustrate how competitive positioning splits between integration depth and deployment velocity.
| Leading Market Players |
|---|
| ATOSS Software AG |
| Oracle Corporation |
| IBM Corporation |
| Automatic Data Processing, Inc. (ADP) |
| SAP SE |
| UKG Inc. |
| Workday, Inc. |
| Verint Systems Inc. |
| Infor Global Solutions, Inc. |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS migration compresses both deployment economics and vendor cost structures across European workforce management, concentrating pricing power with platforms that absorb compliance infrastructure burdens under GDPR and the EU AI Act while fragmenting margins for on-premises legacy providers.
Pricing Analysis
Input-cost pass-through from EU-sovereign data residency requirements and algorithmic audit infrastructure inflates subscription tiers for high-risk automated scheduling applications. Three-tier pricing structure across premium, standard, and economy levels separates enterprise analytics suites with predictive labor modeling from mid-market scheduling modules and basic time-capture tools. Price differentiation hinges on vertical integration depth and certification grade under EU AI Act conformity assessment frameworks. Pricing pressure stems from subscription commoditization among cloud-native challengers attacking SME segments in Southern Europe. Mid-market manufacturers in Spain and Italy exhibit highest price sensitivity, while German automotive corridors prioritize integration depth over per-seat cost.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Ireland anchor cloud infrastructure provisioning for workforce data processing under GDPR residency mandates. Software development talent concentrates in Germany, Austria, and Switzerland, with implementation expertise clustering in Central European technology corridors. Raw material dependencies center on semiconductor components for biometric time-clock hardware and GPU compute capacity for machine learning scheduling models. Supply chain risk manifests in single-source vulnerability for specialized GDPR compliance audit services and algorithmic bias validation tooling. Distribution runs through direct enterprise sales teams for large accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European workforce management software functions as a geographic-arbitrage play where regulatory compliance costs in Germany and France create margin pools that subsidize aggressive SaaS pricing in underpenetrated Southern European markets.
For Market Incumbents: Cement platform stickiness through deep ERP integration into SAP and Oracle manufacturing corridors while embedding EU AI Act algorithmic transparency modules that emerging cloud-native challengers lack resources to replicate. Prioritize backward integration into biometric hardware supply chains to capture margin pools from time-clock manufacturers facing REACH and RoHS compliance cost inflation. Defend against subscription-based insurgents by accelerating pre-configured vertical solutions for healthcare and automotive segments. For New Entrants and Emerging Players: Systems integrators and regional IT consultancies in Italy, Spain, and Portugal offer the most accessible channel leverage for rapid mid-market penetration. Target SME manufacturing firms in Lombardy and Emilia-Romagna that abandoned spreadsheet scheduling but remain underserved by enterprise-focused incumbents. White-space opportunities concentrate in predictive absence management for Dutch and Belgian healthcare networks and CSRD-compliant labor analytics for listed manufacturers. Go-to-market velocity depends on rapid-deployment templates with pre-built GDPR consent workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized time-and-attendance precision players with entrenched industrial client bases in German-speaking markets but limited analytics expansion capability. Long-term viability over the next decade hinges on successful migration from perpetual licensing to recurring subscription revenue and AI-powered feature monetization. Acquisition target archetypes include mid-market vertical specialists with healthcare or manufacturing domain expertise and established compliance module libraries. Monitor EU AI Act enforcement patterns as the critical inflection signal for platform differentiation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Conformity assessment for high-risk scheduling algorithms unlocks enterprise procurement pipelines in German healthcare networks. |
| Cloud-Native Platform Migration | SaaS delivery compresses implementation timelines from quarters to weeks for Italian and Spanish mid-market manufacturers. |
| Vertical Solution Development | Pre-configured modules for automotive IoT integration and clinician fatigue monitoring capture segment-specific pricing premiums. |
| Strategic Partnership with ERP Vendors | SAP and Oracle database-layer connectivity sustains complex workforce analytics pipelines in enterprise manufacturing accounts. |
| Acquisition of Biometric Hardware Specialist | GDPR-compliant time-clock manufacturing capabilities secure margin pools and eliminate third-party supply dependencies. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Southern Europe, with primary inputs from each regional cluster. The analysis combines structured interviews with workforce management software vendors, HR technology procurement officers at manufacturing and healthcare enterprises, systems integration specialists, and regulatory compliance consultants with secondary validation against EU AI Act implementation guidance, GDPR enforcement patterns from national data protection authorities, and SEC filings from publicly traded platform providers. Bottom-up triangulation of vendor-reported deployment metrics and top-down reconciliation against aggregate market sizing ensures methodological rigor.
Granularity-level modeling extends across deployment architecture, organization size tier, vertical industry segment, integration complexity profile, and regional adoption pattern. Value and volume outputs derive from triangulated approaches incorporating vendor revenue disclosures, customer procurement database analysis, and macroeconomic labor cost indicators across the projection horizon. CAGRs emerge from segment-level growth rate reconciliation against aggregate market trajectory assumptions. Forecast inputs center on EU AI Act compliance timeline acceleration and cloud migration velocity among mid-market industrial firms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement stringency variations across member states and potential GDPR biometric data processing restriction tightening. Outputs reflect documented assumptions regarding regulatory implementation timelines and technology adoption curve parameters. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Gamification Software Market
Software & Services
Construction Software Market
Software & Services
United States IT Services Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
United States Human Resource (HR) Technology Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
Web Framework Software Market
Software & Services
Global Pension Administration Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Driver Updater Software Market
Software & Services
Global Kiosk Software Market
Software & Services
Telecom IT Services Market
Software & Services
Global Project Software Market