
 Echo Reduction Software Market | 2026-2036
Echo Reduction Software Market Size, Share, and Industry Trends Forecast 2026-2036
Echo Reduction Software Market Insights
Enterprise-grade latency specifications below 50 milliseconds is reorganizing competitive dynamics across the echo reduction software landscape. Krisp leverages its neural network training infrastructure to sustain real-time processing advantages across noisy environments. VOCAL Technologies anchors its position through deep specialization in embedded audio algorithms for telecommunications hardware. SoliCall competes by extending proprietary noise-profile libraries that differentiate its API offerings from generic open-source alternatives.
Echo reduction software employs adaptive filtering algorithms, acoustic echo cancellation kernels, and spectral subtraction methods to eliminate reverberant artifacts from real-time voice streams, typically operating within 10-150 millisecond processing windows to preserve conversational naturalness. The technology serves primary commercial purposes in unified communications platforms, telemedicine consultations, and remote learning environments where audio clarity directly determines user retention and operational compliance. Cloud-based solutions currently lead deployment preferences among corporate sector end users seeking elastic scaling without capital infrastructure commitments, while integrated systems capture margin pools in healthcare provider networks requiring HIPAA-aligned data sovereignty. Machine learning architectures represent the fastest-expanding technology segment as training datasets expand across multilingual acoustic environments.
The FCC enforces voice quality standards through Part 68 terminal equipment rules that indirectly mandate echo control performance in interconnected systems, while HIPAA security frameworks constrain audio data handling practices for healthcare provider deployments. GDPR cross-border data transfer provisions shape cloud architecture decisions for European corporate users of SaaS-based echo reduction platforms. Stakeholders must monitor evolving AI transparency requirements from the EU AI Act as automated audio processing faces emerging algorithmic accountability obligations.
Market Dynamics
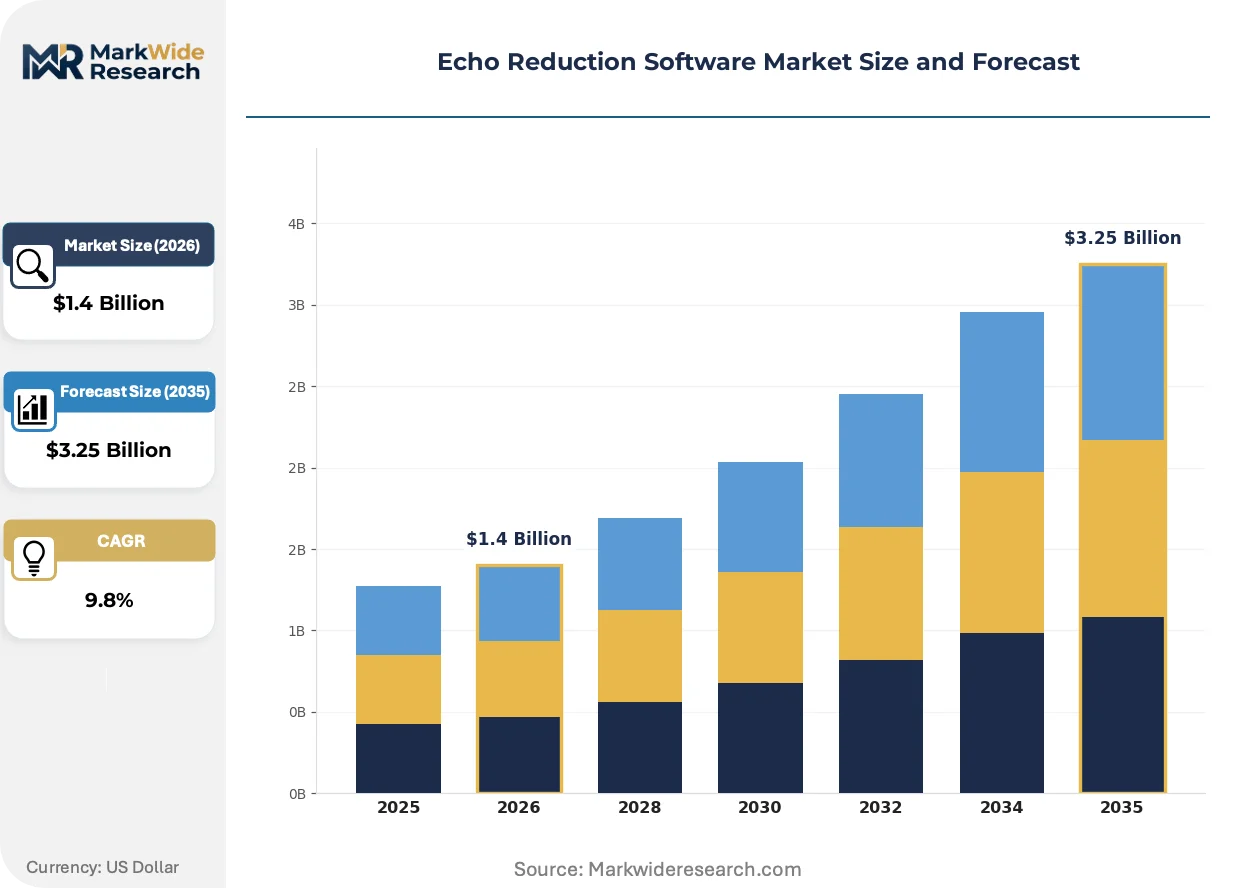
Machine learning inference architectures are compressing latency benchmarks below 50 milliseconds, forcing DSP-based legacy systems into obsolescence and redistributing competitive advantage toward neural network training scale.
Growth Catalysts
- Hybrid Work Protocols:Permanent distributed operations across corporate campuses and contact centers sustain enterprise procurement of real-time audio processing suites.
- FCC Part 68 Rules:Terminal equipment standards indirectly mandate echo control performance, embedding compliance requirements into interconnected voice systems.
- HIPAA Security Frameworks:Audio data handling constraints for healthcare providers accelerate demand for on-premise and sovereign-cloud deployments.
Market Restraints
- GPU Compute Cost Volatility:Neural training infrastructure depends on concentrated semiconductor supply chains subject to foundry allocation constraints.
- GDPR Cross-Border Friction:Data transfer provisions complicate SaaS architecture decisions for European corporate users, extending procurement cycles.
- Spectral Subtraction Limitations:Traditional non-neural methods retain residual artifacts in reverberant environments, capping performance in cost-sensitive segments.
Strategic Opportunities
- Telemedicine Expansion:Remote consultation platforms in underserved rural health networks present white-space demand for embedded echo cancellation.
- EU AI Act Transparency Mandates:Emerging algorithmic accountability obligations for automated audio processing create compliance-service revenue streams.
- Edge-Cloud Convergence:Federated inference architectures split processing between device and infrastructure, opening hybrid deployment models.
Industry Challenges
- Acoustic Engineer Scarcity:Specialized talent pools for adaptive filter tuning and kernel optimization lag behind deployment velocity.
- Legacy UC Integration Complexity:Proprietary APIs in incumbent unified communications platforms resist standardized plug-in architectures.
- ISO/IEC 27001 Certification Timelines:Information security management audits delay go-to-market for healthcare-focused vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Echo Reduction Software Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Cloud-Based Solutions, Integrated Systems, Mobile Applications End User: Corporate Sector, Educational Institutions, Healthcare Providers, Hospitality Services Technology: Machine Learning, Digital Signal Processing, AI Algorithms, Audio Engineering Techniques Deployment: On-Premise, Hybrid, SaaS, Multi-Tenant |
| Companies Covered | Krisp, SoliCall, Silentium, VOCAL Technologies, AudioCommander, Claerityai, IRIS Clarity, Noise Blocker, Utterly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Echo Reduction Software Market Trends and Innovations
Neural inference at the edge is rewriting performance economics, collapsing the latency-cost tradeoff that previously segmented cloud and embedded deployment strategies.
Transformer-based acoustic models are displacing recurrent neural network architectures in real-time echo cancellation pipelines. Enterprise IT departments and telemedicine platform operators adopt these architectures within 18-month refresh cycles. The shift is displacing DSP coprocessor vendors from premium tier supply chains and concentrating value capture in GPU-accelerated inference stacks.
GDPR cross-border data transfer provisions are tightening architectural constraints on SaaS-based echo reduction platforms. European corporate users now require data residency guarantees that fragment cloud infrastructure strategies. Healthcare provider networks in Germany and France respond by prioritizing on-premise or regional sovereign-cloud deployments over hyperscaler alternatives.
Subscription consumption models are supplanting perpetual license structures in enterprise procurement. Chief information officers negotiate usage-based contracts that unbundle implementation services from core software fees. This pattern concentrates in United States distributed contact centers, where seasonal volume volatility favors elastic scaling commitments over fixed-capacity investments.
Echo Reduction Software Market Segmentation
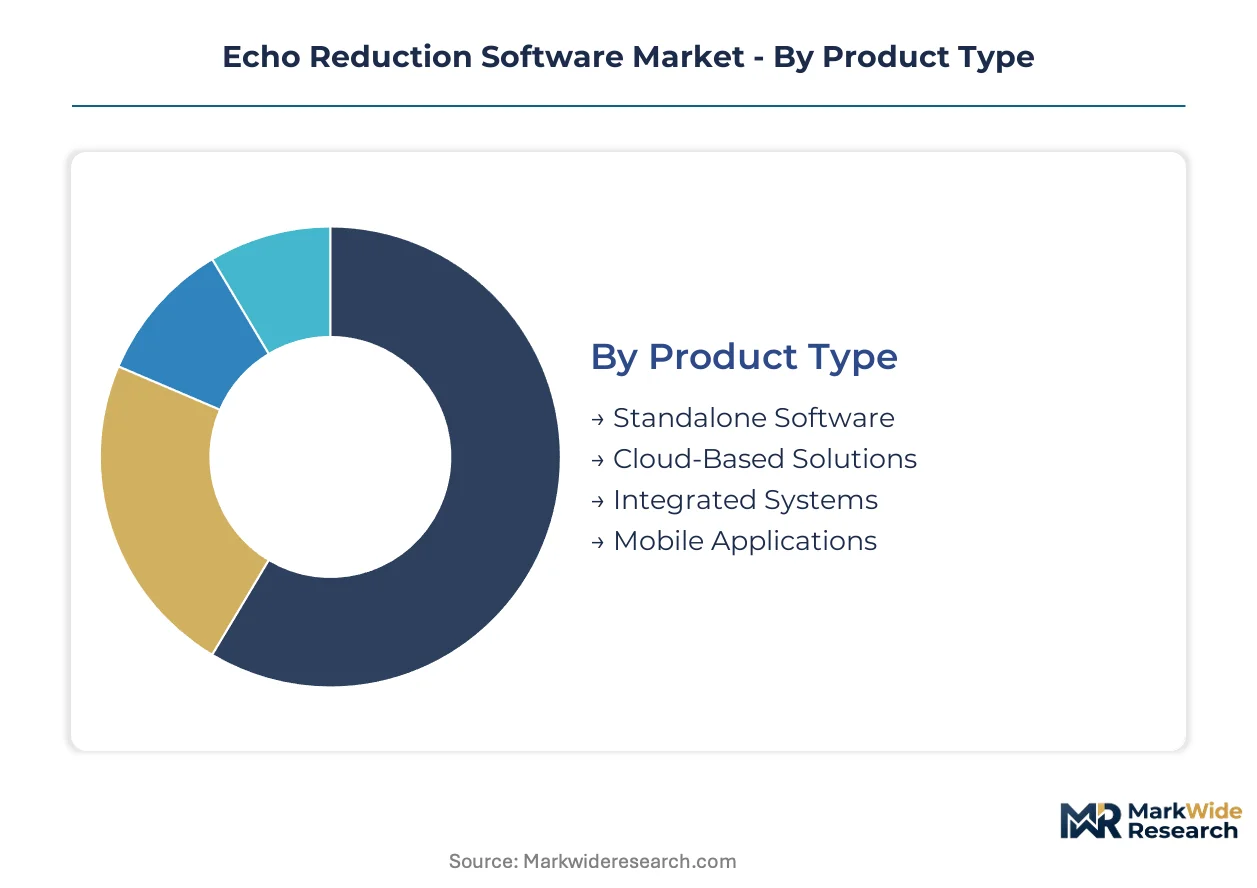
Echo reduction software vendors face divergent substitution pressures across product architectures, with cloud-native platforms threatening legacy on-premise installations while integrated systems displace standalone deployments in consolidated procurement cycles. Segmentation strategy determines margin capture, as machine learning inference stacks command premium pricing against commoditized DSP alternatives.
Product Type:
Substitution pressure intensifies against perpetual-license standalone products as consumption-based cloud models reduce capital barriers for mid-market adopters.
- Standalone Software:Perpetual-license desktop installations with local processing kernels serve cost-sensitive education and small hospitality operators. Procurement concentrates in United States school districts with constrained IT budgets and limited cloud infrastructure.
- Cloud-Based Solutions:Elastic inference architectures with sub-50ms latency targets capture enterprise refresh cycles. United States distributed contact centers drive volume through usage-based contracts that match seasonal staffing volatility.
- Integrated Systems:Bundled hardware-software stacks for unified communications platforms. Healthcare provider networks in Germany prioritize these for HIPAA-aligned data sovereignty.
- Mobile Applications:Lightweight SDKs for iOS and Android telemedicine clients. Telehealth operators in rural India deploy these for field consultation workflows.
Cloud-based solutions anchor the volume base while integrated systems gain share at the steepest rate.
End User:
Cost tier stratification separates premium healthcare deployments from price-optimized education procurement, with hospitality representing an emerging volume segment.
- Corporate Sector:Enterprise IT departments mandate sub-50ms latency specifications for hybrid work platforms. United States Fortune 500 campuses drive premium software procurement with annual refresh commitments.
- Healthcare Providers:Telemedicine platforms require HIPAA-compliant audio pipelines with audit trails. German hospital networks favor on-premise deployments over hyperscaler alternatives.
- Educational Institutions:K-12 districts and universities prioritize cost-per-seat metrics over performance benchmarks. Procurement clusters in United States public school systems with federal connectivity subsidies.
- Hospitality Services:Conference venues and hotel contact centers adopt echo cancellation for guest service automation. Dubai hospitality operators lead deployment in premium property segments.
Corporate sector deployments generate the highest revenue per seat while healthcare providers expand most quickly under regulatory compliance mandates.
Technology:
Volume concentration favors mature DSP implementations, though machine learning architectures are climbing the fastest as training scale advantages compound.
- Machine Learning:Transformer-based acoustic models trained on multilingual datasets. United States enterprise IT departments adopt these within 18-month refresh cycles for noise-robust performance.
- Digital Signal Processing:Fixed-kernel adaptive filters with deterministic latency. Embedded telecommunications hardware in legacy Japanese infrastructure relies on these for regulatory stability.
- AI Algorithms:Hybrid neural-DSP pipelines optimized for edge inference. South Korean consumer electronics manufacturers integrate these for smart speaker products.
- Audio Engineering Techniques:Spectral subtraction and manual filter tuning for broadcast post-production. French radio networks retain these for content archival workflows.
Digital signal processing anchors installed capacity while machine learning captures the steepest expansion trajectory in new procurement.
Deployment:
Customer type segmentation separates regulated healthcare operators requiring data residency from agile corporate adopters prioritizing elastic scaling.
- SaaS:Fully managed inference with automatic model updates. United States mid-market corporations favor these for zero-infrastructure deployments.
- On-Premise:Air-gapped installations with local GPU clusters. German healthcare providers mandate these under GDPR and national data sovereignty laws.
- Hybrid:Split processing with edge inference and cloud model synchronization. Telemedicine platforms in rural Australia deploy these for intermittent connectivity environments.
- Multi-Tenant:Shared infrastructure with tenant isolation for contact center operators. Indian BPO providers adopt these to serve multiple client compliance regimes.
SaaS deployments anchor current volume while hybrid architectures gain share at the steepest rate under edge-cloud convergence strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU-accelerated inference infrastructure clusters heavily in the United States, with secondary concentrations emerging in Germany and Japan where data sovereignty requirements reshape cloud architecture decisions. Enterprise procurement patterns diverge sharply between North American elastic-scaling preferences and European on-premise mandates.
United States
Distributed contact centers in Texas and Arizona drive seasonal procurement of usage-based echo reduction contracts. FCC Part 68 terminal equipment rules embed compliance requirements into interconnected voice systems. Fortune 500 campuses in Silicon Valley and Manhattan mandate sub-50ms latency specifications for hybrid work platforms.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia prioritize on-premise deployments over hyperscaler alternatives. GDPR cross-border data transfer provisions constrain SaaS architecture decisions for corporate users. Berlin-based healthcare IT providers specialize in HIPAA-aligned sovereign-cloud configurations for telemedicine platforms.
Japan
Legacy telecommunications infrastructure relies on fixed-kernel adaptive filters for regulatory stability in Tokyo-Osaka corridors. METI industrial standards shape procurement specifications for embedded audio algorithms. Consumer electronics manufacturers in Nagoya integrate hybrid neural-DSP pipelines for smart speaker products.
India
BPO providers in Bangalore and Hyderabad adopt multi-tenant architectures to serve multiple client compliance regimes. TRAI quality-of-service benchmarks indirectly pressure echo control performance in interconnected systems. Telehealth operators in rural Maharashtra deploy lightweight mobile SDKs for field consultation workflows.
United Kingdom
Financial services contact centers in London mandate real-time audio processing for trading floor communications. GDPR implementation through the UK GDPR framework shapes data residency requirements post-Brexit. Cambridge-based audio engineering firms specialize in spectral subtraction methods for broadcast archival workflows.
Echo Reduction Software Market Competitive Landscape
Concentration sits with neural-network training scale rather than installed base, redistributing advantage toward GPU-accelerated inference stacks and compressing legacy DSP vendors into cost-sensitive segments. The vendor base separates into three archetypes: cloud-native API platforms, embedded algorithm specialists, and hybrid hardware-software integrators. Dominant competitive moves include strategic partnerships with unified communications platforms and vertical integration into edge inference silicon.
Within the cloud-native tier, Krisp exemplifies the neural-training-scale archetype through its real-time processing infrastructure. SoliCall anchors the API-specialist position with proprietary noise-profile libraries. VOCAL Technologies occupies the embedded-specialist tier, representing deep algorithmic focus for telecommunications hardware deployments.
| Leading Market Players |
|---|
| Krisp |
| SoliCall |
| Silentium |
| VOCAL Technologies |
| AudioCommander |
| Claerityai |
| IRIS Clarity |
| Noise Blocker |
| Utterly |
| Others |
Pricing and Supply Chain Analysis
ISO/IEC 27001 certification timelines gate both vendor qualification and price tier access simultaneously, compressing margins for healthcare-focused suppliers while rewarding certified incumbents with premium contract terms. Enterprise procurement teams in United States contact centers and German hospital networks filter vendor pools through security audit completion, creating a bifurcated market where certification status substitutes for price competition at the top tier.
Pricing Analysis
FCC Part 68 terminal equipment rules dictate the pricing tier structure across enterprise deployments, separating HIPAA-aligned on-premise bundles from elastic SaaS consumption models. Price differentiation rests on latency specification attainment and data residency guarantee scope, with sub-50ms architectures commanding substantial premiums over legacy DSP alternatives. Pricing pressure stems from GPU compute cost volatility in neural training infrastructure, squeezing margins for ML-native vendors. Educational institutions in United States public school systems exhibit the highest price sensitivity, while Fortune 500 campuses absorb premium tier costs for compliance-certain deployments.
Supply Chain Analysis
Neural accelerator inventory lead times have extended to twelve-to-eighteen month horizons, constraining vendor scaling velocity and forcing allocation decisions across customer tiers. GPU fabrication concentrates in Taiwan and South Korea, with advanced packaging operations anchored in United States and Japan. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized photonics components. Single-source vulnerability in TSMC's leading-edge node capacity presents structural supply risk. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels, with healthcare procurement favoring authorized reseller networks for compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting toward API-first distribution as unified communications vendors consolidate echo reduction into native feature sets, eroding standalone software margins and compressing vendor count in enterprise procurement cycles.
For Market Incumbents: Secure neural training data moats through multilingual acoustic dataset expansion, defending against open-source model commoditization. Deepen backward integration into edge inference silicon to capture hardware-software margin pools. Prioritize ISO/IEC 27001 certification maintenance as hospital procurement committees harden security requirements. Channel control through exclusive UC platform partnerships represents the critical defensive lever against API disintermediation. For New Entrants and Emerging Players: Differentiate on sovereign-cloud deployment architectures for European healthcare networks constrained by GDPR cross-border friction. Target rural telemedicine operators in India and Australia with lightweight mobile SDKs optimized for intermittent connectivity. White-space penetration in hospitality automation for Dubai premium properties offers escape from enterprise pricing compression. Go-to-market through audio hardware OEM integration bypasses direct sales cost structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across transformer-based acoustic model development, favoring scaled incumbents with captive training infrastructure. Long-term viability in the five-to-ten year window hinges on edge-cloud convergence execution and regulatory compliance service bundling. Acquisition targets should display vertical integration into noise-profile data assets or embedded algorithm portfolios for telecommunications hardware. Watch GPU foundry allocation announcements as the critical inflection signal for vendor scaling capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Neural Training Infrastructure Expansion | Scalable GPU clusters enable real-time processing advantages across noisy environments. |
| HIPAA-Aligned Sovereign-Cloud Deployment | German hospital networks mandate data residency guarantees over hyperscaler alternatives. |
| Embedded Algorithm Licensing | Telecommunications hardware manufacturers in Japan require fixed-kernel adaptive filters. |
| API Platform Integration | Unified communications vendors consolidate echo reduction into native feature sets. |
| Edge Inference Silicon Development | South Korean consumer electronics manufacturers integrate hybrid neural-DSP pipelines. |
Research Methodology
Operator-level perspectives from enterprise IT directors, telemedicine platform engineers, contact center operations managers, and healthcare compliance officers anchored the qualitative base. Primary interview findings combined with secondary validation from FCC equipment authorization databases, HIPAA security framework documentation, GDPR implementation guidance, and hyperscaler capex disclosures. Bottom-up vendor revenue triangulation against top-down enterprise software spending estimates established market size boundaries.
Sensitivity analysis across deployment model adoption curves, GPU cost trajectories, and regulatory timeline scenarios shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, end-user vertical, technology stack, and deployment topology alongside regional compliance regime clustering. CAGRs derived from fitting logistic adoption curves to enterprise refresh cycle data, with neural inference penetration rates and cloud infrastructure elasticity as software-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained hybrid work protocol permanence, stable semiconductor supply allocation, or unaltered FCC terminal equipment rules would require recalibration. Forecasts reflect documented assumptions regarding enterprise procurement velocity and healthcare regulatory enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
On-Shelf Availability Solutions Market
Digital Solutions
Application Modernization Services Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Mobile Marketing Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
South Korea Cloud OSS BSS Market