
 Sterile Rubber Stopper Market | 2026-2036
Sterile Rubber Stopper Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Rubber Stopper Market Analytics
The capital-intensity divergence between fully integrated compounders and component-only molders is rotating competitive advantage toward in-house polymer synthesis. West Pharmaceutical Services leverages captive butyl rubber formulation to sustain margin control across North American vial closure supply. Datwyler Holding Inc. anchors European biologics demand through Swiss-based cleanroom molding infrastructure. Samsung Medical Rubber Co., Ltd. competes on cost-optimized silicone stopper volumes for Asian generic injectable producers.
Sterile rubber stoppers are elastomeric sealing components manufactured from halobutyl or silicone compounds, designed to maintain container integrity while permitting needle penetration for parenteral drug delivery; they must meet particle count, extractables, and self-sealing standards under pharmacopeial test methods. Vial stoppers dominate current volume as legacy small-molecule injectables retain substantial share, though syringe stoppers capture accelerating growth from prefilled delivery system conversions. Butyl rubber formulations occupy the mature core of material demand, while silicone variants extend into high-value biologics applications requiring reduced protein adsorption and extended shelf stability.
US FDA container closure integrity guidance, EU MDR traceability mandates, and ISO 8871 elastomeric closure standards collectively elevate barrier performance requirements and documentation burdens for market access. China's NMPA alignment with ICH Q3D elemental impurity limits further narrows acceptable material sourcing for suppliers serving multinational pharmaceutical manufacturers. Stakeholders must monitor evolving extractables testing protocols and regional pharmacopeial harmonization gaps to anticipate qualification timeline shifts and capital allocation priorities.
Market Dynamics
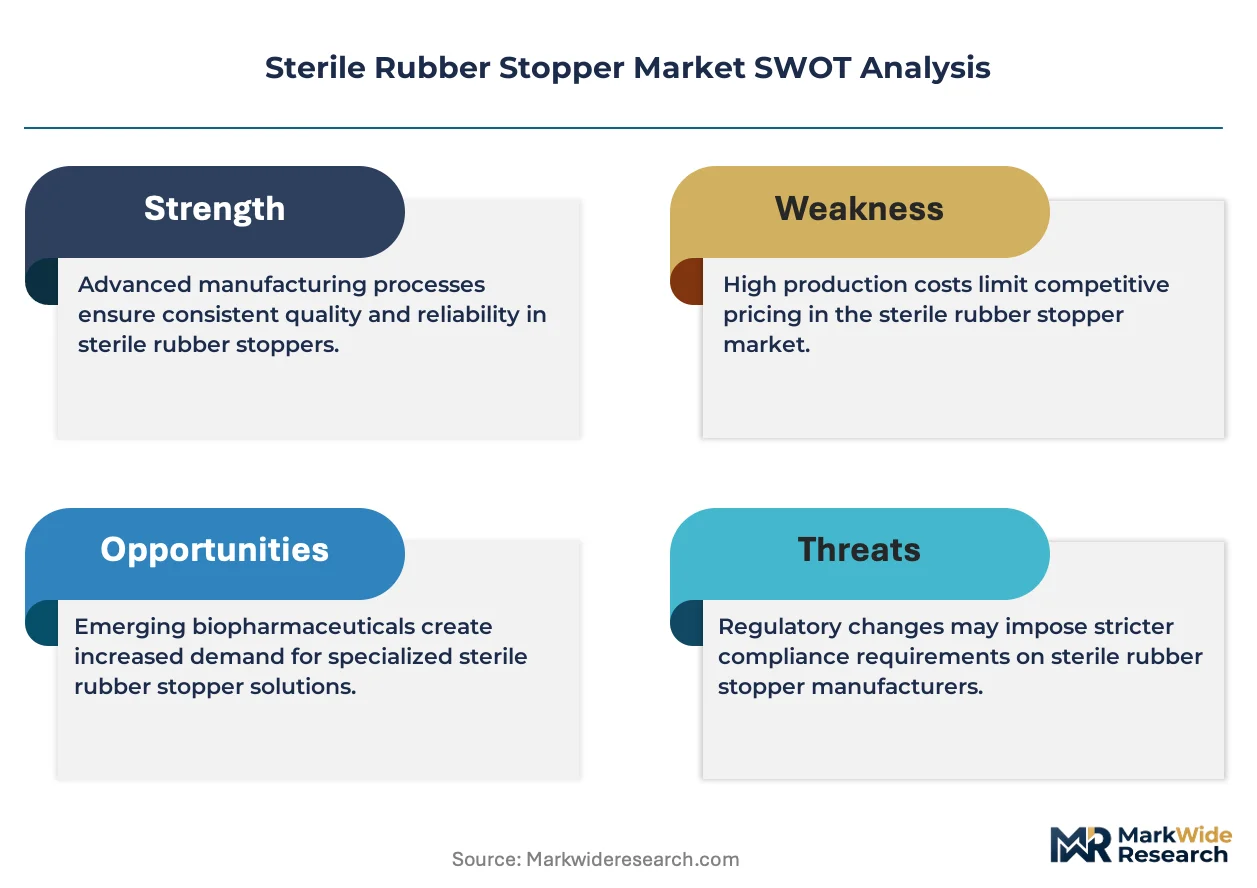
Biologics manufacturers are forcing a material specification upgrade cycle across elastomeric closure supply chains, as protein-based therapies demand stoppers with demonstrably lower extractables profiles and validated barrier performance under accelerated stability protocols.
Growth Catalysts
- US FDA container closure integrity guidance:Updated extractables and leachables testing requirements for new drug applications are compelling pharmaceutical sponsors to specify premium-grade halobutyl formulations with comprehensive documentation packages.
- Prefilled syringe system conversions:The shift from vial-to-syringe delivery formats for chronic disease therapies is expanding addressable demand for coated and laminated stopper designs with enhanced glide and reseal properties.
- German injectable manufacturing clusters:Concentrated biologics production infrastructure around Frankfurt and Munich is sustaining localized demand for high-barrier elastomeric solutions with rapid qualification turnaround.
Market Restraints
- Halobutyl rubber feedstock concentration:Four integrated petrochemical groups control the majority of pharmaceutical-grade butyl rubber polymer supply, creating input cost volatility and allocation risk during capacity tightness.
- Silicone raw material dependency:High-purity silicone monomer and catalyst supply routes concentrate in East Asian chemical manufacturing zones, exposing Western molders to freight cost swings and customs processing delays.
- ISO 8871-1 testing burden:Comprehensive physicochemical and biological reactivity testing protocols extend qualification timelines for new stopper formulations, compressing development economics for mid-volume applications.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are scaling sterile injectable capacity, creating qualification opportunities for suppliers with established US FDA and EU MDR dossiers.
- Cell and gene therapy cryogenic requirements:Ultra-low temperature storage protocols for CAR-T and viral vector products are opening specification windows for fluoropolymer-laminated stoppers with validated seal integrity at minus eighty degrees Celsius.
- EU MDR traceability mandates:Unique device identification requirements for pharmaceutical contact materials are favoring suppliers with integrated serialization and electronic batch record capabilities.
Industry Challenges
- Extractables chemist scarcity:Qualified analytical scientists capable of designing and executing comprehensive extractables studies per US FDA and EMA guidelines command premium compensation and extended recruitment cycles.
- Cleanroom molding capacity lead times:ISO Class 7 and Class 8 certified injection molding cells with validated isolator technology require eighteen-to-twenty-four-month commissioning schedules, constraining rapid demand response.
- Legacy vial format interoperability:New stopper designs must maintain dimensional compatibility with existing aluminum crimp seal tooling and glass vial neck finishes across multiple pharmaceutical packaging lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Rubber Stopper Market |
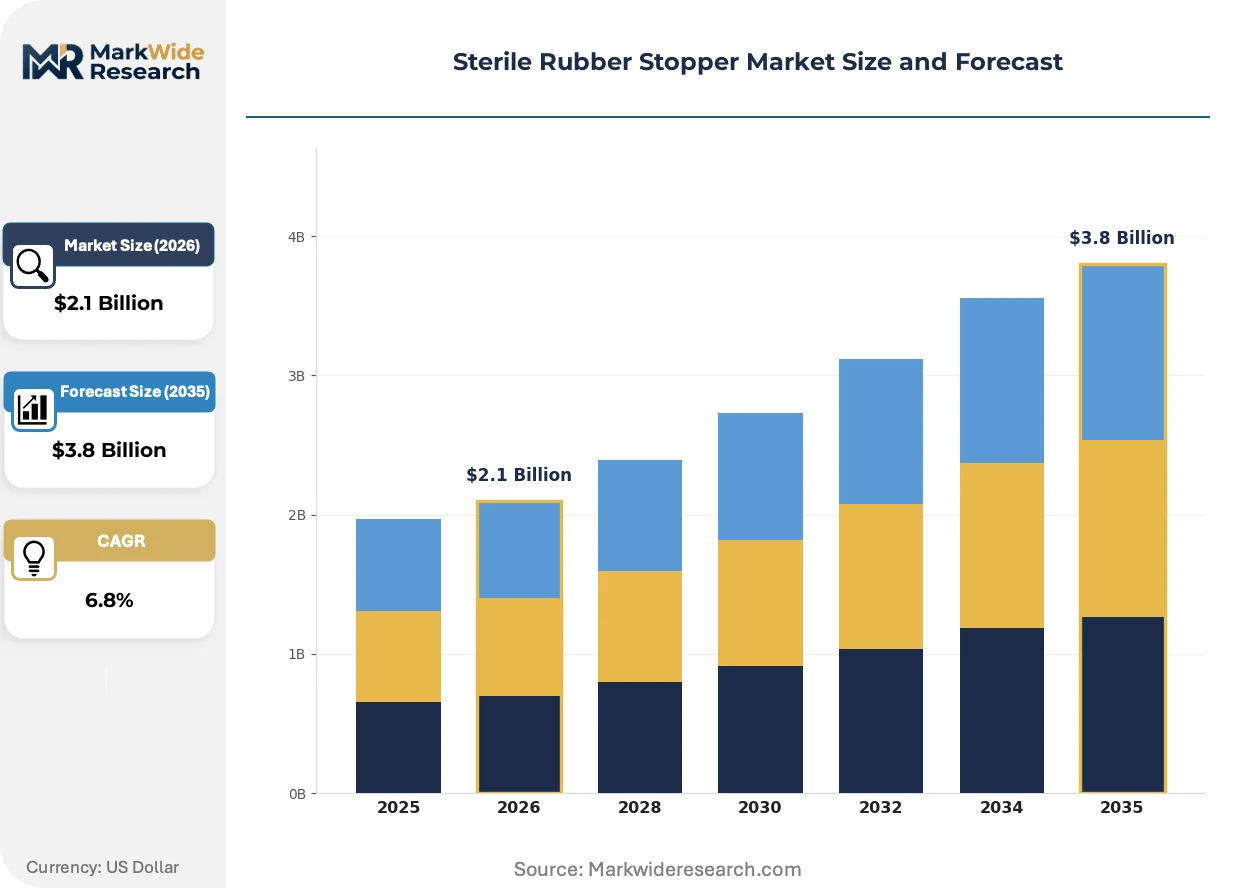
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vial Stoppers, Syringe Stoppers, Bottle Closures, Customized Stoppers Material: Natural Rubber, Silicone, Butyl Rubber, Ethylene Propylene Diene Monomer Application: Pharmaceuticals, Biologics, Nutraceuticals, Diagnostics End User: Pharmaceutical Manufacturers, Contract Manufacturing Organizations, Research Laboratories, Hospitals |
| Companies Covered | Daikyo Seiko, Ltd., Sumitomo Rubber Industries, Ltd., West Pharmaceutical Services, Inc., Hubei Huaqiang High-Tech Co., Ltd., APG Pharma, Datwyler Holding Inc., Samsung Medical Rubber Co., Ltd., Jiangsu Best Seal Co., Ltd., AptarGroup, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Rubber Stopper Market Evolving Landscape
Material science advances and regulatory documentation requirements are converging to redefine competitive advantage in elastomeric closure supply, with differentiation shifting from commodity molding toward integrated formulation and analytical services.
Fluoropolymer film lamination technology is displacing conventional uncoated halobutyl stoppers in high-value biologics applications. Regeneron, Amgen, and Roche's Genentech unit have adopted laminated closures for monoclonal antibody products with extended shelf-life requirements. This displacement is compressing margins for component-only molders lacking in-house coating capabilities while rewarding integrated suppliers with captive lamination infrastructure.
EU MDR Article 10 technical documentation requirements and EMA's updated reflection paper on extractables are forcing pharmaceutical sponsors to demand extended characterization data packages. The industrial consequence is a bifurcation between suppliers with established European notified body relationships and those facing extended qualification delays. Biologics manufacturers with EU commercialization strategies are most affected, responding by consolidating supplier panels to three or fewer qualified partners per region.
Pharmaceutical procurement functions are consolidating stopper specifications across therapeutic franchises to leverage volume scale and reduce qualification overhead. Large-cap biopharma buyers are replacing fragmented site-by-site purchasing with global category management structures and master service agreements. This concentration is most visible among US-based sponsors with centralized supply chain functions, where annual contract negotiations now span multi-year demand forecasts and dedicated capacity reservations.
Sterile Rubber Stopper Market Segmentation
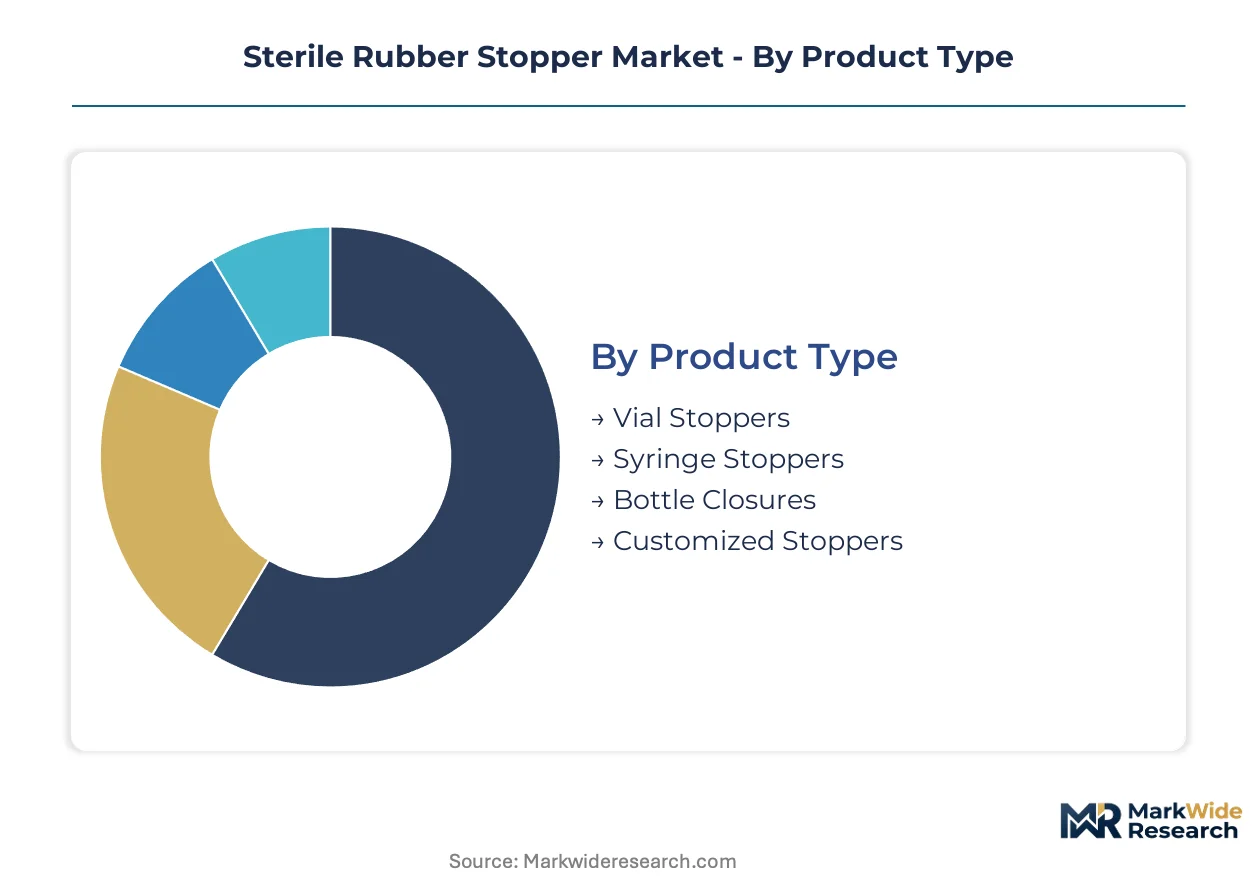
Sterile rubber stopper procurement decisions increasingly hinge on validated extractables profiles and container closure integrity documentation. Pharmaceutical sponsors segment supply sources by material chemistry, delivery format, and end-use regulatory burden to align qualification timelines with drug development milestones.
Product Type:
US FDA container closure guidance distinguishes penetration reseal requirements between vial and syringe formats, driving specification divergence.
- Vial Stoppers:Halobutyl elastomeric plugs with validated aluminum crimp seal compatibility dominate legacy small-molecule injectable packaging. Demand concentrates in German biologics manufacturing clusters around Frankfurt, where high-barrier formulations with comprehensive extractables dossiers command premium positioning.
- Syringe Stoppers:Coated or laminated designs with enhanced glide properties enable prefilled delivery system conversions for chronic disease therapies. Adoption is climbing the fastest among North American and European sponsors consolidating supplier panels under global category management structures.
- Bottle Closures:Larger-format elastomeric seals serve parenteral nutrition and bulk API storage applications with reduced barrier requirements.
- Customized Stoppers:Proprietary dimensional specifications accommodate novel container designs for cell and gene therapy cryogenic storage protocols.
Established volume favors vial stoppers; emerging adoption favors syringe stoppers.
Material:
Feedstock chemistry determines barrier performance, protein adsorption rates, and qualification pathway complexity across pharmacopeial jurisdictions.
- Butyl Rubber:Halobutyl formulations with low permeability and validated self-sealing properties anchor mature injectable applications. Four integrated petrochemical groups control pharmaceutical-grade polymer supply, concentrating input cost volatility risk.
- Silicone:Platinum-cured elastomers with reduced protein adsorption extend into high-value biologics requiring extended shelf stability. Demand concentrates in Swiss and German cleanroom molding infrastructure serving European EMA-regulated sponsors.
- Natural Rubber:Legacy formulations persist in cost-sensitive generic injectable markets with less stringent extractables requirements.
- Ethylene Propylene Diene Monomer:Alternative elastomeric chemistry offers ozone resistance for specific climatic storage conditions.
Butyl rubber retains the dominant revenue share; silicone gains share fastest in biologics-directed applications.
Application:
Protein-based therapy complexity elevates material specification requirements and documentation burdens disproportionately across therapeutic categories.
- Pharmaceuticals:Small-molecule injectables with established stability profiles tolerate broader elastomeric closure specifications. Volume concentrates in Asian generic manufacturing serving cost-optimized procurement functions.
- Biologics:Monoclonal antibodies and recombinant proteins demand laminated or coated stoppers with demonstrably lower extractables under accelerated stability protocols. Regeneron, Amgen, and Roche's Genentech unit have adopted fluoropolymer film lamination for extended shelf-life requirements.
- Nutraceuticals:Dietary supplement injectables operate under reduced regulatory scrutiny with abbreviated qualification pathways.
- Diagnostics:Analytical reagent containment requires chemical inertness rather than parenteral-grade biocompatibility certification.
Pharmaceuticals anchor current volume; biologics command the steepest expansion trajectory.
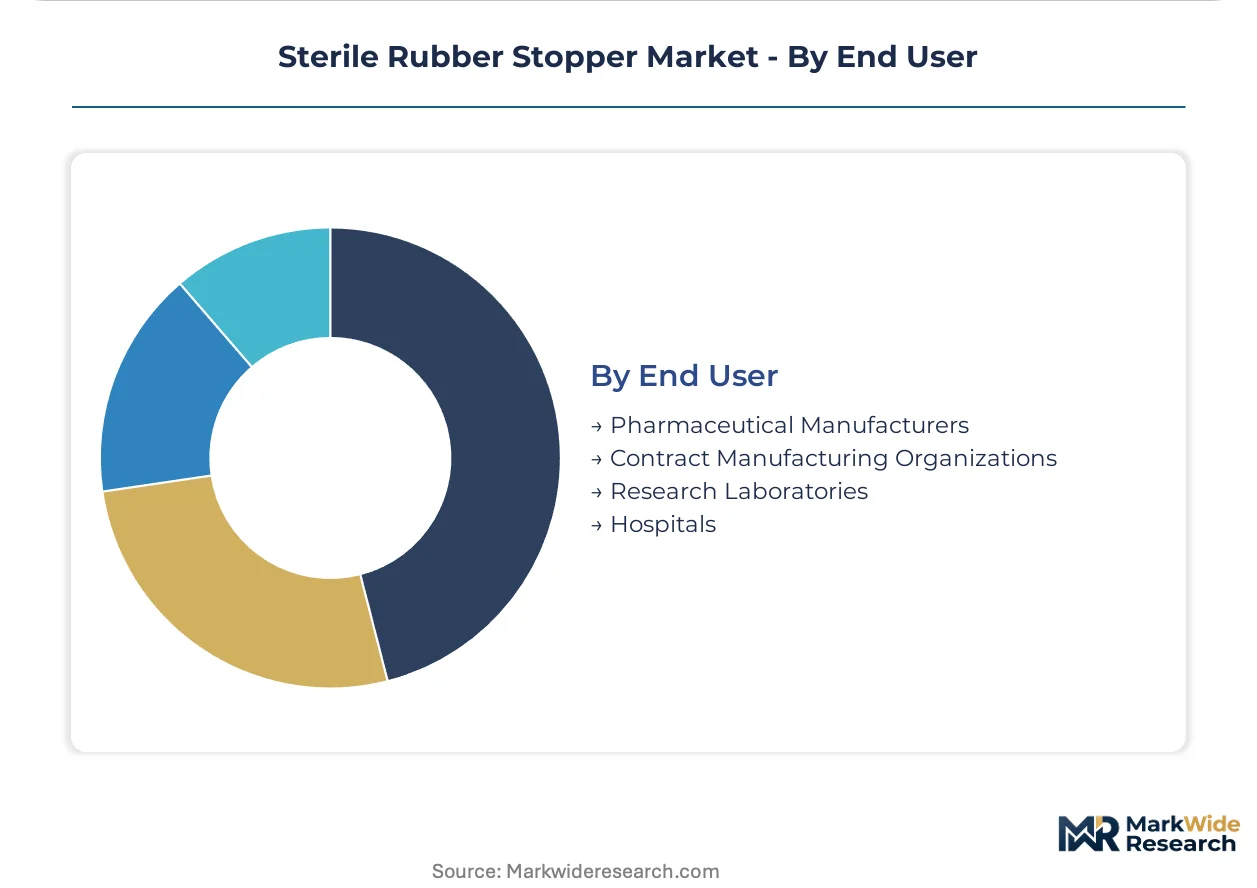
End User:
Procurement sophistication and qualification capacity vary sharply between integrated manufacturers and outsourced service providers.
- Pharmaceutical Manufacturers:Large-cap biopharma sponsors with centralized supply chain functions negotiate multi-year master service agreements with dedicated capacity reservations. US-based sponsors with global category management structures drive consolidation toward three or fewer qualified partners per region.
- Contract Manufacturing Organizations:Indian CDMOs in Hyderabad and Ahmedabad are scaling sterile injectable capacity, creating qualification opportunities for suppliers with established US FDA and EU MDR dossiers. CDMO procurement teams prioritize suppliers with rapid turnaround on technical documentation packages.
- Research Laboratories:Clinical trial material production requires flexible batch sizes with abbreviated lead times.
- Hospitals:Compounding pharmacy operations source through distributor channels with reduced direct manufacturer relationships.
Pharmaceutical manufacturers dominate contract value; contract manufacturing organizations represent the fastest-growing customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major pharmaceutical manufacturing bases. German sponsors prioritize laminated stoppers for biologics stability protocols, while Indian and Chinese generic producers optimize for halobutyl cost efficiency. US procurement functions drive supplier consolidation through multi-year master agreements.
United States
FDA container closure integrity guidance compels sponsors to specify premium-grade formulations with comprehensive extractables dossiers. Large-cap biopharma buyers in New Jersey and Massachusetts negotiate centralized category management contracts spanning dedicated capacity reservations. The Greater Boston biologics cluster sustains demand for fluoropolymer-laminated designs with validated ultra-low temperature performance.
Germany
EMA reflection papers on extractables extend qualification timelines for new stopper formulations entering European commercialization strategies. Frankfurt and Munich injectable manufacturing clusters require high-barrier elastomeric solutions with rapid technical documentation turnaround. Bavaria-based cleanroom molding infrastructure anchors continental supply for monoclonal antibody producers.
Switzerland
Swissmedic alignment with ICH Q3D elemental impurity limits narrows acceptable material sourcing for multinational pharmaceutical manufacturers. Basel and Zurich biologics production facilities specify platinum-cured silicone variants with reduced protein adsorption profiles. The country's pharmaceutical contact materials sector maintains integrated serialization capabilities for EU MDR traceability compliance.
India
CDSCO harmonization with US FDA standards accelerates qualification pathways for export-oriented sterile injectable producers. Hyderabad and Ahmedabad contract manufacturing organizations scale capacity, creating demand for suppliers with established FDA and EMA dossiers. Gujarat-based generic pharmaceutical clusters prioritize cost-optimized procurement through consolidated supplier panels.
China
NMPA alignment with ICH Q3D limits constrains pharmaceutical-grade butyl rubber polymer sourcing for domestic molders. Yangtze River Delta pharmaceutical packaging manufacturers expand silicone stopper volumes for regional biologics sponsors. Shanghai-based producers face freight cost volatility from East Asian high-purity silicone monomer supply concentration.
Sterile Rubber Stopper Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in sterile rubber stopper supply. Compounders with captive polymer formulation control margin structures across North American and European demand, while component-only molders compete on volume scale and qualification velocity. Two strategic archetypes dominate: integrated formulation-to-component suppliers with in-house lamination infrastructure, and regional molders serving cost-optimized generic markets. Competitive moves concentrate on cleanroom capacity expansion and extractables testing service integration.
Within the integrated tier, West Pharmaceutical Services exemplifies North American compounders leveraging captive butyl rubber production. Datwyler Holding Inc. occupies a position among Swiss-based suppliers anchoring European biologics demand through cleanroom molding infrastructure. Samsung Medical Rubber Co., Ltd. represents East Asian volume competitors serving generic injectable producers across Asia-Pacific markets.
| Leading Market Players |
|---|
| Daikyo Seiko, Ltd. |
| Sumitomo Rubber Industries, Ltd. |
| West Pharmaceutical Services, Inc. |
| Hubei Huaqiang High-Tech Co., Ltd. |
| APG Pharma |
| Datwyler Holding Inc. |
| Samsung Medical Rubber Co., Ltd. |
| Jiangsu Best Seal Co., Ltd. |
| AptarGroup, Inc. |
| Others |
Value Network & Pricing Analysis
Cleanroom molding capacity utilization above eighty percent in German and Swiss facilities creates asymmetric pricing power for integrated compounders with captive polymer synthesis. Scale concentration among four halobutyl rubber producers anchors price floors for pharmaceutical-grade formulations, while mid-volume molders absorb margin compression from extended ISO 8871-1 qualification timelines.
Pricing Analysis
After-sales revenue from extractables testing services and dedicated technical documentation packages drives lifetime value for integrated suppliers. Three-tier pricing structure across premium, standard, and economy levels separates fluoropolymer-laminated biologics stoppers from uncoated halobutyl vial closures and natural rubber generic formats. Pricing pressure stems from Indian CDMO procurement teams consolidating supplier panels around cost-optimized halobutyl volumes. Contract manufacturing organizations exhibit highest price sensitivity; large-cap biopharma sponsors with multi-year master service agreements demonstrate lowest sensitivity due to dedicated capacity reservation requirements.
Supply Chain Analysis
Germany and Switzerland anchor high-barrier elastomeric closure production for European biologics sponsors, while China and South Korea feed cost-optimized silicone stopper volumes for Asian generic markets. Pharmaceutical-grade butyl rubber polymer draws from integrated petrochemical groups in the United States and Western Europe; high-purity silicone monomer sources concentrate in East Asian chemical manufacturing zones. Single-source vulnerability around platinum-cured silicone catalyst supply exposes Western molders to freight cost swings and customs processing delays. Distribution runs through direct manufacturer relationships with large-cap biopharma sponsors and consolidated supplier panels serving contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologics-directed material specification upgrades represent early-cycle expansion, propelled by protein-based therapy adoption forcing validated extractables profiles across container closure supply chains.
For Market Incumbents: Consolidate supplier panel positions by expanding captive fluoropolymer lamination infrastructure and securing rapid EU MDR technical documentation turnaround capabilities. Emerging Asian molders with cost-optimized silicone volumes threaten margin structures in generic injectable segments; vertical integration into pharmaceutical-grade halobutyl polymer synthesis defends pricing power. For New Entrants and Emerging Players: Anchor in Indian CDMO qualification opportunities where Hyderabad and Ahmedabad capacity expansion outpaces established supplier documentation velocity. Cell and gene therapy cryogenic storage protocols offer the most penetrable specification window; partner with Basel or Zurich biologics facilities to validate fluoropolymer-laminated stopper performance at ultra-low temperatures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated compounders with captive polymer formulation and in-house extractables testing services. Long-term viability favors suppliers with established FDA and EMA dossier libraries spanning multiple pharmacopeial jurisdictions. Watch for inflection signals around EU MDR Article 10 technical documentation bottlenecks forcing sponsor consolidation toward three or fewer qualified partners per region.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 7 certified molding cells with isolator technology capture biologics qualification demand from Frankfurt and Munich clusters. |
| Backward Integration into Polymer Synthesis | Captive halobutyl rubber formulation insulates margin structures from petrochemical feedstock allocation volatility. |
| Fluoropolymer Lamination Infrastructure | In-house coating capabilities displace component-only molders for monoclonal antibody extended shelf-life requirements. |
| Extractables Testing Service Integration | Comprehensive analytical capabilities command premium positioning under FDA container closure integrity guidance. |
| EU MDR Serialization Capability Buildout | Electronic batch record systems secure traceability compliance for Swissmedic-regulated pharmaceutical contact materials. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at biologics manufacturers, procurement directors at contract development organizations, cleanroom molding operations managers, and extractables testing laboratory directors and refined through secondary validation against FDA container closure guidance documents, EMA reflection papers on extractables, ISO 8871 elastomeric closure standards, and USP physicochemical testing protocols. Bottom-up demand modeling across vial, syringe, and customized stopper formats triangulated with top-down pharmaceutical packaging expenditure analysis.
Variance decomposition across material chemistry, delivery format, therapeutic application, and end-user procurement sophistication shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume trajectories and value-per-unit escalation patterns for laminated versus uncoated formulations. Forecast inputs incorporated biologics pipeline progression rates and prefilled syringe system conversion velocities.
Material uncertainties — regulatory harmonization gaps between US FDA and EMA extractables protocols, halobutyl rubber feedstock concentration disruptions, and cleanroom molding capacity commissioning delays — sit outside the modeled envelope. Recalibration cycles align with material shifts in container closure integrity guidance revisions and pharmacopeial standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Conductive Silicone Rubber Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Snap on Rubber Stopper Market
Rubber
Acrylic Rubber Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Oil Saver Rubber Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Plastomers Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
US Nitrile Gloves Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Rubber Gloves Market
Rubber
Polyisoprene Market