
 IT As a Service Market | 2026-2036
IT As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
IT As a Service Market Outlook
Subscription-based financing and asset-light leasing models are reshaping competitive entry in the IT As a Service landscape. Amazon Web Services leverages its hyperscale infrastructure to dominate public cloud provisioning. Microsoft Corporation anchors enterprise workflows through deep integration of productivity suites with platform services. IBM Corporation specializes in hybrid cloud orchestration for regulated industries requiring data sovereignty controls.
IT As a Service denotes the delivery of information technology capabilities—spanning compute, storage, networking, and application layers—through remotely managed, metered service contracts rather than owned infrastructure. Service providers maintain multi-tenant architectures with guaranteed uptime thresholds, elastic resource allocation, and API-driven provisioning to eliminate upfront capital deployment. Infrastructure as a Service commands the largest revenue pool currently, while Platform as a Service segments attract the fastest developer adoption as enterprises modernize legacy application portfolios. Software as a Service retains the deepest margin pools where vertical-specific solutions reduce customer churn.
EU GDPR and the EU AI Act impose strict data residency and algorithmic transparency mandates that shape service architecture decisions across European deployments. The US FDA and HIPAA frameworks extend compliance burdens to healthcare-focused SaaS offerings handling protected health information. Stakeholders must monitor how fragmented sovereignty requirements across Germany, France, and India force architectural fragmentation that erodes the cost advantages of centralized cloud delivery.
Market Dynamics
Subscription-based consumption is compressing capital expenditure cycles across enterprise IT, forcing infrastructure providers to restructure revenue recognition and capacity planning around metered usage rather than perpetual licensing.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making platforms in finance and healthcare require auditable cloud infrastructure, expanding demand for sovereign-hosted IT services with embedded governance controls.
- Edge computing proliferation:Manufacturing facilities in Germany's industrial Mittelstand deploy localized compute nodes to reduce latency for predictive maintenance workloads.
- India's PLI scheme for electronics:Domestic data center construction accelerates, creating localized capacity for regional cloud service delivery.
Market Restraints
- Energy input cost volatility:Hyperscale data center operators face margin pressure from electricity price swings in European markets.
- Concentrated silicon supply:Specialized AI accelerator chip fabrication depends on Taiwan-based foundry capacity with limited geographic redundancy.
- GDPR extraterritorial friction:Cross-border data transfers to non-adequacy jurisdictions impose architectural fragmentation costs.
Strategic Opportunities
- Brazil's underpenetrated mid-market:ANVISA-regulated pharmaceutical manufacturers seek compliant SaaS alternatives to on-premise legacy systems.
- Convergence of quantum-safe cryptography:Financial services institutions in Switzerland pilot post-quantum key distribution integrated with existing cloud identity frameworks.
- Japan's METI carbon accounting rules:Mandatory Scope 3 emissions disclosure drives demand for cloud-based sustainability measurement tools.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Enterprises struggle to recruit engineers proficient in Kubernetes management across heterogeneous provider environments.
- HIPAA compliance timeline compression:Healthcare SaaS vendors face extended security audit cycles when handling protected health information across state jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT As a Service Market |
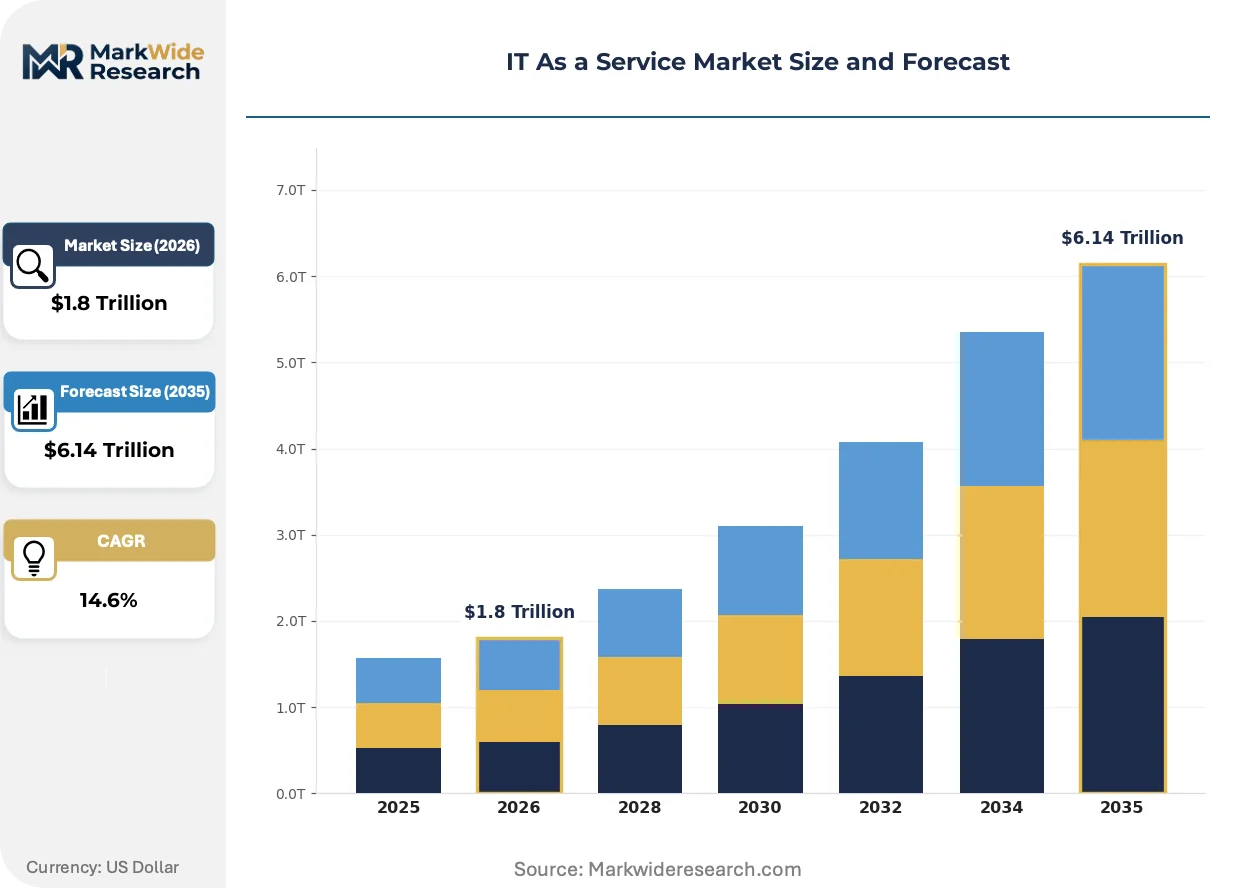
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $6.14 Trillion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Network as a Service Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User: SMEs, Large Enterprises, Government, Educational Institutions Pricing Model: Subscription-Based, Pay-Per-Use, Freemium, Tiered Pricing |
| Companies Covered | IBM Corporation, Amazon Web Services, Microsoft Corporation, Oracle Corporation, Accenture, Cisco Systems, Google, Infosys Limited, Capgemini SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT As a Service Market Strategic Shifts
Artificial intelligence workload optimization is restructuring how compute resources are provisioned, priced, and consumed across enterprise and public sector deployments.
Containerized microservices architecture is hybridizing traditional monolithic application portfolios, enabling financial services firms in Singapore to migrate core banking systems without wholesale replacement. Developers deploy serverless functions alongside retained mainframe connectivity. This hybridizing approach compresses modernization timelines while preserving regulatory audit trails.
CSRD sustainability disclosure requirements in the European Union mandate granular carbon footprint reporting for cloud service consumption. Large enterprises must now account for Scope 3 emissions from IT infrastructure providers. Data center operators in France and the Netherlands respond by publishing real-time power usage effectiveness metrics and renewable energy certificates.
Consumption-based pricing models are displacing committed-use contracts among mid-sized software vendors. Buyers in Australia's healthcare sector now prefer month-to-metered arrangements over annual subscriptions. This flexibility accelerates vendor switching but demands more sophisticated customer success functions to reduce churn.
IT As a Service Market Segmentation
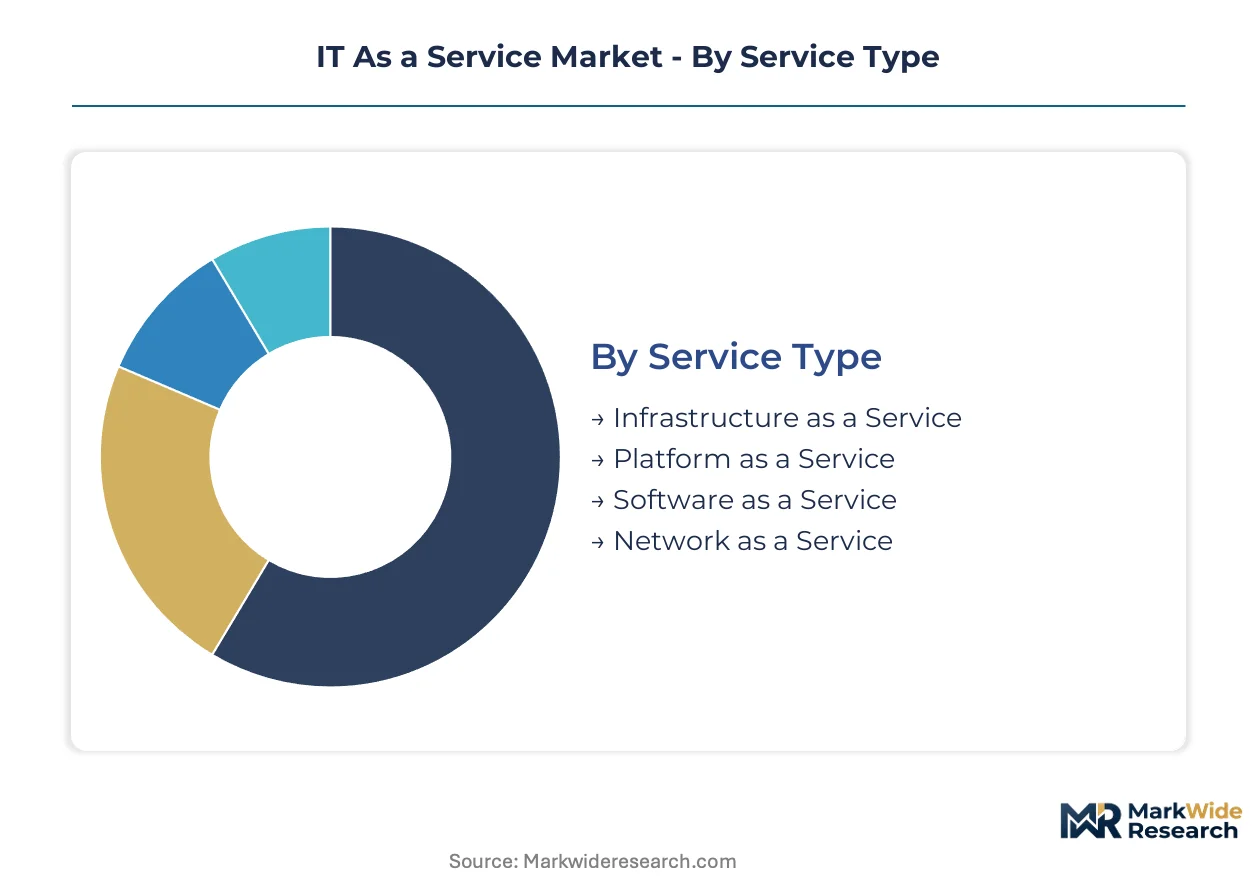
Segmentation in IT As a Service reveals how service intensity, deployment complexity, and customer scale create distinct operational requirements. Providers configure support structures, compliance frameworks, and pricing mechanics differently across each dimension. Understanding these divides clarifies where capital deployment and technical specialization yield competitive returns.
Service Type:
After-sales service intensity varies sharply across service layers, with infrastructure offerings demanding 24/7 technical response while software tiers emphasize customer success and feature onboarding.
- Infrastructure as a Service:Bare-metal compute, storage, and networking resources delivered through virtualized abstraction layers with API-driven provisioning. Demand concentrates among Germany's industrial Mittelstand manufacturers seeking scalable capacity without data center construction, driven by EU AI Act requirements for auditable infrastructure in automated decision-making systems.
- Platform as a Service:Managed runtime environments, middleware, and development toolchains that abstract infrastructure management from application deployment. Healthcare providers in the United States expanding cloud-based electronic health record systems anchor consumption, constrained by HIPAA audit timelines that extend security validation cycles.
- Software as a Service:End-user applications delivered through web interfaces with multi-tenant architectures and automatic updates.
- Network as a Service:Software-defined connectivity with elastic bandwidth allocation and zero-touch provisioning capabilities.
By volume, Infrastructure as a Service leads. By growth pace, Platform as a Service is ahead.
Deployment Model:
Cost tier differentiation separates deployment architectures, with public configurations minimizing upfront commitment while private and hybrid alternatives command premium positioning for sovereignty-sensitive workloads.
- Public Cloud:Shared infrastructure with resource pooling across untrusted tenants and utility-grade pricing. Financial services institutions in Switzerland pilot quantum-safe cryptography integration within public identity frameworks, expanding the addressable market for standardized security tooling.
- Hybrid Cloud:Orchestrated workloads spanning on-premise infrastructure and public capacity with unified management planes. Manufacturing facilities across Germany deploy localized compute nodes for predictive maintenance, balancing edge latency requirements with centralized analytics.
- Private Cloud:Dedicated single-tenant environments with customized hardware and isolated network segments.
- Community Cloud:Collaborative infrastructure serving specific industry verticals or regulatory cohorts with shared compliance frameworks.
By installed base, Public Cloud dominates. By expansion trajectory, Hybrid Cloud is climbing the fastest.
End User:
Customer type determines contract structure, with large enterprises negotiating committed-use agreements while smaller entities favor consumption flexibility and reduced procurement friction.
- SMEs:Organizations with limited IT staff seeking outsourced expertise and predictable operational expenditure. Mid-sized manufacturers throughout Germany's industrial Mittelstand prefer asset-light leasing to preserve capital for core production equipment, accelerating subscription-based financing adoption.
- Large Enterprises:Complex organizations with legacy integration requirements and multi-jurisdictional compliance obligations. Pharmaceutical manufacturers in Brazil under ANVISA jurisdiction seek compliant SaaS alternatives to on-premise legacy systems, creating substitution demand.
- Government:Public sector entities with procurement regulations and data sovereignty mandates.
- Educational Institutions:Universities and research organizations with variable compute demand patterns and grant-funded budgeting cycles.
By revenue concentration, Large Enterprises lead. By contract velocity, SMEs are gaining share fastest.
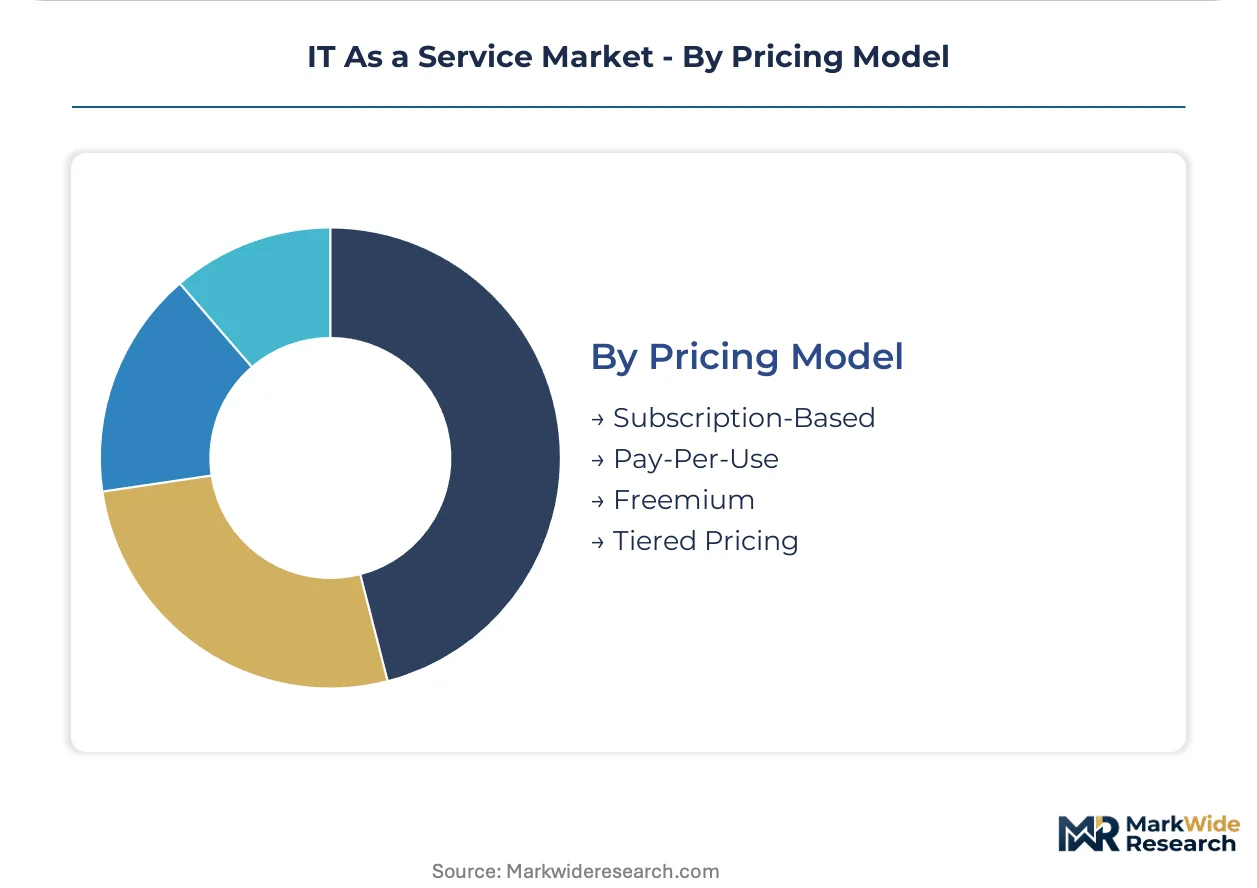
Pricing Model:
Margin structure varies across pricing architectures, with subscription models capturing predictable recurring revenue while usage-based alternatives sacrifice predictability for customer acquisition efficiency.
- Subscription-Based:Fixed recurring fees for defined capacity tiers with annual or multi-year commitment terms. Australia's healthcare sector demonstrates preference for month-to-metered arrangements over annual subscriptions, compressing vendor switching costs and elevating customer success function importance.
- Pay-Per-Use:Metered consumption with granular resource tracking and zero minimum commitments. Mid-sized software vendors increasingly displace committed-use contracts with this flexibility, though churn management complexity rises proportionally.
- Freemium:Tiered access with no-cost entry levels and feature-gated conversion pathways.
- Tiered Pricing:Discrete service bundles with differentiated performance, support, and compliance feature sets.
By revenue stability, Subscription-Based leads. By customer acquisition efficiency, Pay-Per-Use shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics accelerates domestic data center construction, creating localized capacity for regional cloud service delivery. Germany's industrial Mittelstand drives sovereign-hosted infrastructure demand under tightening EU AI Act compliance mandates. Brazil's underpenetrated mid-market presents substitution opportunities for regulated pharmaceutical manufacturers.
United States
Healthcare providers expanding cloud-based electronic health record systems anchor Platform as a Service consumption. HIPAA frameworks extend compliance burdens to healthcare-focused SaaS offerings handling protected health information. The FDA regulates automated decision-making platforms in medical devices, driving demand for auditable infrastructure in Boston's health-tech cluster.
Germany
Mid-sized manufacturers in the industrial Mittelstand seek scalable IT without capital expenditure, accelerating subscription-based financing adoption. The EU AI Act imposes strict algorithmic transparency mandates on automated decision-making systems. Manufacturing facilities across Baden-Württemberg deploy localized edge compute nodes for predictive maintenance workloads.
India
Domestic data center construction accelerates under the PLI scheme for electronics, creating regional cloud delivery capacity. The RBI and SEBI impose data localization requirements on financial services infrastructure. Telangana and Karnataka host concentrated developer talent pools supporting Platform as a Service adoption among domestic software vendors.
Brazil
ANVISA-regulated pharmaceutical manufacturers seek compliant SaaS alternatives to on-premise legacy systems. The national pharmaceutical regulator mandates audit trails for production systems handling sensitive manufacturing data. São Paulo's industrial corridor concentrates demand from mid-market manufacturers modernizing quality management infrastructure.
Japan
METI carbon accounting rules mandate Scope 3 emissions disclosure, driving demand for cloud-based sustainability measurement tools. The central bank's digital currency pilot programs require sovereign-hosted transaction infrastructure. Tokyo's financial district hosts pilot programs for quantum-safe cryptography integration with existing cloud identity frameworks.
IT As a Service Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Hyperscale infrastructure operators dominate public cloud provisioning through utility-grade pricing and elastic resource allocation. Specialist systems integrators anchor hybrid cloud orchestration for regulated industries requiring data sovereignty controls. Competitive moves concentrate on strategic partnerships with industrial automation vendors and geographic expansion into underpenetrated mid-markets.
Within the hyperscale infrastructure tier, Amazon Web Services and Microsoft Corporation exemplify channel-controlling archetypes leveraging global data center footprints. IBM Corporation occupies a position among hybrid cloud specialists addressing regulated verticals with embedded governance controls. These three anchors represent distinct competitive vectors: utility-scale provisioning, enterprise workflow integration, and sovereign-compliant orchestration.
| Leading Market Players |
|---|
| IBM Corporation |
| Amazon Web Services |
| Microsoft Corporation |
| Oracle Corporation |
| Accenture |
| Cisco Systems |
| Infosys Limited |
| Capgemini SE |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Taiwan-based foundry capacity for AI accelerator chips compresses margin buffers across infrastructure tiers while forcing architectural fragmentation into sovereign-hosted alternatives. This chokepoint simultaneously widens pricing spreads between utility-grade public cloud and compliance-premium sovereign deployments while reshaping procurement patterns toward diversified supplier portfolios.
Pricing Analysis
Certification level creates the primary spread across IT As a Service tiers, with EU AI Act-compliant sovereign-hosted infrastructure commanding substantial premiums over standard public cloud offerings. Subscription-based models dominate enterprise procurement, though pay-per-use arrangements accelerate among Australia's healthcare providers seeking month-to-metered flexibility. Cost compression in utility-grade tiers intensifies as hyperscalers compete on elastic resource allocation, while HIPAA-regulated healthcare SaaS exhibits lowest price sensitivity due to extended security audit requirements.
Supply Chain Analysis
Upstream semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with specialized AI accelerator production exhibiting particularly narrow geographic diversity. Critical inputs span silicon wafers, advanced packaging substrates, and rare earth elements for magnetic components. Tariff exposure on Chinese-manufactured networking equipment elevates supply risk for European data center operators. Distribution runs through hyperscale direct-provision channels alongside specialist systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across compliance jurisdictions creates niche opportunities for specialized orchestration providers as sovereignty mandates multiply deployment architectures beyond centralized cloud economics.
For Market Incumbents: Harden hybrid cloud orchestration capabilities against emerging sovereign-hosting specialists by embedding automated governance controls that satisfy EU AI Act audit requirements. Prioritize backward integration into edge compute hardware for Germany's industrial Mittelstand predictive maintenance workloads. Defensive patent positioning around quantum-safe cryptography integration protects against fintech-focused challengers. For New Entrants and Emerging Players: Pursue underpenetrated mid-market pharmaceutical manufacturers in Brazil's ANVISA-regulated corridor with compliant quality management SaaS replacing legacy on-premise systems. Target India's domestic data center construction wave under PLI scheme incentives for localized platform service delivery. Lead with consumption-based pricing and rapid implementation timelines to bypass incumbent procurement friction. For Investors and Strategic Acquirers: The EU AI Act's full enforcement reshapes the acquisition landscape toward sovereign-compliant orchestration specialists with embedded governance tooling. Five-to-ten-year viability favors hybrid cloud integrators possessing multi-jurisdictional compliance expertise rather than pure infrastructure plays. Monitor ANVISA regulatory harmonization progress as signal for Brazilian pharmaceutical SaaS consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act compliance mandates create defensive moats for early-certified providers in financial services. |
| Edge Compute Partnership | Industrial automation vendor alliances capture predictive maintenance workloads across Germany's Mittelstand. |
| Quantum-Safe Cryptography Integration | Switzerland's financial institutions pilot post-quantum key distribution within existing identity frameworks. |
| Platform Integration | Electronic health record system connectivity anchors healthcare provider retention against vendor switching. |
| Geographic Expansion | India's PLI-accelerated data center construction enables regional service delivery without cross-border latency. |
Study Parameters
Cross-validation between hyperscaler capex disclosures and enterprise IT procurement surveys anchors the qualitative findings on deployment model preferences. Primary interviews with cloud architects, compliance officers, platform engineers, and channel partners combine with secondary analysis of SEC filings, EU regulatory submissions, and data center development databases. Bottom-up service tier sizing and top-down macroeconomic calibration ensure consistency across the analysis window.
Calibration against historical adoption curves and regulatory implementation timelines shapes the projection framework across service type, deployment model, organization scale, and vertical industry segmentation. CAGRs derive from fitted growth models incorporating sovereign compliance cost premiums and edge compute latency requirements as industry-specific inputs throughout the modeling period.
Sensitivities concentrate around EU AI Act enforcement intensity, Taiwan semiconductor supply continuity, and energy input cost volatility in European markets. Forecasts embed assumptions on regulatory harmonization progress and hyperscaler capacity expansion cadence. Quarterly review of data center construction permits, sovereign cloud certification announcements, and foundry utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Event Apps Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Thin Client Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Change Management Software Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Graph Technology Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Cloud Based Drug Discovery Platform Market