
 Terminal Emulator Software Market | 2026-2036
Terminal Emulator Software Market Size, Share, and Industry Trends Forecast 2026-2036
Terminal Emulator Software Market Analytics
The gap between premium secure terminal emulation and commodity remote access tools is broadening as enterprise security requirements harden. Rocket Software anchors its position through deep mainframe integration and specialized host connectivity protocols. Ericom Software differentiates via browser-isolation technology that secures legacy application access without endpoint agents. VanDyke Software competes on cryptographic strength and FIPS-validated SSH implementations for regulated industries.
Terminal emulator software enables users to access and interact with remote computing systems, legacy mainframes, and network equipment through text-based command-line interfaces supporting protocols such as SSH, Telnet, and serial connections. The technology translates host data streams into visual formats while maintaining session state, serving critical functions in banking transaction processing, manufacturing floor control, and telecommunications network management. Cloud-based deployment is outpacing on-premise installation as organizations prioritize elastic capacity and reduced data center footprint. Standalone products retain dominance in high-security environments where air-gapped operation remains mandatory. The integrated segment is gaining traction among enterprises consolidating remote access, file transfer, and session management into unified platforms.
The US National Institute of Standards and Technology publishes zero-trust architecture guidelines that directly influence terminal emulator procurement specifications for federal contractors. The EU Cybersecurity Act and ENISA technical standards shape product certification requirements for vendors serving European financial and healthcare institutions. Japan's Ministry of Economy, Trade and Industry promotes secure supply chain frameworks that affect how domestic manufacturers evaluate foreign terminal emulator vendors. Stakeholders must weigh interoperability commitments against accelerating cloud migration timelines when selecting deployment architectures.
Market Dynamics
Zero-trust security architectures are forcing wholesale reconfiguration of how enterprises evaluate terminal emulator procurement, elevating cryptographic validation and session isolation above legacy connectivity metrics.
Growth Catalysts
- FIPS 140-2 Validation Mandates:US federal contractors now require FIPS-validated SSH implementations for all remote mainframe access, compressing vendor qualification timelines and disqualifying uncertified alternatives from federal procurement channels.
- Manufacturing Floor Modernization:Industrial automation networks in Germany and Japan are replacing serial-based terminal access with encrypted browser-native emulation to secure programmable logic controller programming interfaces against lateral movement attacks.
- Cloud-Native Deployment Models:Containerized terminal emulation services are displacing on-premise installations as financial services firms in New York and London prioritize elastic capacity for seasonal transaction processing peaks.
Market Restraints
- Specialized Cryptographic Talent Scarcity:FIPS validation engineering expertise concentrates among a handful of security consultancies in Maryland and Virginia, creating bottlenecks for vendors pursuing federal certification.
- Legacy Protocol Lock-In:Decades-old custom terminal emulation configurations in insurance and banking core systems resist migration without extensive regression testing, freezing procurement cycles.
- Input Cost Concentration:Commercial SSH library licensing from a dominant open-source foundation creates dependency risk for smaller terminal emulator vendors without in-house cryptographic development.
Strategic Opportunities
- Browser Isolation Convergence:Integration of remote browser isolation technology with terminal emulation is opening new deployment architectures for healthcare organizations requiring HIPAA-compliant mainframe access without endpoint agents.
- Underpenetrated Industrial Verticals:Oil and gas pipeline operators in the US Gulf Coast remain dependent on unencrypted Telnet for SCADA maintenance, representing conversion opportunity as NERC CIP standards harden.
- EU Cybersecurity Certification:The European Cybersecurity Scheme for ICT products creates preferential market access for terminal emulator vendors achieving ENISA-recognized certification ahead of mandatory procurement timelines.
Industry Challenges
- Mainframe Integration Complexity:Preserving session state across heterogeneous IBM z/OS, Unisys ClearPath, and Bull GCOS environments demands specialized protocol engineering that outpaces standard software development cycles.
- Zero-Trust Architecture Reconfiguration:Continuous verification requirements are forcing terminal emulator vendors to rebuild session management architectures around identity-aware proxies rather than traditional network perimeter assumptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terminal Emulator Software Market |
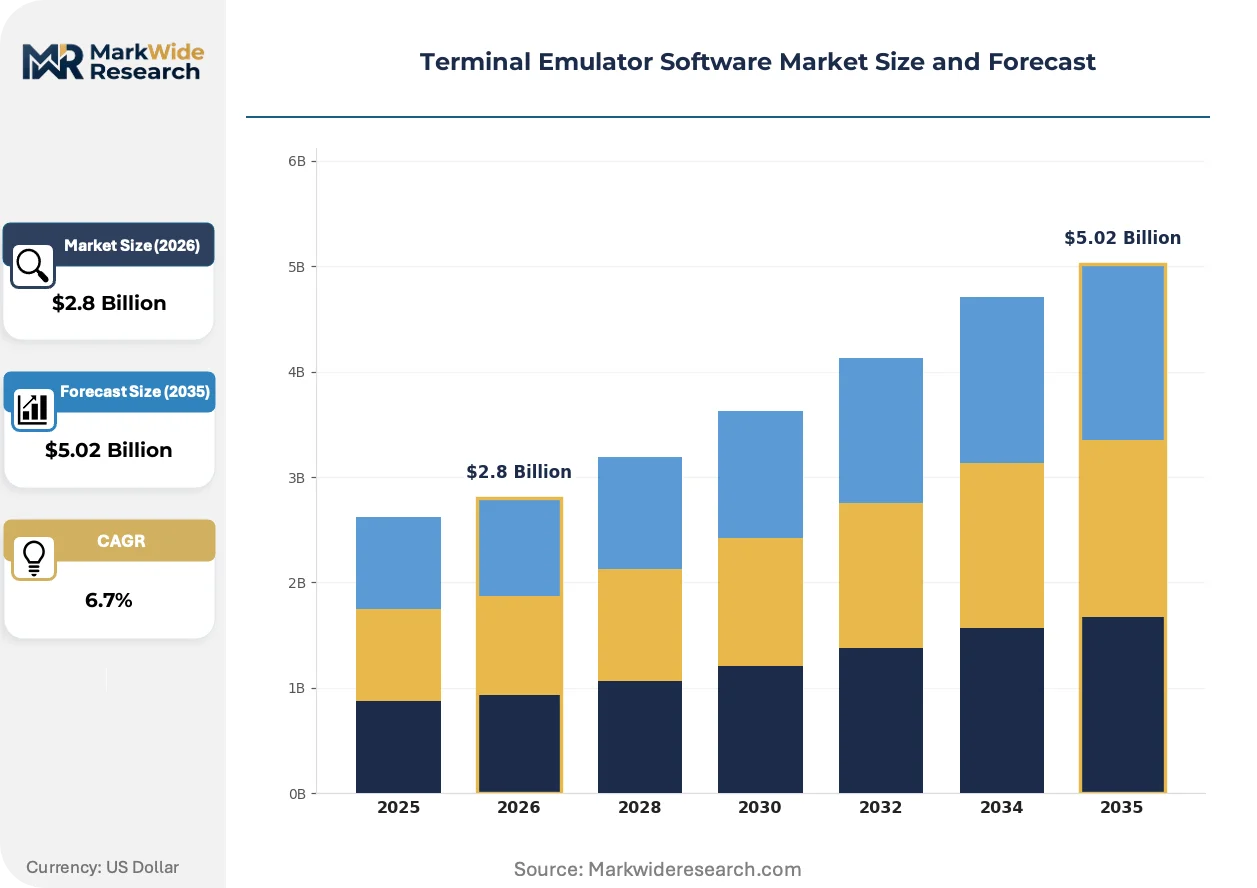
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Cloud-Based, Legacy Deployment: On-Premise, Cloud, Hybrid, SaaS User Type: Individual Developers, Enterprises, Educational Institutions, Government Operating System: Windows, macOS, Linux, Unix |
| Companies Covered | Ericom Software, Inventu Corporation, Rocket Software, HCL Software, Flynet Viewer, OpenText, StayLinked, EmTec, VanDyke Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terminal Emulator Software Market Evolving Landscape
Terminal emulator architecture is pivoting from standalone client applications toward identity-anchored, policy-enforced access layers that embed security controls directly into session orchestration.
WebAssembly-based terminal emulation is electrifying secure browser-native mainframe access by eliminating endpoint software deployment entirely. Large US healthcare systems are piloting these implementations to satisfy HIPAA technical safeguards without managing installed client software. The technology is electrifying competitive positioning by collapsing the traditional trade-off between security hardening and deployment friction.
Japan's METI secure supply chain frameworks are mandating software bill of materials disclosure for critical infrastructure vendors, including terminal emulator providers serving domestic manufacturers. This policy is compressing procurement qualification timelines as buyers demand attestation documentation before contract execution. Domestic automotive and electronics manufacturers are responding by pre-qualifying vendors with existing METI-aligned certification pathways.
Consolidated platform procurement is displacing standalone terminal emulator purchases as enterprise IT departments prioritize unified remote access, file transfer, and session management under single vendor relationships. Value-added resellers and systems integrators are capturing larger share of customer lifetime value by bundling emulation within broader zero-trust transformation contracts. This pattern is most visible among US federal contractors consolidating vendor portfolios to simplify FedRAMP authorization maintenance.
Terminal Emulator Software Market Segmentation
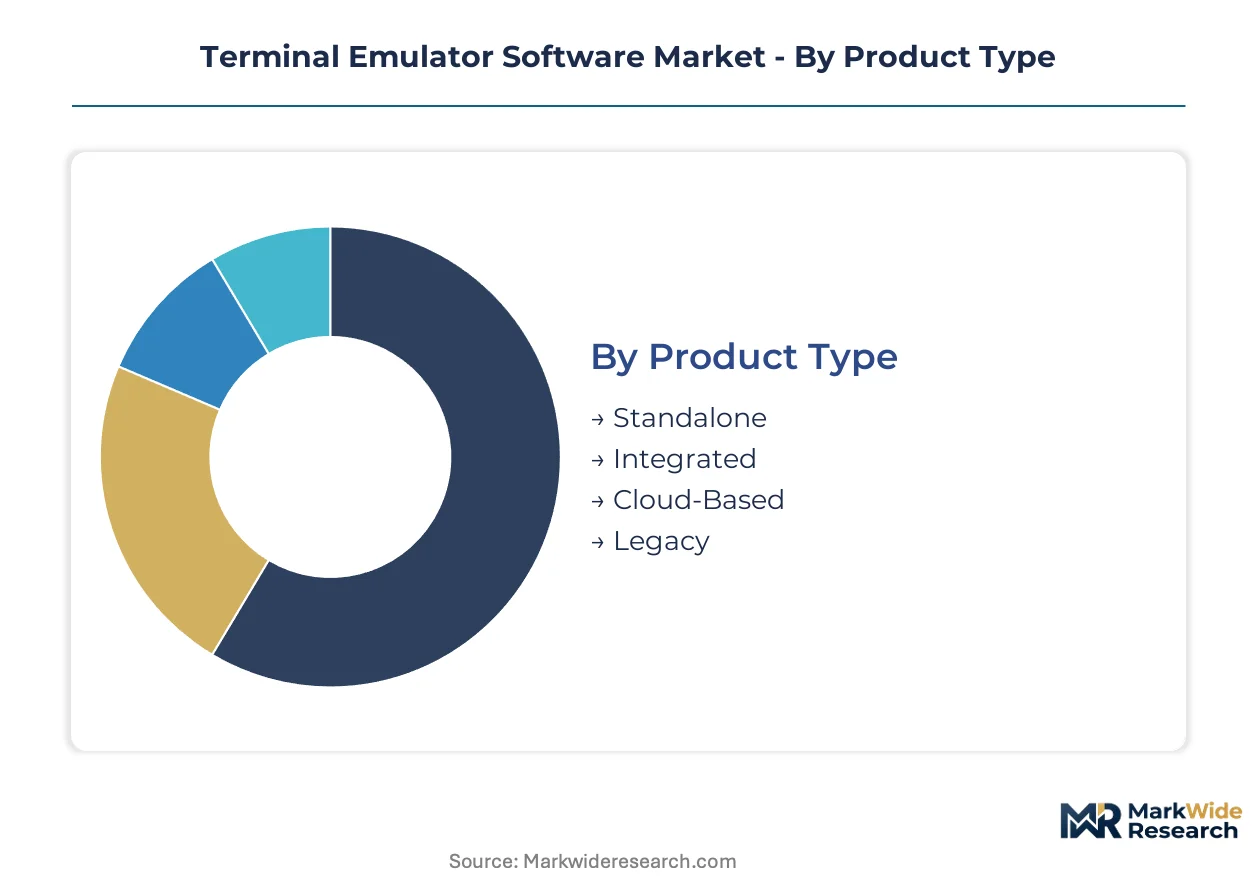
Terminal emulator software segments reflect divergent security postures and infrastructure modernization timelines across enterprise IT estates. Procurement patterns cluster around deployment flexibility and integration depth rather than raw connectivity performance.
Product Type:
Standalone products anchor air-gapped environments where endpoint isolation trumps convenience; integrated and cloud-native variants embed within broader zero-trust access layers.
- Standalone:Self-contained client applications execute entirely on local hardware without external dependencies. Financial services firms in New York maintain these deployments for trading floor workstations where network segmentation mandates offline operation. FIPS 140-2 validation requirements compress vendor qualification timelines for federal contractors.
- Integrated:Unified platforms consolidate terminal emulation with file transfer, session management, and identity federation. Large US healthcare systems pilot these implementations to satisfy HIPAA technical safeguards without managing multiple vendor relationships. Procurement concentrates among enterprises consolidating remote access infrastructure.
- Cloud-Based:Containerized services deliver browser-native emulation without endpoint installation.
- Legacy:Decades-old custom configurations persist in insurance core systems resistant to migration.
Volume placements concentrate in Standalone; the faster expansion belongs to Cloud-Based.
Deployment:
Cost tiers separate capital-intensive on-premise installations from operational expenditure models favored by seasonal transaction processors.
- On-Premise:Perpetual license deployments within customer-controlled data centers demand dedicated infrastructure and internal security operations. Manufacturing networks in Germany retain these configurations for programmable logic controller programming interfaces where latency sensitivity precludes remote hosting. Capital expenditure requirements freeze procurement cycles during budget compression.
- Cloud:Fully managed services eliminate infrastructure ownership while enabling elastic capacity scaling. Financial services firms in London prioritize these models for seasonal transaction processing peaks without permanent data center expansion. Shared responsibility frameworks complicate compliance attestation for regulated industries.
- Hybrid:Split architectures maintain sensitive workloads on-premise while bursting non-critical sessions to cloud infrastructure.
- SaaS:Subscription-native delivery abstracts all infrastructure management to vendor operations.
Revenue gravity sits with Cloud; Hybrid claims the steepest expansion trajectory as regulated industries navigate compliance boundaries.
User Type:
Customer maturity separates individual practitioners seeking basic connectivity from institutions demanding audit trails and policy enforcement.
- Individual Developers:Single-user licenses support software engineering workflows requiring remote server access and embedded system debugging. Demand concentrates among independent contractors and small development shops without centralized IT procurement. Price sensitivity drives selection toward open-source alternatives.
- Enterprises:Multi-seat deployments with centralized policy management serve thousands of concurrent users across distributed locations. Banking and telecommunications operators in Japan specify these implementations for network equipment maintenance requiring session logging and privileged access controls. Procurement cycles extend through security review and integration testing phases.
- Educational Institutions:Volume licensing agreements accommodate fluctuating student populations and research computing access.
- Government:Federal, state, and local agencies mandate certified cryptographic implementations and domestic support operations.
Contract value peaks with Enterprises; Government segments are climbing the fastest as zero-trust mandates harden procurement specifications.
Operating System:
Application footprint varies dramatically across endpoint ecosystems, with Windows dominance in enterprise desktops contrasting Unix persistence in technical computing environments.
- Windows:Dominant enterprise desktop platform supports native GUI integration and Active Directory policy enforcement. Corporate IT departments standardize on these deployments for administrative workstations requiring seamless host connectivity without compatibility layers. Volume licensing agreements anchor vendor revenue stability.
- macOS:Growing presence in creative and development organizations demands native Cocoa or Metal-optimized implementations. Technology firms in California specify these configurations for engineering teams preferring Unix-derived environments without Linux desktop friction. Apple's cryptographic API restrictions complicate FIPS validation pathways.
- Linux:Preferred platform for server administration and embedded development workflows.
- Unix:Legacy workstation environments persist in scientific computing and specialized engineering applications.
Seat count concentrates in Windows; macOS installations are gaining share fastest among technology sector adopters.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York's financial district drives concentrated demand for FIPS-validated terminal emulation as federal contractors modernize legacy mainframe access. The city's banking infrastructure anchors North American procurement volumes for secure host connectivity solutions.
United States
Federal zero-trust mandates and healthcare HIPAA compliance are accelerating browser-native terminal emulation pilots. NIST cybersecurity frameworks shape procurement specifications for contractors serving defense and intelligence agencies. Texas energy corridor operators are replacing unencrypted Telnet for pipeline SCADA maintenance as NERC CIP standards harden.
Germany
Industrial automation networks demand encrypted browser-native emulation for programmable logic controller programming interfaces. EU Cybersecurity Act certification requirements compress vendor qualification timelines for financial and healthcare institutions. Bavarian automotive manufacturers are pre-qualifying vendors with established ENISA-aligned certification pathways.
Japan
Domestic manufacturers evaluate foreign terminal emulator vendors against METI secure supply chain frameworks. Software bill of materials disclosure mandates compress procurement cycles for critical infrastructure buyers. Kanto region electronics producers are consolidating vendor portfolios to simplify compliance attestation.
United Kingdom
London financial services firms prioritize cloud-native deployment models for seasonal transaction processing capacity. Financial Conduct Authority operational resilience requirements influence terminal emulator procurement specifications. The city's banking technology clusters are phasing out on-premise legacy infrastructure in favor of elastic containerized services.
Terminal Emulator Software Market Competitive Landscape
Capital-heavy mainframe integration specialists compete with asset-light browser-isolation innovators for enterprise terminal emulator contracts. The vendor base stratifies between deep protocol engineering shops and modern zero-trust access layer providers. Three archetypes dominate: legacy host connectivity specialists, browser-native security platforms, and consolidated unified access vendors. Competitive intensity centers on FIPS certification velocity and cloud-native architecture partnerships rather than raw connectivity performance.
Within the legacy integration tier, Rocket Software anchors deep mainframe protocol expertise while VanDyke Software exemplifies cryptographic specialization for regulated industries. Ericom Software occupies the browser-isolation convergence position. These three represent distinct strategic postures: mainframe-native engineering depth, federal-grade cryptographic validation, and agentless security architecture respectively.
| Leading Market Players |
|---|
| Ericom Software |
| Inventu Corporation |
| Rocket Software |
| HCL Software |
| Flynet Viewer |
| OpenText |
| StayLinked |
| EmTec |
| VanDyke Software |
| Others |
Value Network & Pricing Analysis
Commercial SSH library licensing fees from the dominant open-source foundation cascade through terminal emulator vendor cost structures, compressing margins for smaller players without in-house cryptographic development while enabling tiered pricing stratification across FIPS-certified premium offerings and uncertified economy alternatives.
Pricing Analysis
Value-based pricing anchored to guaranteed session uptime and compliance attestation dominates enterprise procurement, with FIPS 140-2 validated implementations commanding substantial premiums over standard encrypted connectivity. Certification grade and volume scale drive price differentiation, with federal contractors absorbing higher per-seat costs for validated cryptographic modules. Pricing pressure stems from open-source alternatives commoditizing basic SSH functionality. Individual developers exhibit highest price sensitivity, while regulated financial institutions demonstrate lowest elasticity.
Supply Chain Analysis
FIPS validation engineering expertise concentrates among security consultancies in Maryland and Virginia, creating qualification bottlenecks that gate vendor market entry and sustain pricing power for certified incumbents. Supply draws from cryptographic library developers in the United States, Germany, and Israel, with hardware security module manufacturers in the Netherlands and Taiwan feeding authentication infrastructure. Single-source vulnerability in commercial SSH library licensing represents structural supply chain risk. Distribution runs through value-added resellers and systems integrators bundling emulation within zero-trust transformation contracts.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FIPS validation engineering capacity constraints prop pricing power for certified vendors, as federal procurement mandates compress qualification timelines and disqualify uncertified alternatives from contracting channels.
For Market Incumbents: Anchor defensive positioning through accelerated FIPS 140-3 recertification investment ahead of mandate transitions, while deepening mainframe protocol integration to resist browser-native substitution threats. Pursue backward integration into cryptographic library development to reduce licensing dependency and capture margin compression from open-source commoditization. For New Entrants and Emerging Players: Begin with oil and gas pipeline operators along the US Gulf Coast, where unencrypted Telnet dependence and impending NERC CIP enforcement create immediate conversion opportunity for encrypted browser-native alternatives. Target healthcare systems piloting WebAssembly-based implementations to satisfy HIPAA technical safeguards without endpoint agents. For Investors and Strategic Acquirers: Distressed-cycle entries favor browser-isolation technology specialists with established ENISA-aligned certification pathways in Germany, as EU Cybersecurity Act mandatory procurement timelines approach. Watch for FIPS validation backlog clearance velocity as inflection indicator for vendor qualification capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FIPS 140-3 Recertification Investment | Accelerated validation timelines capture federal contractor procurement before mandate disqualification. |
| WebAssembly-Based Product Launch | Browser-native architecture eliminates endpoint deployment friction for HIPAA-compliant healthcare access. |
| Backward Integration into Cryptographic Libraries | In-house SSH development reduces licensing dependency and margin exposure to open-source foundation pricing. |
| ENISA-Aligned Certification Pathway | European Cybersecurity Scheme recognition secures preferential access to EU financial and healthcare procurement. |
| Strategic Partnership with Industrial Automation OEMs | Embedded emulation for programmable logic controller interfaces captures manufacturing floor modernization budgets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with chief information security officers, federal procurement officers, healthcare IT directors, and mainframe operations managers. NIST cybersecurity framework documentation, ENISA technical standards, and METI supply chain disclosure requirements provided regulatory validation. SEC 10-K filings from publicly traded vendors and FedRAMP authorization databases supplied financial and compliance metrics. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Granularity-level modeling deployed deployment mode, organization size, vertical industry, and integration complexity as primary segmentation dimensions across the projection horizon. CAGRs derived from fitted growth curves applied to validated baseline estimates, with cross-reference to hyperscaler terminal services capex disclosures and federal IT modernization budget allocations. Elastic capacity scaling patterns in financial services transaction processing informed cloud-native adoption trajectory assumptions.
Regulatory mandate delay, FIPS validation backlog extension, and zero-trust architecture implementation slowdown are the dominant revision risks to forecast outputs. A model refresh is warranted upon material change in federal procurement specification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Configuration Management (CM) Tools Market
Software & Services
HCS Software and Services Market
Software & Services
Braking Systems Software Market
Software & Services
Salesforce Services Market
Software & Services
Dealer Management System Market
Software & Services
RIP Color Management Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Enterprise-Grade Saas Market
Software & Services
Smartphone Music Production Software Market
Software & Services
Online Paint Editor App Market
Software & Services
Batch Management Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Global Presentation Software Market
Software & Services
Load Balancing Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Content Marketing Software Market