
 Global Saas Backup Software Market | 2026-2036
Global Saas Backup Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Saas Backup Software Market Foresight
Shift from in-house tape backup systems to outsourced SaaS recovery platforms is hardening as the dominant procurement pattern among mid-market and enterprise buyers. Veeam leverages its hybrid-cloud architecture to anchor positions in organizations running mixed VMware and Microsoft 365 environments. Druva competes through a fully managed, agentless design that eliminates on-premises hardware overhead. Acronis extends its footprint by integrating cyber protection layers directly into backup workflows, blurring traditional boundaries between security and data resilience.
Global SaaS backup software comprises cloud-native applications that automate the replication, encryption, and restoration of data residing in third-party SaaS platforms such as Salesforce, Google Workspace, and Microsoft 365, typically operating on 15-minute to 24-hour recovery point objectives depending on service tier. The technology serves commercial and institutional users by ensuring business continuity when SaaS vendors experience outages, ransomware attacks, or accidental data deletion by administrators. Cloud-to-cloud backup solutions within the Solution Type segment are capturing the fastest growth as organizations recognize that native SaaS vendor snapshots do not satisfy enterprise retention or granular recovery requirements. Subscription-Based pricing models dominate revenue flows in the Pricing Model category, though Usage-Based arrangements are gaining traction among seasonal businesses and development-stage SaaS companies seeking variable cost structures.
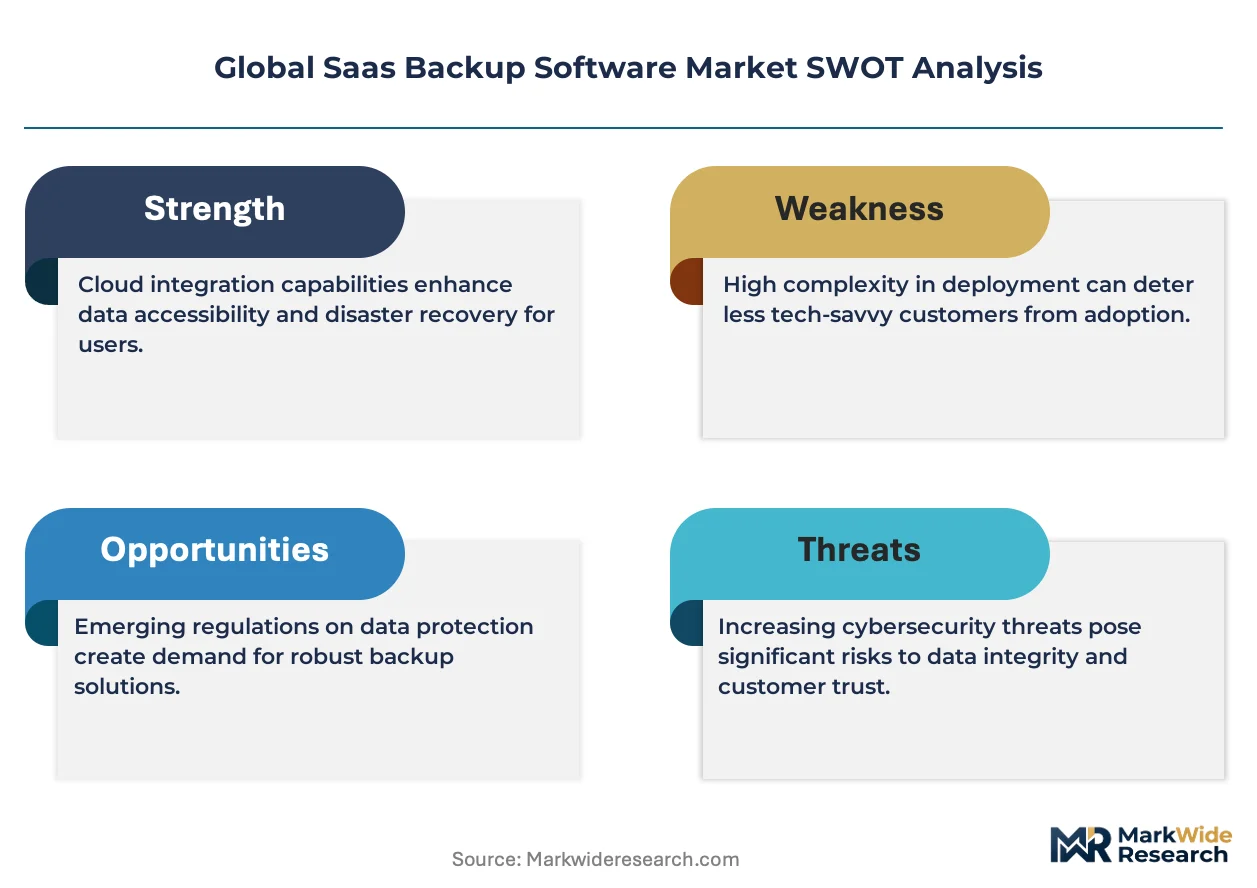
FDA 21 CFR Part 11 guidelines shape backup requirements for US life sciences firms, mandating audit trails and immutable records that SaaS backup vendors must architect into their platforms. GDPR and the EU AI Act impose cross-border data residency and encryption standards that European buyers evaluate during vendor selection, directly filtering which providers qualify for procurement shortlists. Stakeholders must monitor how NIS2 Directive implementation across EU member states reclassifies backup availability as critical infrastructure obligation rather than discretionary IT spend.
Market Dynamics
The migration of enterprise workloads to multi-cloud environments is compressing recovery point objectives from 24-hour cycles to near-continuous replication, forcing backup vendors to re-architect ingestion pipelines for API rate limits across heterogeneous SaaS platforms.
Growth Catalysts
- EU AI Act data governance mandates:European enterprises must maintain immutable audit trails for AI training datasets, accelerating procurement of encrypted backup infrastructure that satisfies Article 50 documentation requirements.
- Healthcare cloud-to-cloud protocols:US life sciences firms under FDA 21 CFR Part 11 are replacing tape archives with automated SaaS replication to satisfy electronic record integrity standards for clinical trial data.
- German multi-cloud migration:Enterprises in Frankfurt and Munich are distributing critical workloads across AWS, Azure, and Google Cloud, creating demand for vendor-agnostic backup orchestration layers.
Market Restraints
- API rate limit bottlenecks:Salesforce and Microsoft 365 impose throttling thresholds that constrain backup throughput for large enterprises, extending initial seeding windows to multiple weeks.
- Cross-border data residency friction:GDPR Article 44 transfer mechanisms complicate backup routing for multinational firms operating shared tenancy across EU and US cloud regions.
- Immutable storage cost premiums:Write-once-read-many object storage tiers carry 40-60% price elevation over standard cloud storage, elevating total cost of ownership for compliance-grade retention policies.
Strategic Opportunities
- NIS2 Directive critical infrastructure reclassification:EU member states are recategorizing backup availability as mandatory operational resilience obligation, converting discretionary IT spend into regulated procurement.
- India SaaS ecosystem maturation:Bangalore and Hyderabad software exporters are adopting cloud-native backup for customer data protection, creating greenfield demand outside saturated North American and European markets.
- AI-driven anomaly detection convergence:Integration of machine learning classification with backup workflows enables proactive ransomware identification before encryption events propagate.
Industry Challenges
- Multi-tenant isolation architecture:Backup providers must engineer logical separation controls that prevent cross-customer data exposure in shared infrastructure without sacrificing economies of scale.
- Legacy mainframe integration complexity:Financial institutions in London and Zurich maintain core banking systems on IBM z/OS, requiring custom connector development for hybrid cloud backup orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Saas Backup Software Market |
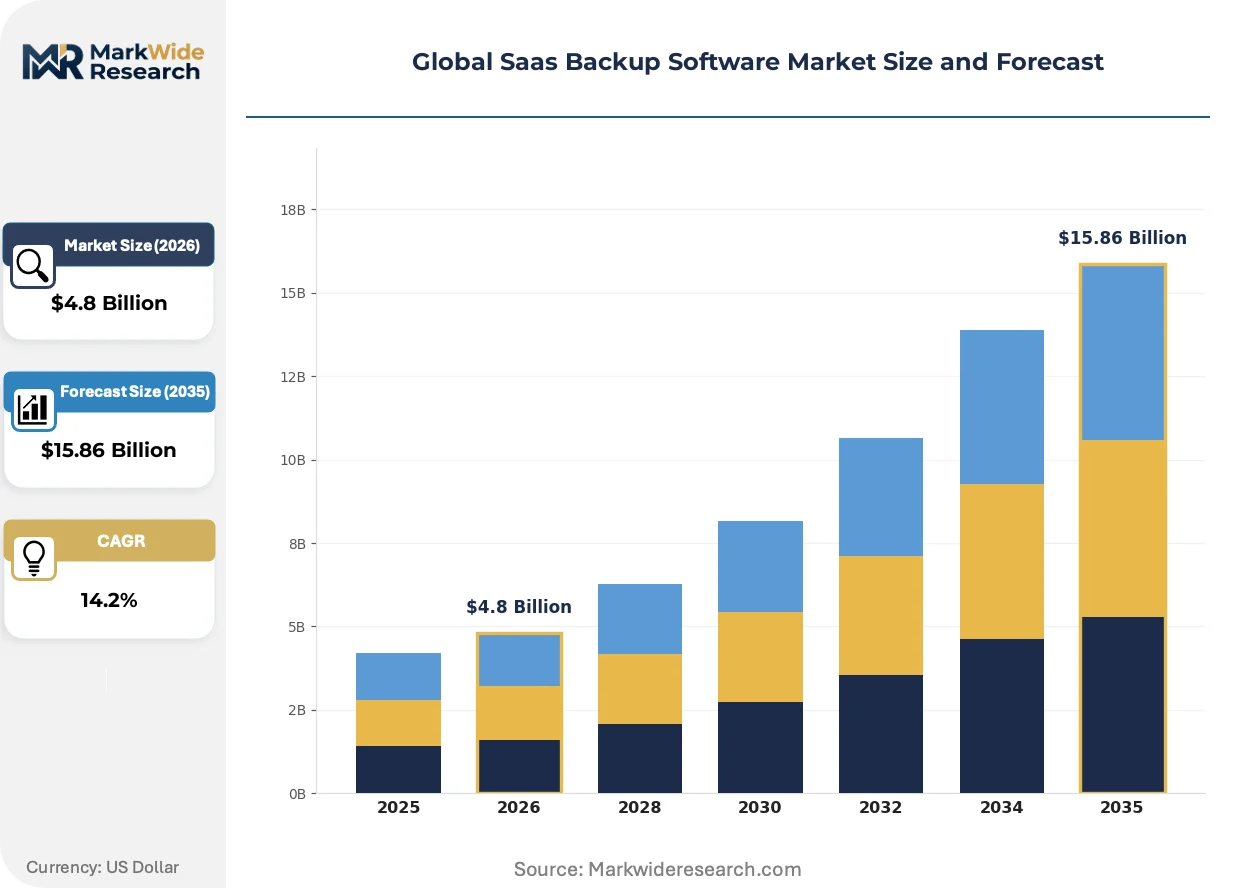
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Environment Solution Type: Backup & Recovery, Disaster Recovery, Data Archiving, Continuous Data Protection, Cloud-to-Cloud Backup End User Industry: Information Technology, Financial Services, Telecommunications, Education, Government Agencies Pricing Model: Subscription-Based, Usage-Based, Per User, Freemium, Enterprise License |
| Companies Covered | Acronis, NetApp, Druva, Veeam, Barracuda Networks, OwnBackup, Spanning, HYCU, Datto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Saas Backup Software Market Shifts & Advancements
Agentless data capture architectures are displacing endpoint-installed software across enterprise backup deployments. Vendors are compressing recovery time objectives through incremental-forever ingestion models that eliminate full re-seeding requirements.
Immutable backup repositories using blockchain-verified integrity checksums are decentralizing trust models for ransomware recovery workflows. Healthcare providers in Boston and pharmaceutical manufacturers in Basel are deploying these architectures to satisfy FDA audit requirements for tamper-evident record retention. The shift removes dependency on vendor-operated key management while introducing operational complexity around cryptographic key lifecycle governance.
The EU AI Act's training data documentation requirements are forcing backup vendors to implement granular metadata indexing for machine learning dataset provenance. German automotive AI developers and French healthcare algorithm vendors must now reconstruct historical data states for regulatory inspection, elevating backup systems from passive insurance to active compliance infrastructure. Providers are responding with time-series database integration that captures schema evolution alongside raw content.
Subscription fatigue among mid-market buyers is fragmenting contract structures toward usage-metered arrangements with committed spend floors. Seasonal e-commerce operators in Rotterdam and project-driven professional services firms in Sydney are negotiating variable pricing that aligns backup costs with revenue cyclicality. The transition compresses vendor predictability while expanding addressable market penetration among capital-constrained growth companies.
Global Saas Backup Software Market Segmentation
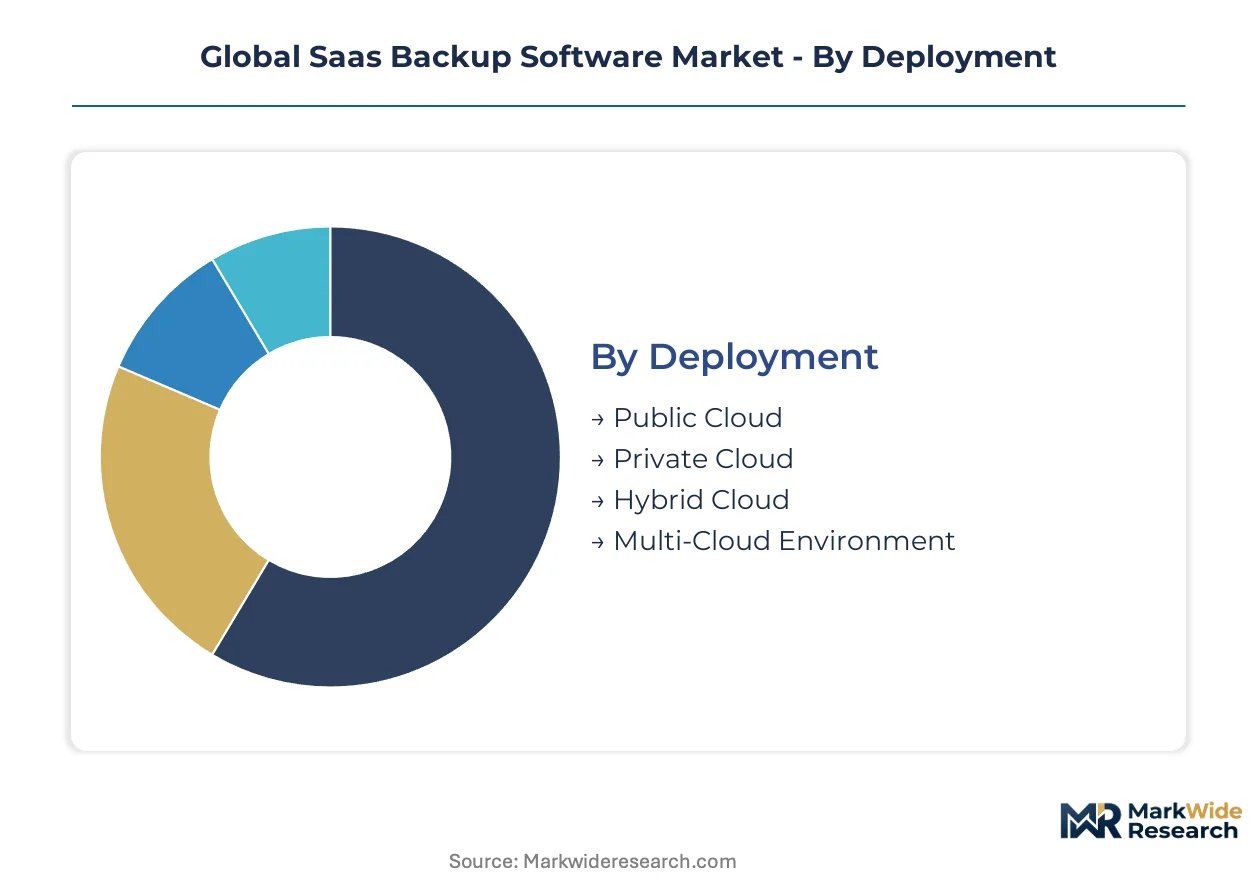
SaaS backup procurement diverges sharply across deployment architectures and compliance burdens. Segmentation reveals how FDA 21 CFR Part 11, GDPR, and EU AI Act requirements filter vendor eligibility by solution type and pricing structure.
Deployment:
FDA and GDPR certification burdens concentrate heaviest in private and hybrid configurations where data residency controls are auditable.
- Public Cloud:Shared infrastructure delivers lowest entry cost for mid-market Microsoft 365 and Google Workspace tenants. Demand clusters among seasonal e-commerce operators in Rotterdam seeking variable recovery point objectives without capital expenditure.
- Private Cloud:Dedicated tenancy satisfies FDA 21 CFR Part 11 audit trail mandates for US pharmaceutical manufacturers in Boston and Basel. Immutable storage with customer-controlled encryption keys elevates procurement scrutiny but captures premium pricing.
- Hybrid Cloud:Split architectures reconcile on-premises legacy systems with SaaS replication for London and Zurich financial institutions maintaining IBM z/OS cores.
- Multi-Cloud Environment:Vendor-agnostic orchestration layers serve Frankfurt and Munich enterprises distributing workloads across AWS, Azure, and Google Cloud.
Leading the category by volume: Public Cloud. Growing fastest: Multi-Cloud Environment.
Solution Type:
Cost tier differentiation separates commodity backup from compliance-grade infrastructure with embedded cyber protection.
- Cloud-to-Cloud Backup:API-native replication between SaaS platforms bypasses on-premises hardware entirely. German automotive AI developers under EU AI Act Article 50 deploy these pipelines to maintain immutable training dataset provenance.
- Continuous Data Protection:Near-zero recovery point objectives through incremental-forever ingestion. Healthcare providers in Boston compress recovery windows from 24-hour cycles to 15-minute granularity for electronic health record systems.
- Backup & Recovery:Scheduled replication with point-in-time restoration for standard business productivity suites.
- Disaster Recovery:Orchestrated failover workflows spanning multiple availability zones.
- Data Archiving:Long-term retention with write-once-read-many immutability for regulatory preservation.
Volume leader: Backup & Recovery. Steepest expansion trajectory: Cloud-to-Cloud Backup.
End User Industry:
Application intensity varies by sector-specific regulator pressure and data criticality.
- Financial Services:Real-time transaction replication for Basel III operational resilience mandates. London and Zurich institutions require hybrid connectors bridging mainframe cores to cloud-native backup.
- Information Technology:Internal platform protection and customer-facing backup-as-a-service offerings. Bangalore and Hyderabad software exporters drive greenfield demand for multi-tenant isolation architectures.
- Telecommunications:Network equipment configuration backup and subscriber data protection.
- Government Agencies:Classified and unclassified tiering with sovereign cloud requirements.
- Education:Student information system protection with semester-aligned retention policies.
Dominant by procurement value: Financial Services. Expanding most quickly: Information Technology.
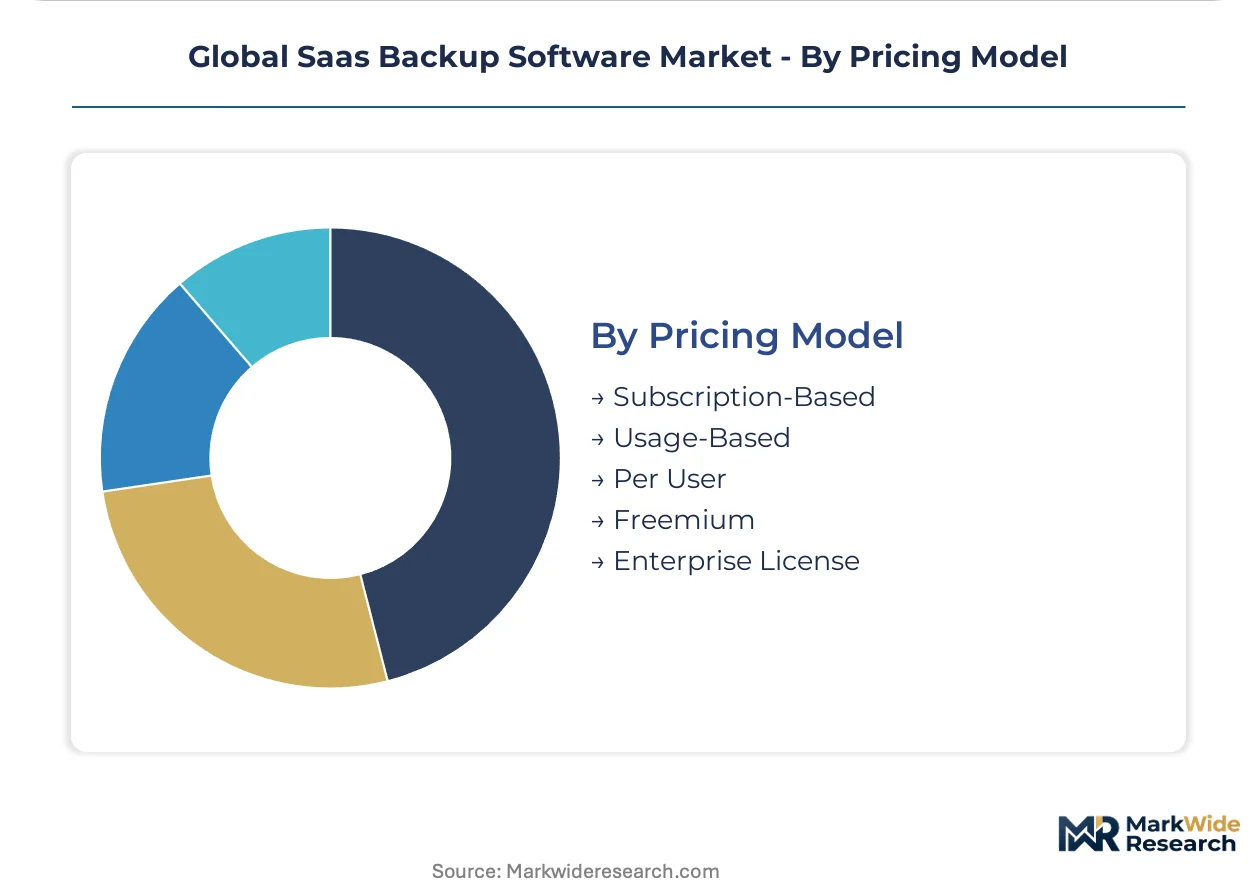
Pricing Model:
Customer type and maturity dictate contract structure preference across enterprise and growth-stage buyers.
- Subscription-Based:Predictable annual or monthly commitments dominate revenue flows. Mid-market buyers in Sydney professional services favor fixed costs for budget certainty.
- Usage-Based:Metered consumption aligns spend with data velocity. Seasonal operators negotiate committed spend floors with variable overage rates.
- Per User:Seat-based licensing for homogeneous workforce protection.
- Freemium:Limited-tier acquisition funnel for small business conversion.
- Enterprise License:Unlimited capacity agreements with custom service level objectives.
Revenue concentration: Subscription-Based. Gaining share fastest: Usage-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital concentration anchors SaaS backup software development, while Frankfurt's financial infrastructure and Bangalore's software export clusters drive differentiated regional demand patterns across three continents.
United States
FDA 21 CFR Part 11 mandates immutable audit trails for pharmaceutical manufacturers in Boston and San Francisco, accelerating procurement of compliance-grade backup infrastructure. HIPAA enforcement actions against healthcare providers in Chicago elevate encrypted replication to operational priority. Cloud-native vendors cluster in Austin and Seattle to serve federal contractors requiring FedRAMP-authorized data protection.
Germany
Frankfurt and Munich enterprises distribute workloads across AWS, Azure, and Google Cloud, creating demand for vendor-agnostic orchestration layers. EU AI Act Article 50 documentation requirements force automotive AI developers in Stuttgart to maintain granular training dataset provenance. GDPR Article 44 transfer mechanism complexity filters vendor shortlists to providers with EU sovereign cloud certifications.
India
Bangalore and Hyderabad software exporters adopt multi-tenant isolation architectures for customer data protection, generating greenfield demand outside saturated Western markets. RBI data localization guidelines for fintech companies in Mumbai mandate in-country backup residency. PLI scheme incentives for IT hardware manufacturing in Chennai indirectly expand domestic cloud infrastructure capacity.
United Kingdom
London financial institutions under Basel III operational resilience mandates require real-time transaction replication with sub-hour recovery objectives. FCA guidance on operational continuity pushes insurance underwriters in Edinburgh toward automated failover workflows. Hybrid cloud adoption in Manchester manufacturing clusters bridges legacy ERP systems with SaaS-native protection.
Japan
Tokyo financial services firms integrate backup workflows with METI cybersecurity framework requirements for critical infrastructure operators. Osaka pharmaceutical manufacturers align SaaS replication with PMDA electronic record integrity standards. Manufacturing automation vendors in Nagoya deploy edge-to-cloud backup for industrial IoT sensor data retention.
Global Saas Backup Software Market Competitive Landscape
Strategic partnership formation dominates the current landscape as vendors race to embed cyber protection layers and AI-driven anomaly detection into core backup workflows. The vendor base organizes around three functional tiers: established data management platforms with hybrid-cloud reach, cloud-native specialists with agentless architectures, and vertical-focused providers serving regulated industries. Consolidation pressure intensifies as mid-market buyers demand bundled security-resilience offerings rather than point solutions.
Within the hybrid-cloud infrastructure tier, Veeam and NetApp exemplify scale-driven positioning through broad platform coverage and enterprise channel density. Druva anchors the cloud-native specialist archetype with fully managed, hardware-eliminating deployment models that resonate with distributed workforce requirements. Acronis occupies a converged security-backup position that blurs traditional category boundaries. These three patterns—hybrid reach, cloud-native simplicity, and integrated cyber protection—collectively define competitive differentiation vectors as procurement shifts from discretionary insurance spend toward regulated operational resilience obligation.
| Leading Market Players |
|---|
| Acronis |
| NetApp |
| Druva |
| Veeam |
| Barracuda Networks |
| OwnBackup |
| Spanning |
| HYCU |
| Datto |
| Others |
Supply & Pricing Matrix
Compliance-grade certification tiers bifurcate the SaaS backup market into premium immutable-storage offerings and commodity public-cloud replication, with FDA 21 CFR Part 11 and GDPR Article 44 requirements driving divergent supply chain configurations. German automotive AI developers and US pharmaceutical manufacturers absorb 40-60% storage cost premiums for write-once-read-many architectures, while Rotterdam e-commerce operators minimize capital exposure through shared-tenancy deployments with variable recovery objectives.
Pricing Analysis
Service-bundling intensity separates fully managed agentless deployments from unbundled infrastructure-only tiers. Subscription-based annual commitments dominate revenue flows among mid-market buyers in Sydney seeking budget predictability, though usage-metered arrangements with committed spend floors gain traction among seasonal operators. Price differentiation rests on encryption key custody and cyber protection integration. Cost compression in public cloud tiers intensifies as hyperscaler storage commoditizes, while private cloud buyers demonstrate lowest price sensitivity due to regulatory audit mandates.
Supply Chain Analysis
Dual-sourcing requirements from Frankfurt financial institutions and Munich automotive enterprises mandate multi-cloud qualification across AWS, Azure, and Google Cloud. Software development concentrates in the United States, India, and Germany, with API-native ingestion pipelines drawing from hyperscaler compute infrastructure, cryptographic hardware security modules, and blockchain-verified integrity frameworks. Single-source vulnerability persists around customer-controlled key management systems. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SaaS backup market occupies a technology-transition phase as agentless cloud-native architectures displace legacy endpoint-installed software across enterprise deployments.
For Market Incumbents: Anticipate margin compression from hyperscaler-native backup services by deepening cyber protection integration and pursuing FedRAMP authorization for federal contractor segments. Prioritize immutable storage certification investment to defend positioning against compliance-grade specialists. For New Entrants and Emerging Players: Enter via multi-tenant isolation architectures targeting Bangalore and Hyderabad software exporters with customer-facing backup-as-a-service offerings. The Indian SaaS ecosystem presents the most penetrable greenfield geography, accessible through channel partnerships with hyperscaler marketplace programs. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays as mid-market buyers demand bundled security-resilience offerings. Long-term viability favors vendors with EU sovereign cloud certifications and FDA 21 CFR Part 11 validation. Monitor NIS2 Directive implementation across EU member states as the critical inflection signal converting discretionary spend into regulated procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding cyber protection layers into backup workflows addresses FDA 21 CFR Part 11 audit requirements. |
| Strategic Partnership | Hyperscaler marketplace listings accelerate procurement cycles for German multi-cloud enterprises. |
| Acquisition of Specialist Firm | Immutable storage technology targets GDPR Article 44 compliance for EU financial services buyers. |
| Geographic Expansion | Indian software export clusters generate greenfield demand for multi-tenant isolation architectures. |
| Product Launch | AI-driven anomaly detection converges machine learning classification with ransomware identification workflows. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners. SEC 10-K disclosures, hyperscaler capex reports, and EU regulatory databases provided demand-side validation. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Granularity-level modeling captured deployment architecture, organization size, vertical industry, and regional adoption pattern dimensions throughout the forecast period. CAGRs derived from time-series regression against SaaS platform growth rates and compliance mandate implementation timelines. API rate limit constraints and immutable storage cost curves informed supply-side capacity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NIS2 Directive implementation delays or hyperscaler storage pricing volatility. Deviation in EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Fire Software Market
Software & Services
API Design Software Market
Software & Services
Non-Profit Software Market
Software & Services
Taxi Booking Software Market
Software & Services
Global Note Taking App Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Global Home Inspection Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Petcare Software Market
Software & Services
Labor Management Software Market
Software & Services
Audit Management Software Market
Software & Services
Customs Declaration Software Market
Software & Services
India Sports Management Software Market
Software & Services
Global HVAC Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
Global Data Discovery Software Market