
 Global CMMS Software Market | 2026-2036
Global CMMS Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global CMMS Software Market Foresight
Subscription-based preventive maintenance modules is decoupling software licensing from perpetual ownership across industrial accounts. IBM Maximo Application Suite leverages deep enterprise integration to anchor complex asset-heavy environments. MaintainX competes through mobile-first interfaces that reduce technician onboarding friction. UpKeep CMMS specializes in mid-market manufacturing workflows with simplified work order routing.
Computerized maintenance management system (CMMS) software digitizes asset lifecycle tracking through centralized databases that log equipment history, schedule preventive interventions, and monitor spare parts inventories. Cloud-based deployment now leads solution delivery by eliminating on-site server infrastructure while enabling real-time mobile access for distributed technician teams. Predictive maintenance segments are growing fastest as IoT sensor integration allows condition-based alerts that reduce unplanned downtime. Work order management remains the most mature category with established margin pools in enterprise accounts requiring multi-site coordination.
FDA validation requirements for equipment maintenance records in pharmaceutical manufacturing shape product standards for audit trail completeness. EU Green Deal carbon reporting obligations and OSHA process safety mandates both drive documentation rigor that CMMS platforms must satisfy. Stakeholders should monitor how ISO 55000 asset management standards evolve to incorporate AI-driven predictive thresholds that redefine compliance benchmarks.
Market Dynamics
Cloud-native architectures are dismantling the on-premise software monopoly that once defined enterprise maintenance management, forcing incumbents to rebuild delivery models around API-first ecosystems and consumption-based pricing.
Growth Catalysts
- EU Green Deal carbon reporting:German manufacturing plants must document equipment energy efficiency and maintenance-induced emissions reductions, creating mandatory software procurement across automotive and chemical sectors.
- IoT sensor proliferation:Condition monitoring hardware costs have collapsed, enabling predictive maintenance modules that convert unplanned downtime into scheduled interventions for asset-intensive operations.
- FDA validation requirements:Pharmaceutical manufacturers in the United States face audit trail mandates for equipment maintenance records, elevating CMMS from operational convenience to regulatory necessity.
Market Restraints
- Data sovereignty fragmentation:China's Cybersecurity Law and Russia's data localization rules prevent cloud-native vendors from offering unified global instances, forcing costly regional infrastructure duplication.
- Legacy system entrenchment:SAP PM and Oracle EAM modules remain embedded in Fortune 500 maintenance workflows, creating switching costs that delay SaaS migration timelines by 18-36 months.
- Technician digital literacy gaps:Aging maintenance workforces in heavy industry verticals resist mobile interface adoption, constraining addressable market expansion for interface-dependent vendors.
Strategic Opportunities
- India's PLI scheme manufacturing expansion:Electronics and pharmaceutical production incentives are greenfielding facilities without legacy system baggage, enabling native cloud CMMS deployment from commissioning.
- AI-driven predictive threshold integration:Machine learning models that anticipate bearing failures and lubrication degradation are converging with CMMS platforms, creating premium pricing tiers for algorithmic maintenance.
- Small-batch contract manufacturing:Biotech and specialty chemical toll producers need flexible asset tracking across shared equipment pools, an underserved segment between enterprise suites and basic work order tools.
Industry Challenges
- ISO 55000 certification complexity:Asset management standard audits require cross-functional data integration that most CMMS implementations fail to satisfy, extending sales cycles and implementation timelines.
- OT-IT convergence friction:Maintenance software must interface with SCADA and PLC systems through proprietary protocols, demanding specialized integration engineering that strains vendor delivery capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CMMS Software Market |
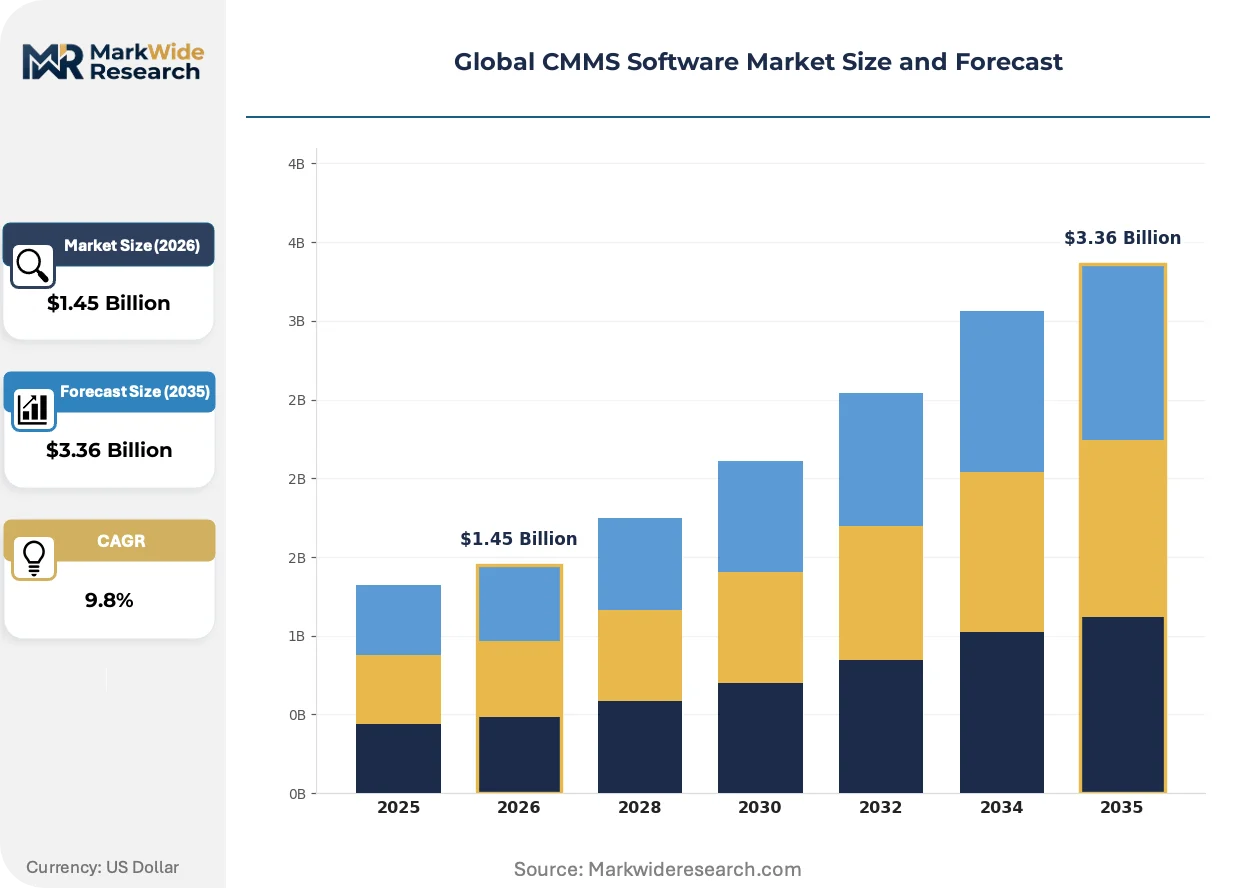
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.36 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS, Hosted Solution Offering: Preventive Maintenance, Predictive Maintenance, Work Order Management, Asset Management, Inventory Management, Compliance Management Use Case: Manufacturing, Facilities Management, Transportation, Energy Generation, Hospitality, Education End User: OEMs, Plant Operators, Maintenance Contractors, Facility Managers, Equipment Leasing Firms |
| Companies Covered | MaintainX, eMaint CMMS, IBM Maximo Application Suite, Asset Panda, Infor EAM, UpKeep CMMS, Limble CMMS, Tractian, Fiix by Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CMMS Software Market Shifts & Advancements
Edge computing architectures are redistributing computational load away from centralized cloud servers, enabling real-time decision-making at the asset level that reshapes latency-sensitive maintenance workflows.
Digital twin technology is decentralizing asset knowledge by creating persistent virtual replicas that mirror physical equipment behavior. Chemical processors and power utilities are deploying these models to simulate maintenance scenarios before committing field resources. This shift compresses the feedback loop between diagnostic insight and technician dispatch, reducing mean time to repair.
REACH chemical substance restrictions are forcing European manufacturers to track maintenance fluid compositions and disposal pathways through integrated environmental modules. The regulation mandates substitution planning for hazardous lubricants and coolants, requiring CMMS platforms to incorporate chemical inventory lifecycle tracking. German automotive suppliers and Dutch food processors face the steepest compliance deadlines.
Subscription fatigue among mid-market manufacturers is fragmenting vendor relationships as buyers resist multi-year SaaS commitments. Equipment OEMs are responding by embedding lightweight CMMS functionality into service contracts, capturing maintenance data without separate software procurement. This pattern concentrates in United States metal fabrication and industrial machinery sectors where capital equipment vendors already control spare parts supply.
Global CMMS Software Market Segmentation
CMMS software segments diverge sharply on compliance burden. FDA-validated audit trails govern pharmaceutical deployments. EU Green Deal carbon reporting shapes European manufacturing procurement. Cloud-native architectures face data sovereignty fragmentation across national borders.
Deployment:
FDA 21 CFR Part 11 validation requirements and EU GDPR data residency rules create divergent certification pathways across deployment modes.
- Cloud-Based:Multi-tenant architectures eliminate on-site server infrastructure while enabling real-time mobile access for distributed technician teams. Demand concentrates in United States manufacturing plants seeking rapid scalability without capital expenditure. ISO 27001 certification and SOC 2 Type II attestation separate enterprise-grade vendors from mid-market offerings.
- SaaS:Subscription pricing decouples software licensing from perpetual ownership, reducing upfront procurement barriers for mid-market accounts. German automotive suppliers favor consumption-based models aligned with EU Green Deal compliance timelines. Annual recurring revenue concentration attracts private equity consolidation.
- On-Premise:Air-gapped installations satisfy China's Cybersecurity Law and Russia's data localization mandates for critical infrastructure operators.
- Hybrid:Split architectures process sensitive maintenance records locally while pushing analytics workloads to cloud endpoints.
- Hosted:Single-tenant managed services bridge legacy system entrenchment and cloud migration timelines for Fortune 500 maintenance workflows.
Leading the category by volume: Cloud-Based. Growing fastest: SaaS.
Solution Offering:
Functional modules map directly to regulatory audit scopes and operational maturity tiers.
- Predictive Maintenance:IoT sensor integration enables condition-based alerts that convert unplanned downtime into scheduled interventions. United States power utilities and chemical processors deploy machine learning models anticipating bearing failures and lubrication degradation. FDA validation requirements elevate audit trail completeness for pharmaceutical equipment monitoring.
- Work Order Management:Centralized databases log equipment history and schedule preventive interventions across multi-site coordination requirements. Mature margin pools in enterprise accounts contrast with simplified routing tools for mid-market manufacturing. India's PLI scheme electronics manufacturers adopt native cloud deployment from facility commissioning.
- Preventive Maintenance:Calendar-based scheduling modules satisfy baseline ISO 55000 asset management documentation for certification audits.
- Asset Management:Lifecycle cost tracking supports EU Green Deal carbon reporting obligations for equipment energy efficiency documentation.
- Inventory Management:Spare parts tracking integrates with REACH chemical substance restrictions for maintenance fluid composition monitoring.
- Compliance Management:Integrated environmental modules mandate substitution planning for hazardous lubricants and coolants under European regulations.
Highest margin concentration: Work Order Management. Steepest expansion trajectory: Predictive Maintenance.
Use Case:
End-use verticals stratify by asset intensity, technician digital literacy, and regulatory exposure.
- Manufacturing:Asset-heavy environments anchor complex enterprise deployments requiring deep ERP integration and multi-site coordination. German automotive and chemical sectors drive mandatory software procurement under EU Green Deal carbon reporting deadlines. FDA validation requirements elevate CMMS from operational convenience to regulatory necessity for United States pharmaceutical production.
- Energy Generation:SCADA and PLC system integration demands specialized engineering for OT-IT convergence in power utilities. Edge computing architectures enable real-time decision-making at turbine and transformer assets. NERC CIP cybersecurity standards constrain cloud-native vendor selection.
- Facilities Management:Distributed building portfolios favor mobile-first interfaces reducing technician onboarding friction.
- Transportation:Fleet maintenance tracking spans rolling stock and infrastructure assets across rail and aviation operators.
- Hospitality:Seasonal demand volatility drives preference for flexible subscription terms over multi-year SaaS commitments.
- Education:Capital-constrained institutional buyers gravitate toward equipment OEM embedded functionality within service contracts.
Deepest enterprise penetration: Manufacturing. Fastest greenfield adoption: Energy Generation.
End User:
Procurement authority and legacy system baggage determine addressable market expansion.
- Plant Operators:Direct asset ownership creates incentive for comprehensive lifecycle tracking and predictive intervention investment. SAP PM and Oracle EAM module entrenchment delays SaaS migration timelines by 18-36 months in Fortune 500 accounts. India's PLI scheme greenfield facilities bypass legacy constraints entirely.
- Maintenance Contractors:Multi-client service portfolios demand flexible asset tracking across shared equipment pools in biotech and specialty chemical toll production. Mobile interface dependency constrains expansion where aging workforces resist digital adoption.
- OEMs:Equipment manufacturers embed lightweight CMMS functionality into service contracts, capturing maintenance data without separate software procurement.
- Facility Managers:Building portfolio oversight prioritizes work order routing simplicity over predictive algorithm complexity.
- Equipment Leasing Firms:Asset utilization tracking supports residual value optimization and lease rate structuring.
Primary revenue concentration: Plant Operators. Fastest-growing procurement authority: Maintenance Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates CMMS software consumption through cloud-native procurement, while Germany and China anchor manufacturing-driven demand. Production of maintenance management platforms clusters in North American and European technology hubs serving asset-intensive verticals.
United States
Pharmaceutical manufacturers deploy FDA-validated audit trails under 21 CFR Part 11 mandates, converting operational software into regulatory infrastructure. OSHA process safety documentation requirements elevate CMMS procurement in chemical processing clusters. Houston's petrochemical corridor and New Jersey's pharmaceutical belt drive enterprise-grade predictive maintenance adoption.
Germany
Automotive suppliers document equipment energy efficiency to satisfy EU Green Deal carbon reporting deadlines. REACH chemical substance restrictions force maintenance fluid tracking through integrated environmental modules. Bavaria's automotive engineering clusters and North Rhine-Westphalia's chemical processing facilities mandate native cloud deployment from facility commissioning.
China
State-owned power utilities integrate edge computing architectures for real-time turbine monitoring despite Cybersecurity Law data localization constraints. MIIT industrial digitization targets accelerate CMMS penetration in steel and cement sectors. Yangtze River Delta manufacturing hubs deploy condition-based maintenance to reduce unplanned downtime in heavy asset operations.
India
Electronics and pharmaceutical production under PLI scheme incentives greenfield facilities without legacy system baggage. BIS standards for equipment maintenance documentation shape software procurement specifications. Karnataka's semiconductor fabrication parks and Gujarat's specialty chemical zones adopt mobile-first technician interfaces from commissioning.
Japan
Aging industrial infrastructure drives predictive maintenance investment to extend asset life cycles. METI energy efficiency regulations mandate equipment performance monitoring in steel and paper processing. Chubu region's automotive component suppliers and Kansai's machinery manufacturers integrate IoT sensor networks with legacy ERP systems.
Global CMMS Software Market Competitive Landscape
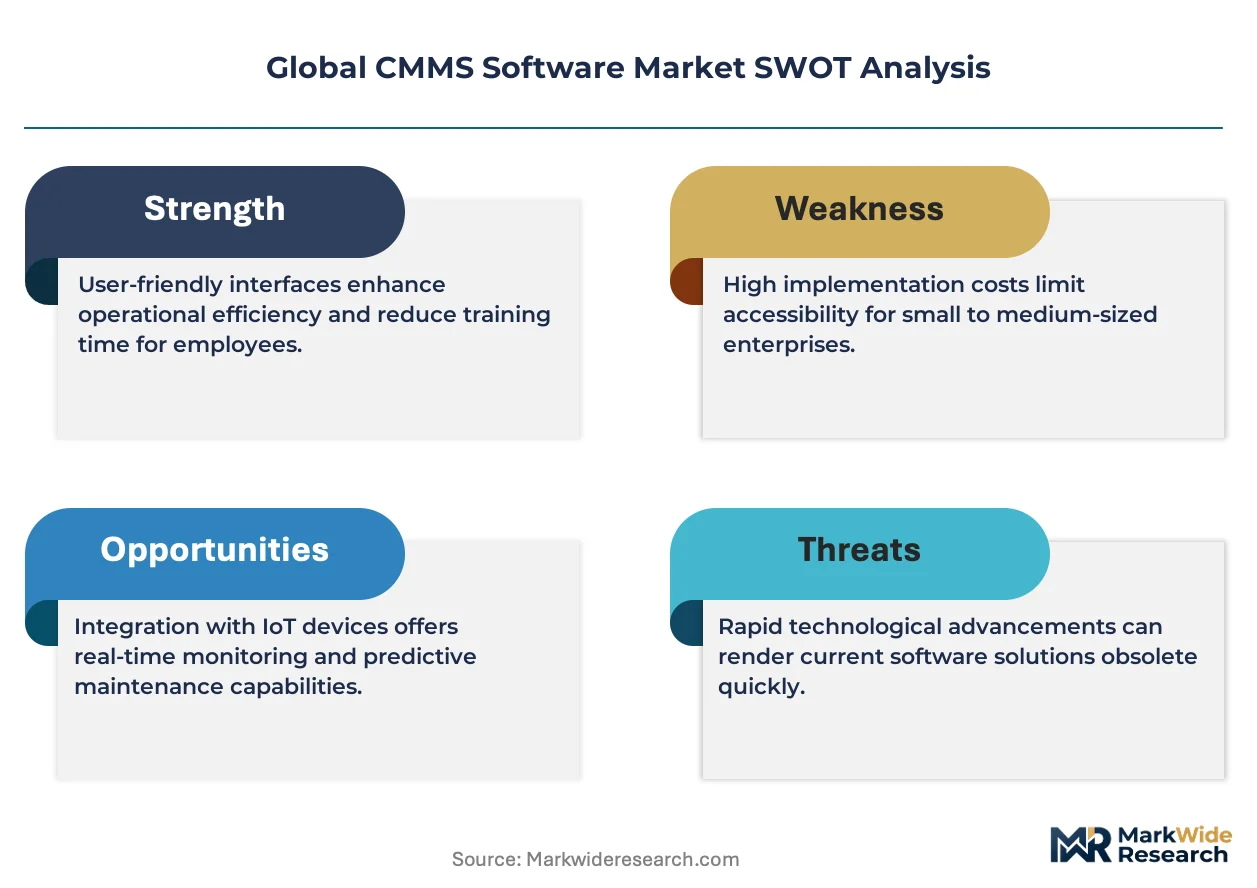
Top-tier vendors anchor enterprise accounts through deep ERP integration, while mid-market specialists compete on mobile-first deployment speed and technician onboarding friction. The vendor base stratifies across three archetypes: legacy platform incumbents with maintenance module extensions, pure-play SaaS native entrants, and industrial automation conglomerates embedding CMMS into broader control system portfolios. Dominant competitive moves include API-first ecosystem expansion and consumption-based pricing model migration.
Within the pure-play SaaS tier, MaintainX and UpKeep CMMS exemplify mobile-native positioning that reduces field technician training overhead. IBM Maximo Application Suite anchors the enterprise integration archetype, occupying a position where complex asset-heavy environments demand centralized lifecycle tracking across multi-site coordination requirements. These three representatives illustrate the competitive tension between lightweight deployment velocity and comprehensive functional depth.
| Leading Market Players |
|---|
| MaintainX |
| eMaint CMMS |
| IBM Maximo Application Suite |
| Asset Panda |
| Infor EAM |
| UpKeep CMMS |
| Limble CMMS |
| Tractian |
| Fiix by Rockwell Automation |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon reporting mandates gate qualified supply and premium-tier pricing access for CMMS vendors, as German automotive suppliers and Dutch food processors demand integrated environmental modules that track maintenance fluid compositions and disposal pathways under REACH chemical substance restrictions.
Pricing Analysis
Margin tightening in SaaS tiers reflects subscription fatigue among mid-market manufacturers resisting multi-year commitments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated enterprise suites from mobile-native mid-market offerings and equipment OEM embedded functionality. Pricing pressure stems from equipment manufacturers bundling lightweight CMMS into service contracts without separate software procurement. Plant operators show least price sensitivity due to regulatory compliance mandates, while education and hospitality segments gravitate toward capital-expenditure-free embedded solutions.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and India anchor hub-and-spoke delivery patterns for cloud-native CMMS platforms. Software development draws from Silicon Valley engineering clusters, Bavarian automotive technology hubs, and Bengaluru IT services corridors. Single-source vulnerability concentrates in hyperscaler infrastructure dependencies for multi-tenant architectures. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and equipment OEM service contract channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into IoT sensor hardware and predictive analytics engines defines the competitive race, as vendors pursue upstream control over condition monitoring data pipelines and downstream capture of maintenance contractor workflows.
For Market Incumbents: Deepen API-first ecosystem expansion to anchor complex ERP integration requirements against pure-play SaaS entrants. Fortify FDA validation documentation and ISO 55000 certification support to defend enterprise accounts from mobile-native challengers. Invest in edge computing architectures that process sensitive maintenance records locally while pushing analytics workloads to cloud endpoints, countering data sovereignty fragmentation risks. For New Entrants and Emerging Players: India's PLI scheme manufacturing expansion opens a window for native cloud deployment in electronics and pharmaceutical greenfield facilities without legacy system baggage. Target small-batch contract manufacturing in biotech and specialty chemical toll production, an underserved segment between enterprise suites and basic work order tools. Lead with mobile-first technician interfaces that reduce onboarding friction for aging maintenance workforces. For Investors and Strategic Acquirers: Private equity consolidation of SaaS-native vendors with annual recurring revenue concentration is the leading indicator that mid-market rollup strategies are accelerating. Focus acquisition screening on predictive maintenance specialists with proven IoT sensor integration and machine learning model deployment. Watch for AI-driven predictive threshold integration converging with CMMS platforms as the signal for premium pricing tier emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first ecosystems enable seamless ERP and SCADA connectivity for asset-heavy environments. |
| Acquisition of Specialist Firm | Predictive maintenance vendors with IoT sensor expertise command premium valuation multiples. |
| Geographic Expansion | India's PLI scheme electronics manufacturing offers greenfield cloud-native deployment opportunities. |
| Product Launch | FDA-validated audit trail modules convert operational software into pharmaceutical regulatory infrastructure. |
| Strategic Partnership | Equipment OEM service contract embedding captures maintenance data without separate procurement cycles. |
Research Methodology
Independent corroboration across maintenance directors at Fortune 500 manufacturers, IT procurement officers at mid-market industrial firms, and integration specialists at systems integrator partners underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings revealing CMMS procurement patterns, ECHA REACH compliance documentation, and FDA 21 CFR Part 11 guidance materials. Bottom-up deployment model sizing triangulates against top-down industrial software spending estimates.
Rate-of-change decomposition separates baseline preventive maintenance module growth from predictive maintenance acceleration across the analysis window. Segmentation dimensions span deployment architecture, organization size tier, vertical regulatory exposure, and integration complexity level. CAGRs derive from installed base migration timelines and greenfield adoption velocity in PLI scheme manufacturing. Forecast inputs incorporate IoT sensor cost collapse curves and EU Green Deal compliance deadline schedules.
The model assumes a particular technology adoption path; alternative pathways for edge computing architectures would alter the outlook if latency-sensitive maintenance workflows bypass centralized cloud servers entirely. Forecasts reflect documented assumptions around technician digital literacy convergence and data sovereignty rule stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Business Software Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Statistics Software Market
Software & Services
Global Database Software Market
Software & Services
Invoice Processing Software Market
Software & Services
Deck Design Software Market
Software & Services
Virtual Studio Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Software Construction Components Market
Software & Services
Exploration and Production Accounting System Software Market
Software & Services
Model Based Testing Tools Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Family Office Software Solutions Market
Software & Services
Global Mindfulness Meditation Apps Market
Software & Services
Camera Tracking Software Market
Software & Services
Embedded Hypervisor Market